Key Takeaways
- Pivotal Research reiterated its Buy rating and $475 price target on Alphabet today, 67% above Thursday’s closing, after Q3 results sent the stock sharply lower.
- Google Cloud revenue more than doubled, but Search growth slowed to 12% and free cash flow turned negative as quarterly capital spending reached $51.4 billion.
- Pivotal’s target implies about 33x forward earnings, right at the highest multiple Alphabet has carried in five years.
- That makes $475 look like a best case for a company with negative free cash flow, and Alphabet’s 2027 spending plan, due on its Q4 call, could change that.
Alphabet (GOOG) missed Wall Street’s Q3 revenue and earnings estimates, according to LSEG, and the stock is now 30% below its May high.
Pivotal Research reiterated its Buy rating and $475 price target on the stock today, 67% above Thursday’s closing price.
Search slowed, and the cash went out the door
Revenue grew 25% to $127.6 billion in Q3. But Google Search & other grew just 12%, after 17% in Q2, and CFO Anat Ashkenazi said lapping last year’s search acceleration “will pressure revenue growth in Q4.”
Capital spending hit $51.4 billion, free cash flow came in at negative $9.1 billion, and Ashkenazi still expects capex “to increase significantly in 2027.”
Alphabet is funding the build with new stock and debt: in the quarter it sold 36 million new shares for $12.4 billion, issued $28.7 billion of notes and bought back nothing.
That $9 billion cash burn and the miss in Search sank the stock.
TIKR tracks 60 analysts on Alphabet. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Alphabet, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Alphabet’s Analyst Ratings
Pivotal is betting on Cloud
Pivotal’s case rests on Google Cloud, whose revenue grew 103% to $30.7 billion, far ahead of the 73% the firm had forecast.
Cloud’s operating margin rose to 36.2% from 23.7% a year earlier, and its backlog reached $561 billion, up from $514 billion at the end of June.
Pivotal put the negative free cash flow, worse than its own estimate of negative $3 billion, down to the timing of working capital. Its $475 comes from a discounted cash flow model that runs to 2030.
Does $475 add up?
Sixty analysts cover Alphabet, and their consensus target has climbed from $258 to $418 over the past year:
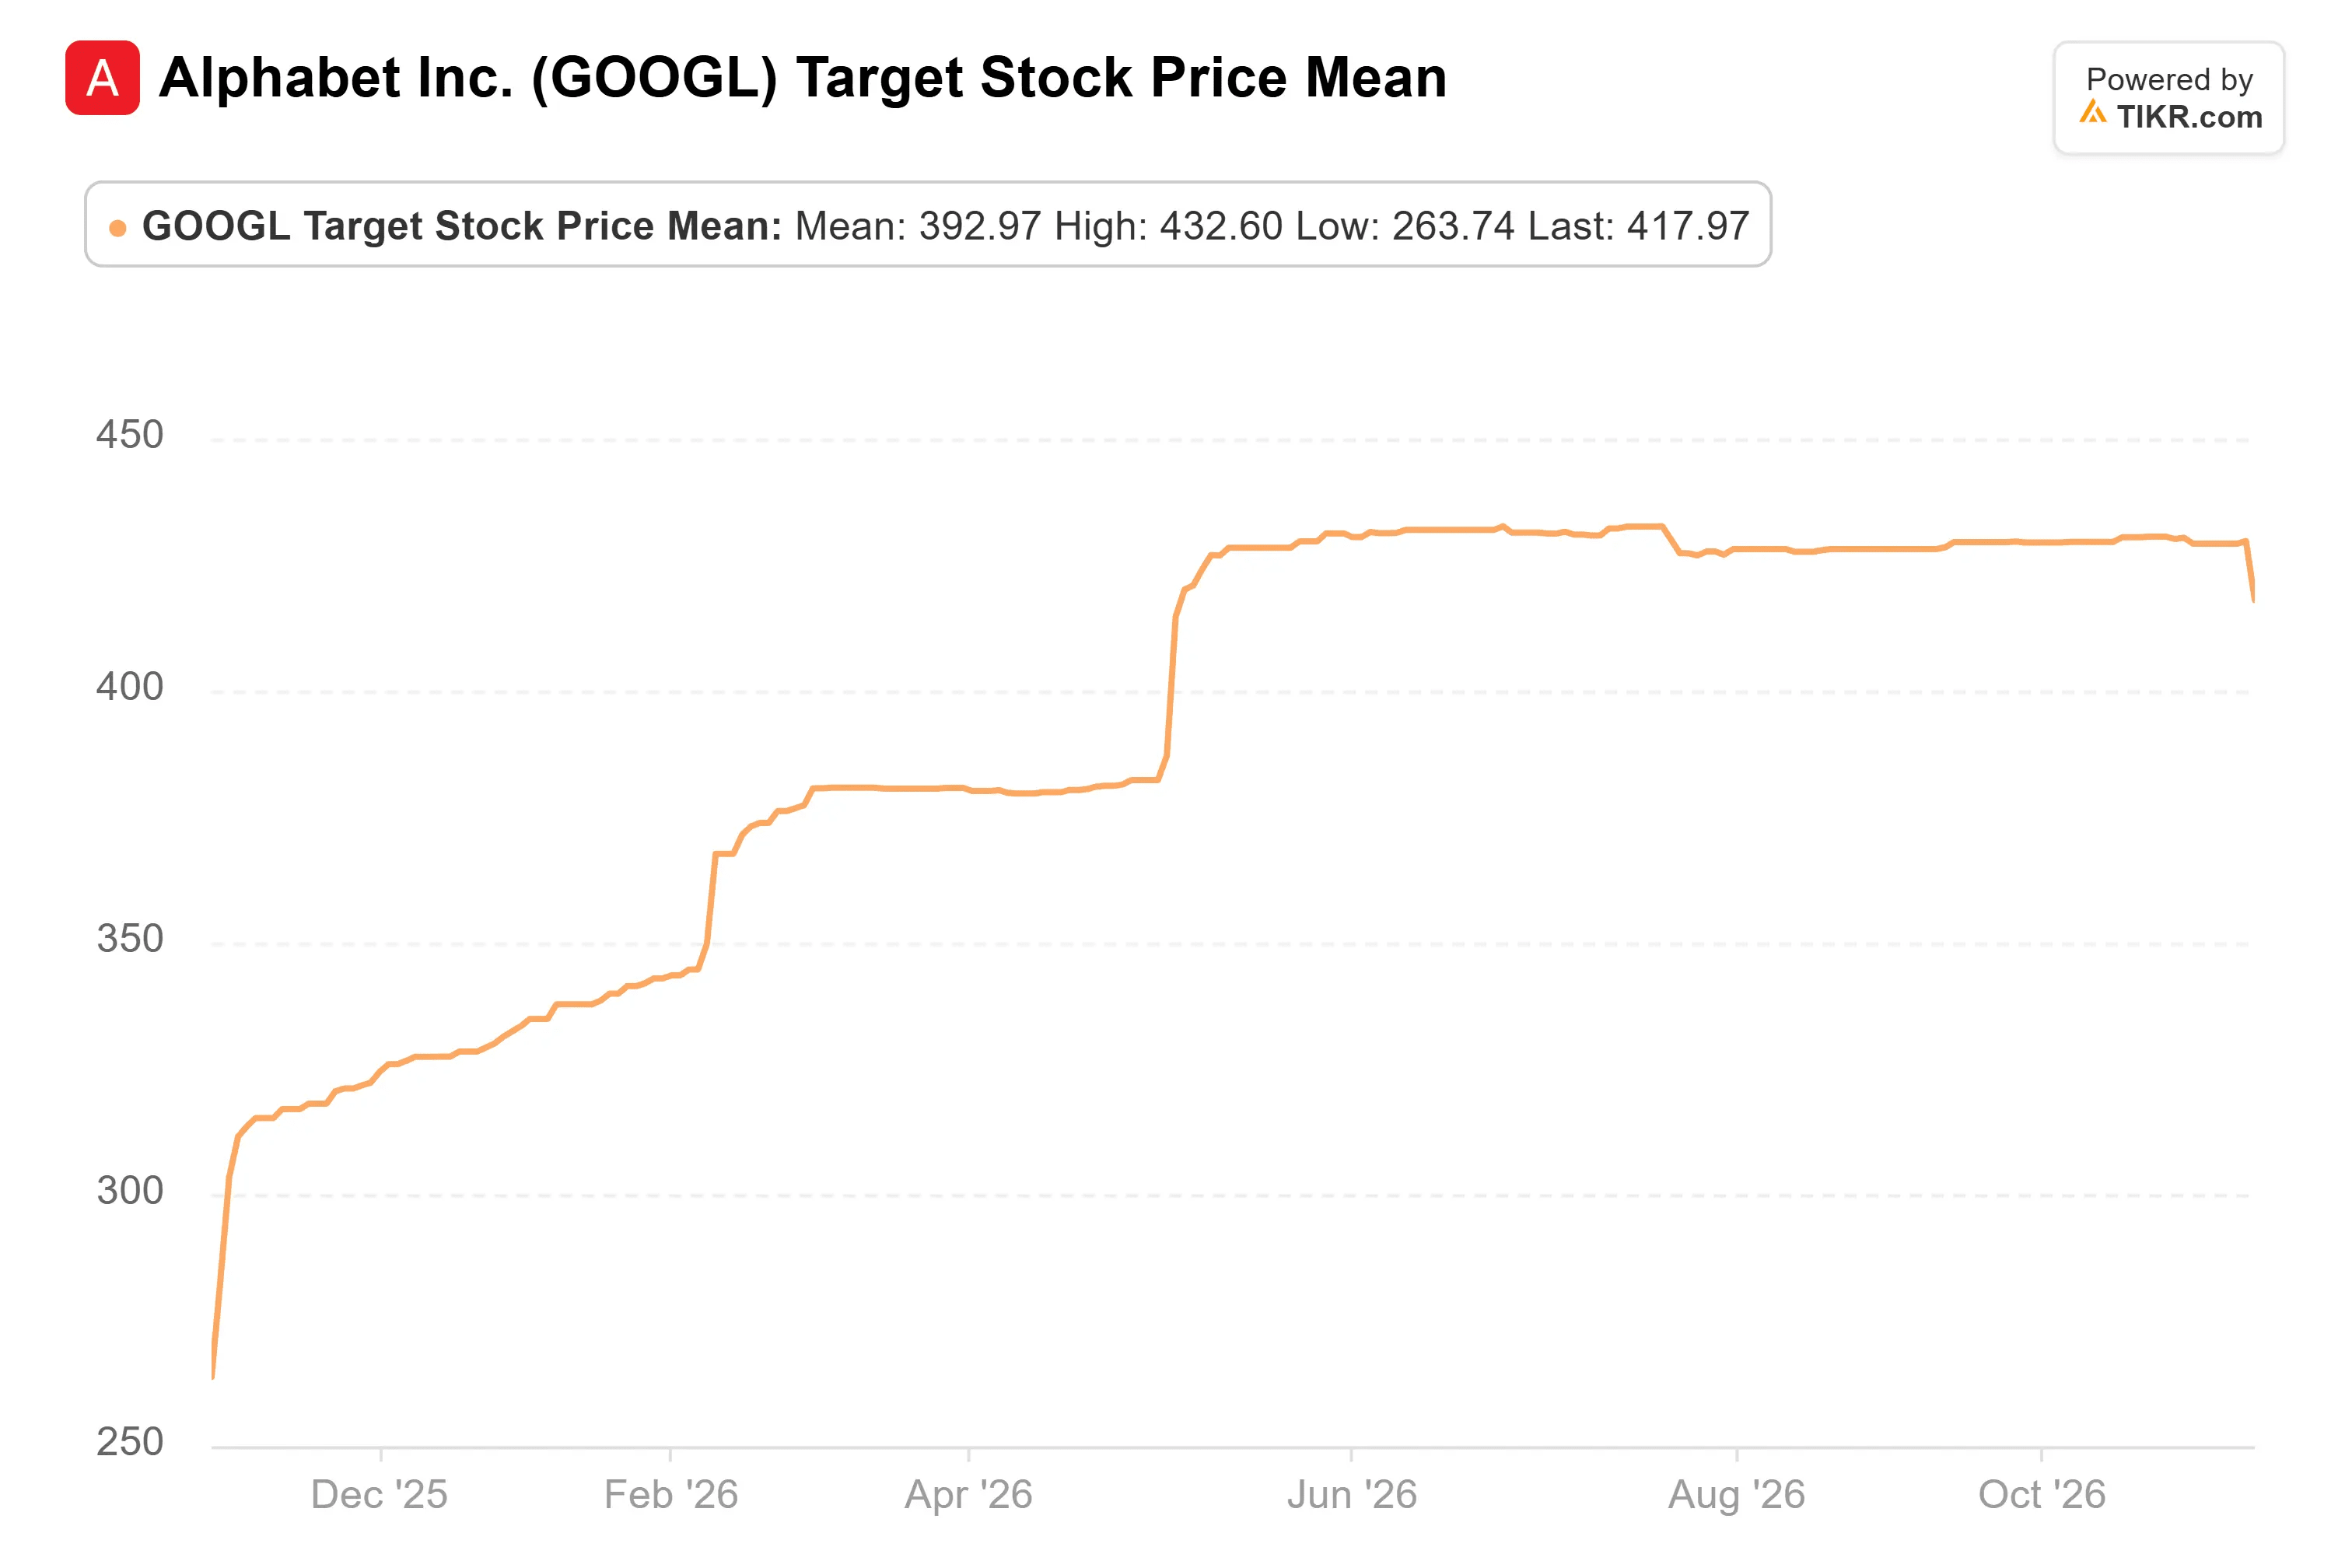
That $418 is 47% above today’s price, and Pivotal’s $475 is 14% above it.
Consensus normalized EPS for 2027 has risen to $15.19, from $14.82 three months ago:

This quarter gives analysts more reason to trim 2027 than to raise it, since Ashkenazi expects depreciation from all that spending to “weigh on the P&L.”
At Thursday’s close of $283, Alphabet traded at 20x forward earnings, close to its five-year average of 23x and well below the 33x it reached on April 30:
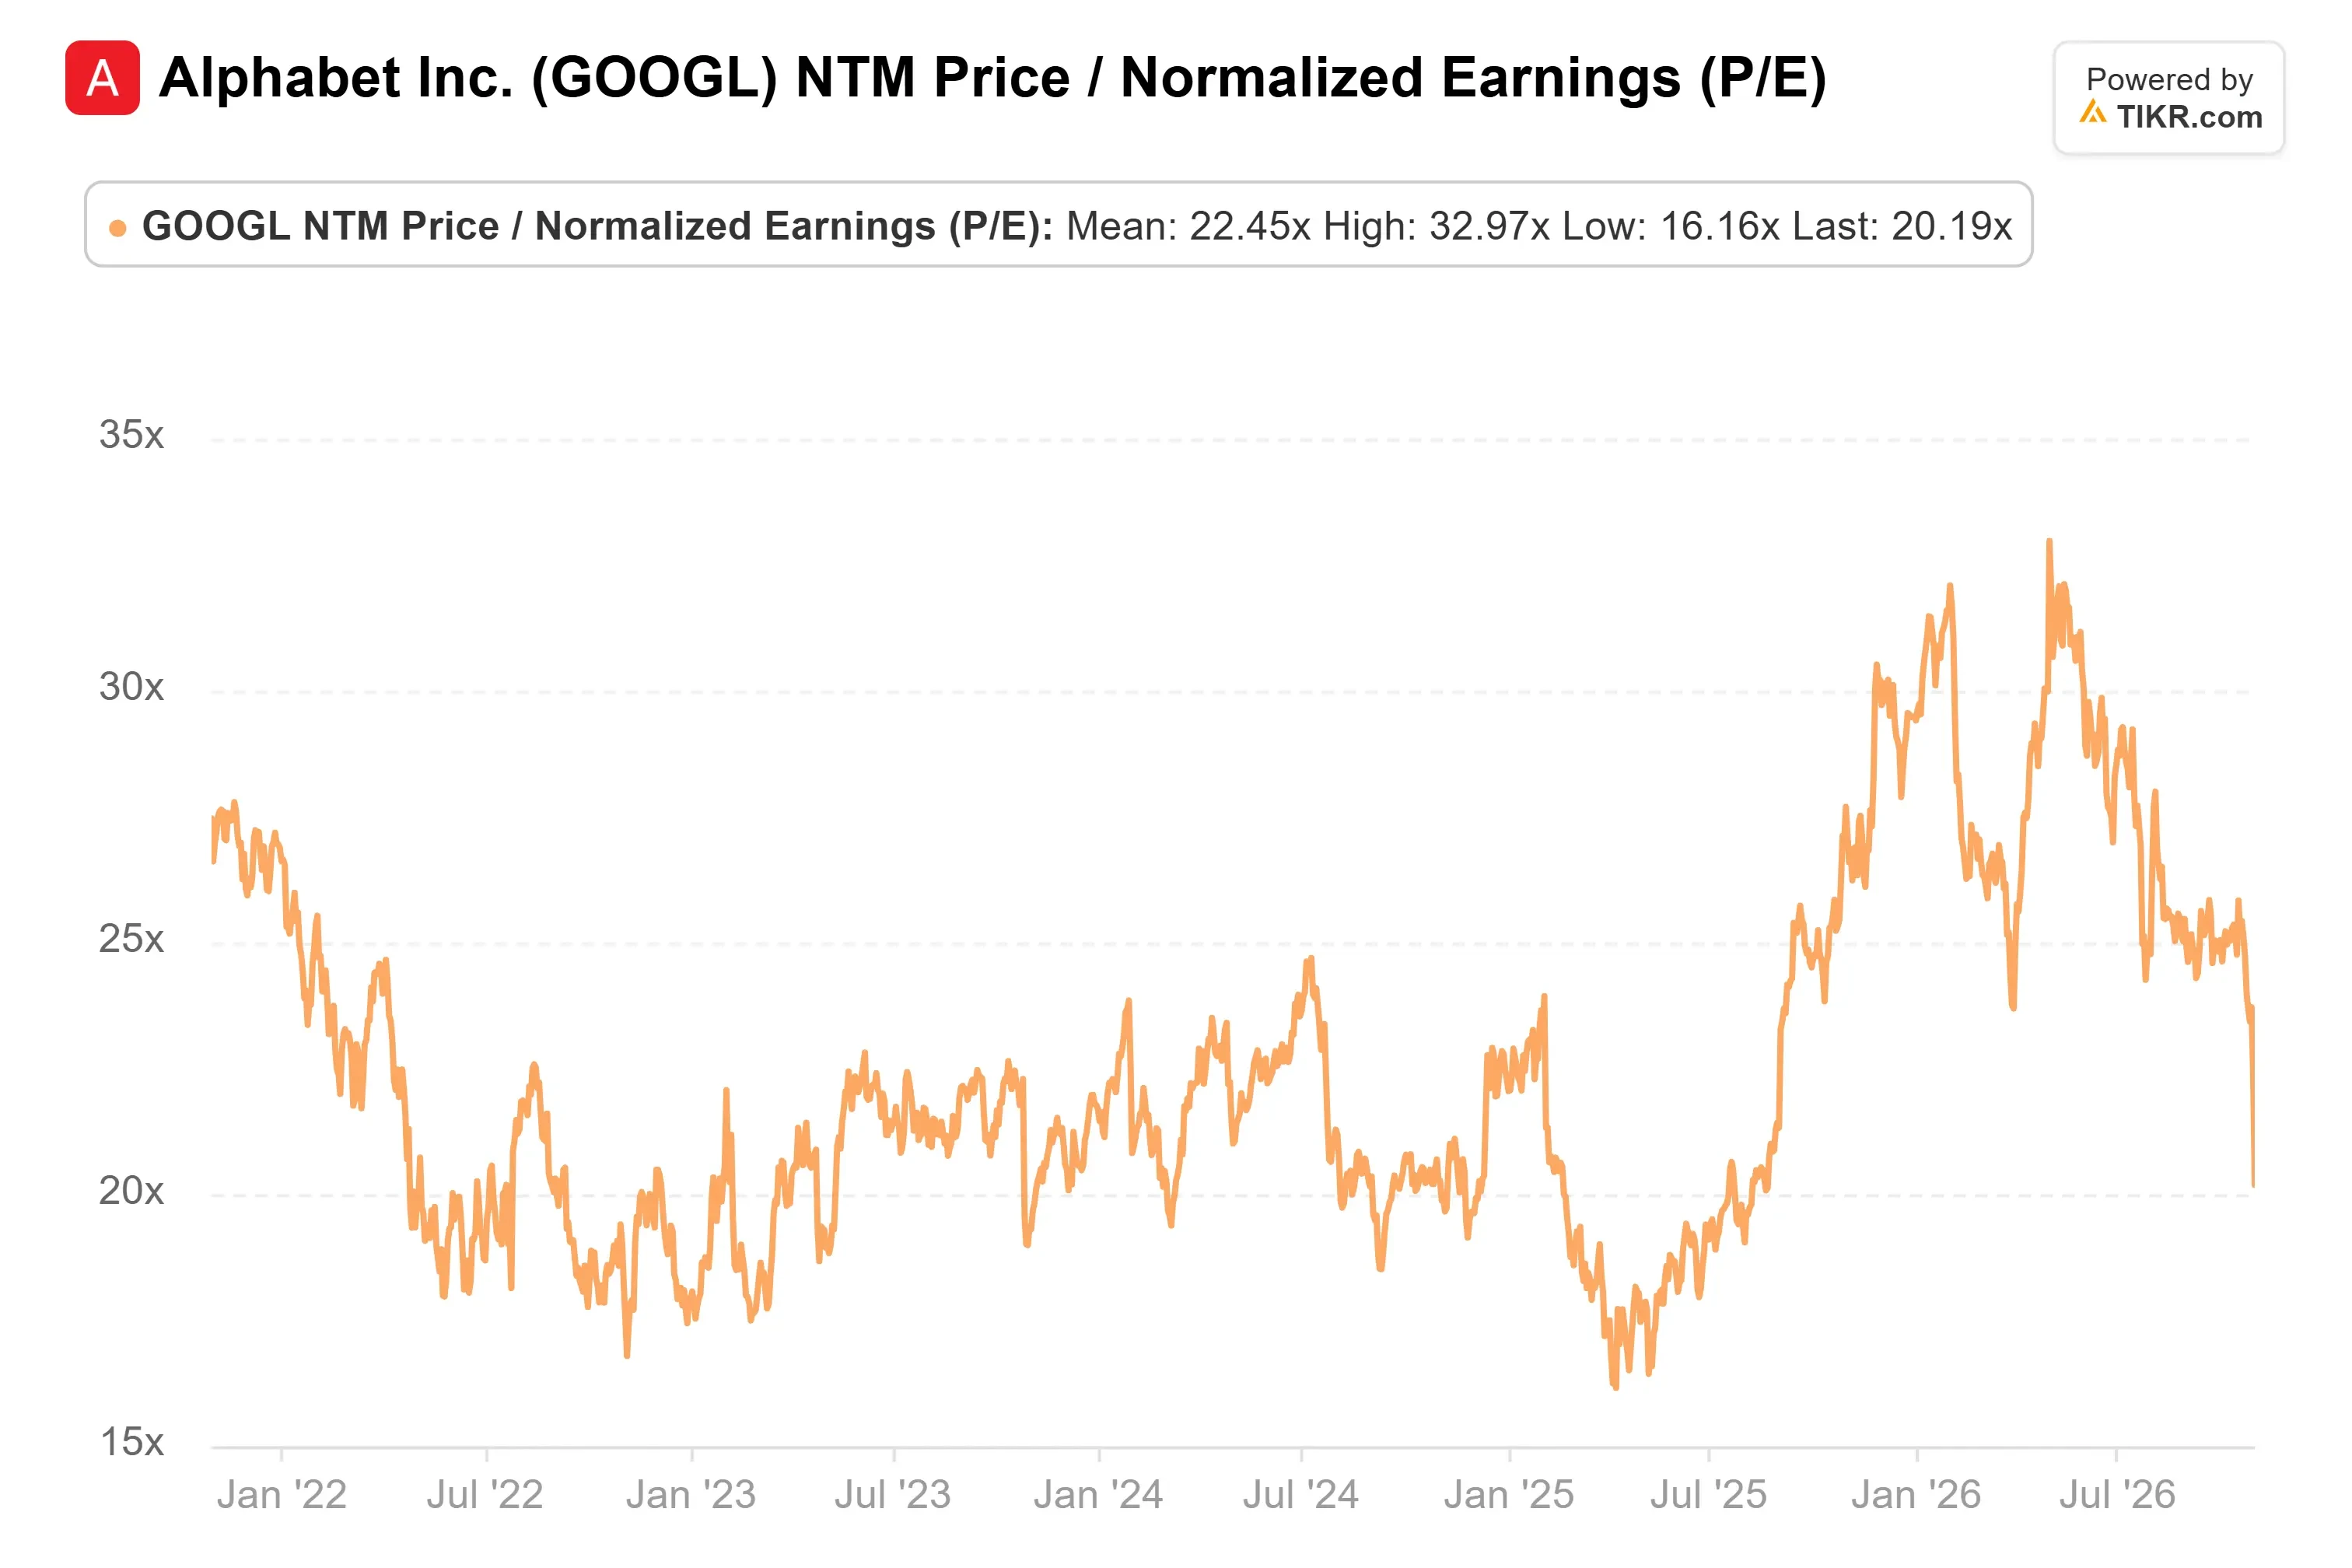
Divide $475 by the $14.49 a share analysts expect over the next twelve months, and you get about 33x, just above that April peak. The $475 GOOGL stock price target needs the tech stock to trade at a premium multiple.
The backlog has a concentration risk, too: Scotiabank estimates Anthropic accounts for about 22% of it.
My take: Pivotal is right about Cloud, and I’d expect a bounce from recent levels. But I can’t see investors paying a peak multiple within a year for a company with negative free cash flow and a rising share count. Pivotal’s $475 looks like a best case.
Alphabet plans to detail its 2027 spending on its Q4 call, likely in early February. A figure the backlog can carry would make Pivotal’s case far easier to defend.
So what is Alphabet stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Alphabet could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!