Key Takeaways
- Cameco shares fell 9% today after a third-quarter adjusted net loss of C$2 million, against adjusted net earnings of C$32 million a year earlier.
- Most of the damage came from a planned mill outage and a tough Westinghouse comparison, and the business underneath held up.
- Cash from operations nearly dried up in the quarter, and analysts’ 2026 earnings estimate looks too high now.
- NuScale Power and Oklo report next week, and both are still waiting on signed power contracts.
Cameco (CCJ) sank 9% today after posting a third-quarter adjusted net loss of C$2 million.
Utility contracting “is rarely linear,” CEO Tim Gitzel said in the release, “but customer requirements do not disappear.” He called AI possible extra upside, adding that Cameco’s “investment thesis does not depend on any single demand driver.” That sets it apart from NuScale Power (SMR) and Oklo (OKLO), which both report next week and are still waiting on signed power contracts.
Blame the mill (mostly)
A longer planned shutdown at Cameco’s Key Lake mill began in the third quarter. Production fell 20%, and the cash cost of each pound Cameco mined jumped 62% to C$40.73. That swamped a 6% rise in its realized uranium price, and gross profit fell 28% on flat revenue of C$619 million.
Westinghouse, the reactor business Cameco owns 49% of, looks worse than it is. Cameco blames Westinghouse’s weaker nine months on a big Dukovany project payment last year. In the third quarter, Cameco’s share of Westinghouse’s adjusted EBITDA rose 15% to C$143 million.
The cash is the sore spot
Cash from operations fell to C$3 million in the quarter from C$156 million.
Analysts expected Cameco’s earnings to nearly double in 2027:
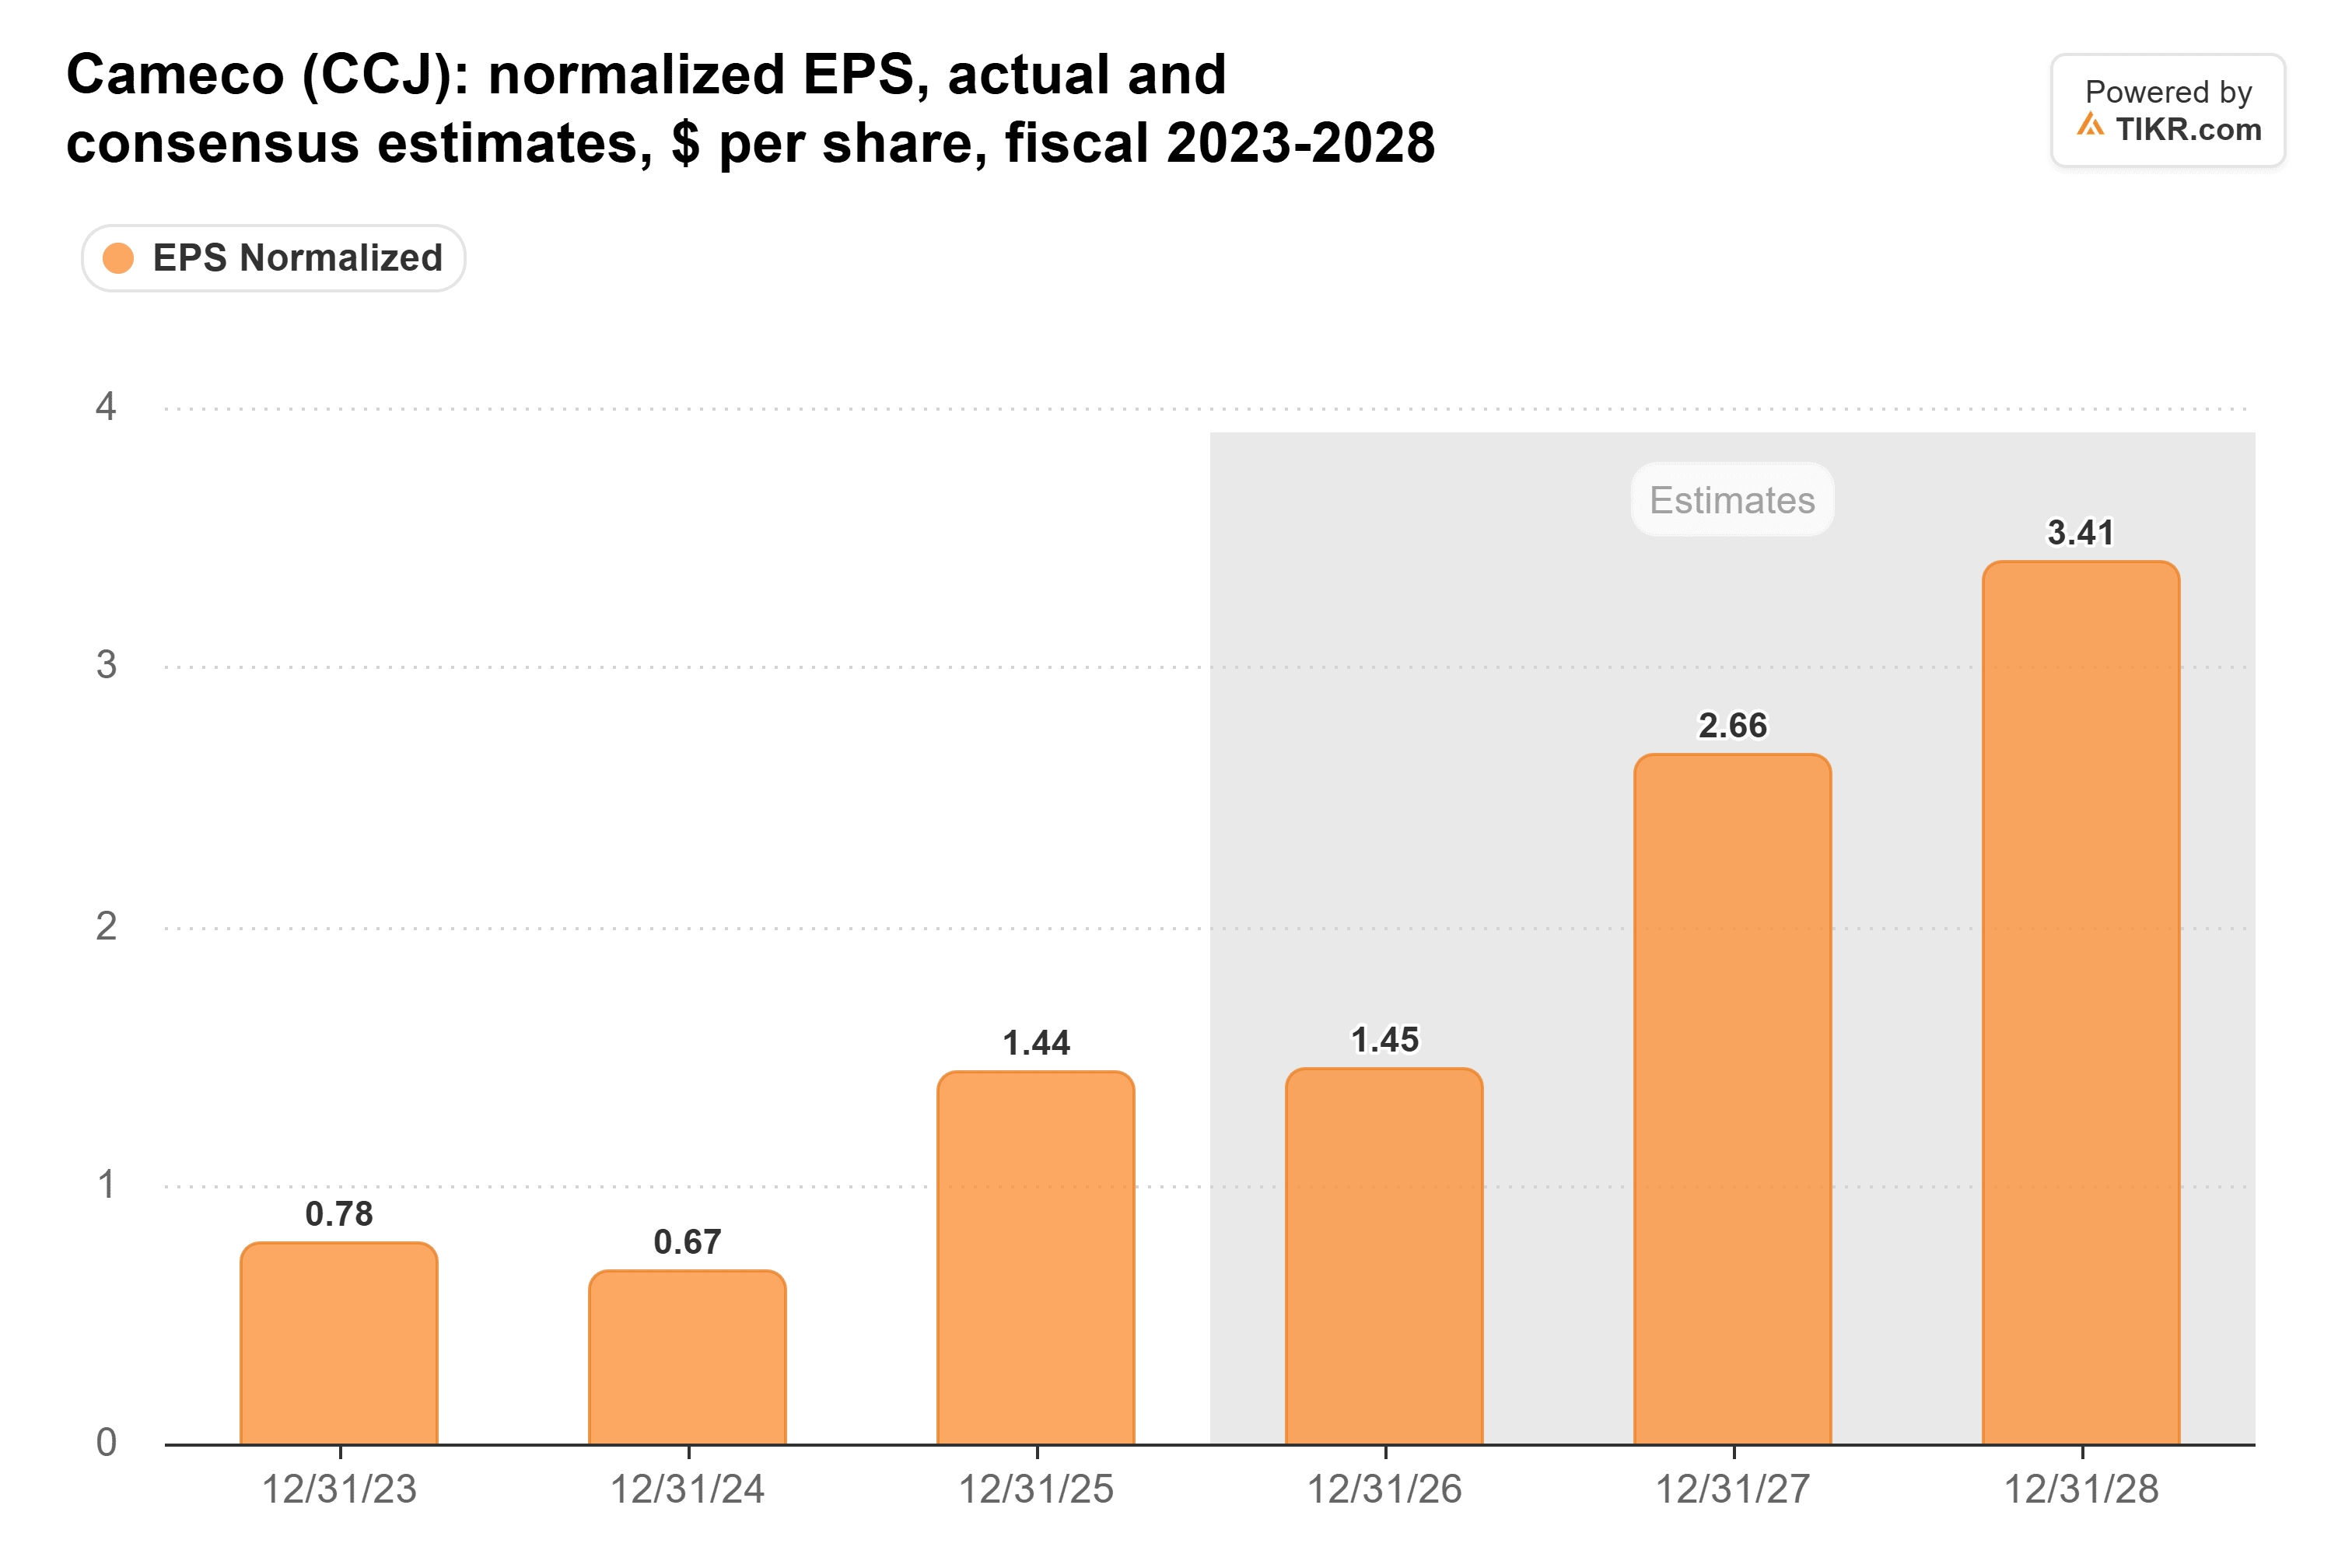
The 2026 estimate of C$1.45 looks too high now: getting there would take more adjusted earnings in the fourth quarter than in the first three combined. But the outage is a 2026 problem, and nothing in the release argues against 2027’s C$2.66.
TIKR tracks 21 analysts on Cameco. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Cameco, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Cameco’s Analyst Ratings
No contract book to lean on
Cameco has contracts for average deliveries of over 28 million pounds of uranium a year through 2030, a cushion NuScale and Oklo don’t have yet.
NuScale’s partner ENTRA1 is still working toward a definitive power purchase agreement with the Tennessee Valley Authority. Oklo has a prepayment agreement with Meta for an Ohio campus, but management said in March it expected the power purchase agreement itself over roughly the next year. Next week’s question for both: has interest turned into a signed contract?
A better price on the same story
My take: this was about as rough as a planned outage makes a quarter, and Westinghouse held up underneath. Cameco traded at 54x forward earnings at the last close, below its 3-year average of 61x, and today’s drop takes it to about 50x. That’s a better price on the same story.
Of course, 50x still asks a lot, and the next real test is February, when Cameco gives its 2027 production guidance.
So what is Cameco stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Cameco could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!