Key Takeaways
- Pinterest shares fell 7% today after third-quarter revenue of $1.17 billion missed estimates and its fourth-quarter guidance came in below Wall Street’s.
- Europe’s revenue was flat as cross-border sellers pulled back, while U.S. and Canada revenue grew 14%.
- Reddit’s strong international growth suggests the problem is Pinterest’s own, and Meta’s rising ad prices show where Pinterest is falling behind.
- Analysts’ 2026 revenue estimates look too high, but the stock already prices in far worse.
Pinterest (PINS) stock sank 7% today after its third-quarter revenue missed estimates and its fourth-quarter guidance came in light. CEO Bill Ready didn’t sugarcoat it on the earnings call: “Overall, Q3 revenue came in below our range. We are not happy with that result.”
So is this Pinterest’s problem, or the ad market’s? Reddit (RDDT), which reported the same night, suggests it’s mostly Pinterest’s. Meta Platforms (META) points to a bigger worry.
Blame Europe
Revenue rose 12% to $1.17 billion, short of the $1.21 billion analysts expected, even with a record 661 million monthly users. The regional split shows where it went wrong:
- U.S. and Canada: $894 million, up 14%
- Europe: $193 million, flat
- Rest of world: $87 million, up 24%
Ready blamed changes to Europe’s de minimis exemption for low-value imports. They hit cross-border sellers harder than Pinterest expected, and he said that pullback took about 3 points off its growth rate from the second quarter.
Reddit’s quarter backs that up: its international revenue grew 67% to $176 million. If advertisers were fleeing social media, it wouldn’t.
Meta worries me more. It sells to many of the same e-commerce advertisers, and its average price per ad rose 14% in the third quarter. Pinterest’s ad impressions rose 17%, but its ad prices fell 4%. That’s a tough way to grow while the biggest platform charges more.
TIKR tracks 39 analysts on Pinterest. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Pinterest, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Pinterest’s Analyst Ratings
Estimates look too high
Pinterest’s fourth-quarter guidance of $1.425-$1.475 billion sits well below the $1.52 billion analysts expected. And for the full year, analysts were expecting $4.91 billion of revenue in 2026:
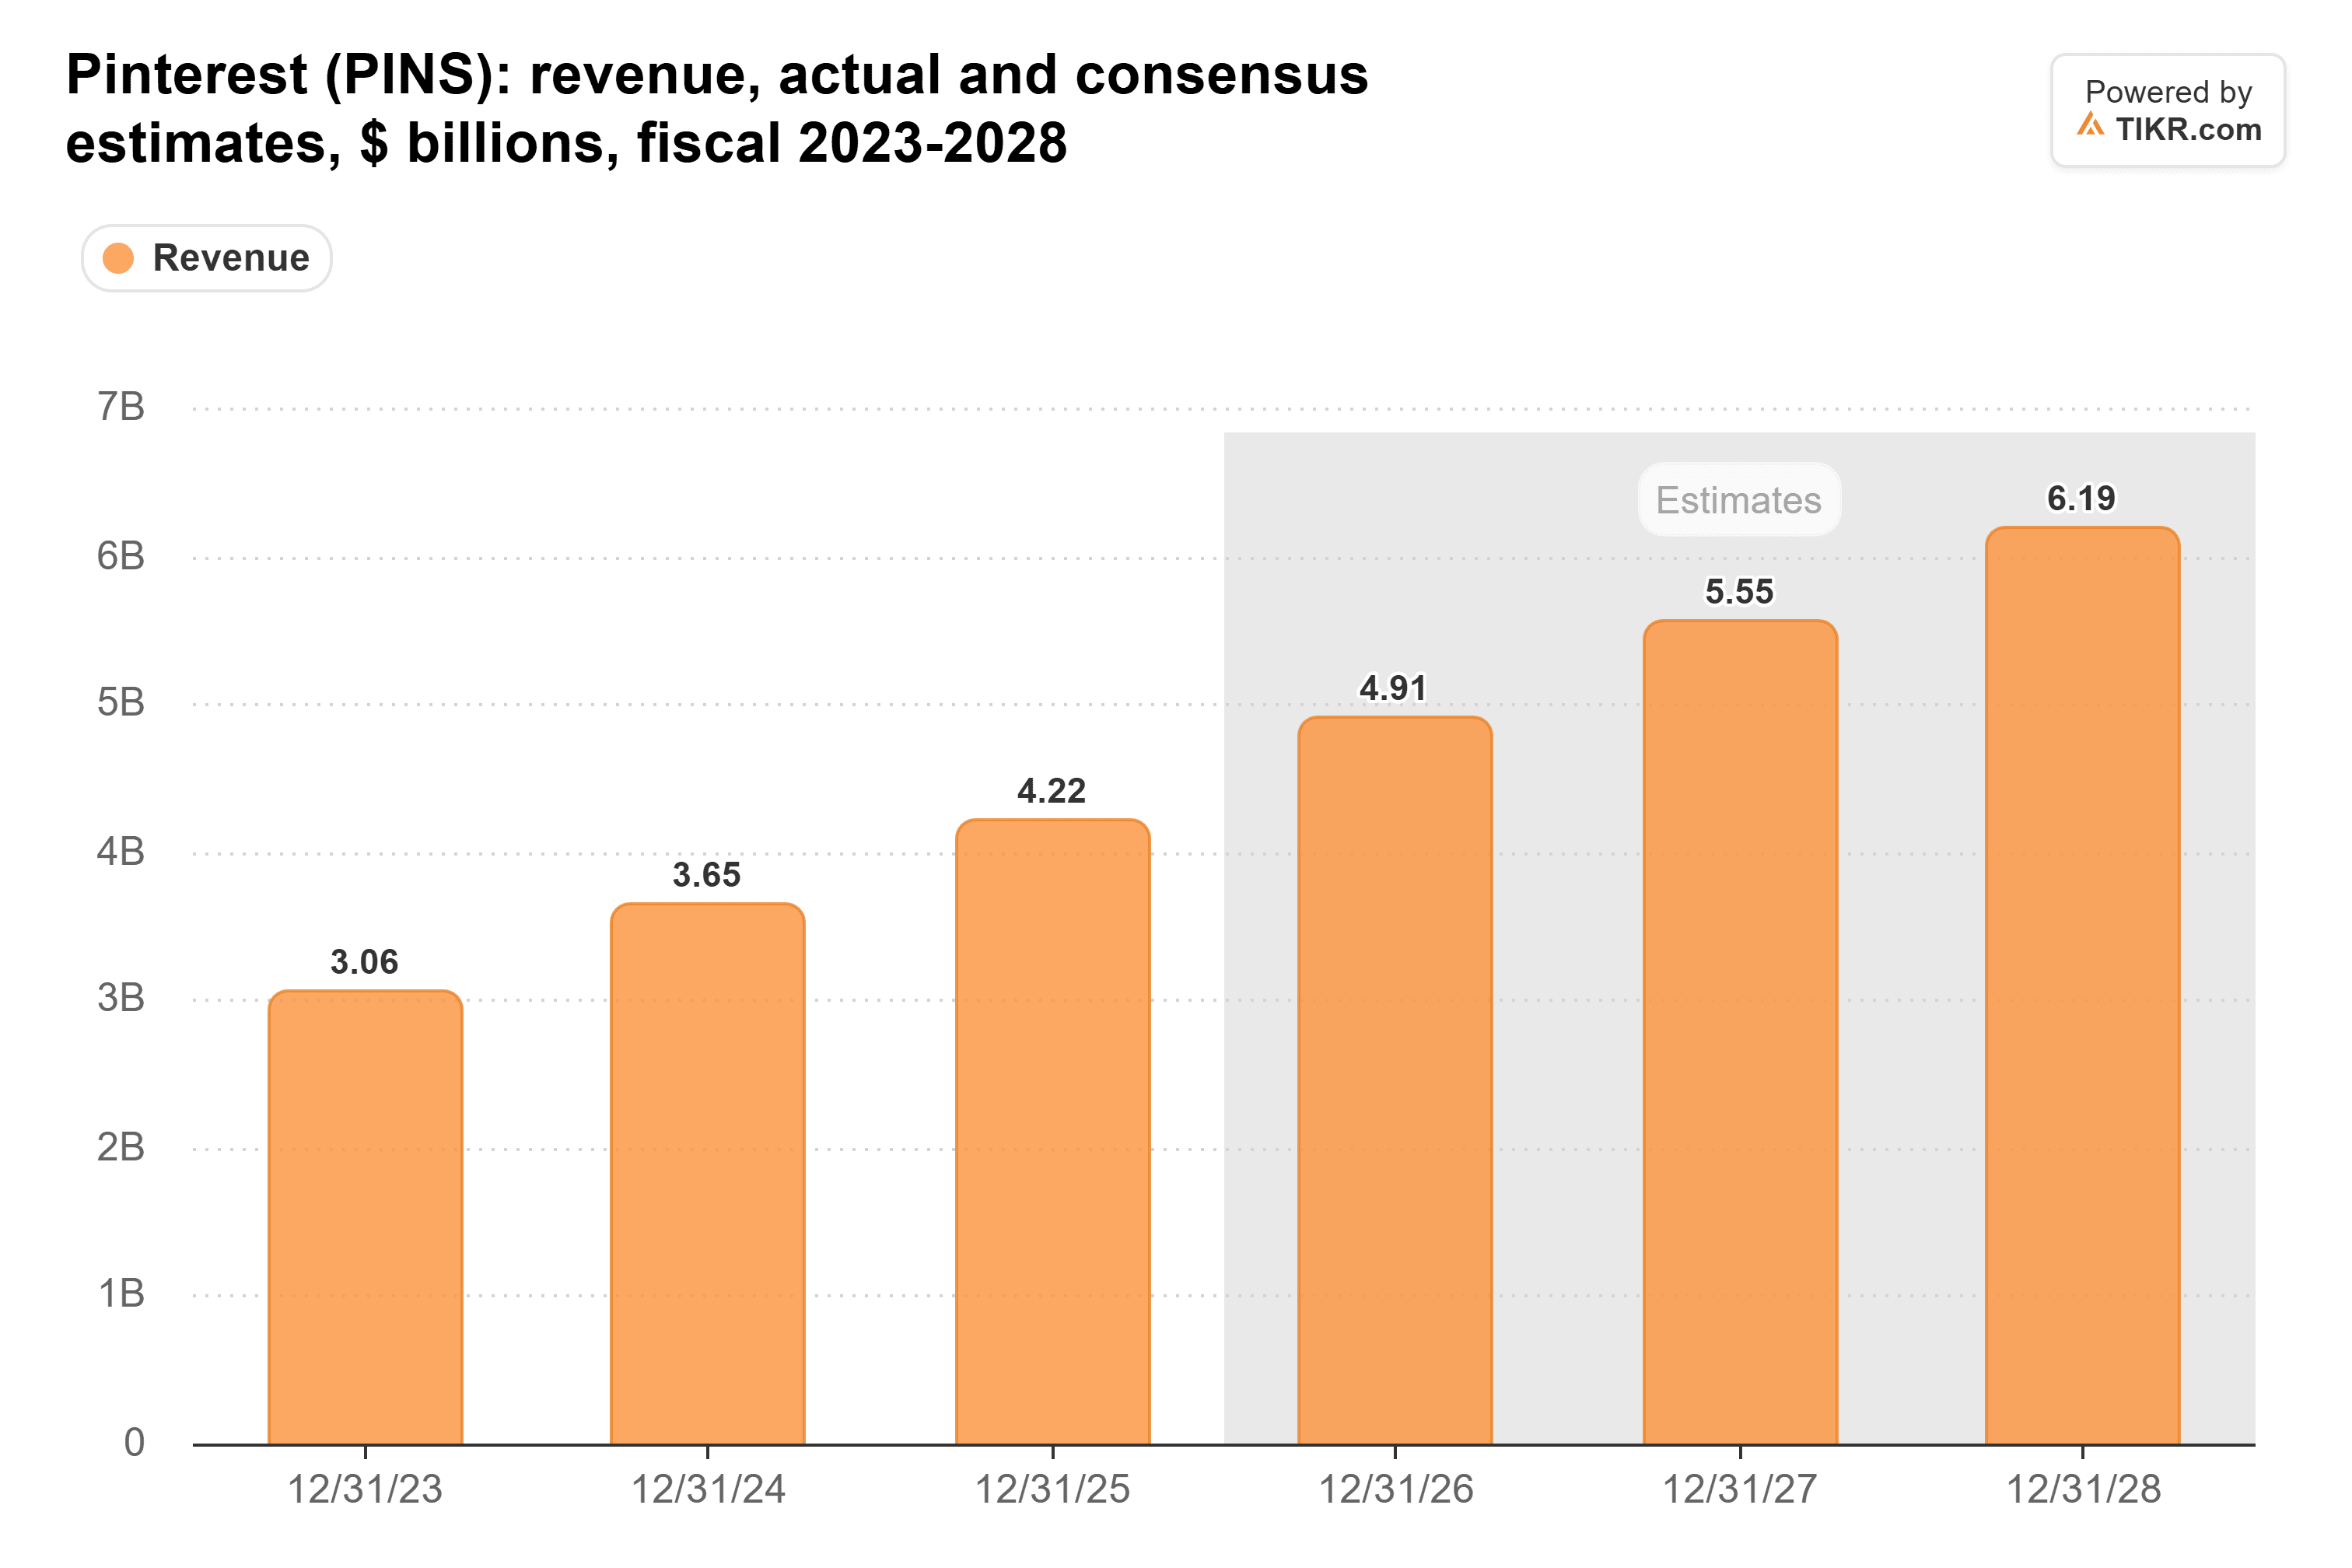
Even the top of the new guidance leaves 2026 revenue around $4.84 billion, so I’d expect those estimates to come down.
Already priced for worse
The stock was cheap going in, at 8.8x forward earnings at the last close against a five-year average of 24x:
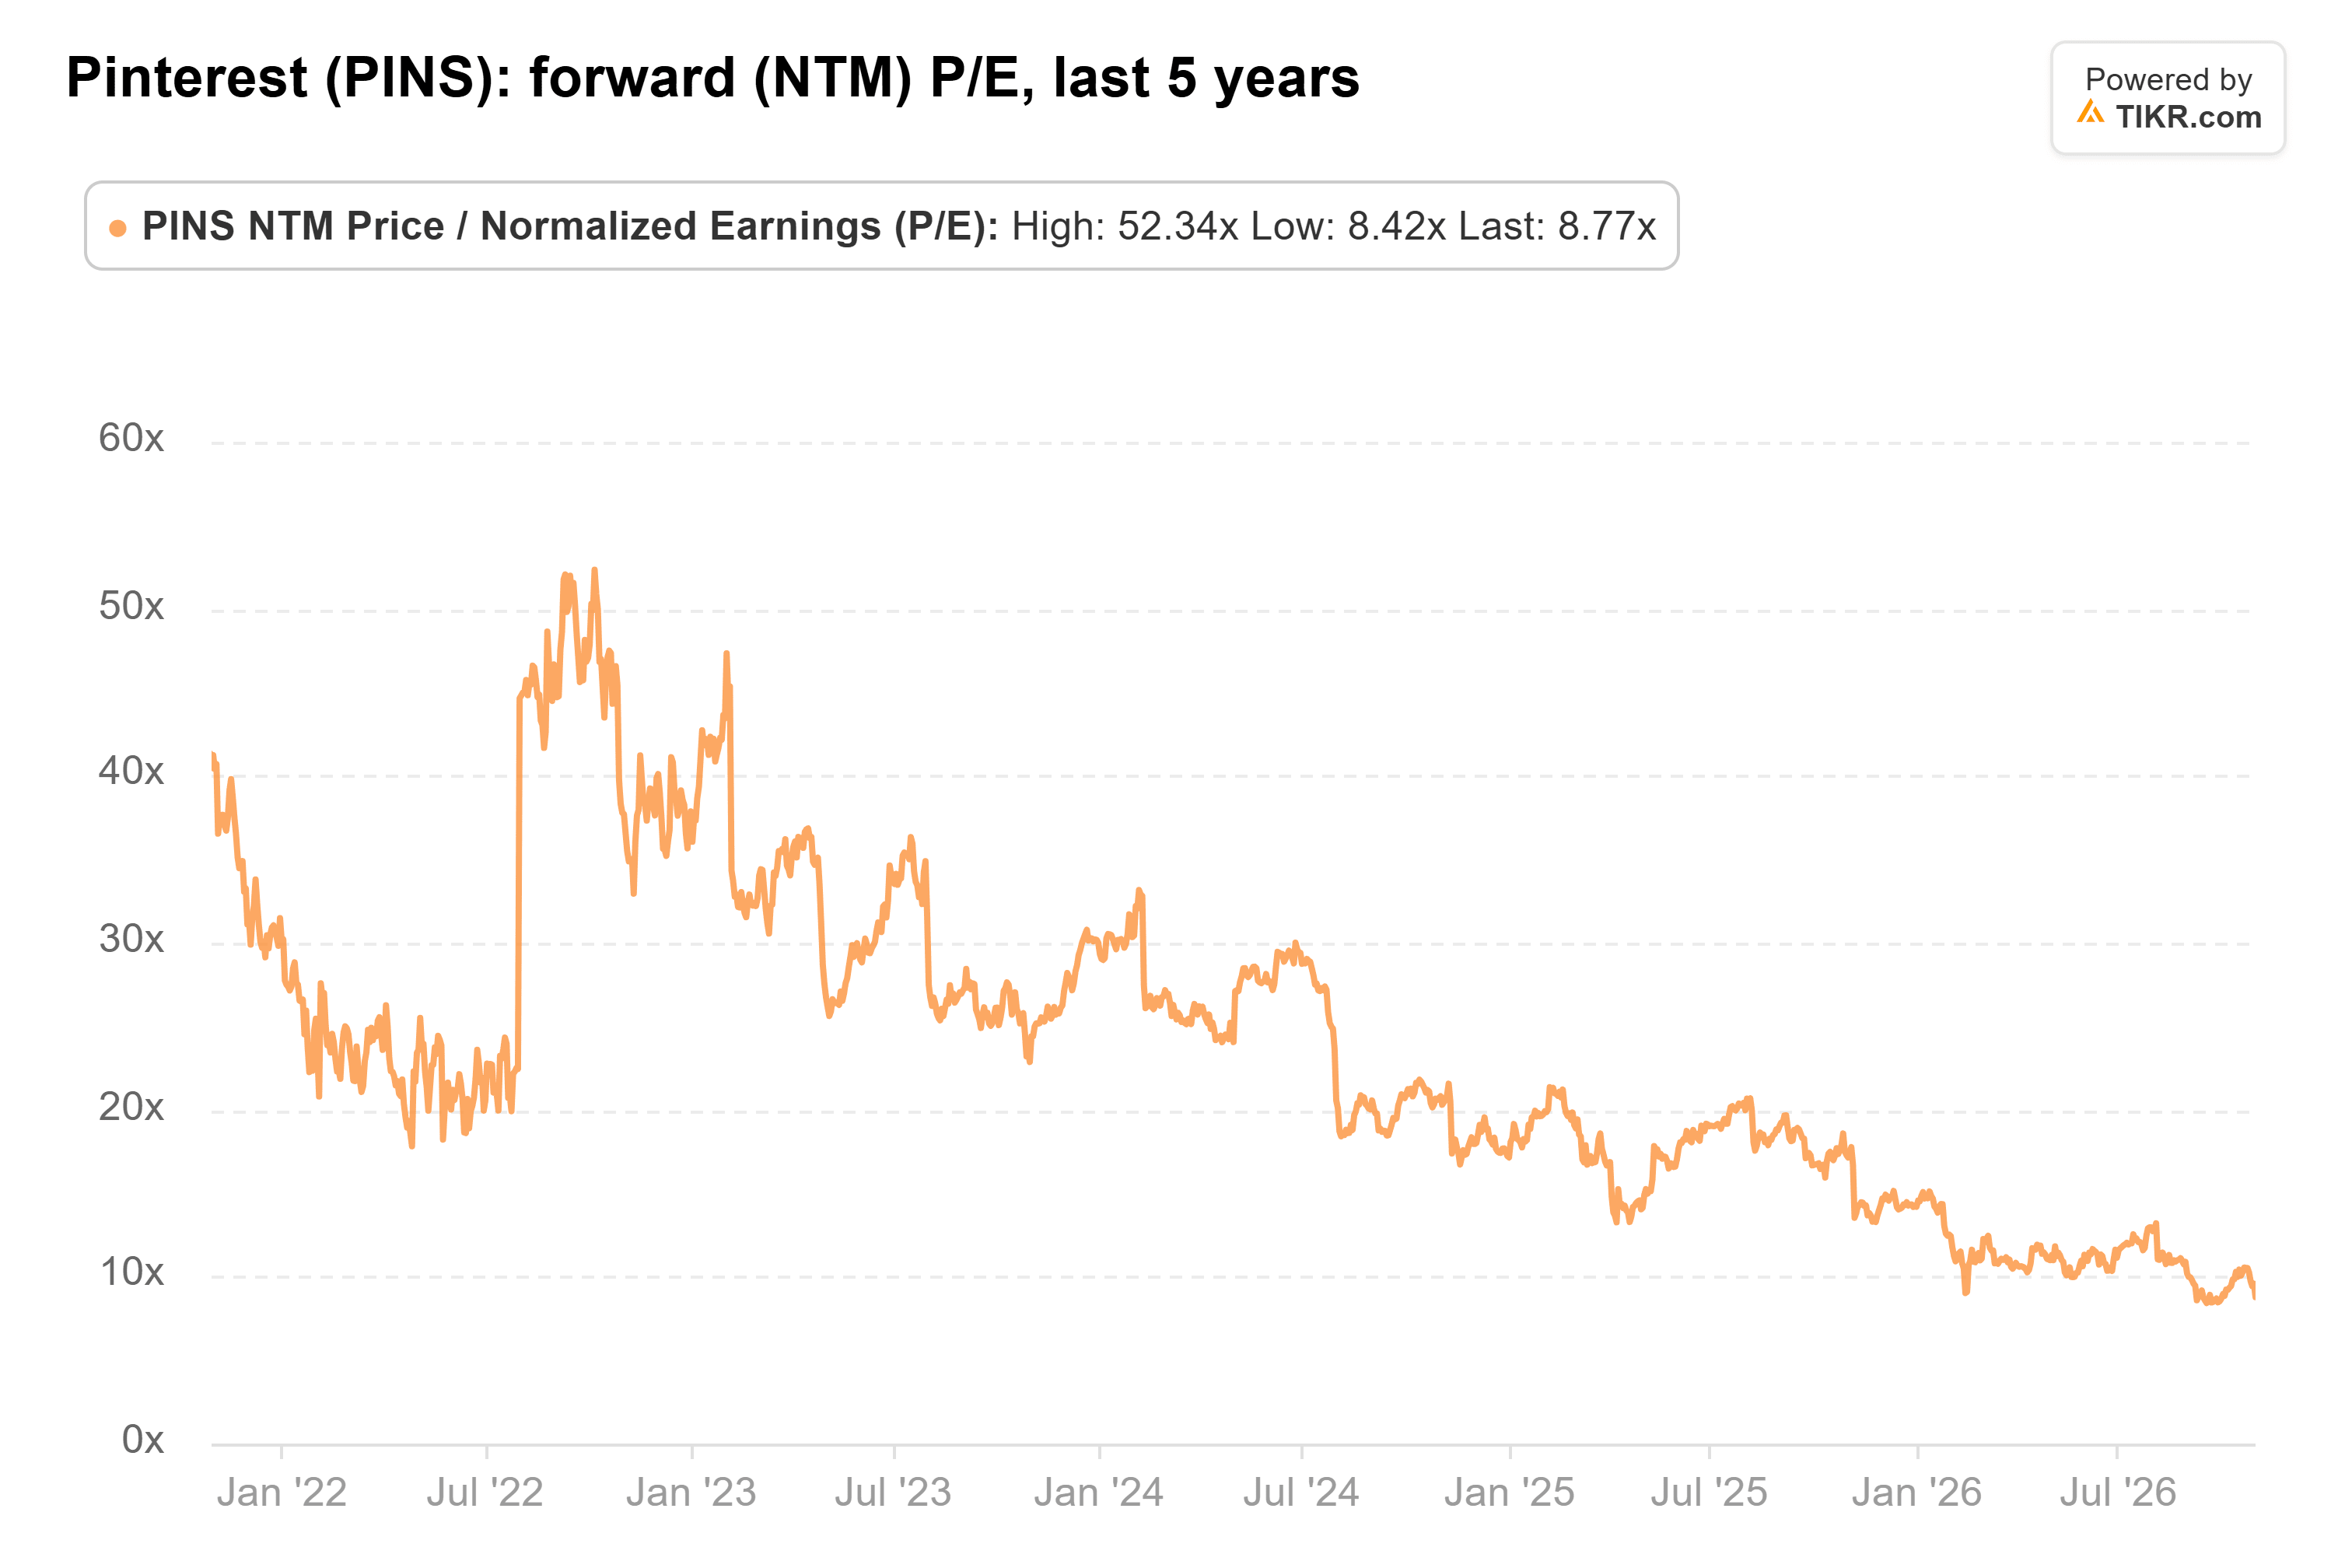
At today’s price, it’s even lower. The catch: third-quarter stock pay of $288 million nearly matched its $300 million of free cash flow, and that P/E leaves it out.
My take: this miss came from one region and one group of advertisers, and the multiple already assumes far worse. That’s five drops after Pinterest’s last six reports, and this one looks overdone.
Of course, guidance this light says Europe’s pressure hasn’t passed. Fourth-quarter results in February, the first full quarter under new CFO James Dibbo, are the next test.
So what is Pinterest stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Pinterest could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!