Key Takeaways
- Capri Holdings jumped 17% after fiscal second-quarter adjusted EPS of $0.42 doubled the $0.21 consensus and it raised its outlook.
- A higher gross margin and interest income drove the beat, while revenue fell 5.5%.
- Third-quarter revenue guidance came in below consensus, leaving the second half’s return to growth to the March quarter.
- Tapestry and Ralph Lauren report next week, a test of whether full-price demand held up for Kors’ rivals.
Capri Holdings (CPRI) jumped 17% today after its fiscal second-quarter adjusted EPS of $0.42 doubled the $0.21 consensus. It also raised its full-year EPS outlook to about $2.20, above the $2.12 consensus.
CEO John Idol said “trends improved sequentially each month” at Michael Kors and Jimmy Choo. That matters beyond Capri: Tapestry (TPR) has grown its Coach brand while Kors shrinks, and Ralph Lauren (RL) is leaning on the same full-price selling.
Margins did the heavy lifting
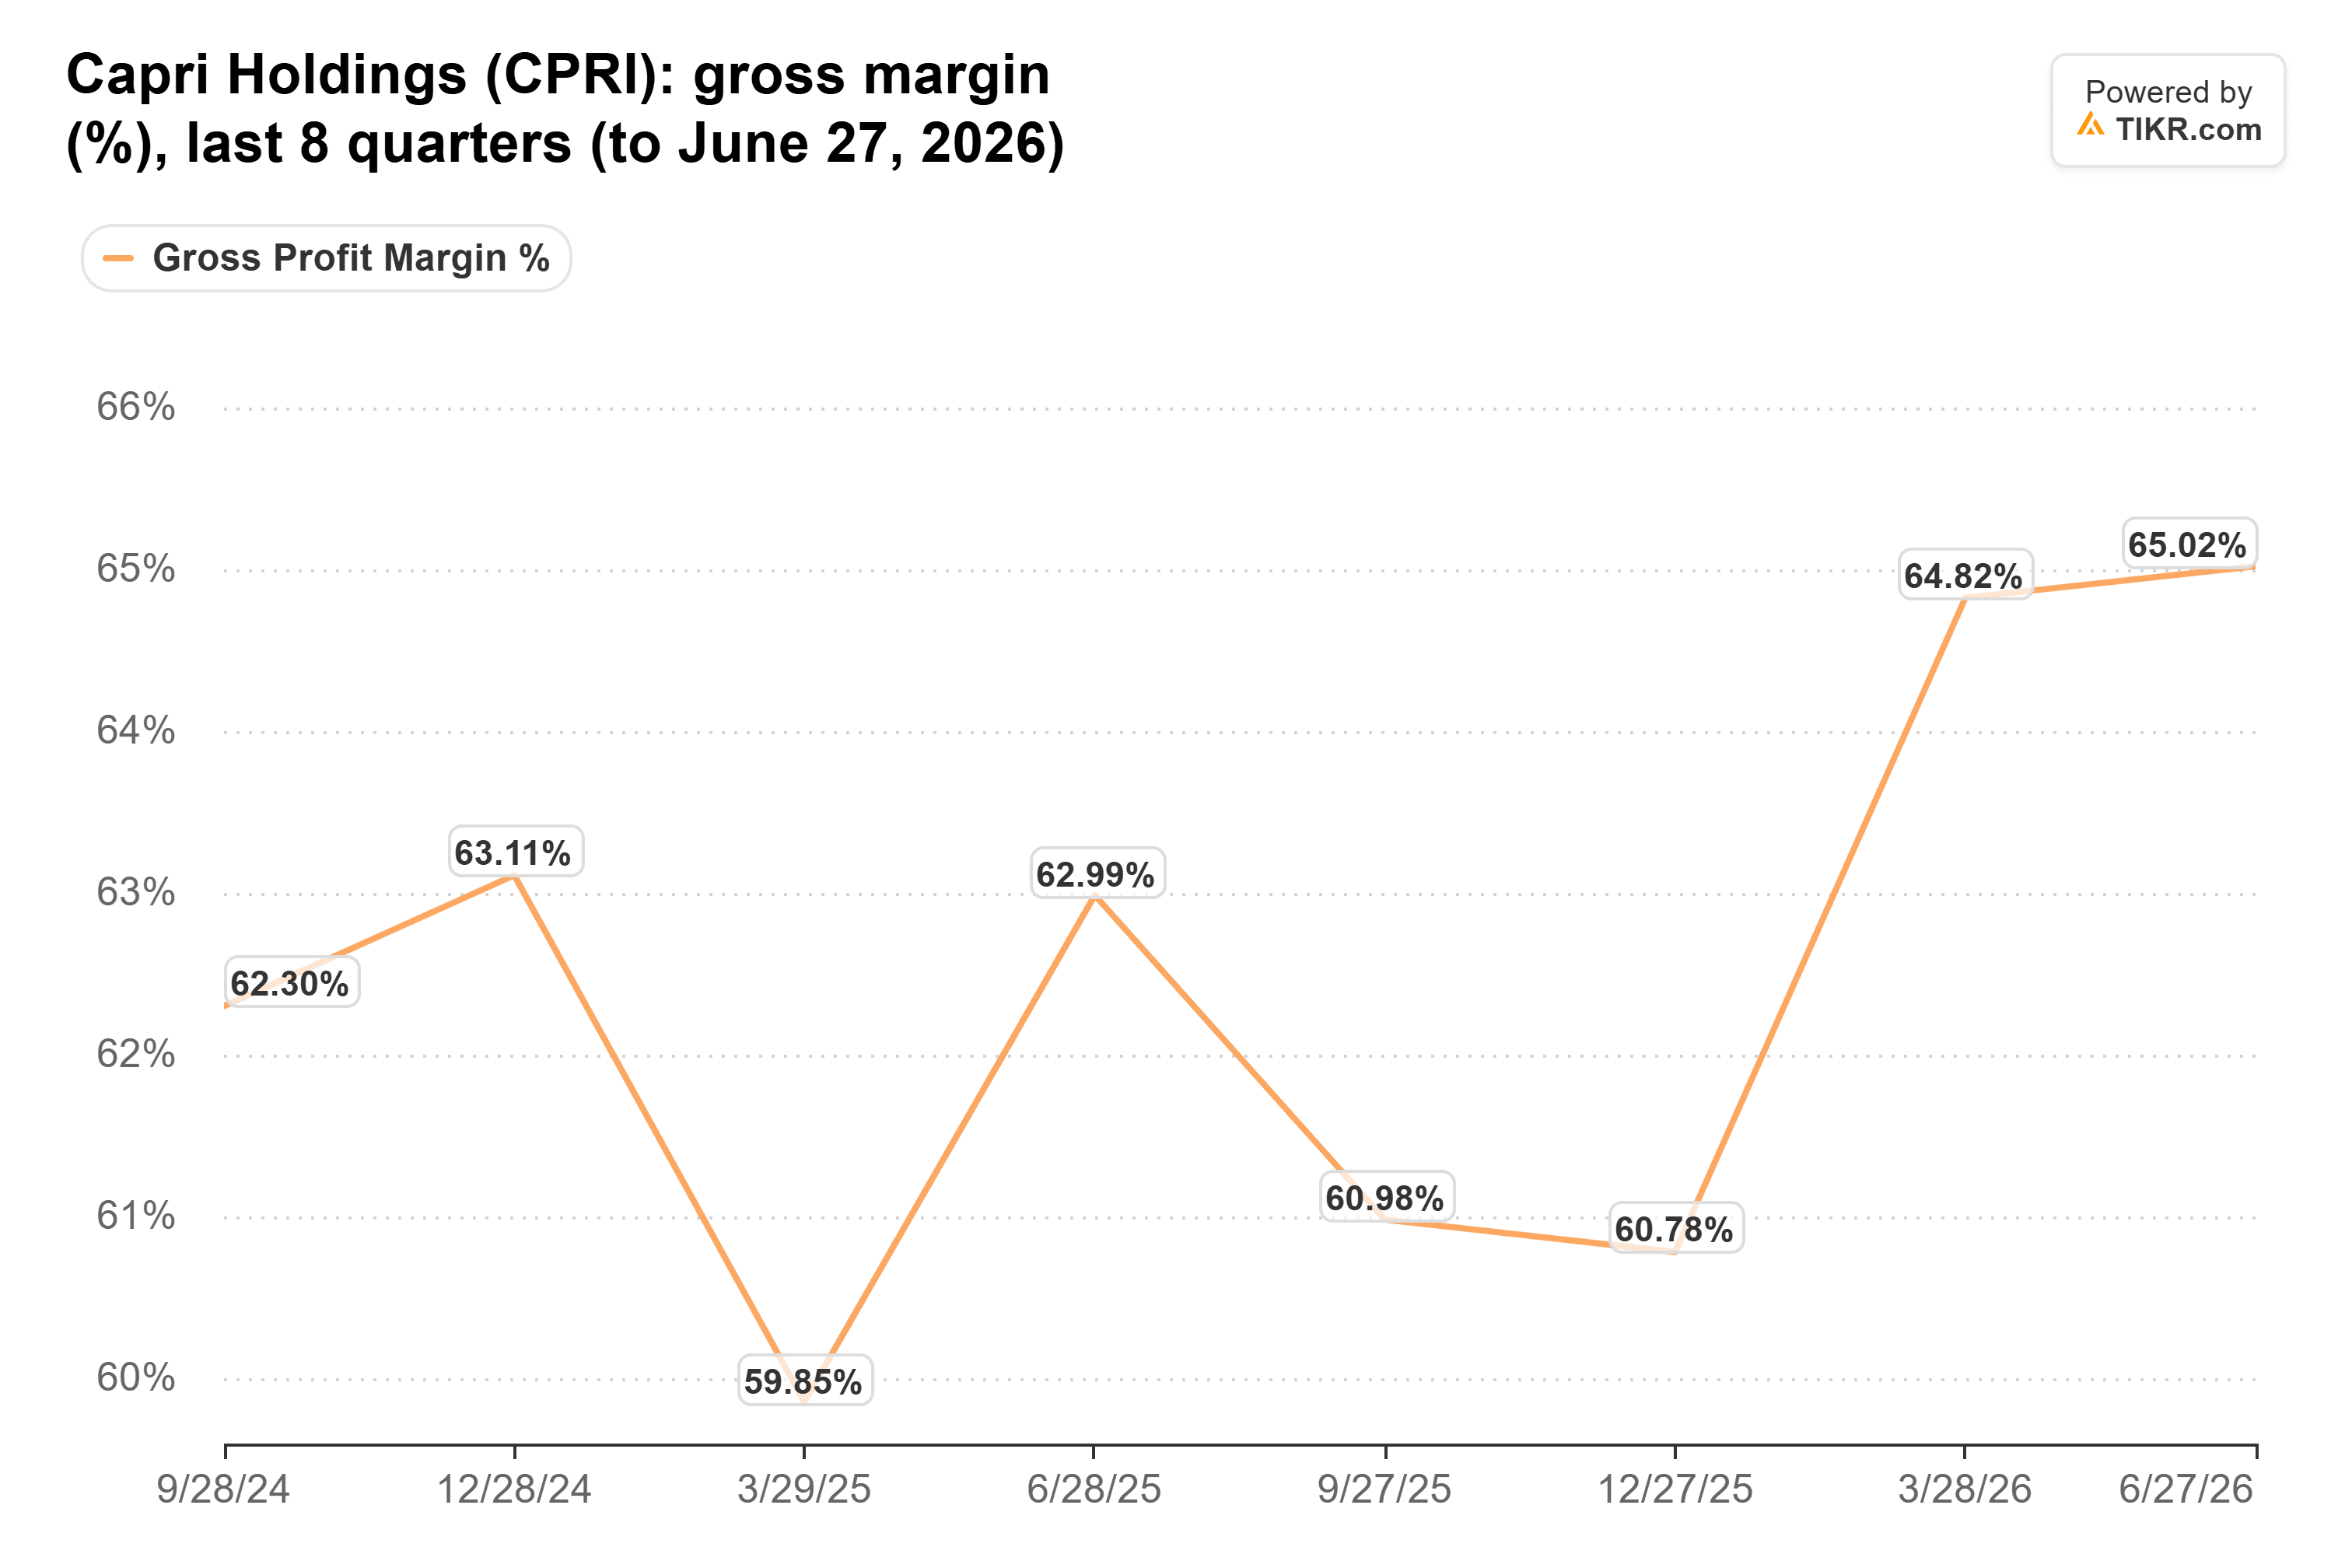
Gross margin rose 230 basis points to 63.3%. Capri credited full-price selling, brand mix and lower tariffs. It had also topped 64% in the two quarters through June:
Interest income rose to $31 million from $17 million a year earlier.
Revenue still has to turn
Revenue fell year over year in each of the four quarters through June:
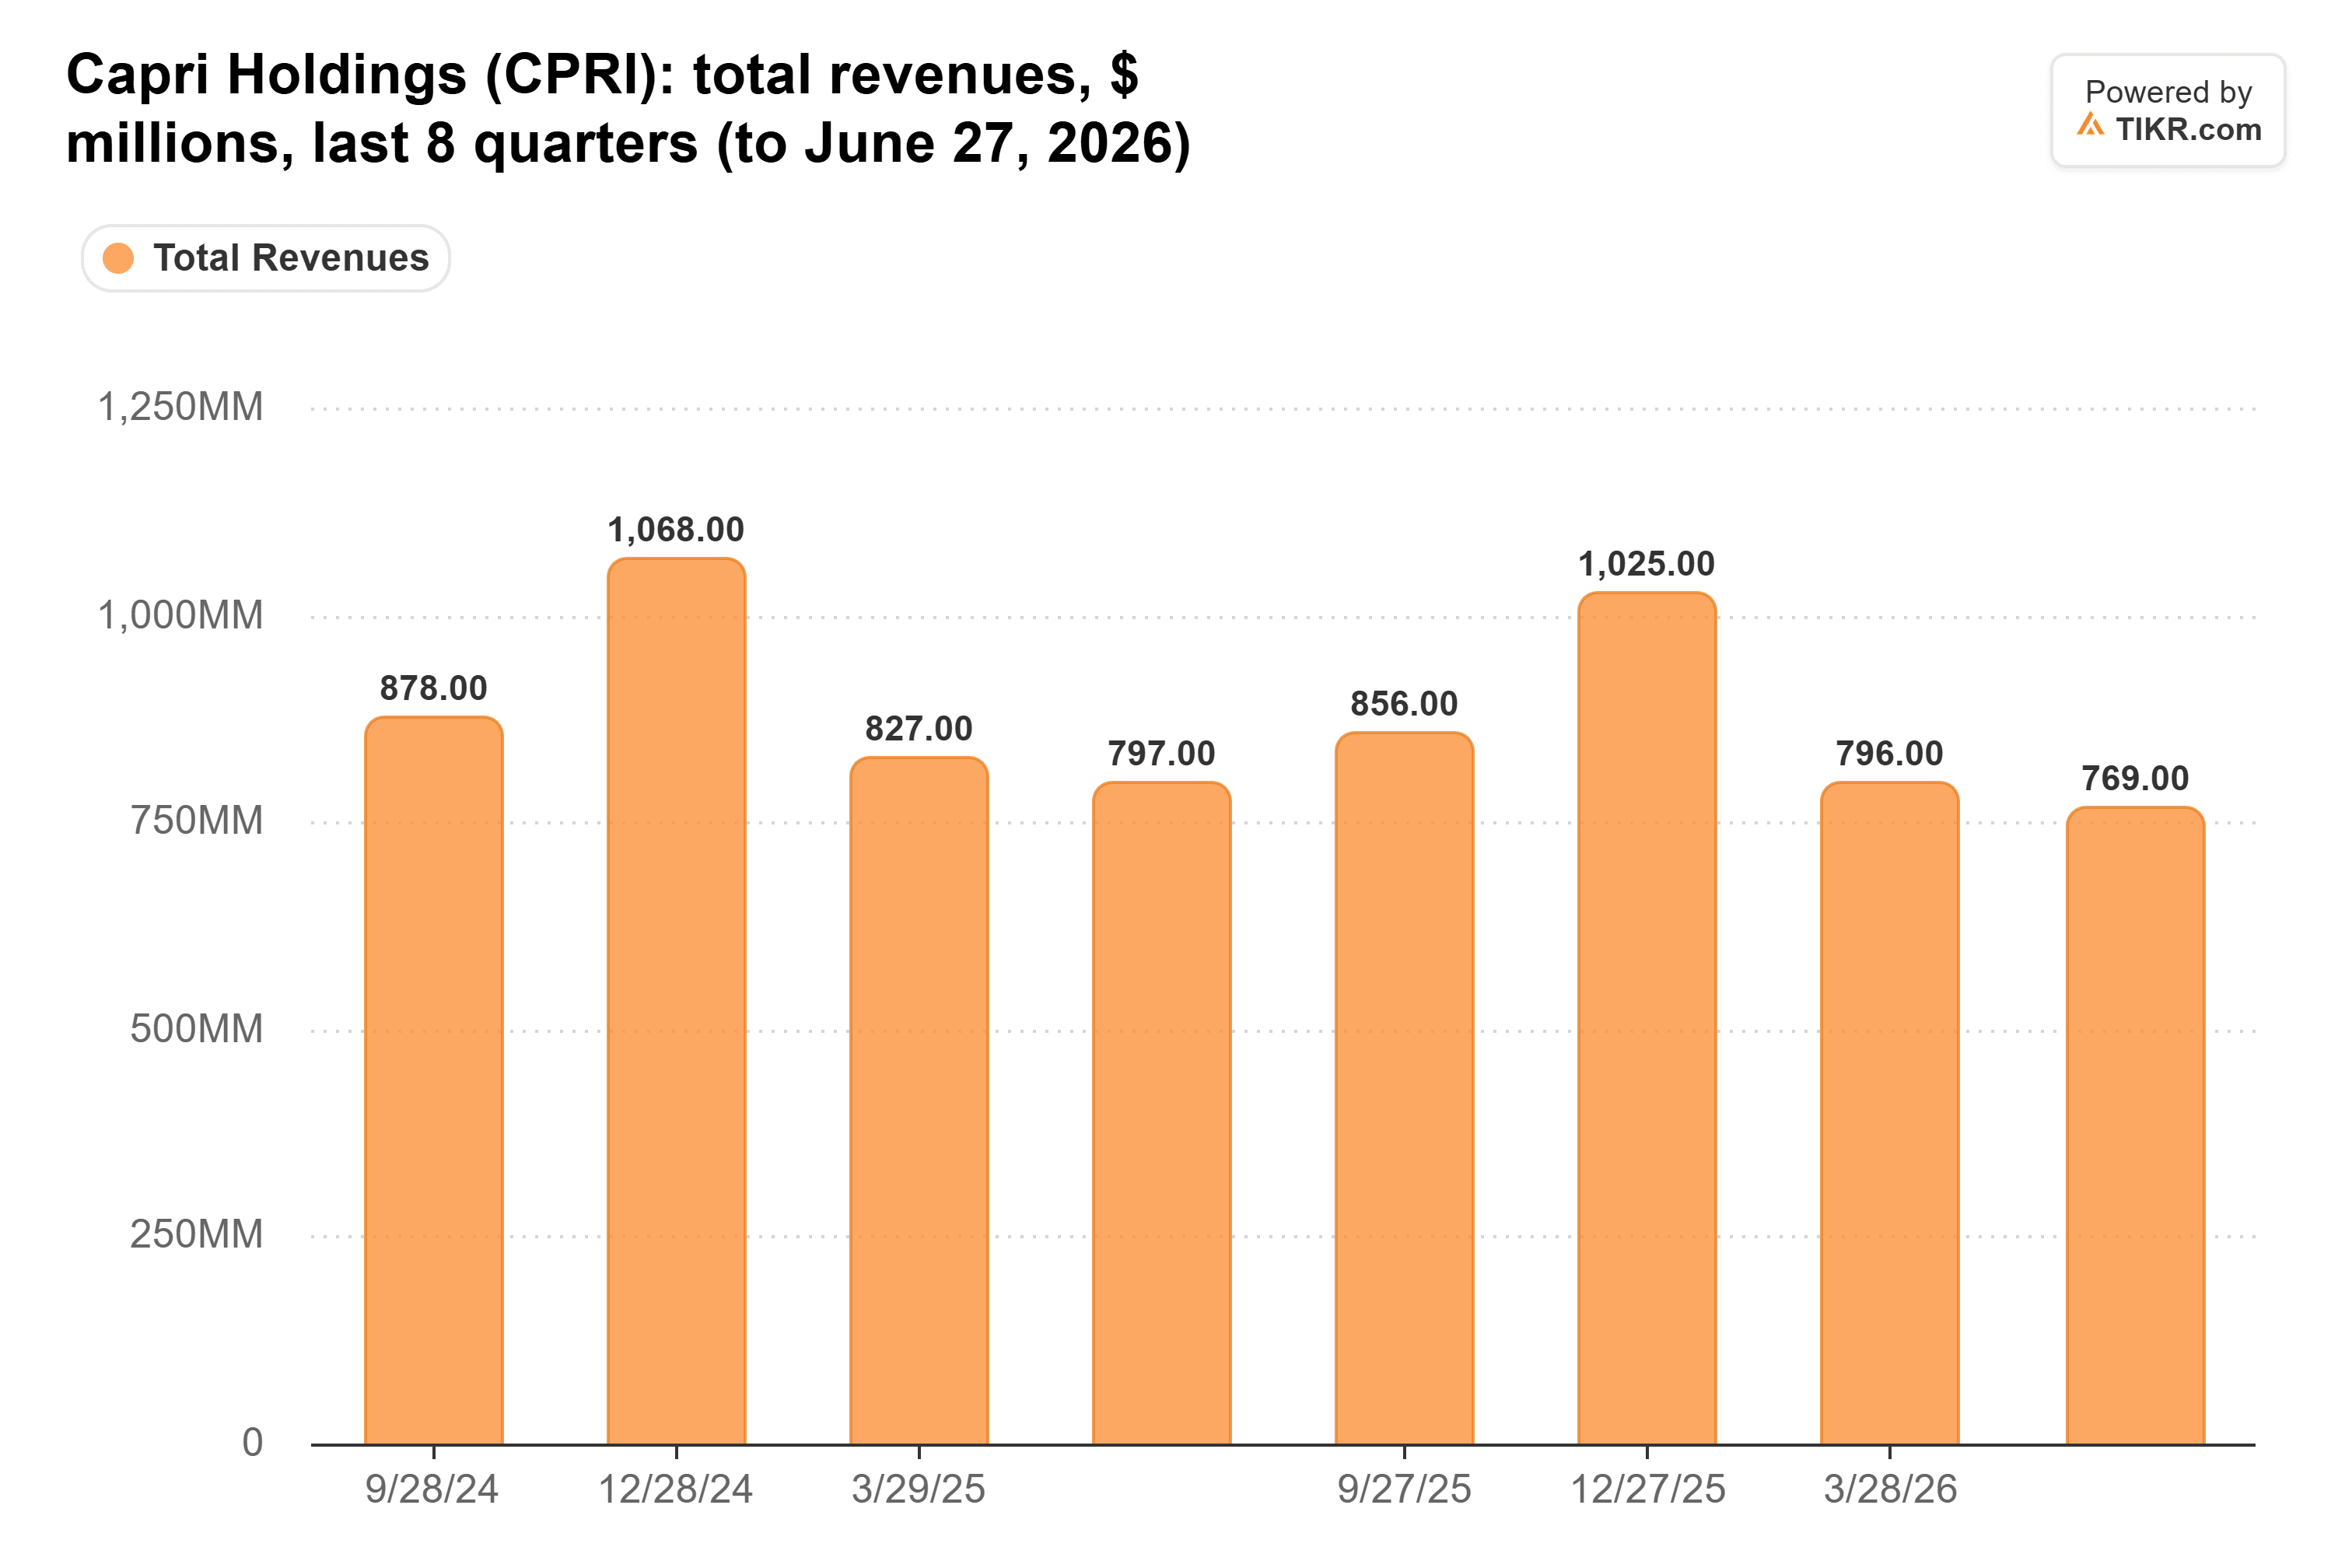
The September quarter made it five in a row, with revenue down 5.5% to $809 million and Kors down 8.6%. About $20 million of those sales were wholesale shipments pulled from the December quarter, which Capri guided to about $1 billion of revenue, below the $1.02 billion consensus and last year’s $1.03 billion.
The full-year outlook implies second-half revenue just 1% above last year’s, so the March quarter has to do the growing.
TIKR tracks 15 analysts on Capri Holdings. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Capri Holdings, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Capri Holdings’ Analyst Ratings
What it means for Kors’ rivals
Kors’ sales in the Americas fell 11% to $405 million. In Tapestry’s quarter to June, Coach grew 15% and North America revenue rose 7% in constant currency. If Kors really is turning, Tapestry’s report next week will show whether that growth slows.
Ralph Lauren also credited full-price selling for its June-quarter gross margin, which rose 140 basis points to 73.7%. Did that hold through September, as it did at Capri?
Cheap, if the growth shows up
Capri traded at 8.5x forward earnings at yesterday’s close, below its five-year average of 11x. Today’s jump still leaves it under 10x:
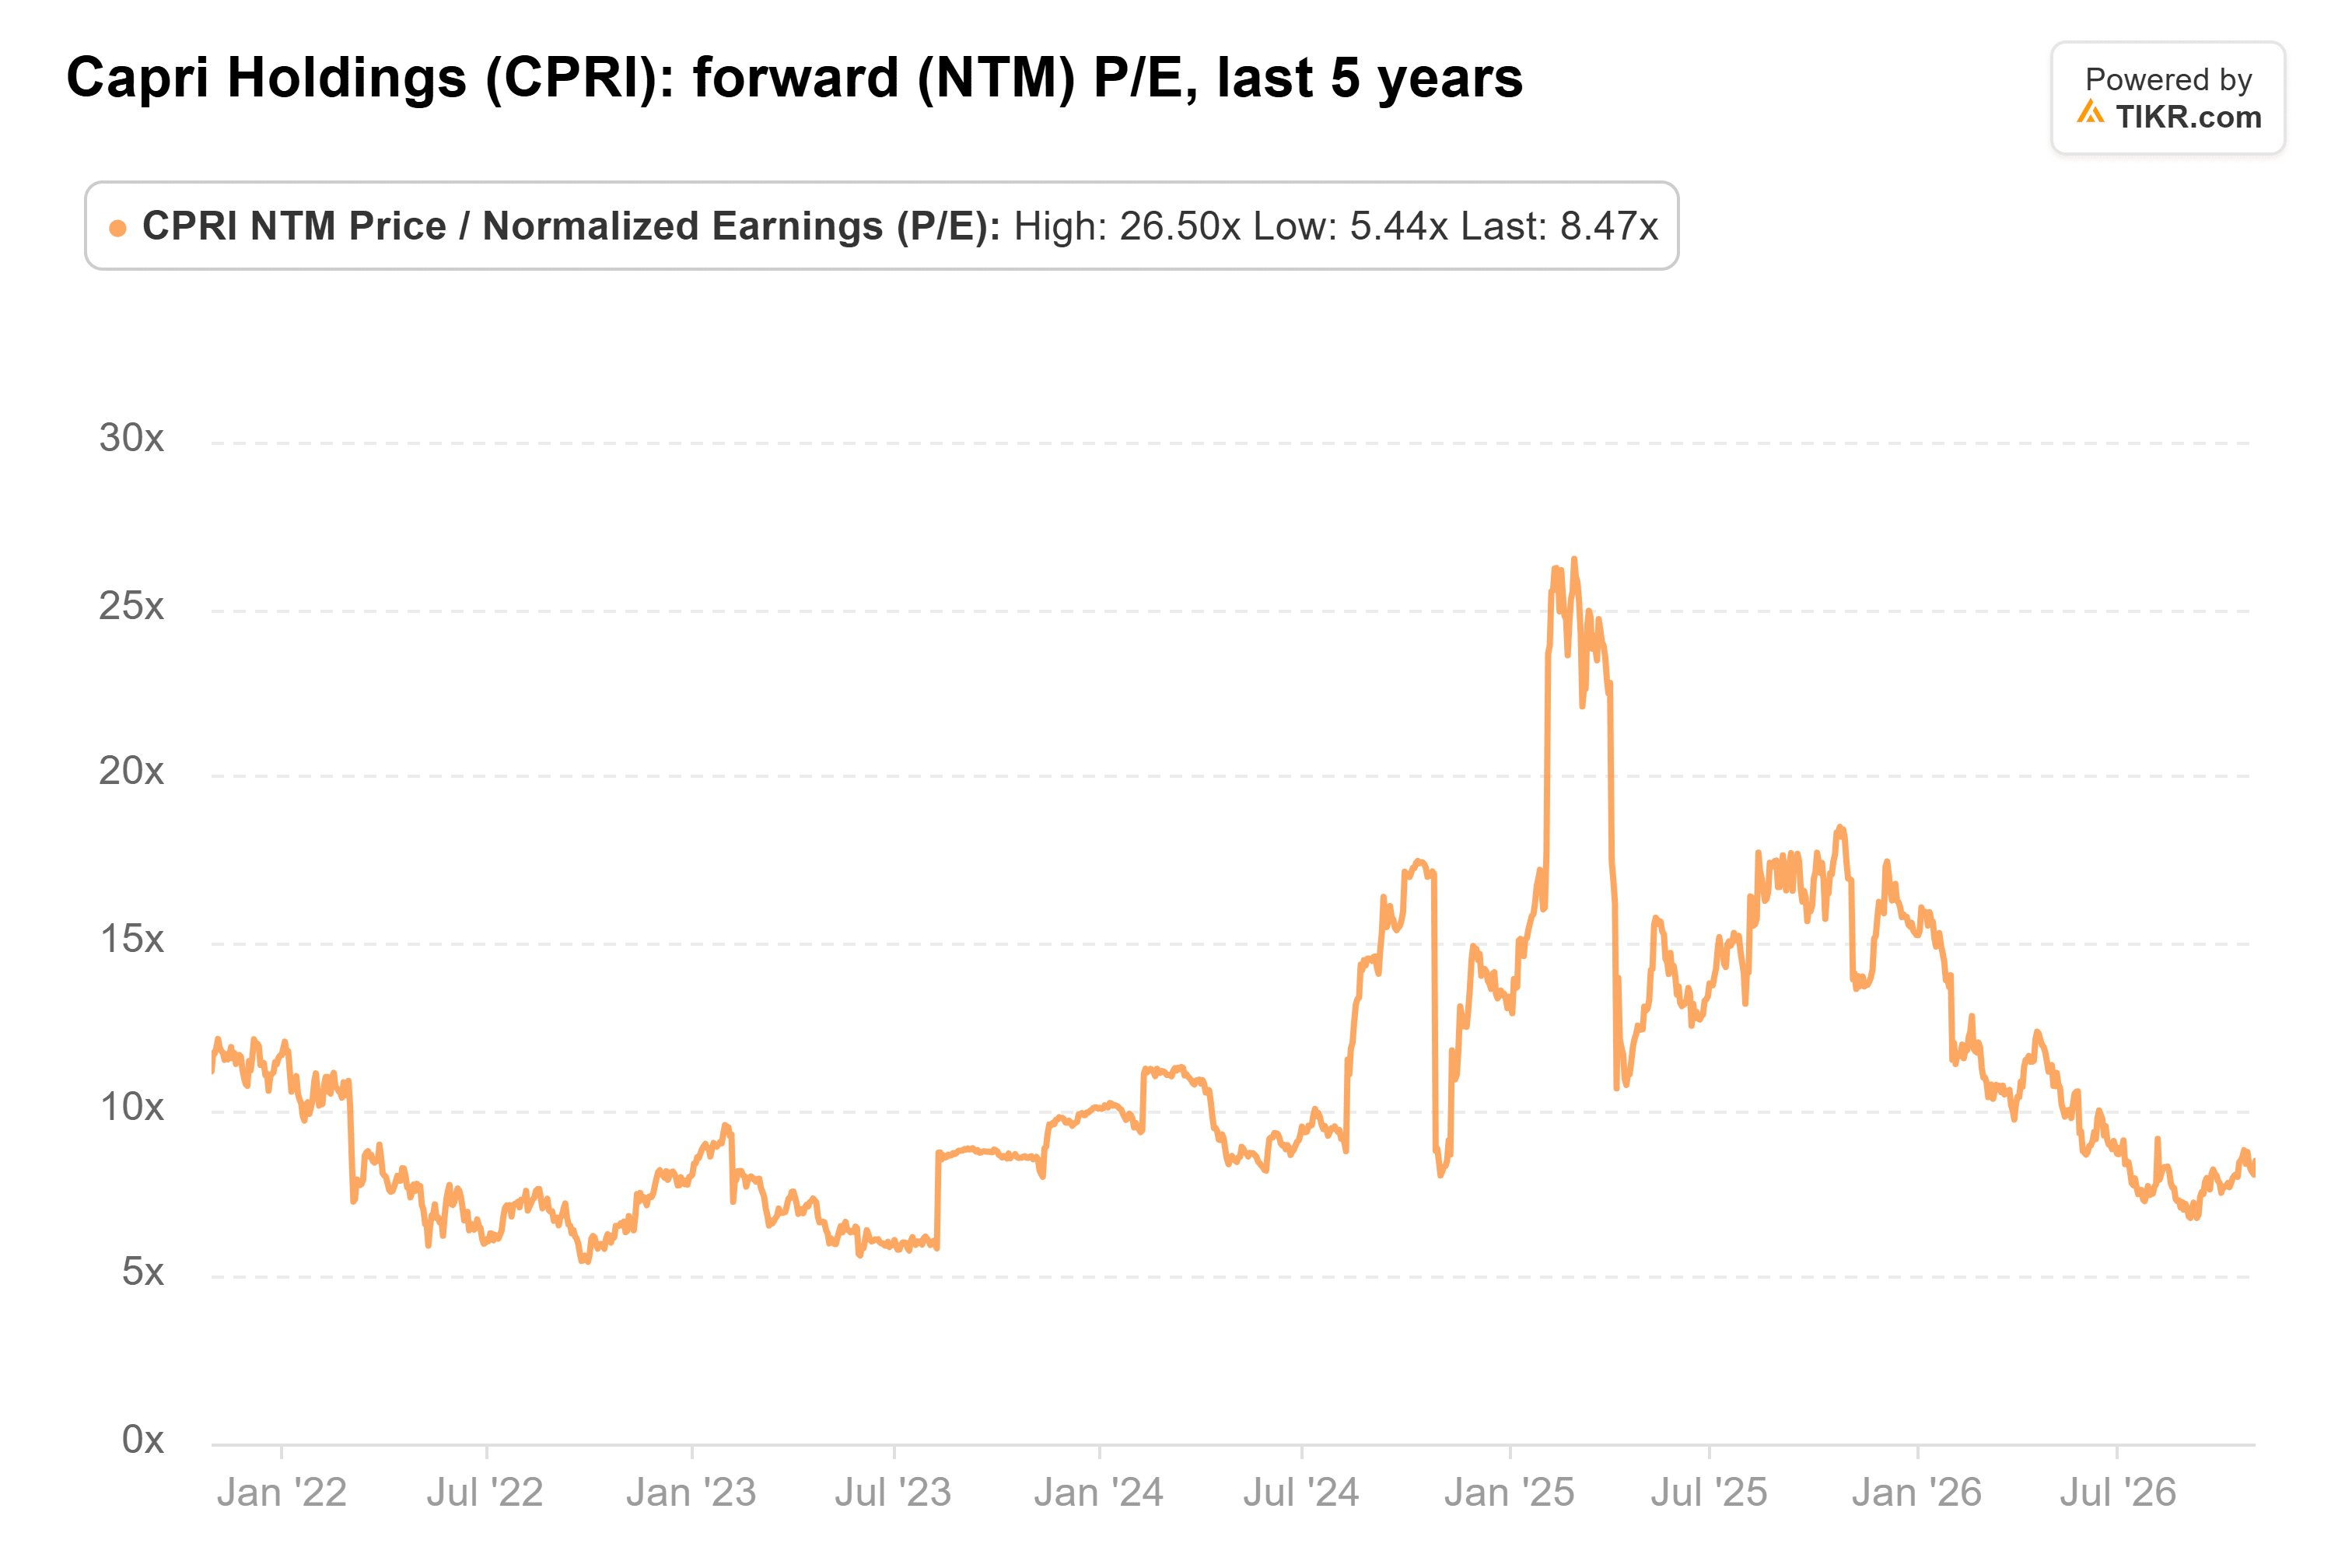
My take: At this multiple, Capri doesn’t need much growth. But Kors is still shrinking, so I’d wait for the March quarter.
So what is Capri stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Capri could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!