Key Stats for Lowe’s Stock
- Current Price: $196.82
- Target Price (Mid): ~$297
- Street Target: ~$252
- Potential Total Return: ~51%
- Annualized IRR: ~8% / year
Now Live: Discover how much upside your favorite stocks could have using TIKR’s new Valuation Model (It’s free) >>>
What Happened?
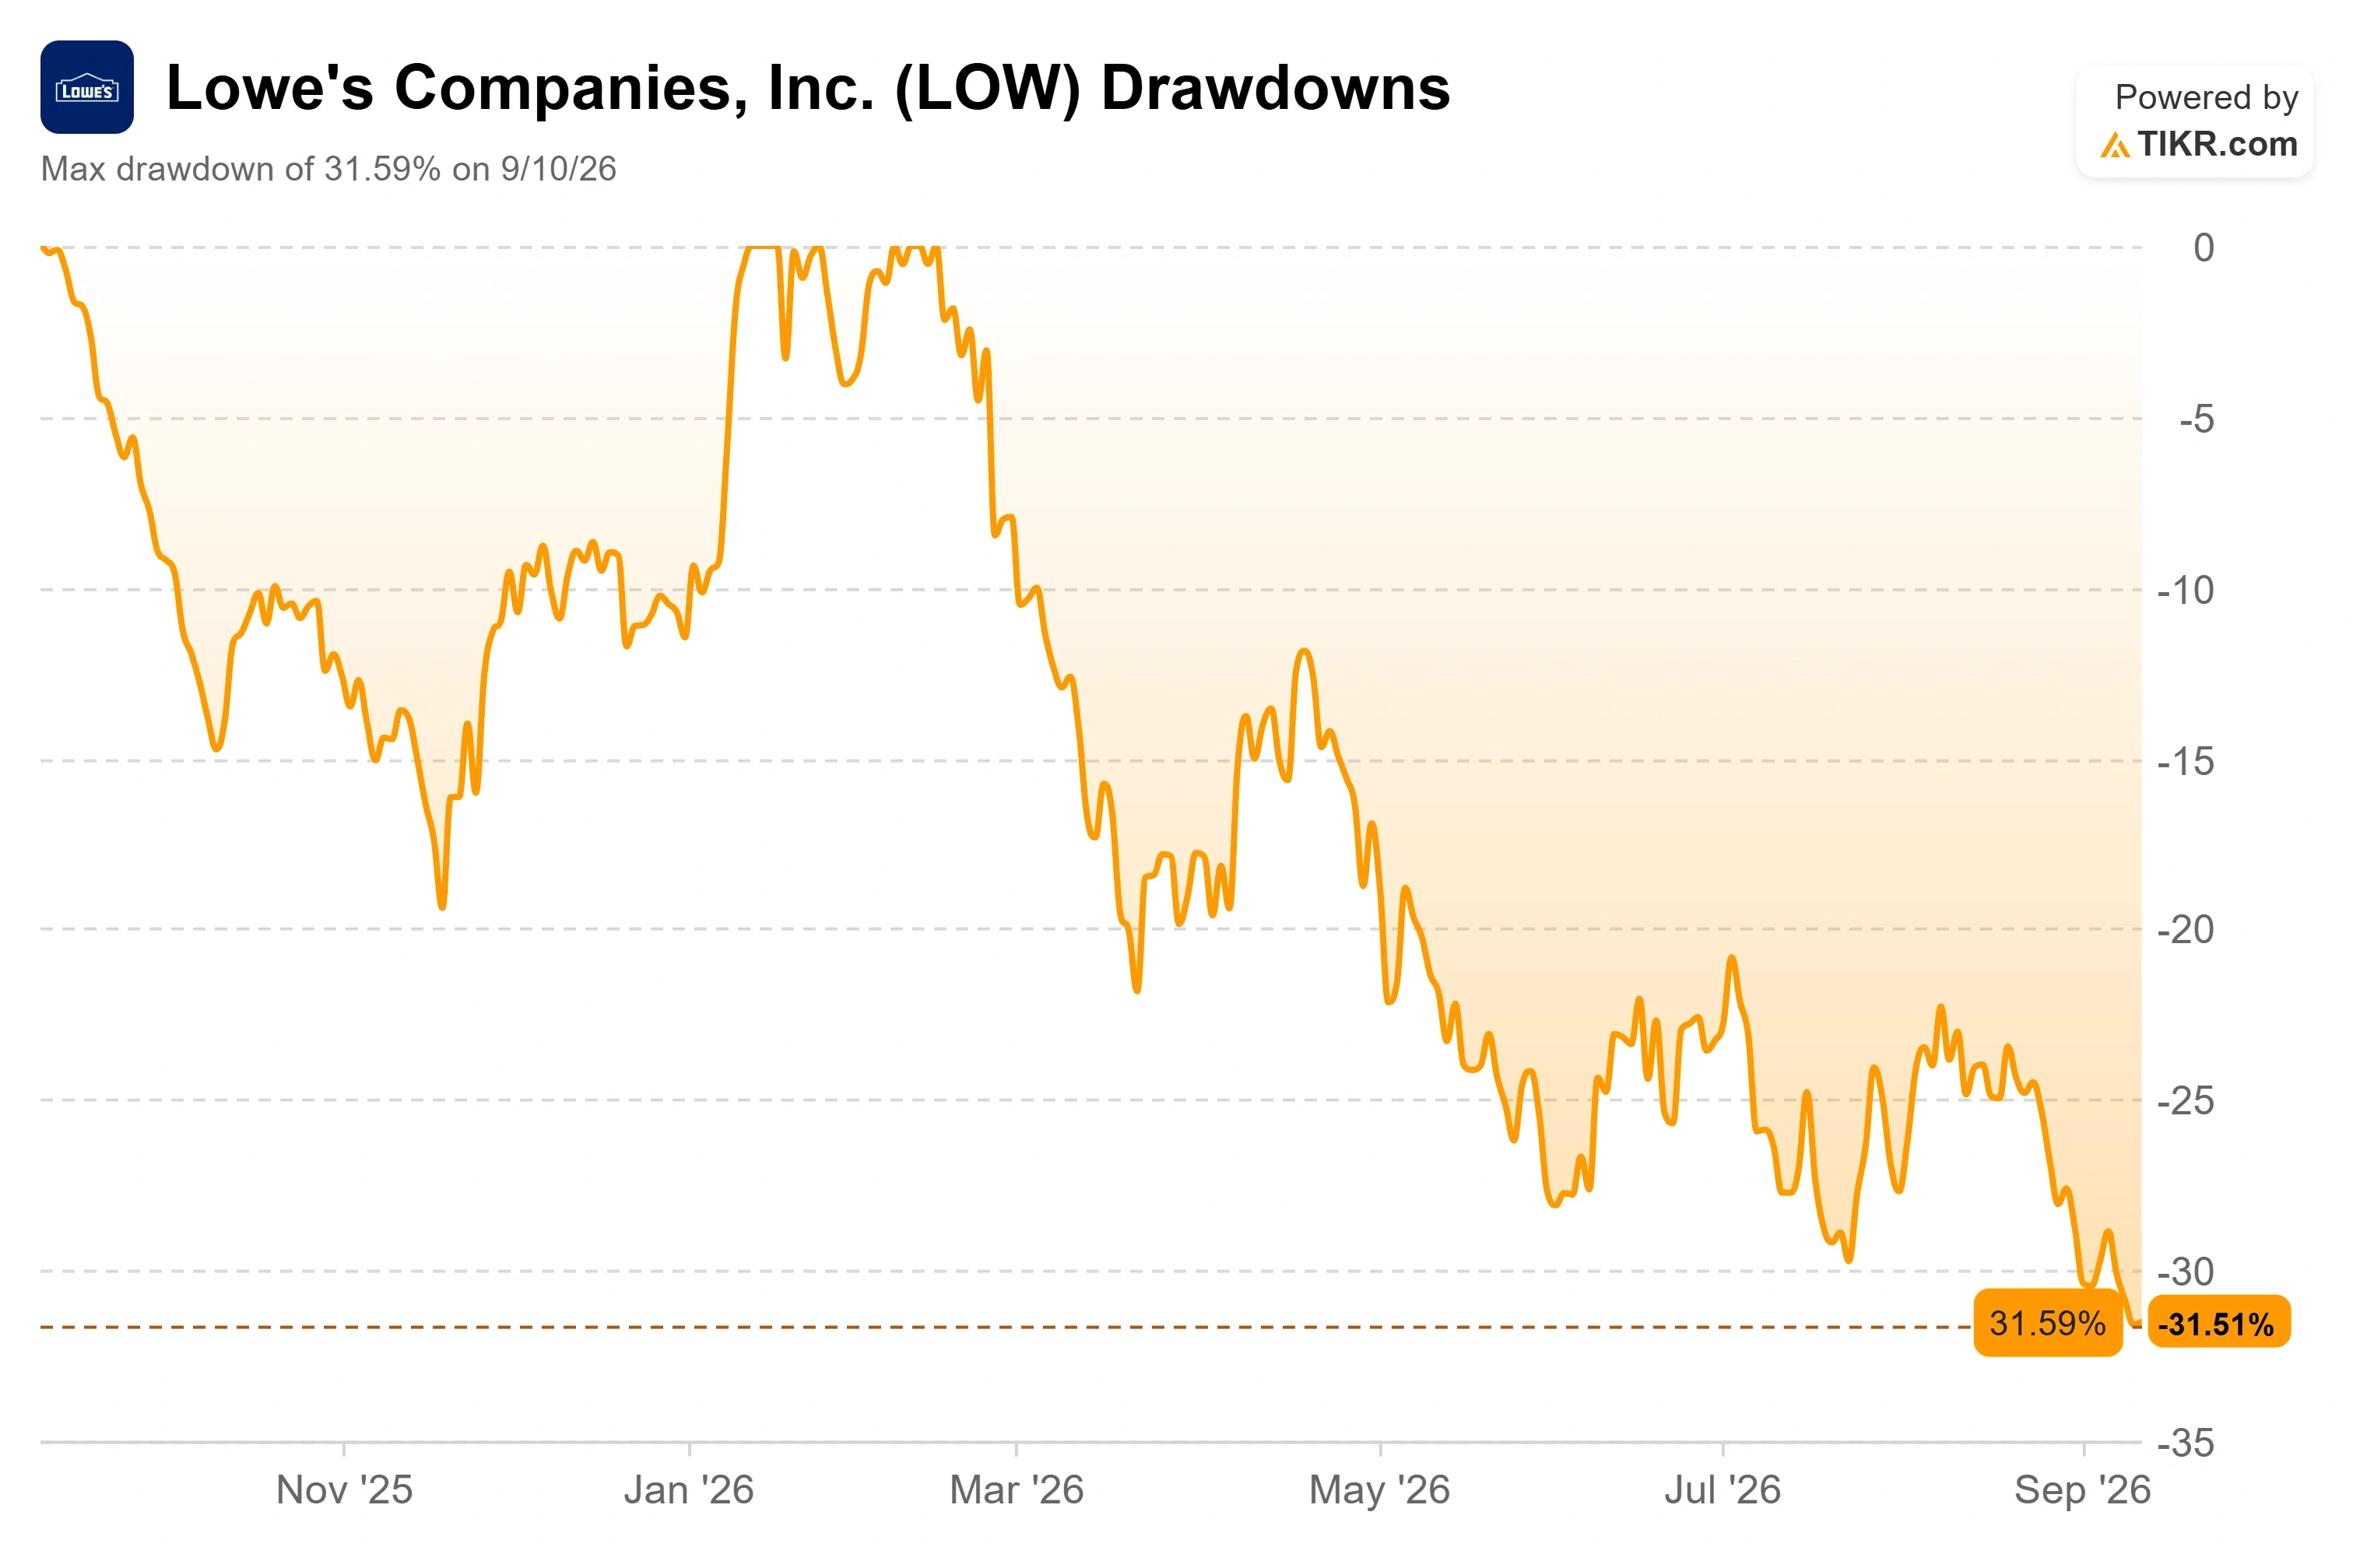
Lowe’s Companies (LOW) just delivered its fifth consecutive quarter of positive comparable sales, and the stock is sitting near a 52-week low of $195.06 anyway. Shares closed at $198.26 on September 14, down roughly 27% in price over the past year and more than 30% below the 52-week high of $293.06. The company keeps executing. The market keeps paying less for it.
Investors searching the ticker are not asking what went wrong at the company, because operationally little did. They are asking whether a home improvement leader trading at 15.8x forward earnings is a genuine bargain or a value trap chained to a housing cycle with no visible bottom.
A Fifth Straight Positive Quarter the Market Shrugged Off
Lowe’s reported second-quarter sales of $26 billion on August 19, with comparable sales up 0.2%. Adjusted diluted EPS came in at $4.40, ahead of the $4.22 the Street expected, helped by an $0.11 benefit from IEEPA tariff refunds. Free cash flow reached $3.1 billion for the quarter. The stock slipped 1.2% on the print and has since drifted to fresh lows.
Comparable sales ran down 0.4% in May, up 1.7% in June, then down 1.2% in July, and management was direct about why. Competitors used their own tariff refund dollars to cut prices on seasonal goods late in the quarter, and Lowe’s declined to chase them. CEO Marvin Ellison called the pressure “transitory” and tied it to a temporary cause: “We believe we had competitors plural that received tariff refunds and decided to take pricing action to either, a, drive units; and b, to clear out seasonal inventory.” That distinction matters. A company losing share to a structural rival is a different investment than one refusing to torch its margins over a quarter of grills and patio sets.
Underneath the promotional noise, the parts of the business Lowe’s has spent years building kept compounding. Online sales grew 15.7%, a second straight quarter above 15%, and the Mylow AI shopping assistant has now fielded more than 25 million questions, with online shoppers who use it converting at triple the rate of those who do not. On August 28, the company named five new executives effective September 1, moving Joe McFarland to Executive Vice President of Pro and Home Services and appointing Seemantini Godbole as its first Chief Information and AI Officer, a reshuffle of existing leaders pointed squarely at Pro, digital, and AI. The catch is the mix: DIY still makes up more than 60% of sales, and the DIY customer is the one waiting.
See historical and forward estimates for Lowe’s stock (It’s free!) >>>
A Cheap Multiple, If the Cycle Turns are Believed
Ellison cited John Burns Real Estate Consulting’s estimate of $20 billion to $50 billion in pent-up, deferred home improvement demand sitting on the sidelines. His case: the core customer is healthy but cautious, a middle-income homeowner with real disposable income, an aging house, and rising equity, waiting out elevated rates before starting the big remodel. The bet embedded in the ADG and Foundation Building Materials acquisitions is that the cycle turns and Lowe’s emerges better positioned than it went in. The risk is duration. “Softer for longer” new construction is squeezing both acquisitions now, and management guided the full year to the low end: roughly $92 billion in sales, flat comps, and adjusted EPS around $12.25.
Lowe’s trades at 15.8x forward earnings, well beneath TJX at 23.3x, Ross Stores at 27.1x, and Williams-Sonoma, the closest home-goods comparison, at 23.1x. Some of that gap is earned, since off-price names like TJX and Ross sell into demand that holds up better when the consumer softens, while Lowe’s revenue is tied to housing turnover. But a business that delivered a 25.5% return on invested capital in the quarter, backed by a dividend aristocrat’s balance sheet, rarely trades at that kind of discount unless the market has written off the next few years.

See how Lowe’s performs against its peers in TIKR (It’s free!) >>>
TIKR Advanced Model Analysis
- Current Price: $196.82
- Target Price (Mid): ~$297
- Potential Total Return: ~51%
- Annualized IRR: ~8% / year

See analysts’ growth forecasts and price targets for Lowe’s stock (It’s free!) >>>
Using the mid-case, the TIKR Valuation Model puts Lowe’s at roughly $297 by early 2031, a total return of about 51% over 4.4 years. The case does not require heroics. It leans on two revenue drivers: a gradual recovery in DIY demand as the aging U.S. housing stock pushes deferred repair and maintenance back onto the calendar, and continued Pro share gains through the FBM and ADG platforms. The margin driver is the company’s perpetual productivity improvement program, the internally funded efficiency work management credits for protecting flow-through even as fuel and transportation costs rose this year.
The mid-case assumes revenue compounding around 4% and net margins near 8%, both inside what Lowe’s has delivered before. Upside: if mortgage rates ease and the deferred remodel wave lands, the high-case target near $457 comes into view. Downside: if housing stays frozen into 2027, that ~4% revenue CAGR is where the model breaks first, and the discount to peers persists rather than closes.
Conclusion
The next real test is the third-quarter report on November 18. Management guided Q3 adjusted EPS to roughly 7% below the prior year, so a beat there is not the tell. The comp is. If Ellison is right that July’s price war was transitory, Q3 comps should hold near flat with no repeat of the seasonal margin bleed. If the discounting bled into fall, “transitory” gets harder to defend, and the stock’s refusal to bottom starts to look justified rather than stubborn. Watch the comp line and gross margin on November 18.
See what stocks billionaire investors are buying so you can follow the smart money with TIKR.
Should You Invest in Lowe’s?
The only way to really know is to look at the numbers yourself. TIKR gives you free access to the same institutional-quality financial data that professional analysts use to answer exactly that question.
Pull up Lowe’s, and you’ll see years of historical financials, what Wall Street analysts expect for revenue and earnings in the quarters ahead, how valuation multiples have moved over time, and whether price targets are trending up or down.
You can build a free watchlist to track Lowe’s alongside every other stock on your radar. No credit card required. Just the data you need to decide for yourself.
Looking for New Opportunities?
- See what stocks billionaire investors are buying so you can follow the smart money.
- Analyze stocks in as little as 5 minutes with TIKR’s all-in-one, easy-to-use platform.
- The more rocks you overturn… the more opportunities you’ll uncover. Search 100K+ global stocks, global top investor holdings, and more with TIKR.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!