Key Takeaways
- Google Cloud revenue grew 82% to $24.8 billion in the second quarter, against 42% growth for Microsoft’s Azure and 37% for Amazon Web Services.
- At those growth rates, Google Cloud would pass Azure in quarterly revenue within about a year, and Alphabet’s valuation doesn’t reflect that.
- The main risk is cost: Alphabet’s capital spending doubled to $44.9 billion last quarter, and its free cash flow turned negative.
- Alphabet and Microsoft both report on Oct. 28, and Google Cloud’s margin is the number to watch.
Alphabet (GOOG) grew Google Cloud’s revenue 82% last quarter, to $24.8 billion.
Over the same three months, Azure at Microsoft (MSFT) grew 42% to $29.4 billion, and Amazon Web Services at Amazon (AMZN) grew 37% to $42.2 billion.
Ranjan Roy went through those exact numbers on the latest episode of the Big Technology Podcast and said Google Cloud has “a meaningful shot” at passing Azure. Then he added: “I don’t think people are recognizing this.”
I think he’s right on both counts.
The gap is closing fast
Run both businesses forward a year at last quarter’s growth rates. Google Cloud’s quarterly revenue would reach about $45 billion, and Azure’s about $42 billion.
Azure isn’t standing still, of course. Microsoft has guided for 44% to 45% growth in constant currency in the September quarter. Even at that pace, Google Cloud would edge past it within a year if it stays anywhere near 82%. (Catching Amazon’s AWS, at $42.2 billion a quarter, is a much longer climb.)
TIKR tracks 57 analysts on Microsoft. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Microsoft, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Microsoft’s Analyst Ratings
Cloud is already pulling its weight
Google Cloud’s operating margin rose to 35.6% in the second quarter, from 20.7% a year earlier. Compared with a year earlier, Cloud added $6.0 billion of operating income. Google Services, with Search and YouTube behind it, added $6.5 billion.
Yet Wall Street has Alphabet’s revenue growing at about today’s pace through 2027, then slowing.
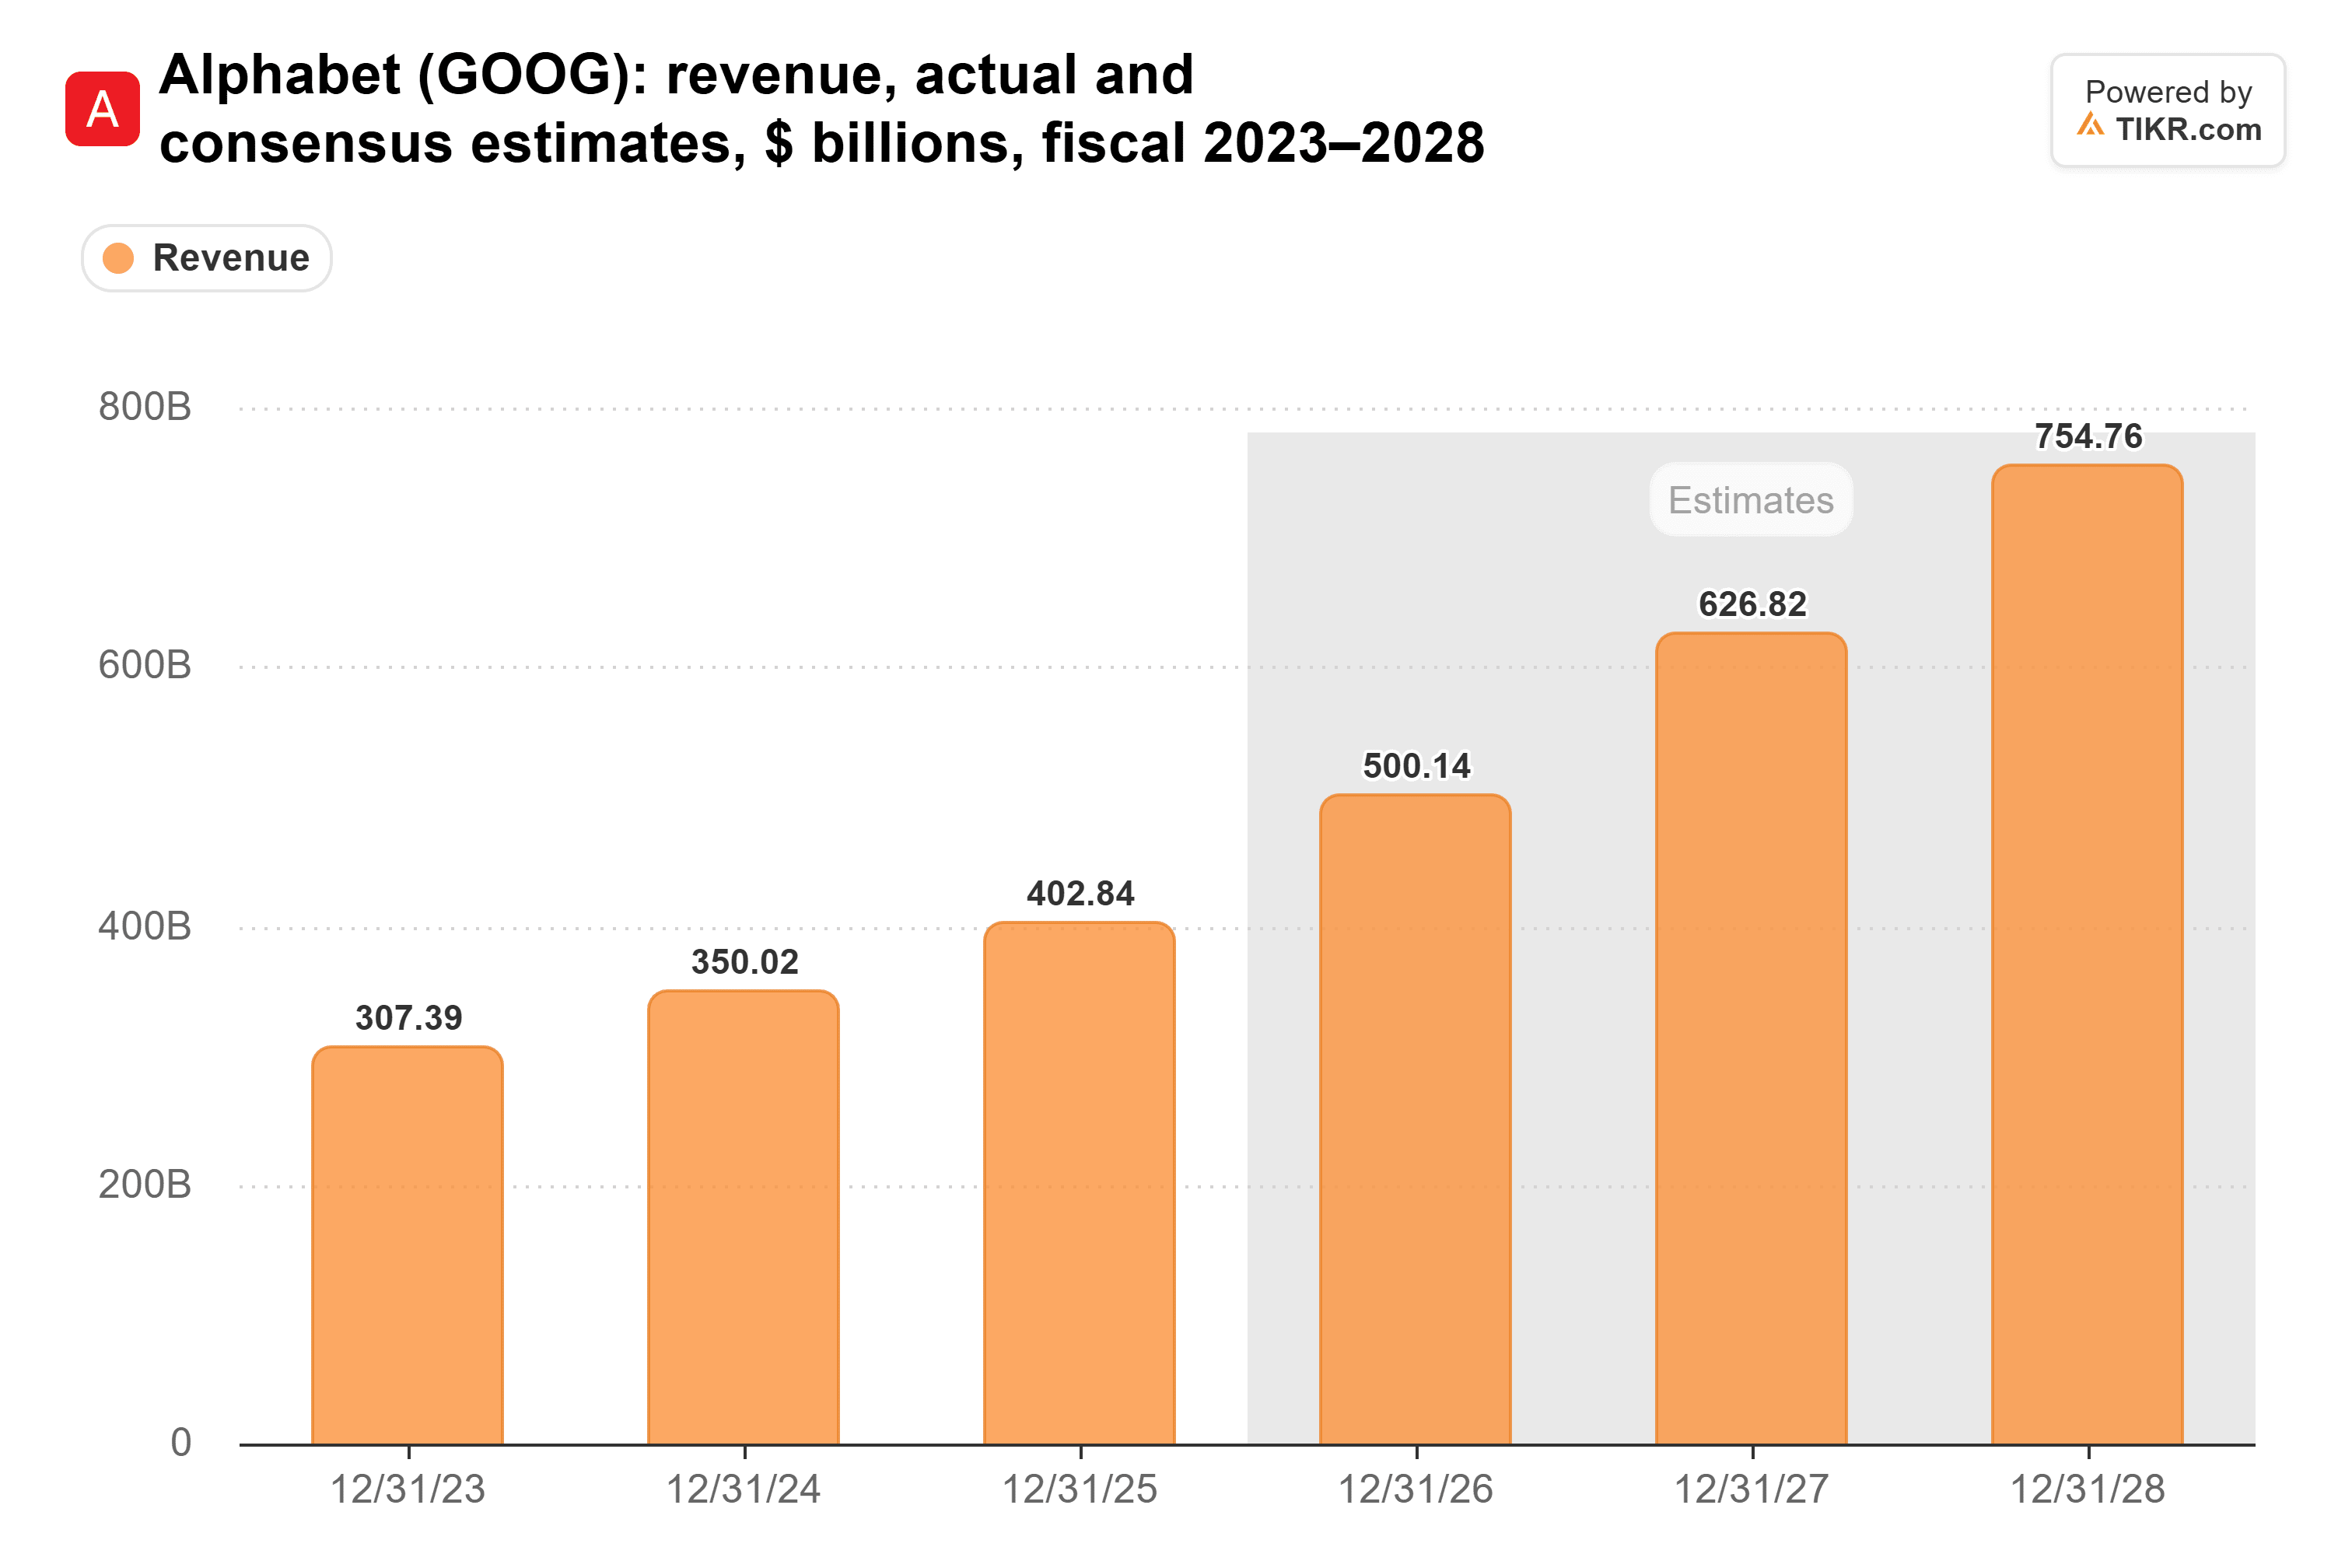
Consensus calls for $500 billion of revenue in 2026 and $627 billion in 2027, up 24% and 25%. Then growth slows to 20% in 2028, for $755 billion. If Google Cloud keeps taking share from Azure, that slowdown looks too cautious to me.
And the market is paying a very ordinary multiple for all this.
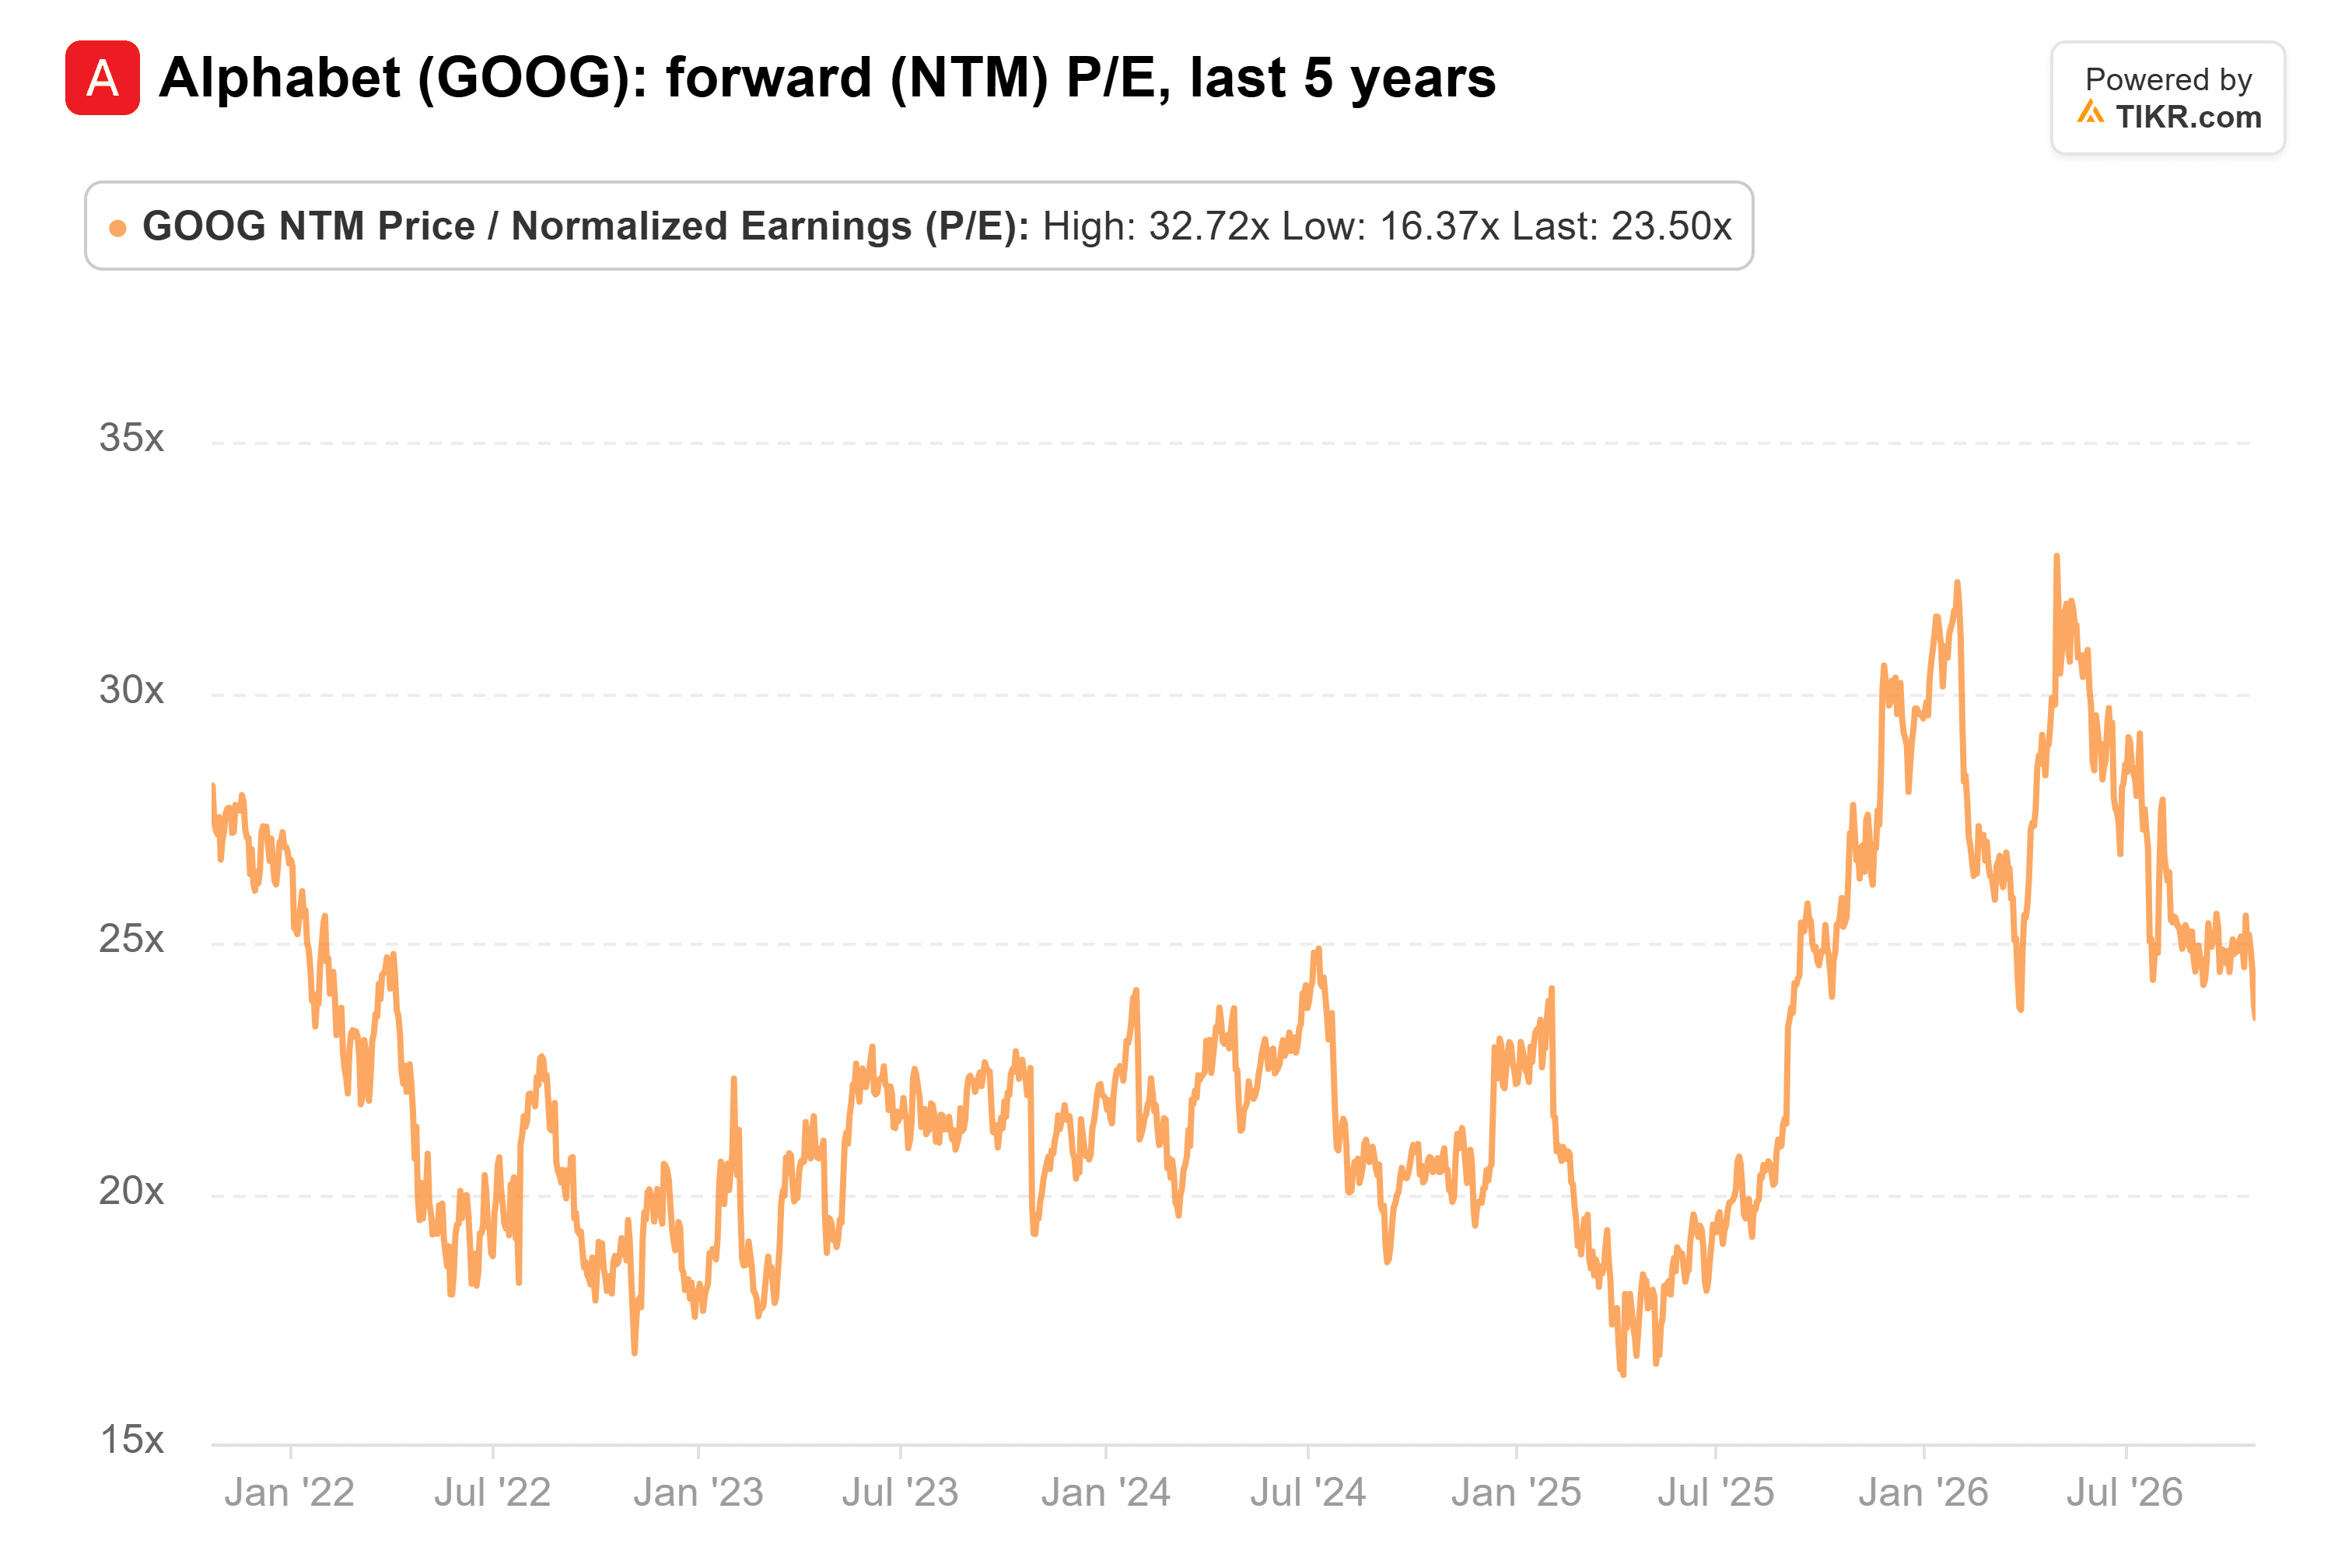
At about 24x forward earnings, Alphabet trades right around its five-year average of 23x. That’s well below the 33x it hit at the end of April.
Somebody has to pay for the chips
The likely reason is the bill. Alphabet’s capital spending nearly quadrupled from $24.6 billion in 2021 to $91.5 billion in 2025. Over the same years, operating cash flow went from $91.7 billion to $165 billion.
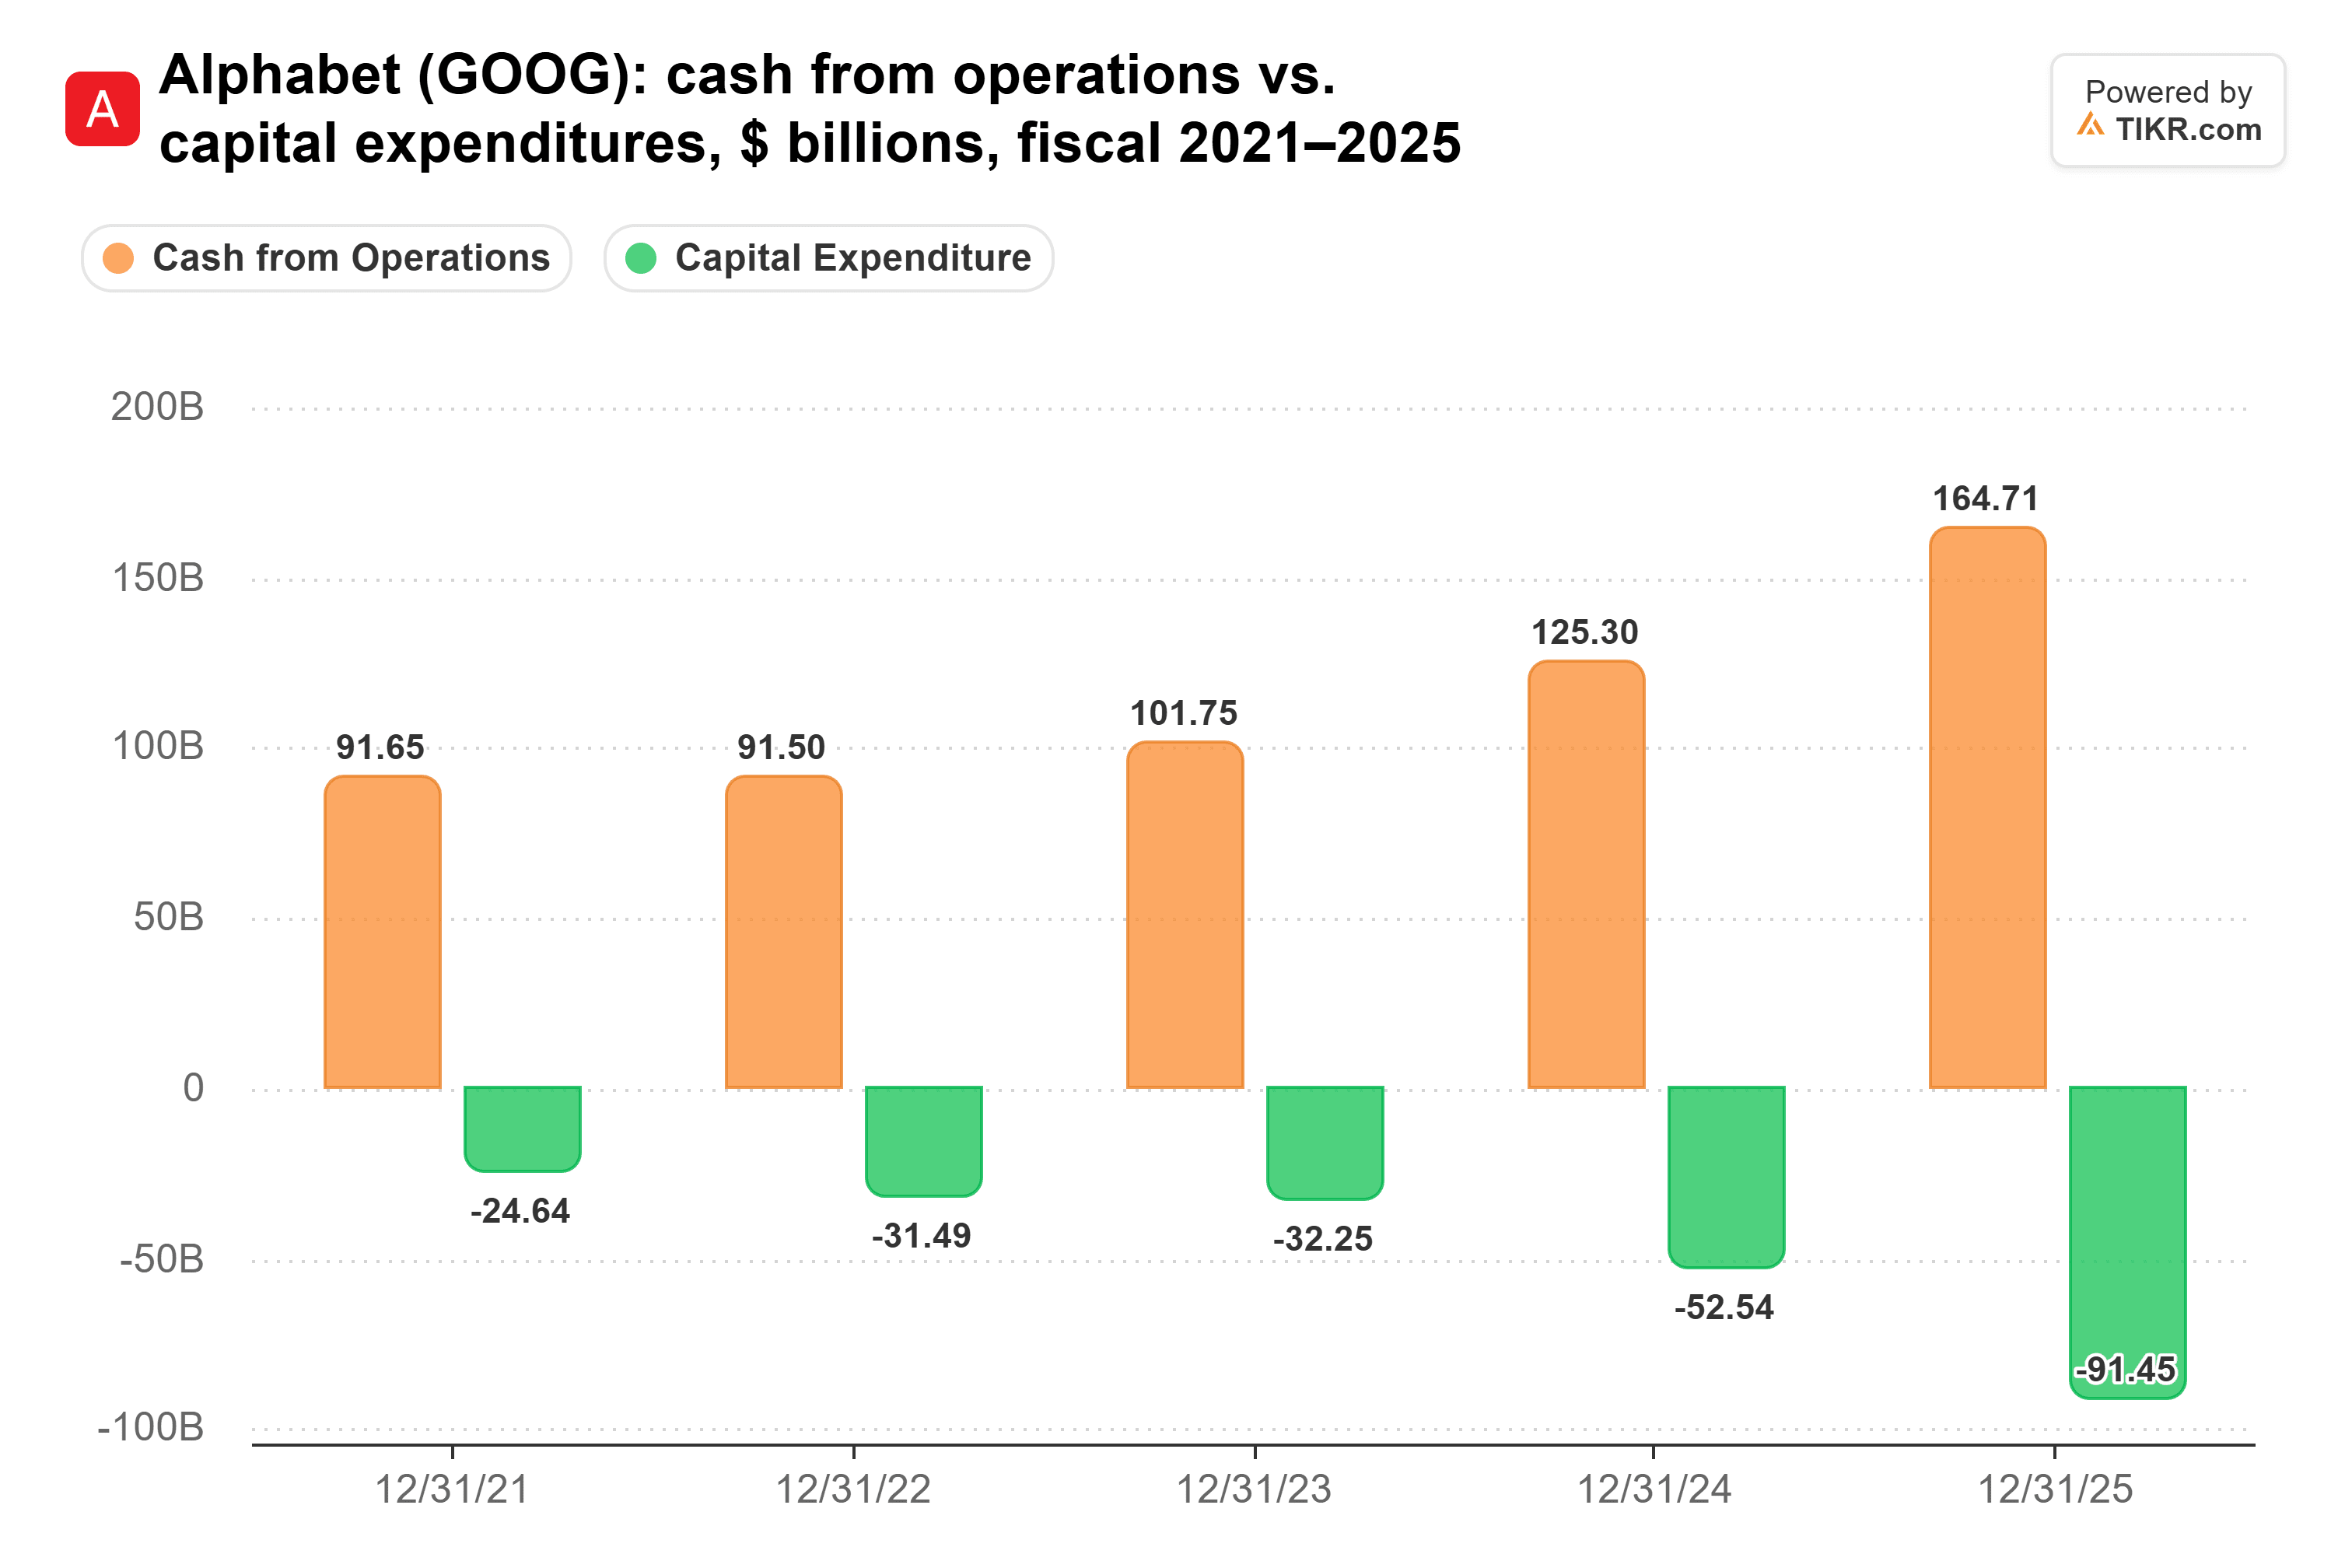
It’s gone further since. Capex doubled to $44.9 billion in the second quarter, free cash flow came in at negative $5.9 billion, and management raised its 2026 capex guidance to $195 billion to $205 billion. Alphabet has stopped buying back stock and doubled its long-term debt in six months, and shares fell 7% after the report.
But the spending is chasing demand that’s already signed. Google Cloud’s backlog reached $513.9 billion at the end of June. Management expects just over half of Alphabet’s backlog to turn into revenue within two years.
And everyone is short of capacity. Google Cloud grew 82% while Alphabet was giving up cloud revenue to feed its own AI research. As the show’s host, Alex Kantrowitz, put it, that growth came “with a lot of the compute capacity going to AI research.” He said Sundar Pichai told him “everybody is short compute.”
When supply is that tight, the cloud that builds the most capacity takes the share. Alphabet is paying up to be that cloud.
The first test lands Oct. 28
My take: Google Cloud has a real shot at passing Azure in the next couple of years. At 24x forward earnings, investors are paying for the Alphabet of the past five years and giving Cloud almost no credit.
Alphabet reports after the close on Oct. 28, the same day as Microsoft, so the two growth rates will come out side by side. The number I’d watch is Google Cloud’s margin. This is its first quarter with rented outside capacity in it, and management has said that will weigh on margins in the near term. If the margin holds near 35.6% and growth stays close to 82%, the capex gets a lot easier to defend.
Of course, one quarter won’t settle a race this big, and 82% growth won’t last forever.
So what is Alphabet stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Alphabet could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!