Key Takeaways
- Banks plan to sell as much as about $21 billion of bonds for the $63 billion package Broadcom put together to finance Anthropic’s chips, Bloomberg reported.
- Former SEC Chair Gary Gensler compared the package to the off-balance-sheet deals of 2008 and raised concerns about guarantees written by Broadcom, NVIDIA and AMD.
- Broadcom backs the package’s $42 billion of senior debt against a fall in the chips’ value, and its two Anthropic deals are far bigger than NVIDIA’s or AMD’s backstops.
- At 20x forward earnings, near its three-year low, Broadcom stock already prices in some of that risk.
Broadcom (AVGO) just put together $63 billion so Anthropic can buy its chips. Now Wall Street has to sell the debt.
Banks plan to sell as much as about $21 billion of high-grade bonds as soon as early next year as part of the package, Bloomberg reported on Tuesday.
Former SEC Chair Gary Gensler, now an MIT professor, noted on Bloomberg Talks that the package isn’t even in Anthropic’s IPO filing yet. He called it “$63 billion of complex guarantees and so forth, all off balance sheet.”
Then: “That’s feeling a little like that 08 off-balance sheet craze.”
Strong words from the man who used to run the SEC.
Broadcom is backing the debt
The money goes to a special purpose company that buys the chips and leases them to Anthropic. Anthropic’s lease payments then pay off the debt. Banks are lending about $42 billion of it, senior secured, and Blackstone is anchoring the rest.
Broadcom provides residual value support on that $42 billion, a backstop against the chips losing value.
The new package alone is nearly as big as all the debt on Broadcom’s own balance sheet…
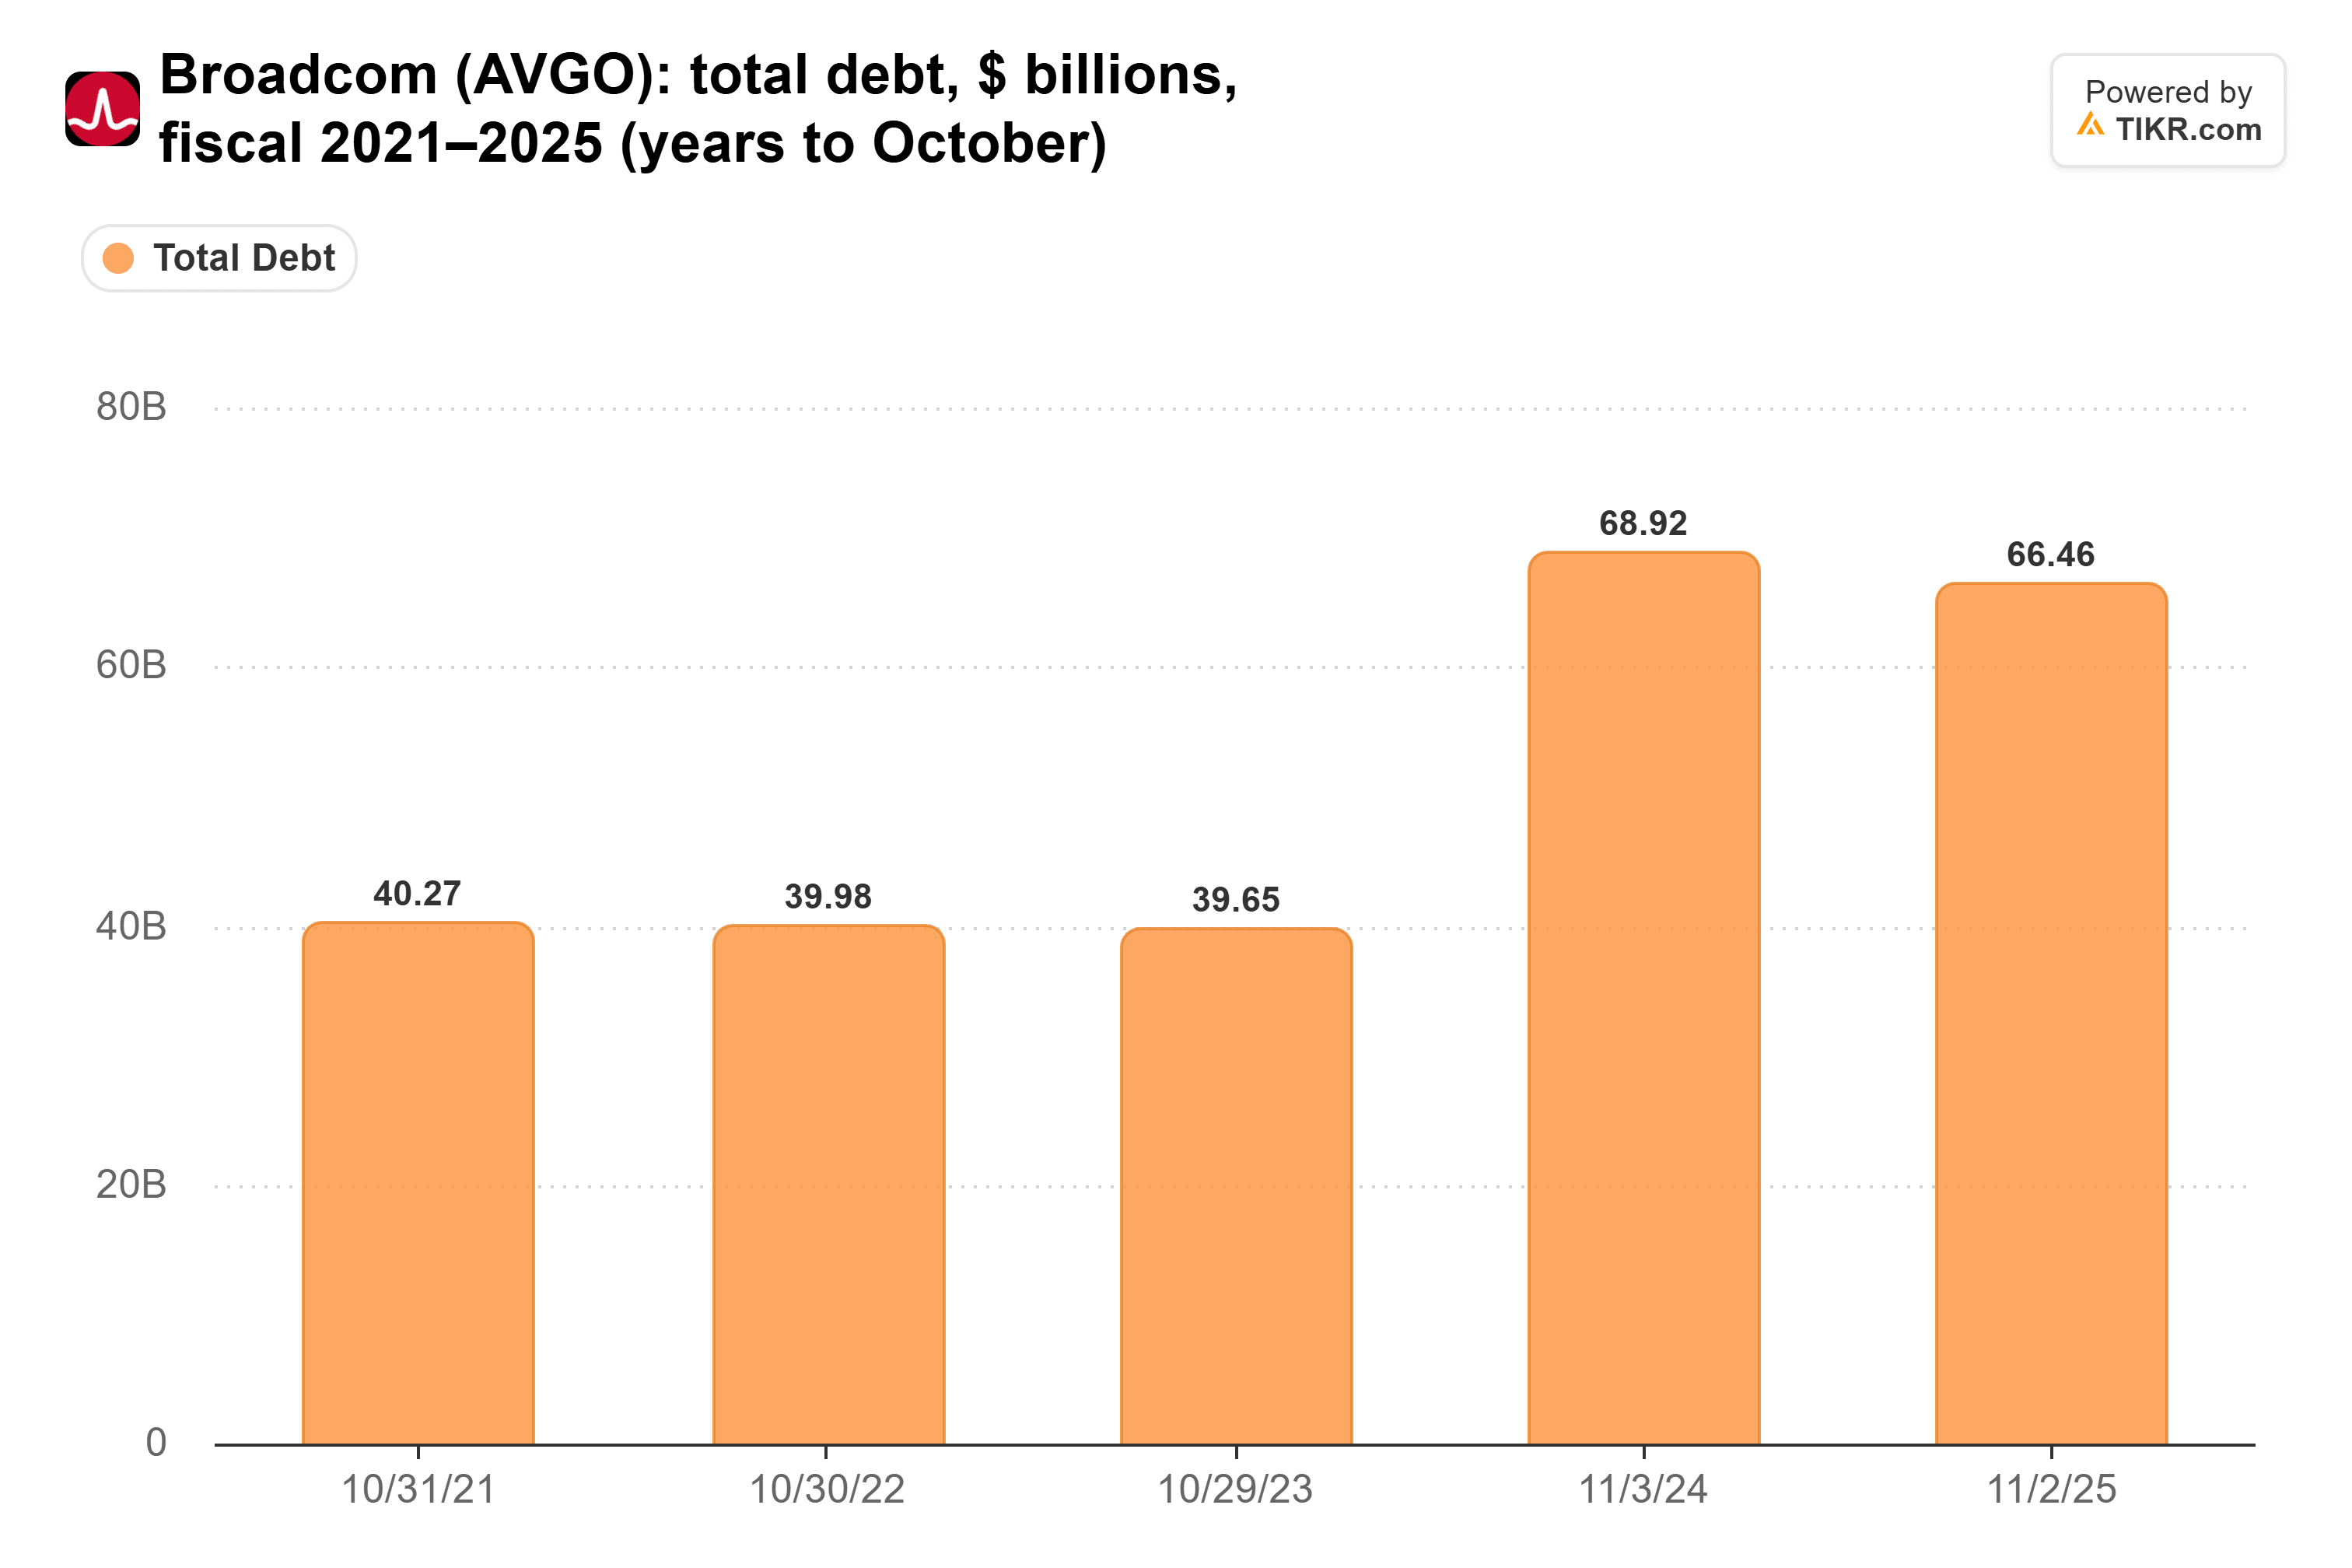
…and none of it shows up there. Neither does the backstop of up to about $29 billion of leases that Broadcom gave on its first package, a $35 billion deal led by Apollo in June.
TIKR tracks 52 analysts on Broadcom. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Broadcom, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Broadcom’s Analyst Ratings
The chips are the catch
Residual value support costs Broadcom when the chips are worth less than what’s owed. Gensler gives AI chips four to seven years of useful life, and adds that “the chips of 2026 won’t be that valuable in 2032.”
Of course, the bonds will probably mature in around five years, with principal paid down along the way, so the debt shrinks as the chips age. And the backstop only kicks in if Anthropic stops paying. Its run-rate revenue passed $30 billion in April, [Reuters](LINK NEEDED) reported, but its IPO filing on Monday also showed steep losses.
The bigger issue for me is that Anthropic is both Broadcom’s growth story and its credit risk. Management expects Anthropic to be its largest custom-chip customer in 2027. If Anthropic stumbles, Broadcom loses its fastest-growing sales and faces its backstops in the same year.
Broadcom can afford a lot. Its free cash flow hit $26.9 billion in fiscal 2025…
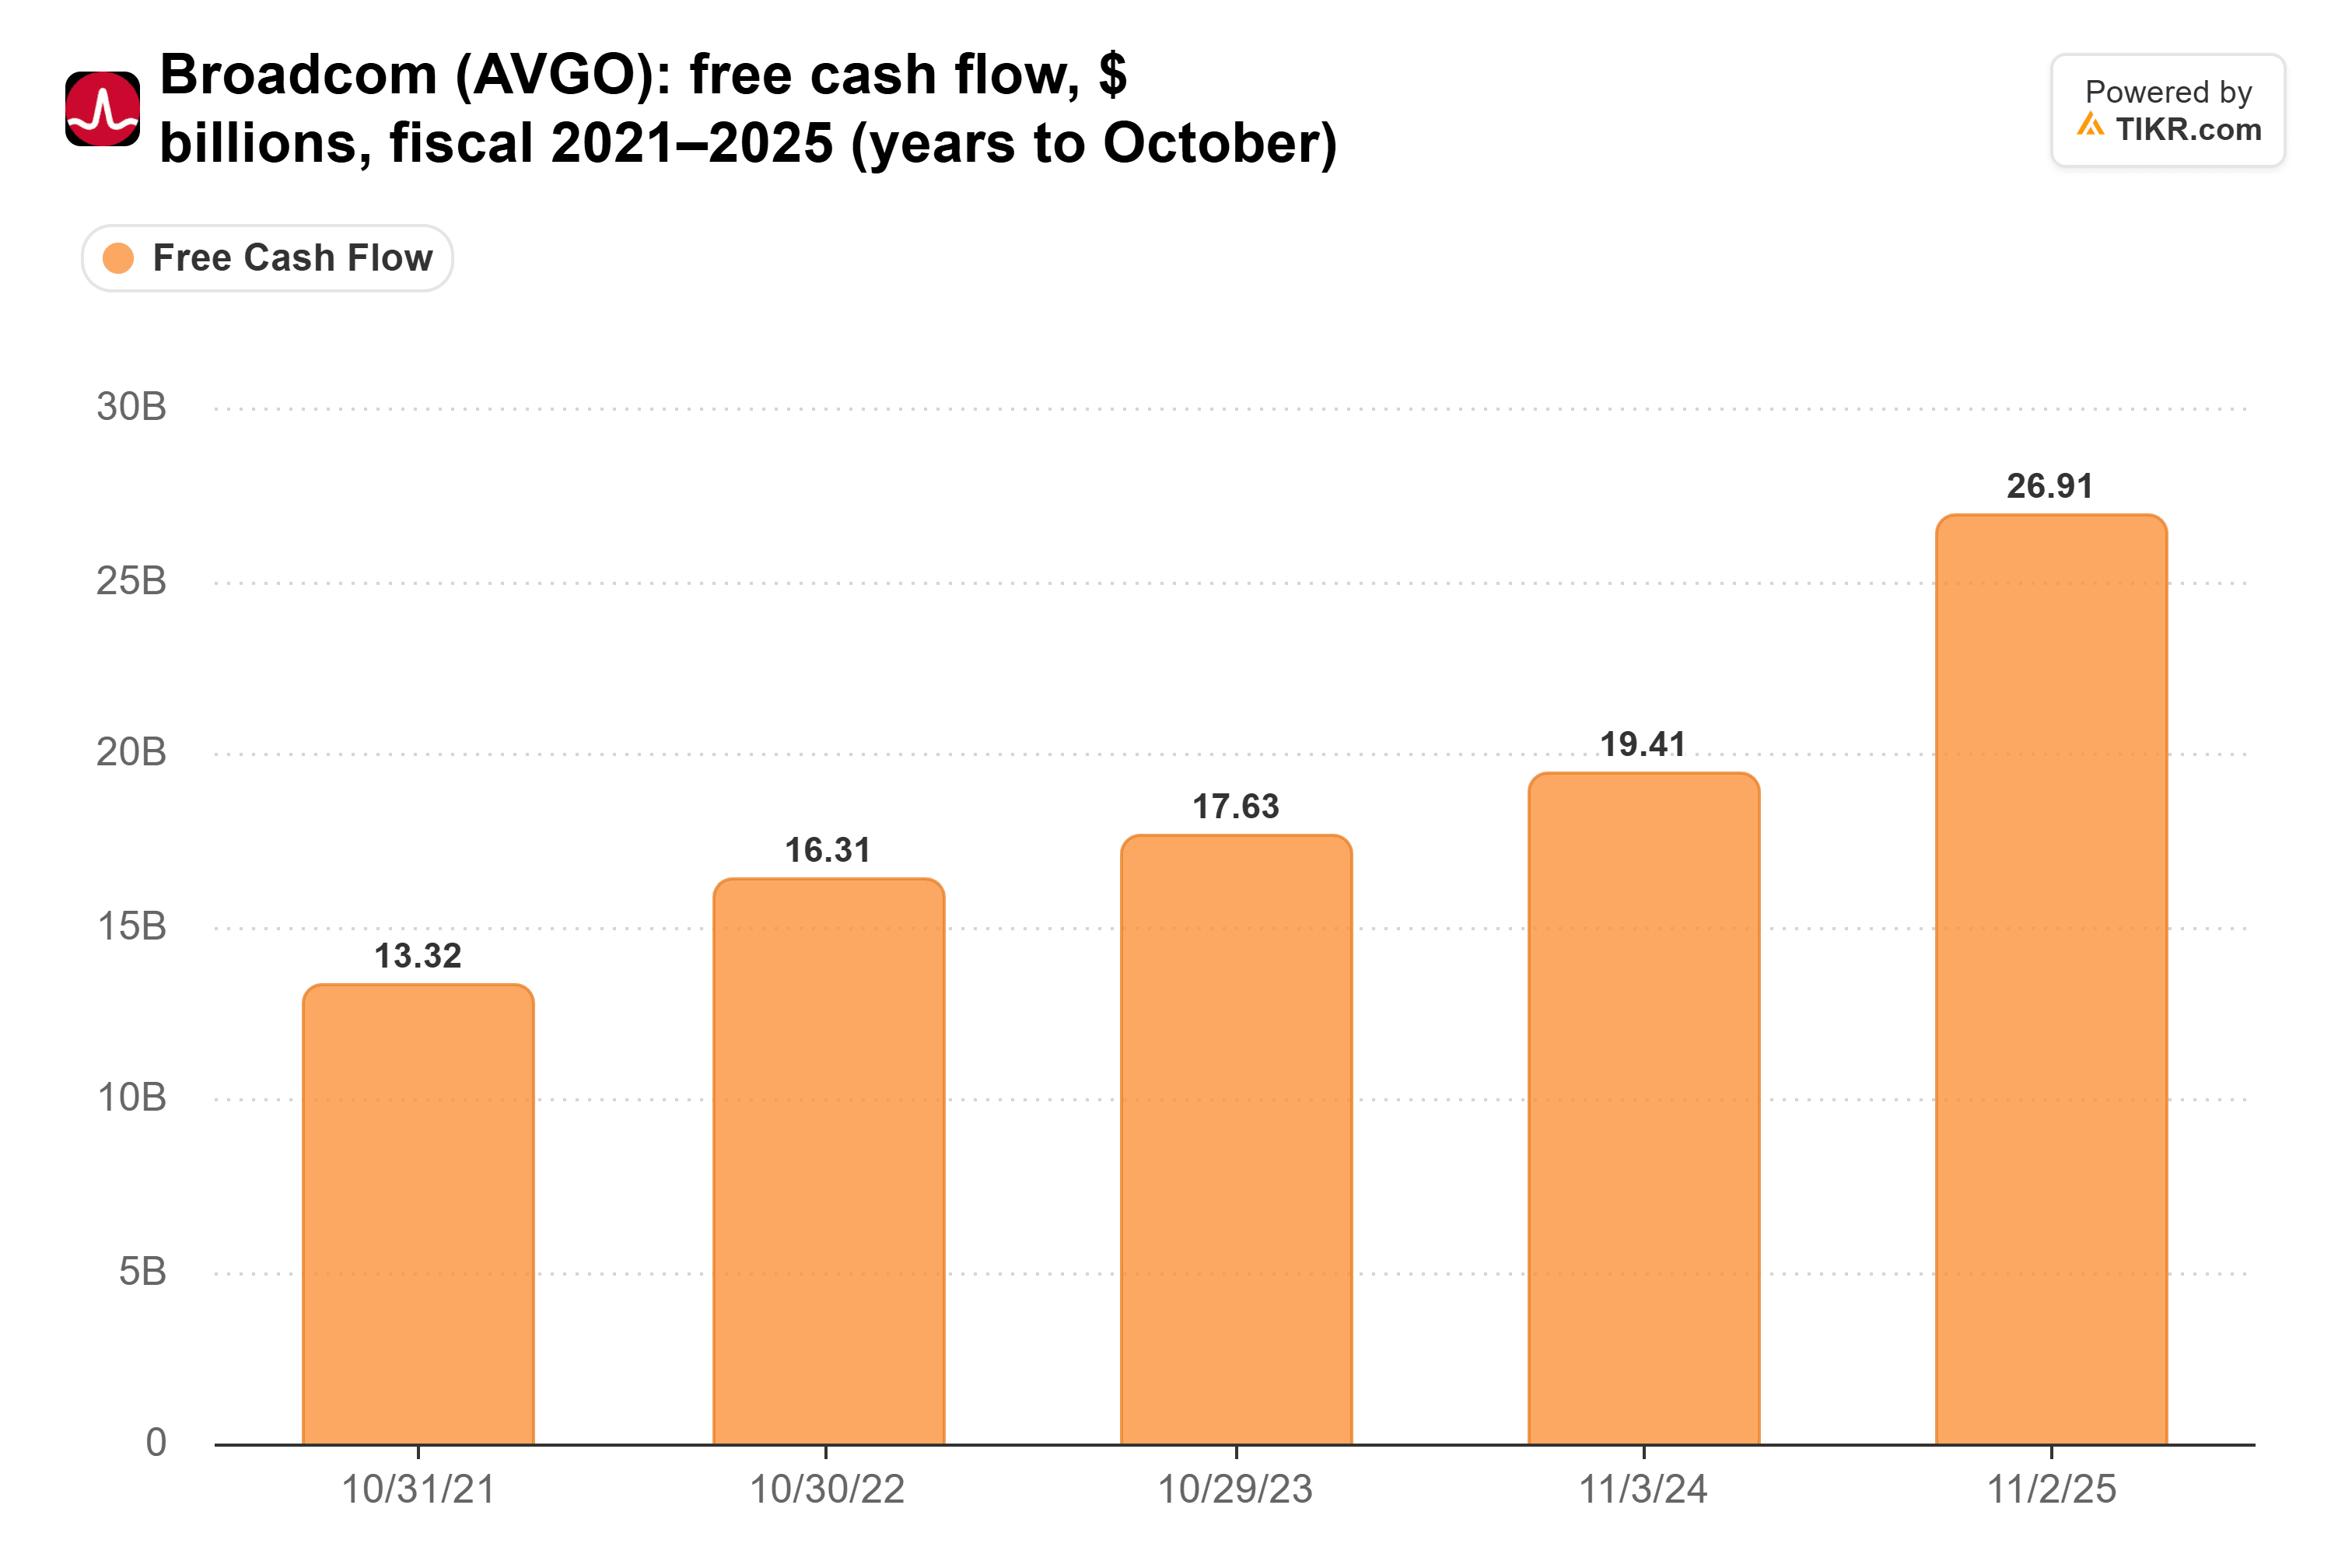
…and it’s running even higher this year, at $31.9 billion through the first nine months of fiscal 2026. Still, the $42 billion Broadcom is backing on this deal is more than a year and a half of fiscal 2025’s free cash flow. (Broadcom would only owe the gap between the debt and what the chips sell for, but the size of that gap is exactly what Gensler is worried about.)
Broadcom’s backstops dwarf its rivals’
Gensler isn’t singling out Broadcom. He worries about “all these guarantees that Broadcom, NVIDIA, AMD have written back into these data centers and it’s off balance sheet.”
NVIDIA (NVDA) agreed in September 2025 to buy CoreWeave’s unsold cloud capacity through April 2032, a commitment first valued at $6.3 billion, CoreWeave disclosed in a filing. AMD (AMD) is effectively guaranteeing a $300 million loan so Crusoe can buy its chips, The Information reported earlier this year.
Broadcom’s two Anthropic deals are many times the size of either. Moody’s still counts Broadcom among the strongest large tech companies, but said its risk would rise if many deals like this pile up in a short time. Two in about four months is a start.
Investors are already nervous
The market isn’t ignoring this. Broadcom trades at 20x forward earnings, well below its three-year average of 30x and just above the three-year low it hit last Friday.
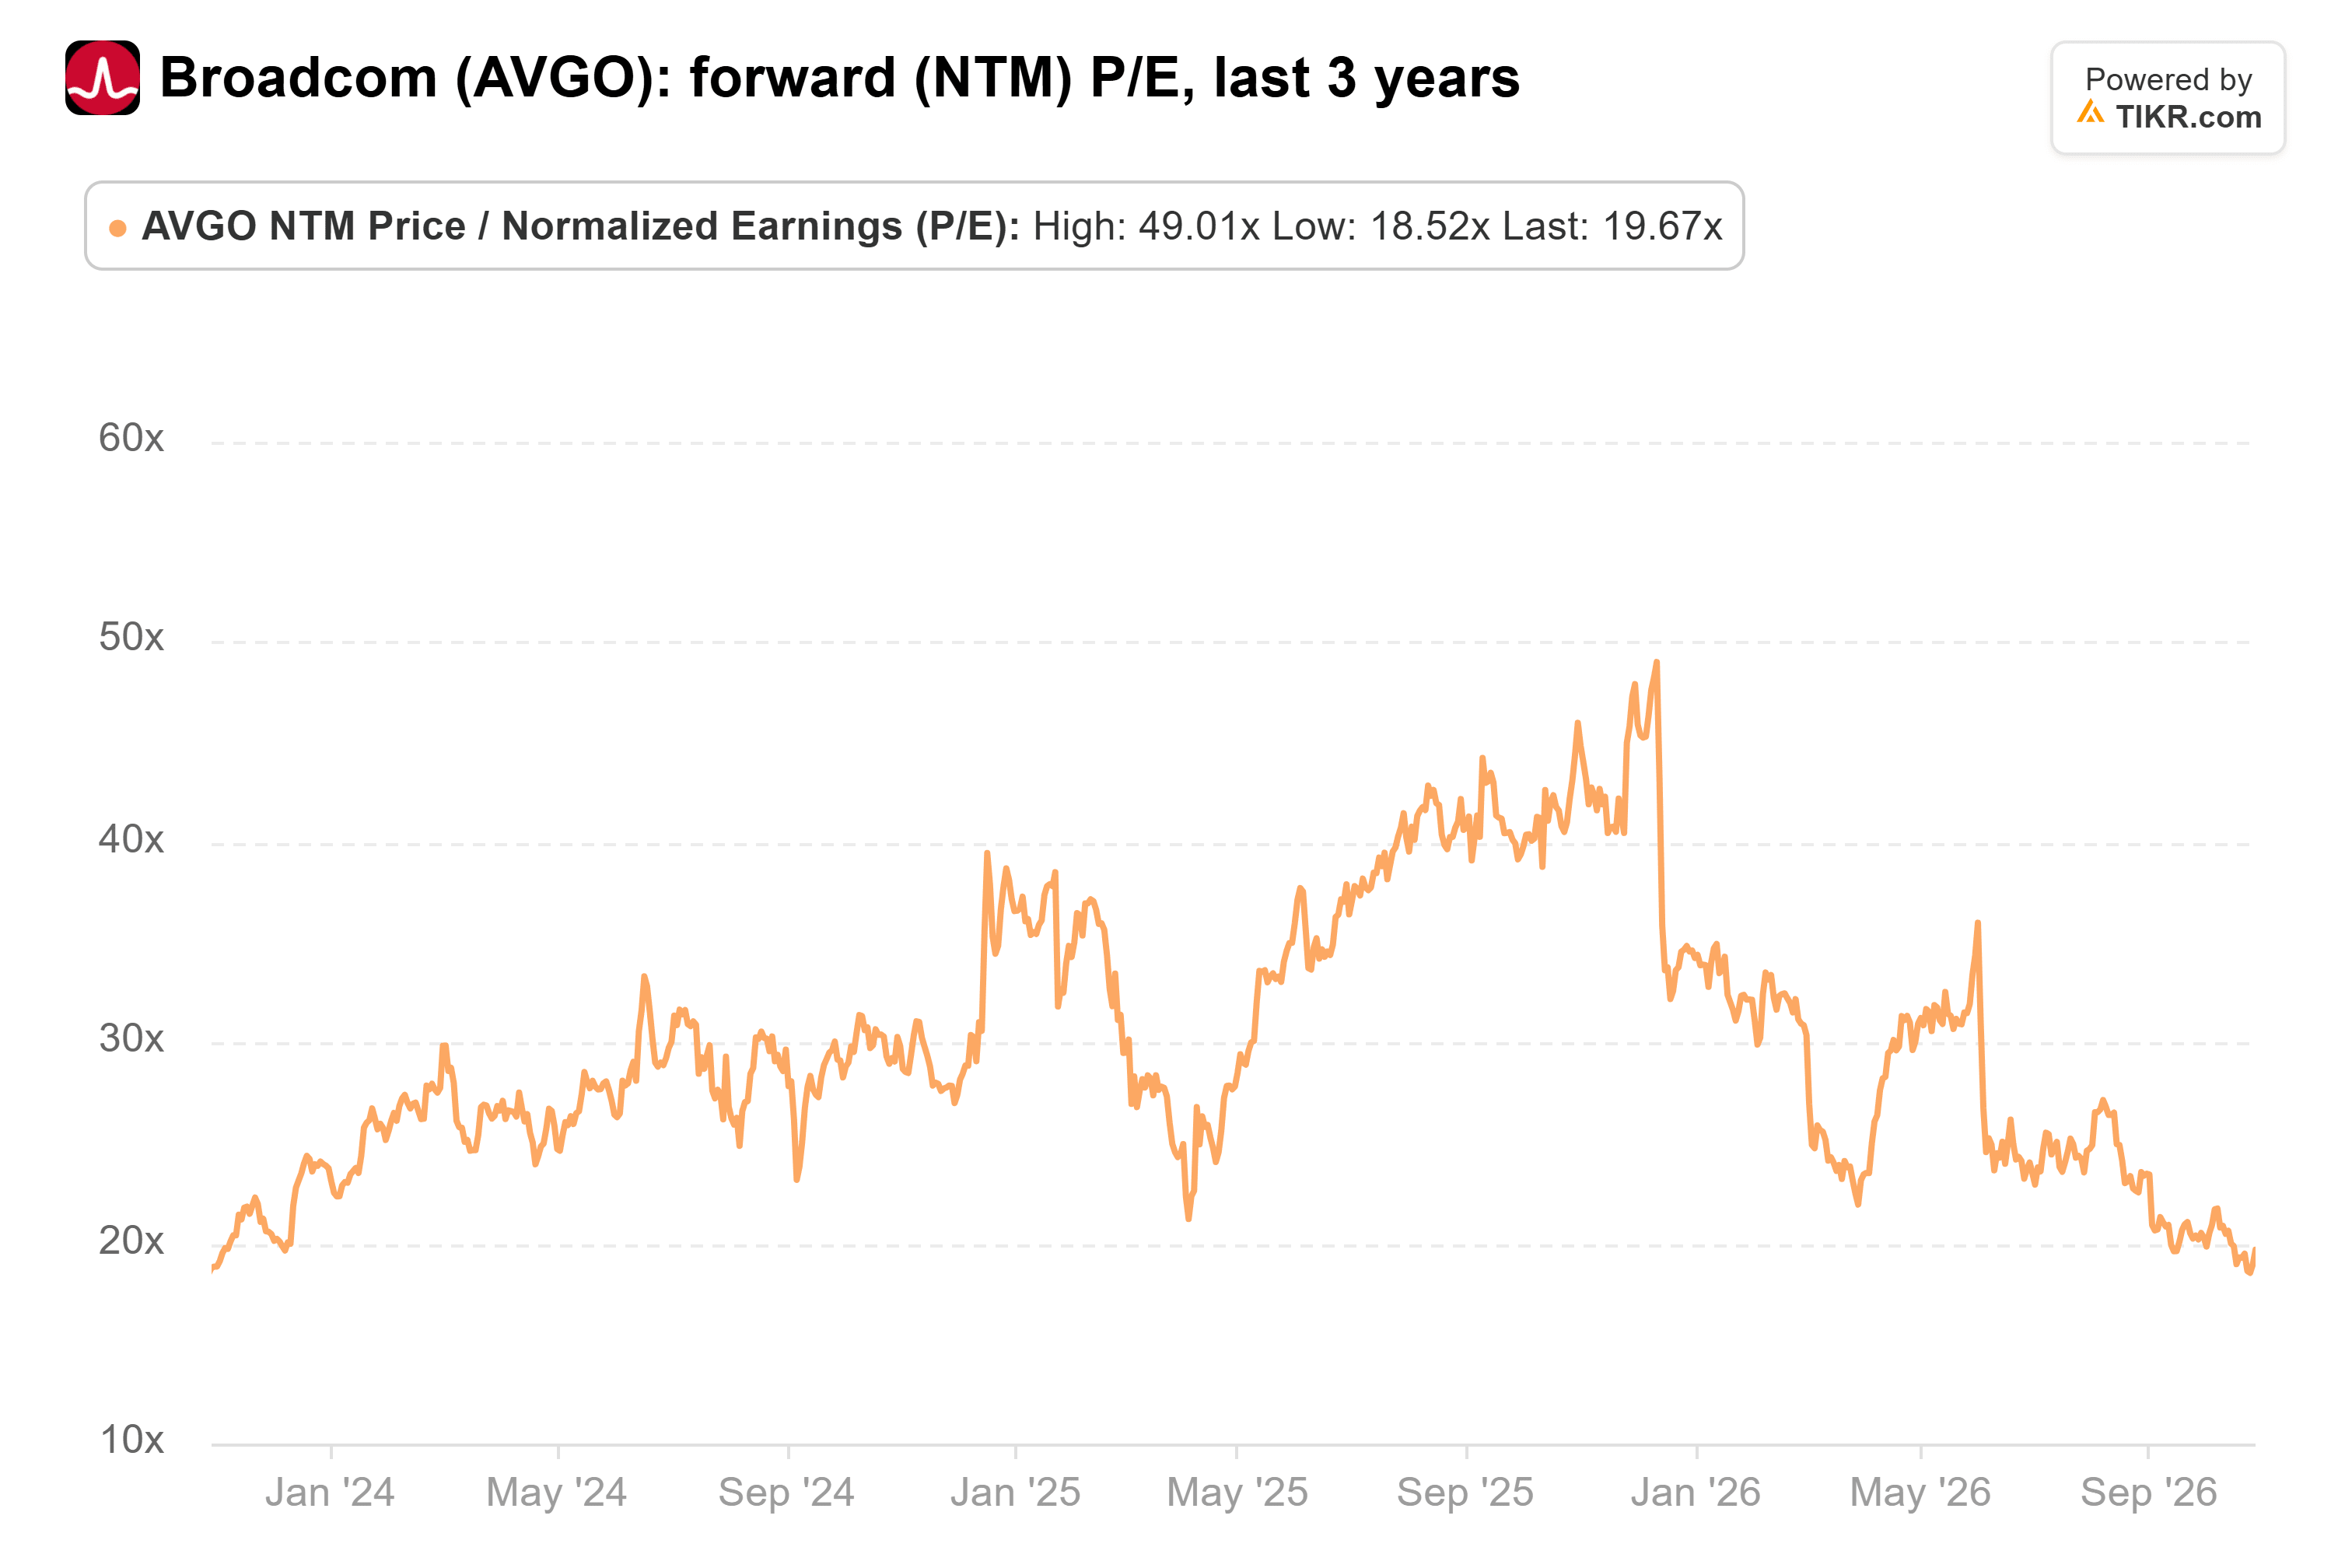
My take: Gensler is right that Broadcom shareholders carry more risk than the balance sheet shows. Calling it 2008 goes too far, since Broadcom brings in enough cash to absorb a hit. And at 20x, a good chunk of that risk is already in the price.
The next deals matter most, though. Broadcom’s annual report, due in December, will show how big its backstops have grown, and Anthropic’s IPO will show whether its biggest customer can pay its own way.
So what is Broadcom stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Broadcom could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!