Key Takeaways
- Stryker shares fell 5% after third-quarter sales and adjusted EPS missed estimates and it cut its 2026 guidance.
- Stryker blamed a slowing market, but Johnson & Johnson grew hips and knees faster in the same quarter, which points to Stryker’s own execution.
- Zimmer Biomet and Smith+Nephew report next week, which should show how much of the slowdown is Stryker’s alone.
Stryker (SYK) stock sank 5% today after its third-quarter results missed estimates and it cut its full-year outlook. CEO Kevin Lobo admitted the quarter “did fall short of our expectations.”
The trouble was hips and knees, a market Stryker shares with Johnson & Johnson (JNJ), Zimmer Biomet (ZBH) and Smith+Nephew (SNN). Their numbers show how much of this is on Stryker.
TIKR tracks 29 analysts on Stryker. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Stryker, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Stryker’s Analyst Ratings
What exactly happened
- Sales rose 7.7% organically to $6.5 billion, below the $6.62 billion expected.
- Adjusted EPS rose 10.3% to $3.52, below the $3.55 expected.
- Stryker now sees 2026 adjusted EPS of $14.80-$14.90, below the $14.95 consensus.
- Orthopaedics grew 5.9% organically, with knee sales up just 1.1% and hip sales down 1.0%.
Stryker lost ground in hips and knees
Lobo said “it is now clear that there is a market slowdown.” But he also admitted “we have not been winning at our historical rate,” after a cyber incident, a July SAP rollout and slow uptake of new products.
J&J’s results back that up. In the same quarter, its knee sales rose 2.5% and its hip sales rose 3.2%.
Smith+Nephew doesn’t look like the one winning Stryker’s cases. Its US knee sales fell 7.2% and its US hip sales fell 1.5% in the second quarter, and it cut its 2026 revenue outlook in August.
Zimmer Biomet is the bigger question. Its hip sales grew 5.1% organically in the second quarter, and in August CEO Ivan Tornos raised guidance, citing “healthy underlying markets.” If its hips and knees hold up when it reports next week, did Zimmer pick up the cases Stryker lost?
A cheaper Stryker
Analysts still expect adjusted earnings to keep climbing.
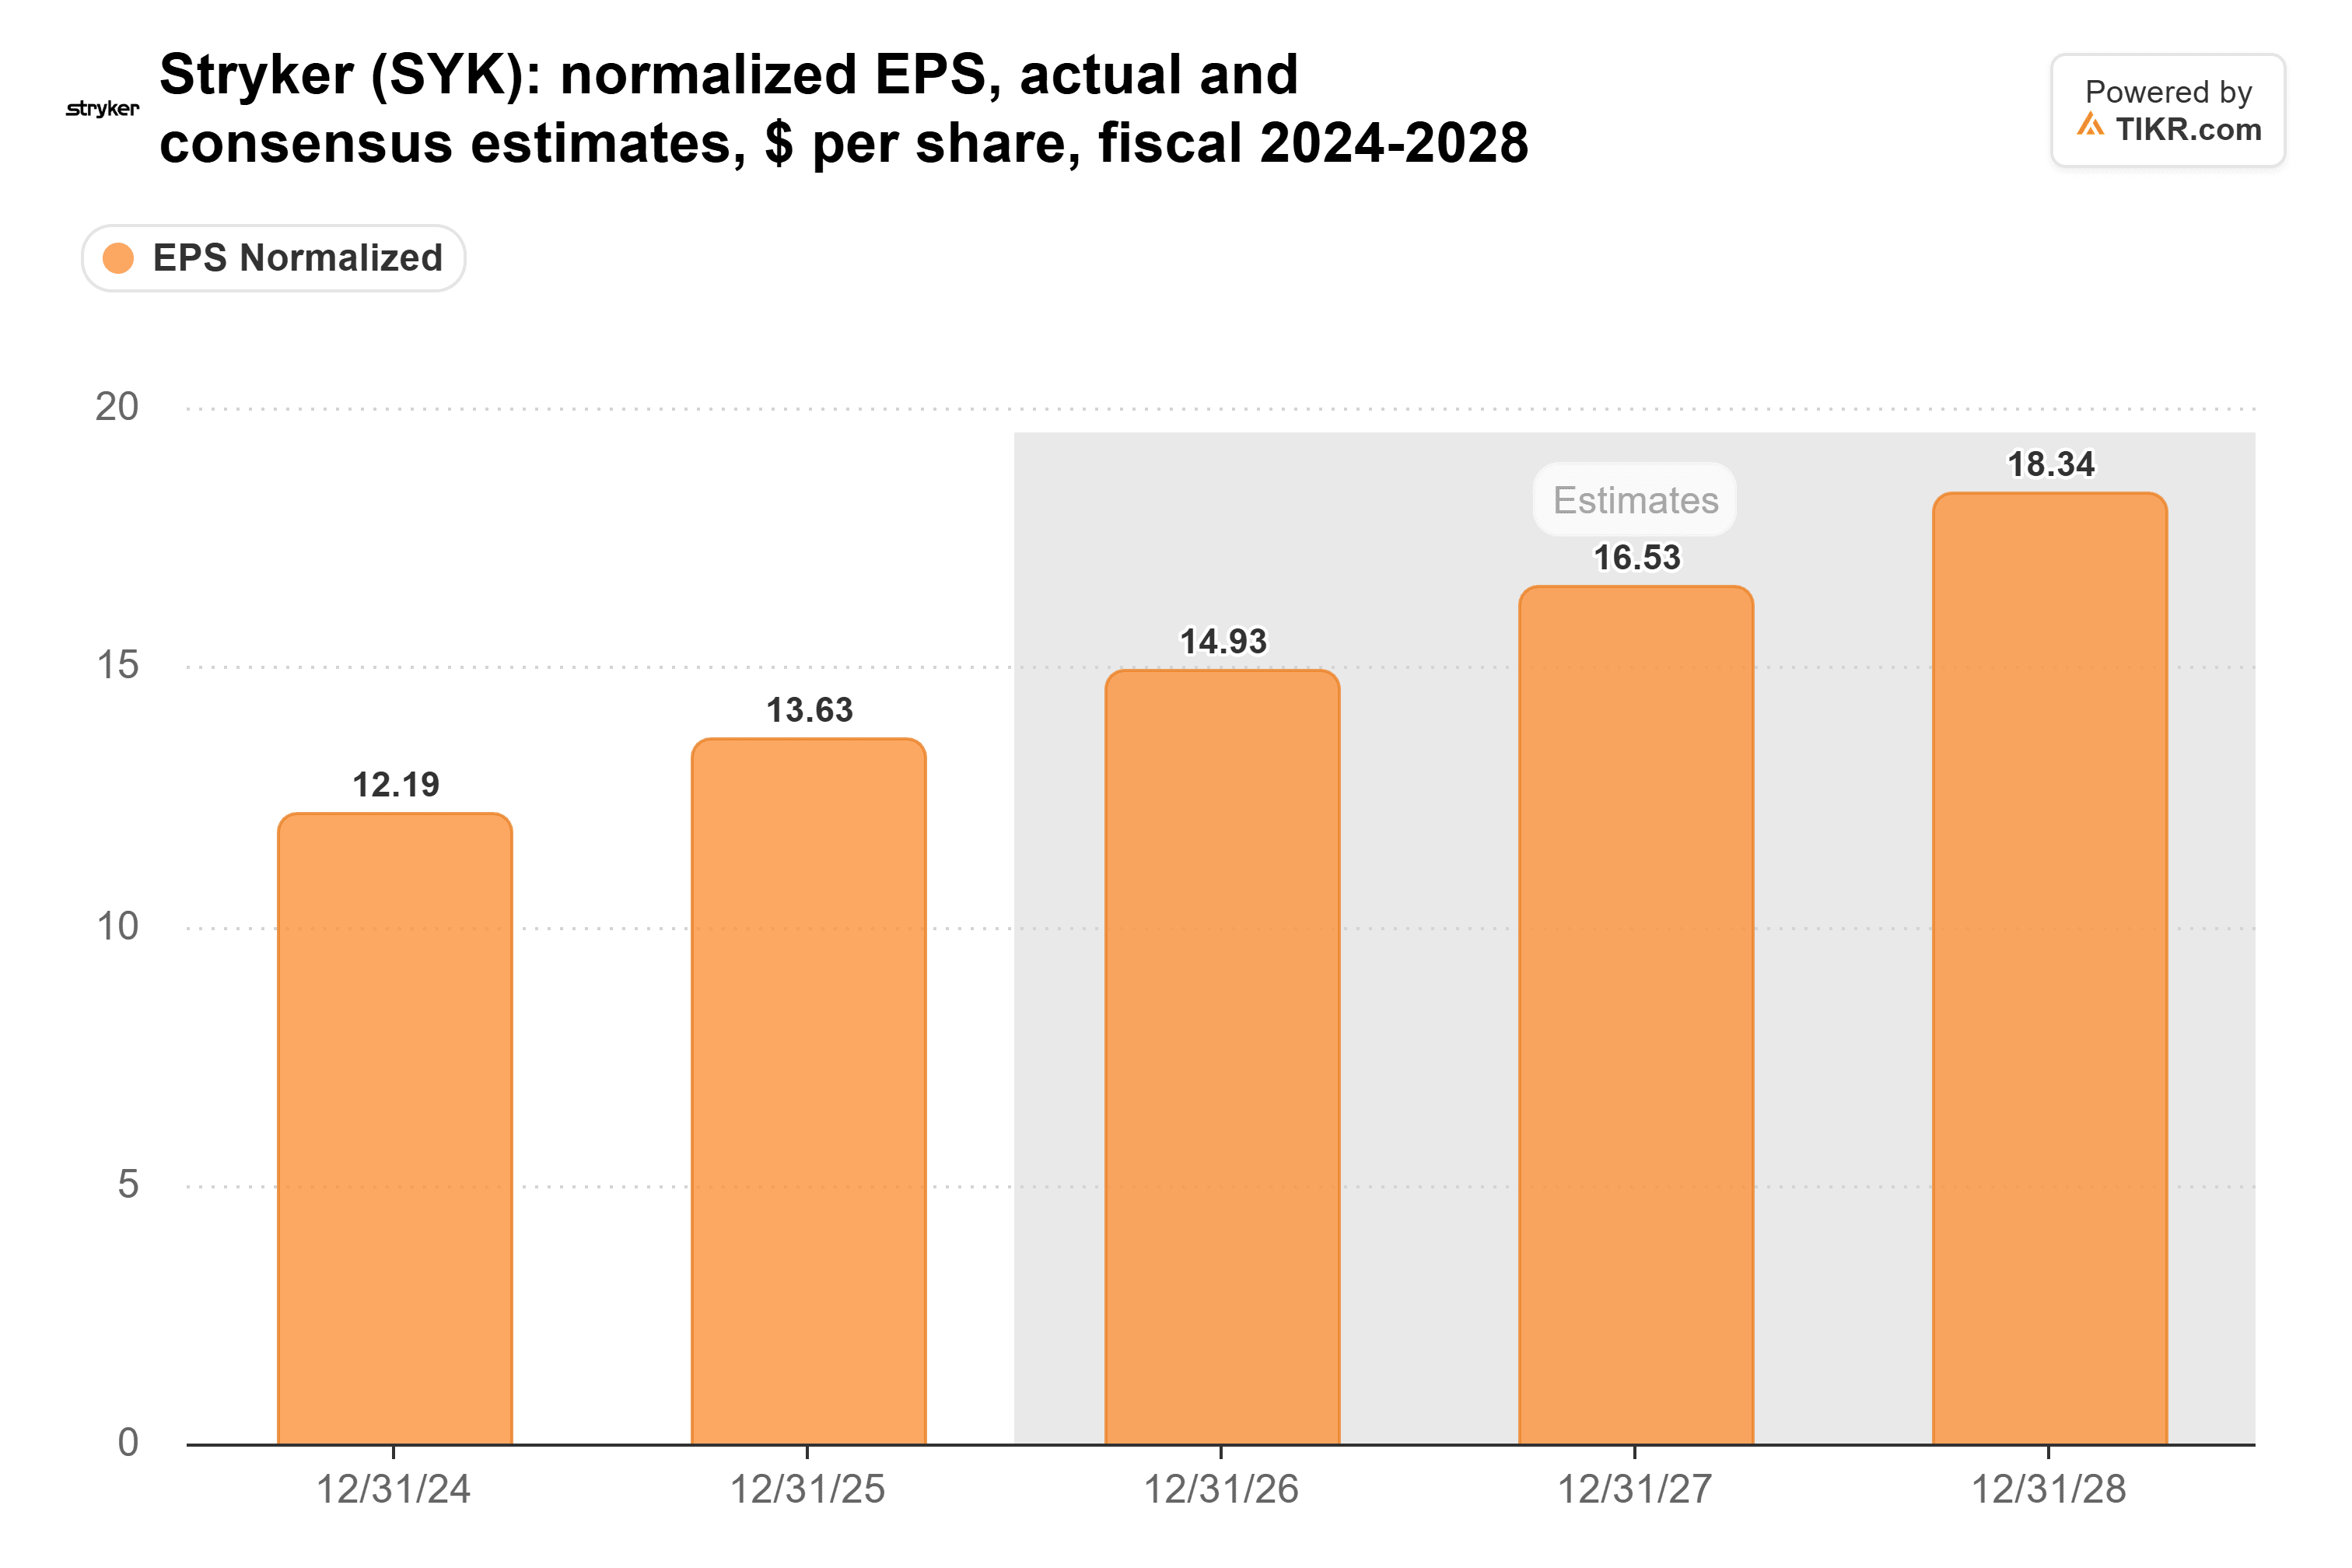
The midpoint of the new guidance, $14.85, is just under the 2026 estimate. So this quarter hurts this year’s number more than the longer path.
Stryker traded at 19x forward earnings at Thursday’s close. Its five-year average is 26x.
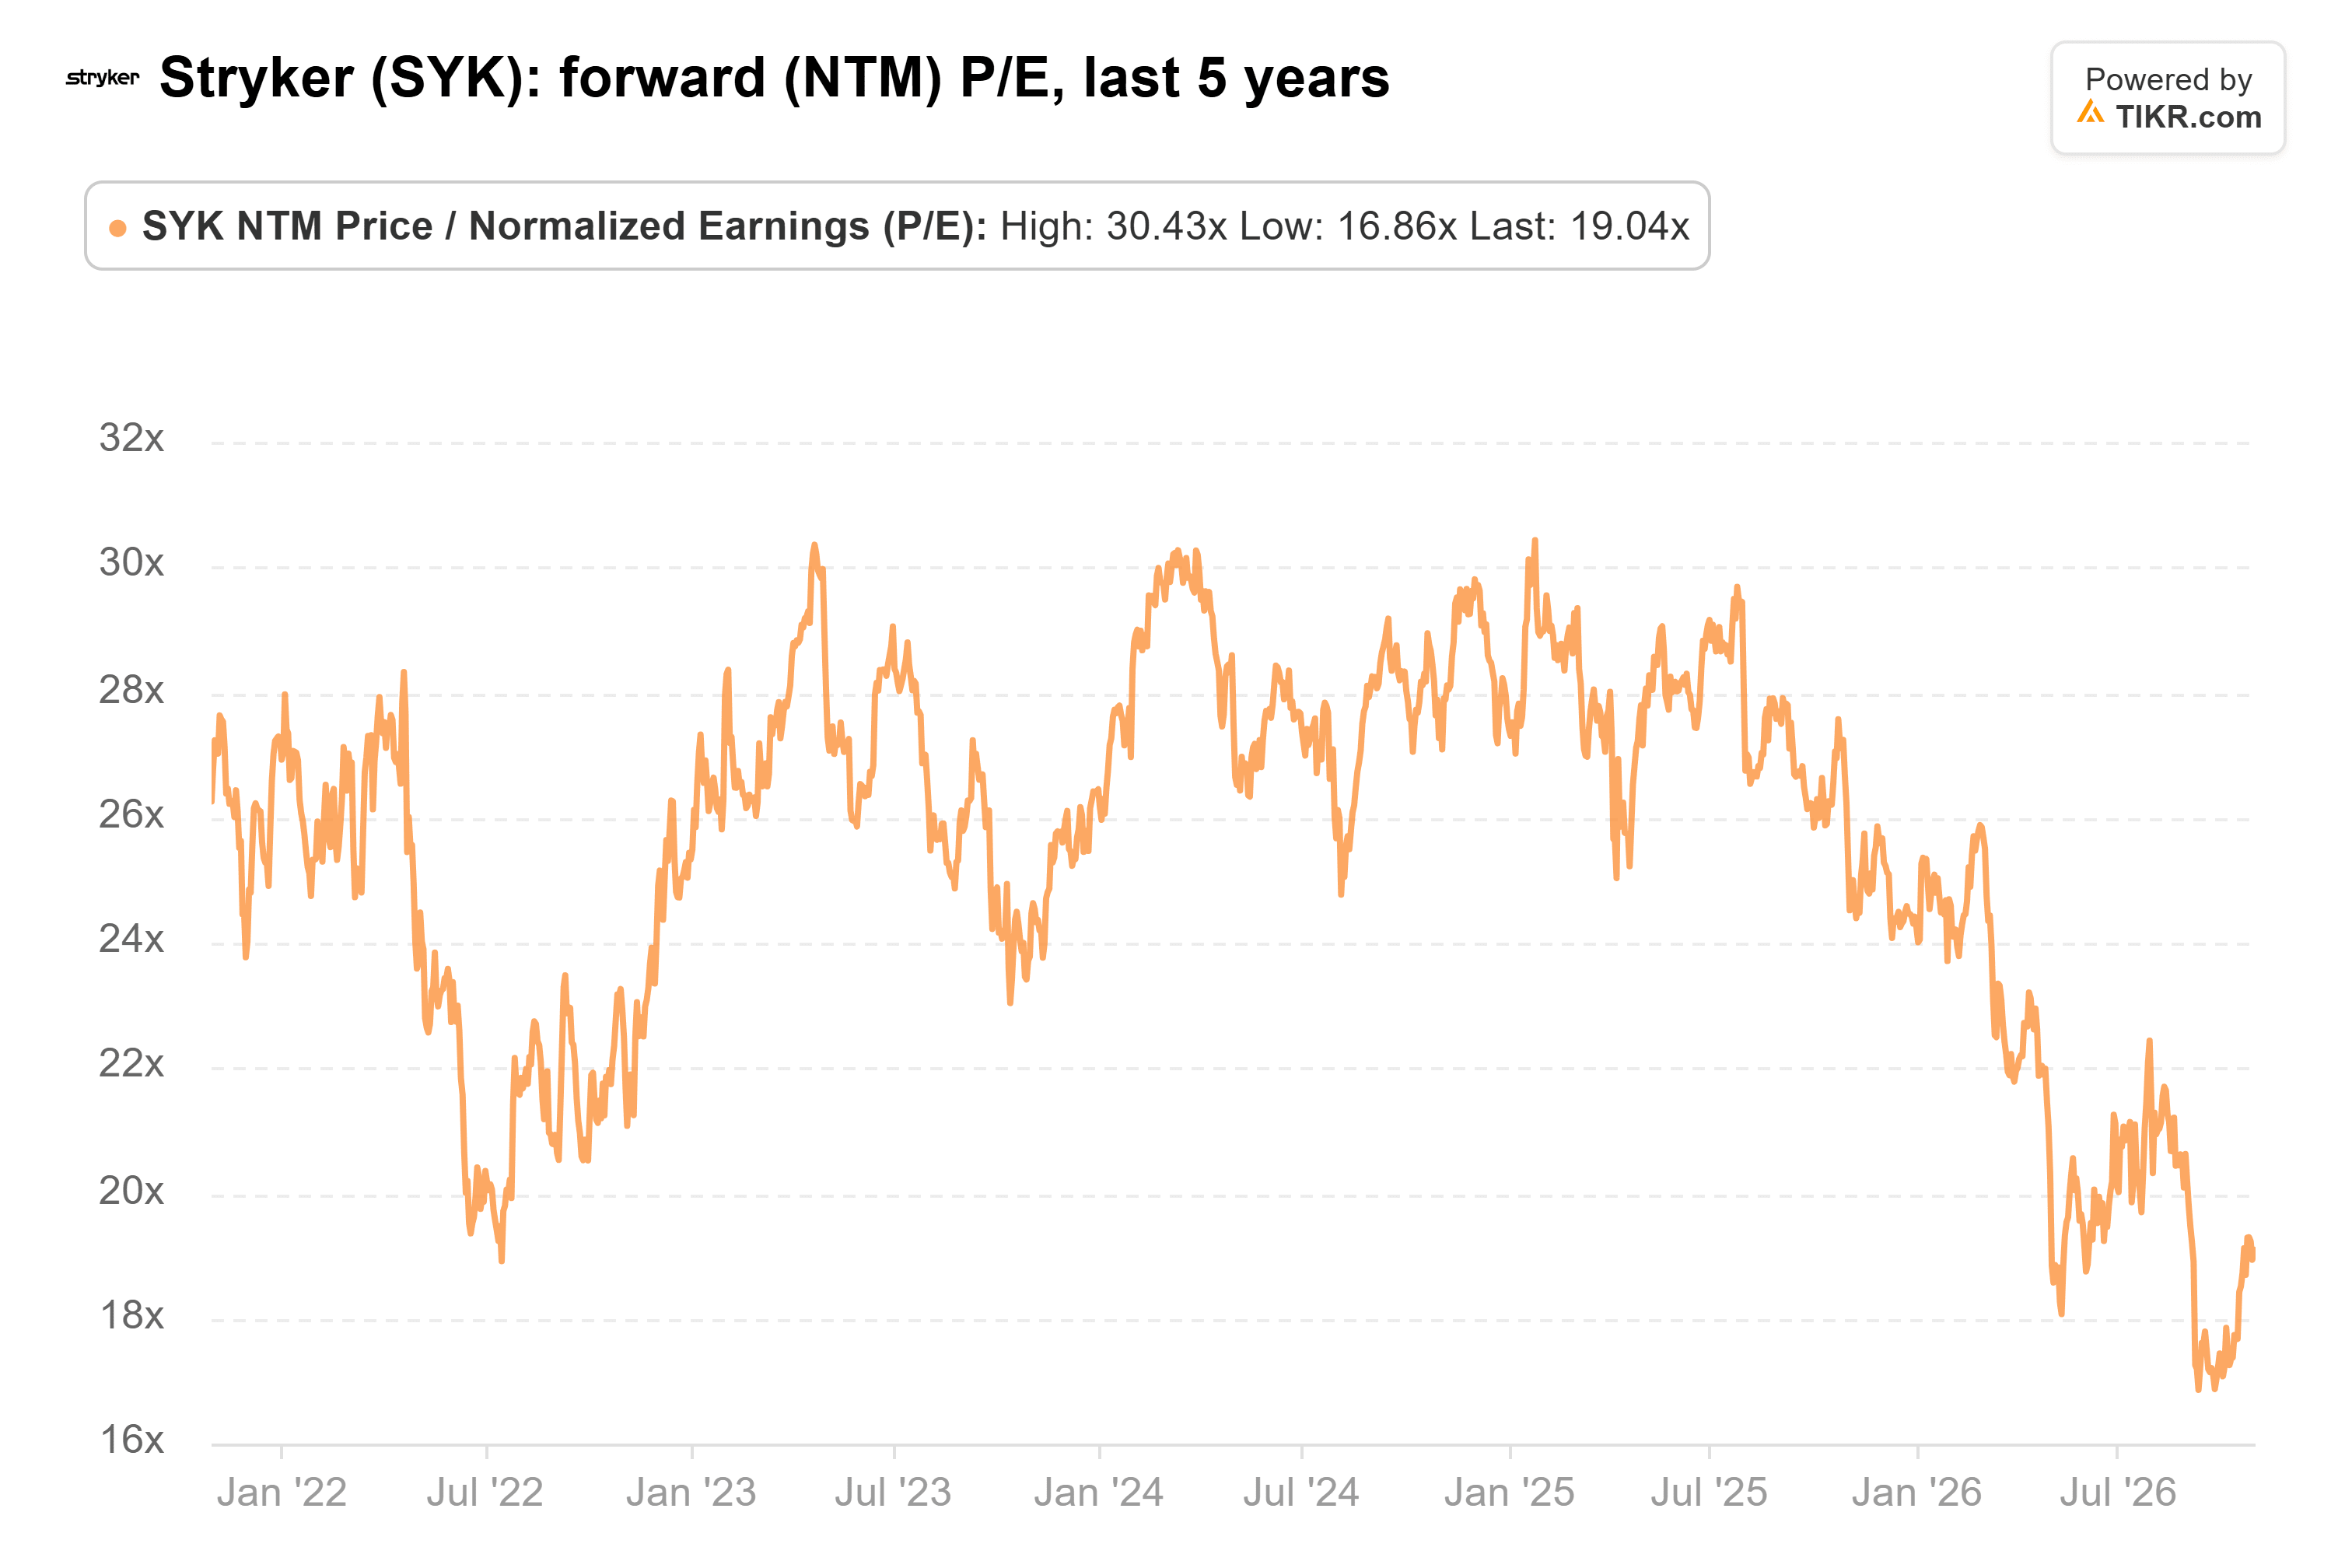
At today’s price it’s about 17x, close to the five-year low it hit in September.
My take: the market is slowing, but J&J’s numbers say Stryker’s own mistakes did more of the damage. At about 17x forward earnings, I think the selloff goes too far.
Of course, the market could keep getting softer. Next week’s reports from Zimmer and Smith+Nephew will show how much.
So what is Stryker stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Stryker could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!