Key Takeaways
- Bank of America cut its DoorDash price target to $257 from $275 on Oct. 30 but kept its Buy rating. That target is 44% above a stock that’s down 33% in a year.
- In the third quarter, DoorDash reported record revenue and profit. It also agreed to buy Instacart for about $17 billion, at least 75% of it in cash.
- DoorDash trades at 25x forward earnings, its lowest in five years, and Bank of America’s target implies 35x, below the stock’s three-year average.
- Bank of America’s call looks right on the numbers. The risks are the debt and new shares from the Instacart deal and how long it will take to close.
DoorDash (DASH) just reported record revenue and profit, and agreed to buy Instacart (CART) for about $17 billion. Its stock is still down 33% from a year ago, at $179 as of Thursday’s close.
On Oct. 30, Bank of America analyst Justin Post cut his price target to $257 from $275 and kept his Buy rating. That’s 44% upside.
A year of bigger bills
The trouble started in November 2025, when management said it would spend several hundred million dollars more in 2026 on new projects.
That bill showed up in the second quarter of 2026, when diluted EPS fell to $0.46 from $0.65.
Then, on Oct. 29, came a much bigger bill: Instacart at $65 a share, at least 75% in cash.
Bank of America is still a buyer
Post’s $257 target matches the Street’s average to the dollar, and the quarter backs him up. Third-quarter revenue rose 34% to $4.6 billion, net income jumped 91% to $466 million, and adjusted EBITDA climbed 41% to $1.06 billion, in the top half of management’s guidance.
TIKR tracks 43 analysts on DoorDash. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on DoorDash, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See DoorDash’s Analyst Ratings
Does $257 add up?
The Street’s average target has fallen from $303 a year ago to $257:

Targets run from $172 to $350, and 43 analysts cover the stock.
Analysts cut their 2026 and 2027 normalized EPS estimates over the past year, but they’ve raised both by 5% to 6% since June 30. They now expect normalized EPS to climb from $5.10 in 2025 to $8.25 in 2027 and $10.16 in 2028:
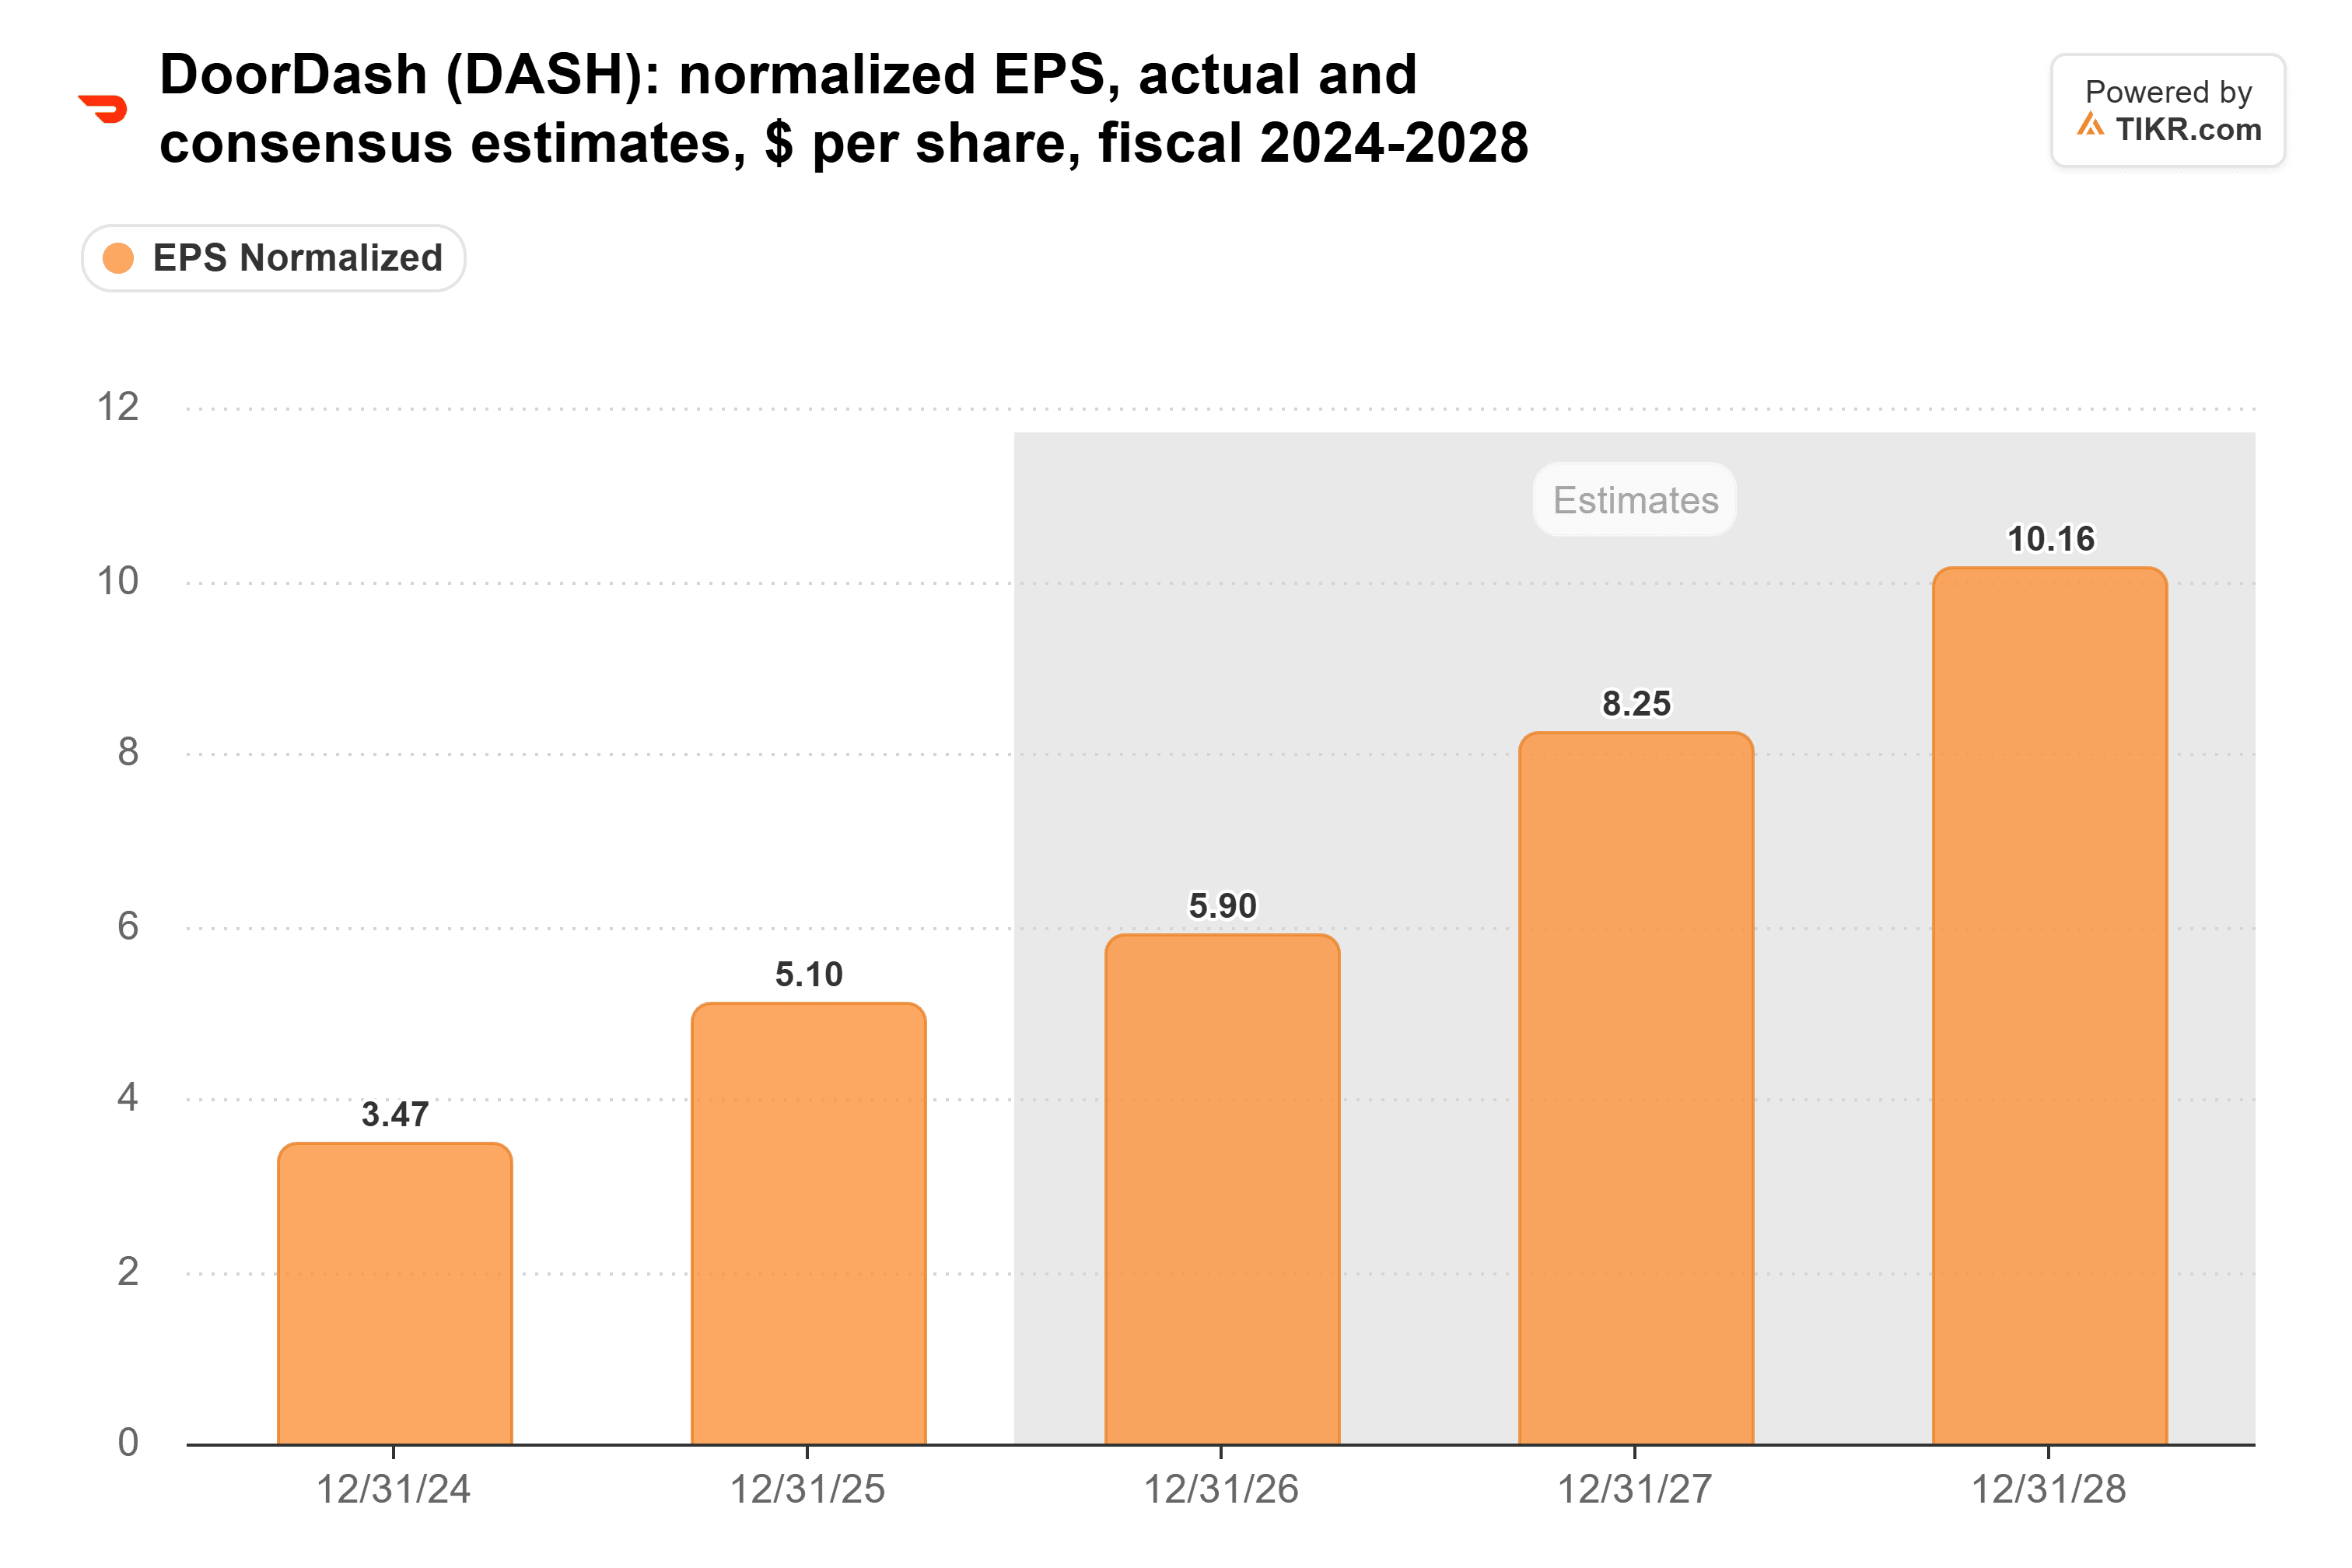
The quarter’s beat should help the 2026 and 2027 estimates hold up. The 2028 estimate is harder to call, since DoorDash plans to reinvest more than all of the Instacart synergies in the first year after closing.
At [$179], DoorDash trades at 25x forward earnings, its lowest in five years. Post’s $257 works out to 35x expected earnings over the next twelve months. That’s above the stock’s one-year average of 33x and below its three-year average of 39x.
Bank of America has this one right
The risk is Instacart. The deal adds debt and new shares, needs regulatory approval, and may not close until the first half of 2028.
I think Post has DoorDash right: his target asks for less than the stock’s three-year average multiple, on rising estimates, from a business that just set records.
The next test is the fourth-quarter report in February. If DoorDash’s 2027 spending plans come in heavier than analysts expect, $257 gets a lot harder to reach.
So what is DoorDash stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what DoorDash could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!