


Key Stats for Coinbase Stock
- Current Price: $183.00
- Target Price (Mid): ~$606
- Street Target: ~$207 (mean of 33 analysts)
- Potential Total Return: ~231%
- Annualized IRR: ~33% / year
Now Live: Discover how much upside your favorite stocks could have using TIKR’s new Valuation Model (It’s free) >>>
What Happened?
Coinbase Global (COIN) picked up a neutral new rating the day before its stock briefly cleared $200. Wells Fargo analyst Daniel Welden started coverage on October 1 at Equal Weight with a $200 target. He called Coinbase a core crypto franchise and said stronger activity may not translate fully into revenue. He added that consumer pricing pressure and mixed USDC trends temper the firm’s constructive view of a crypto recovery.
On October 2, shares hit $200.35 intraday before closing at $183.00, down 3.32%. Coinbase’s response sits on the expense line, a theme in its investor relations materials and spelled out by its CFO.
A 2026 Cost Pledge Meets Shrinking Revenue Estimates
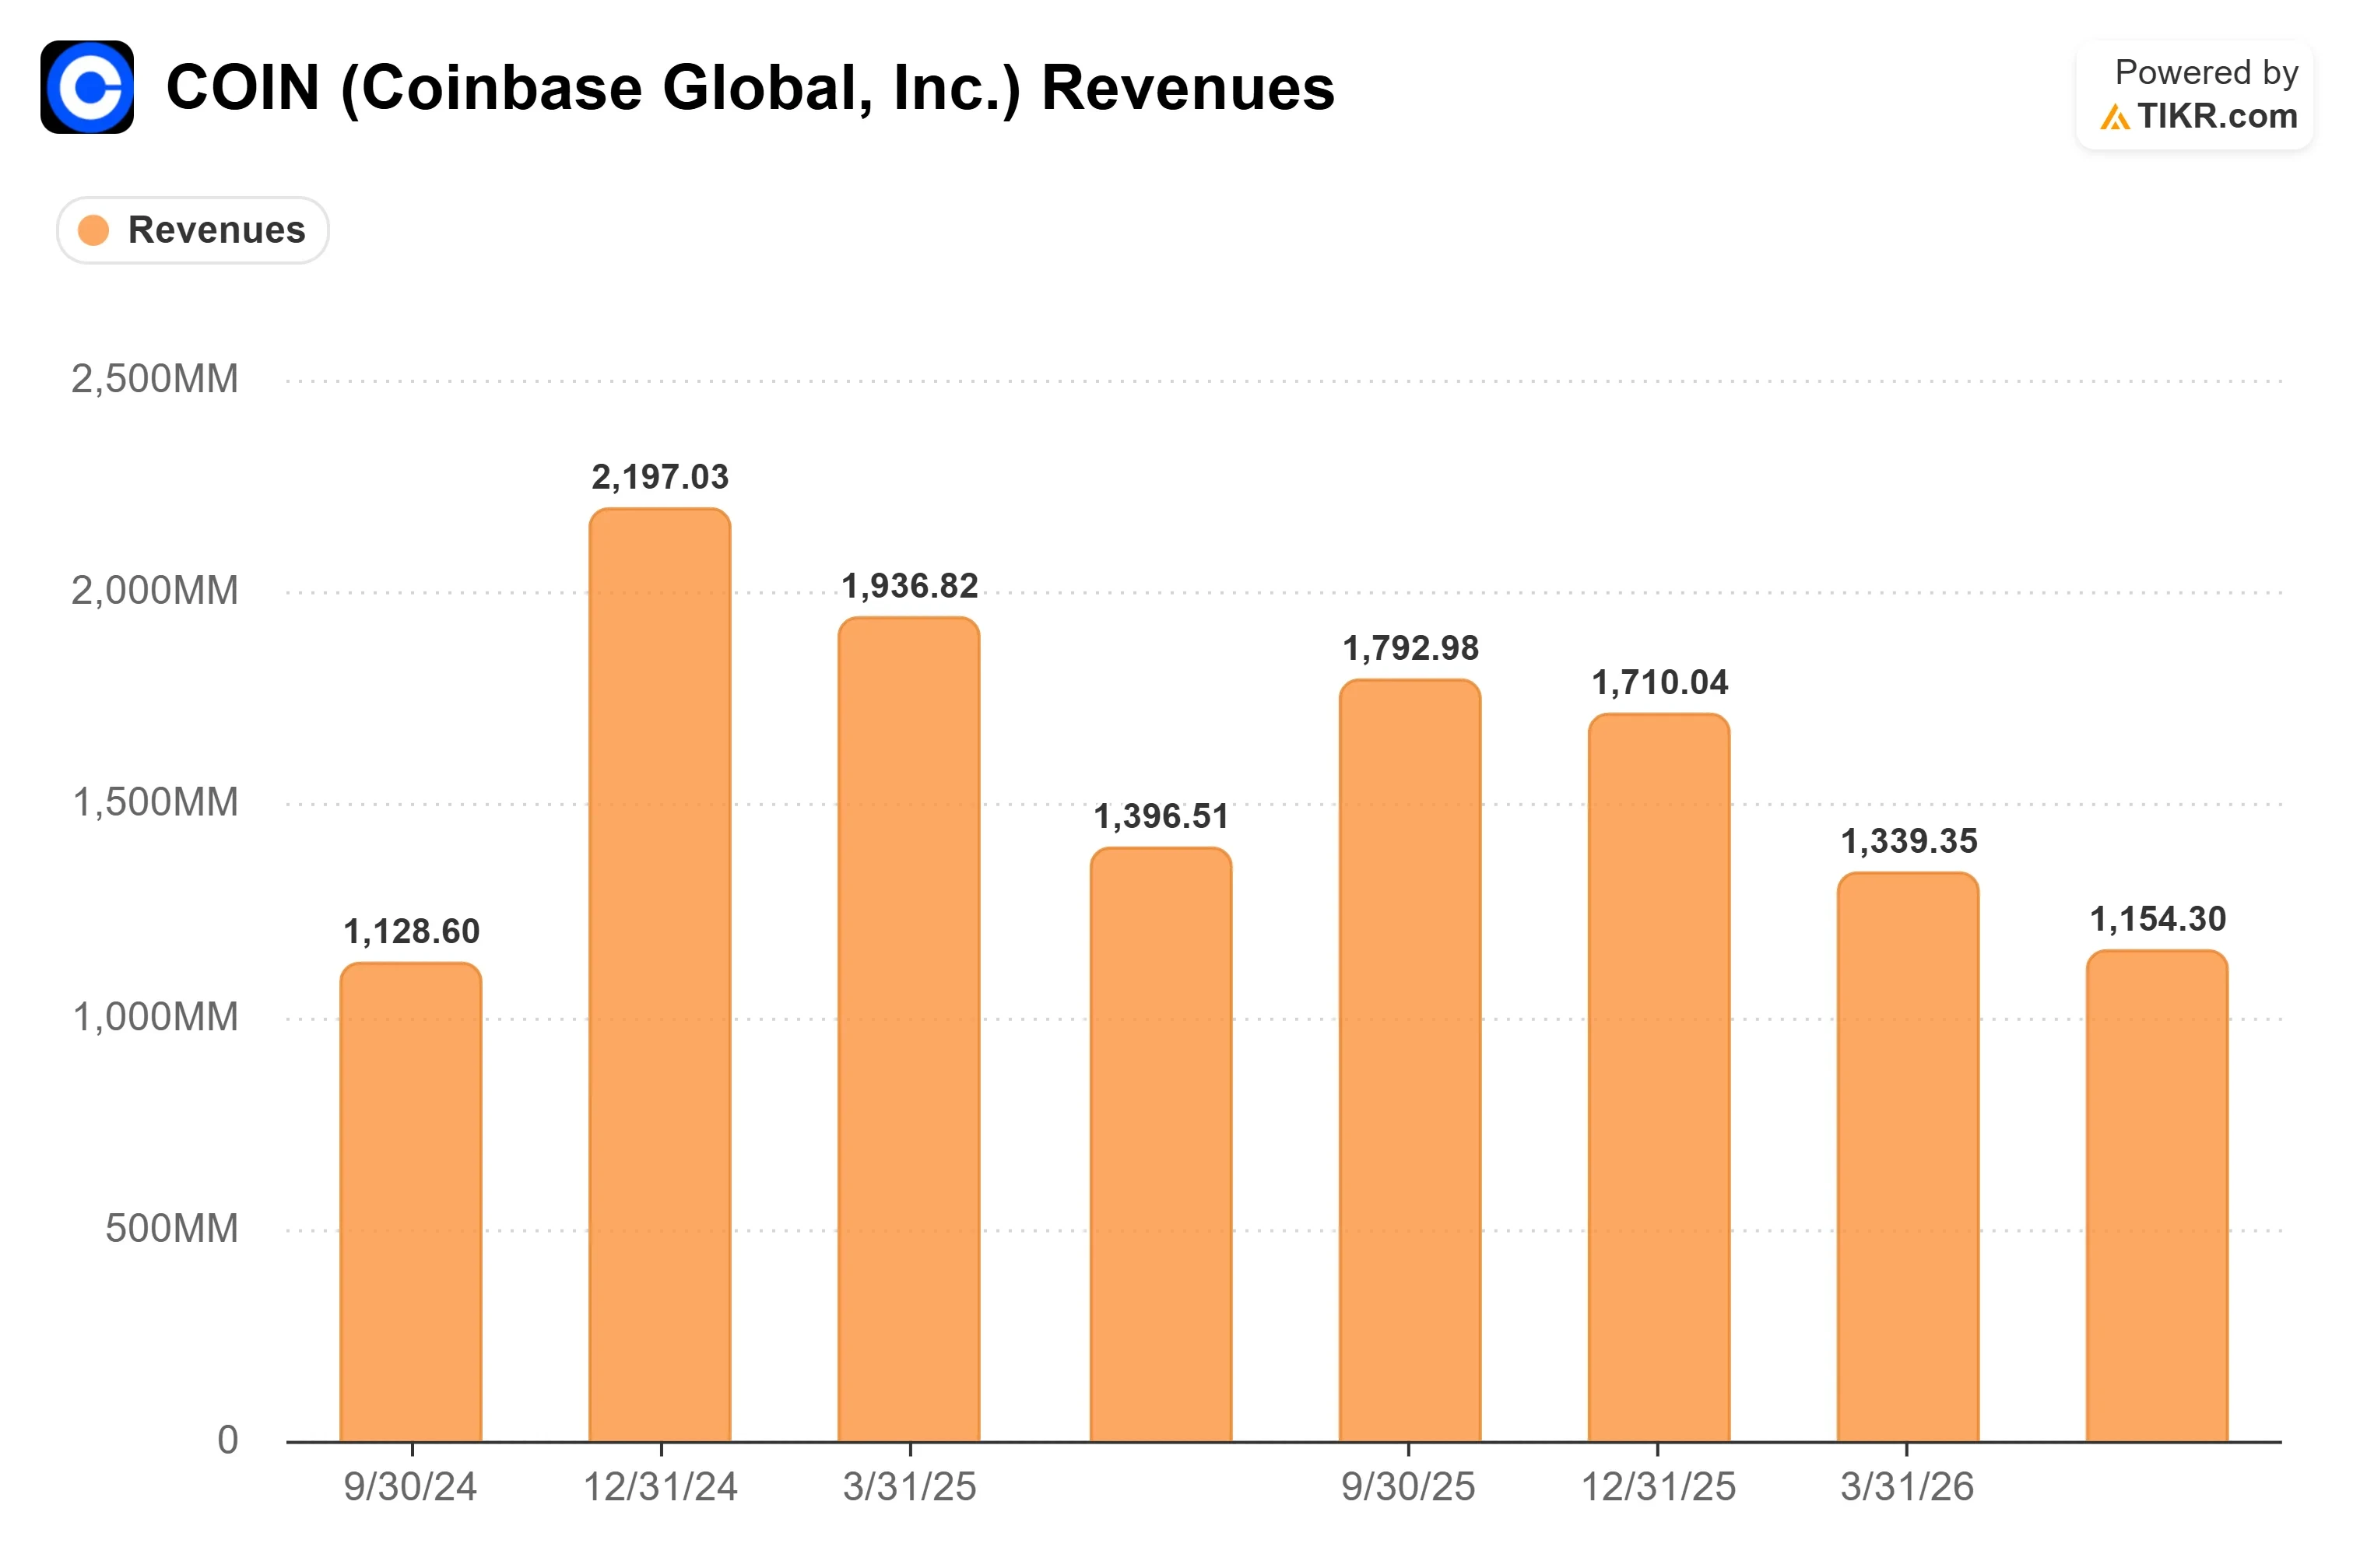
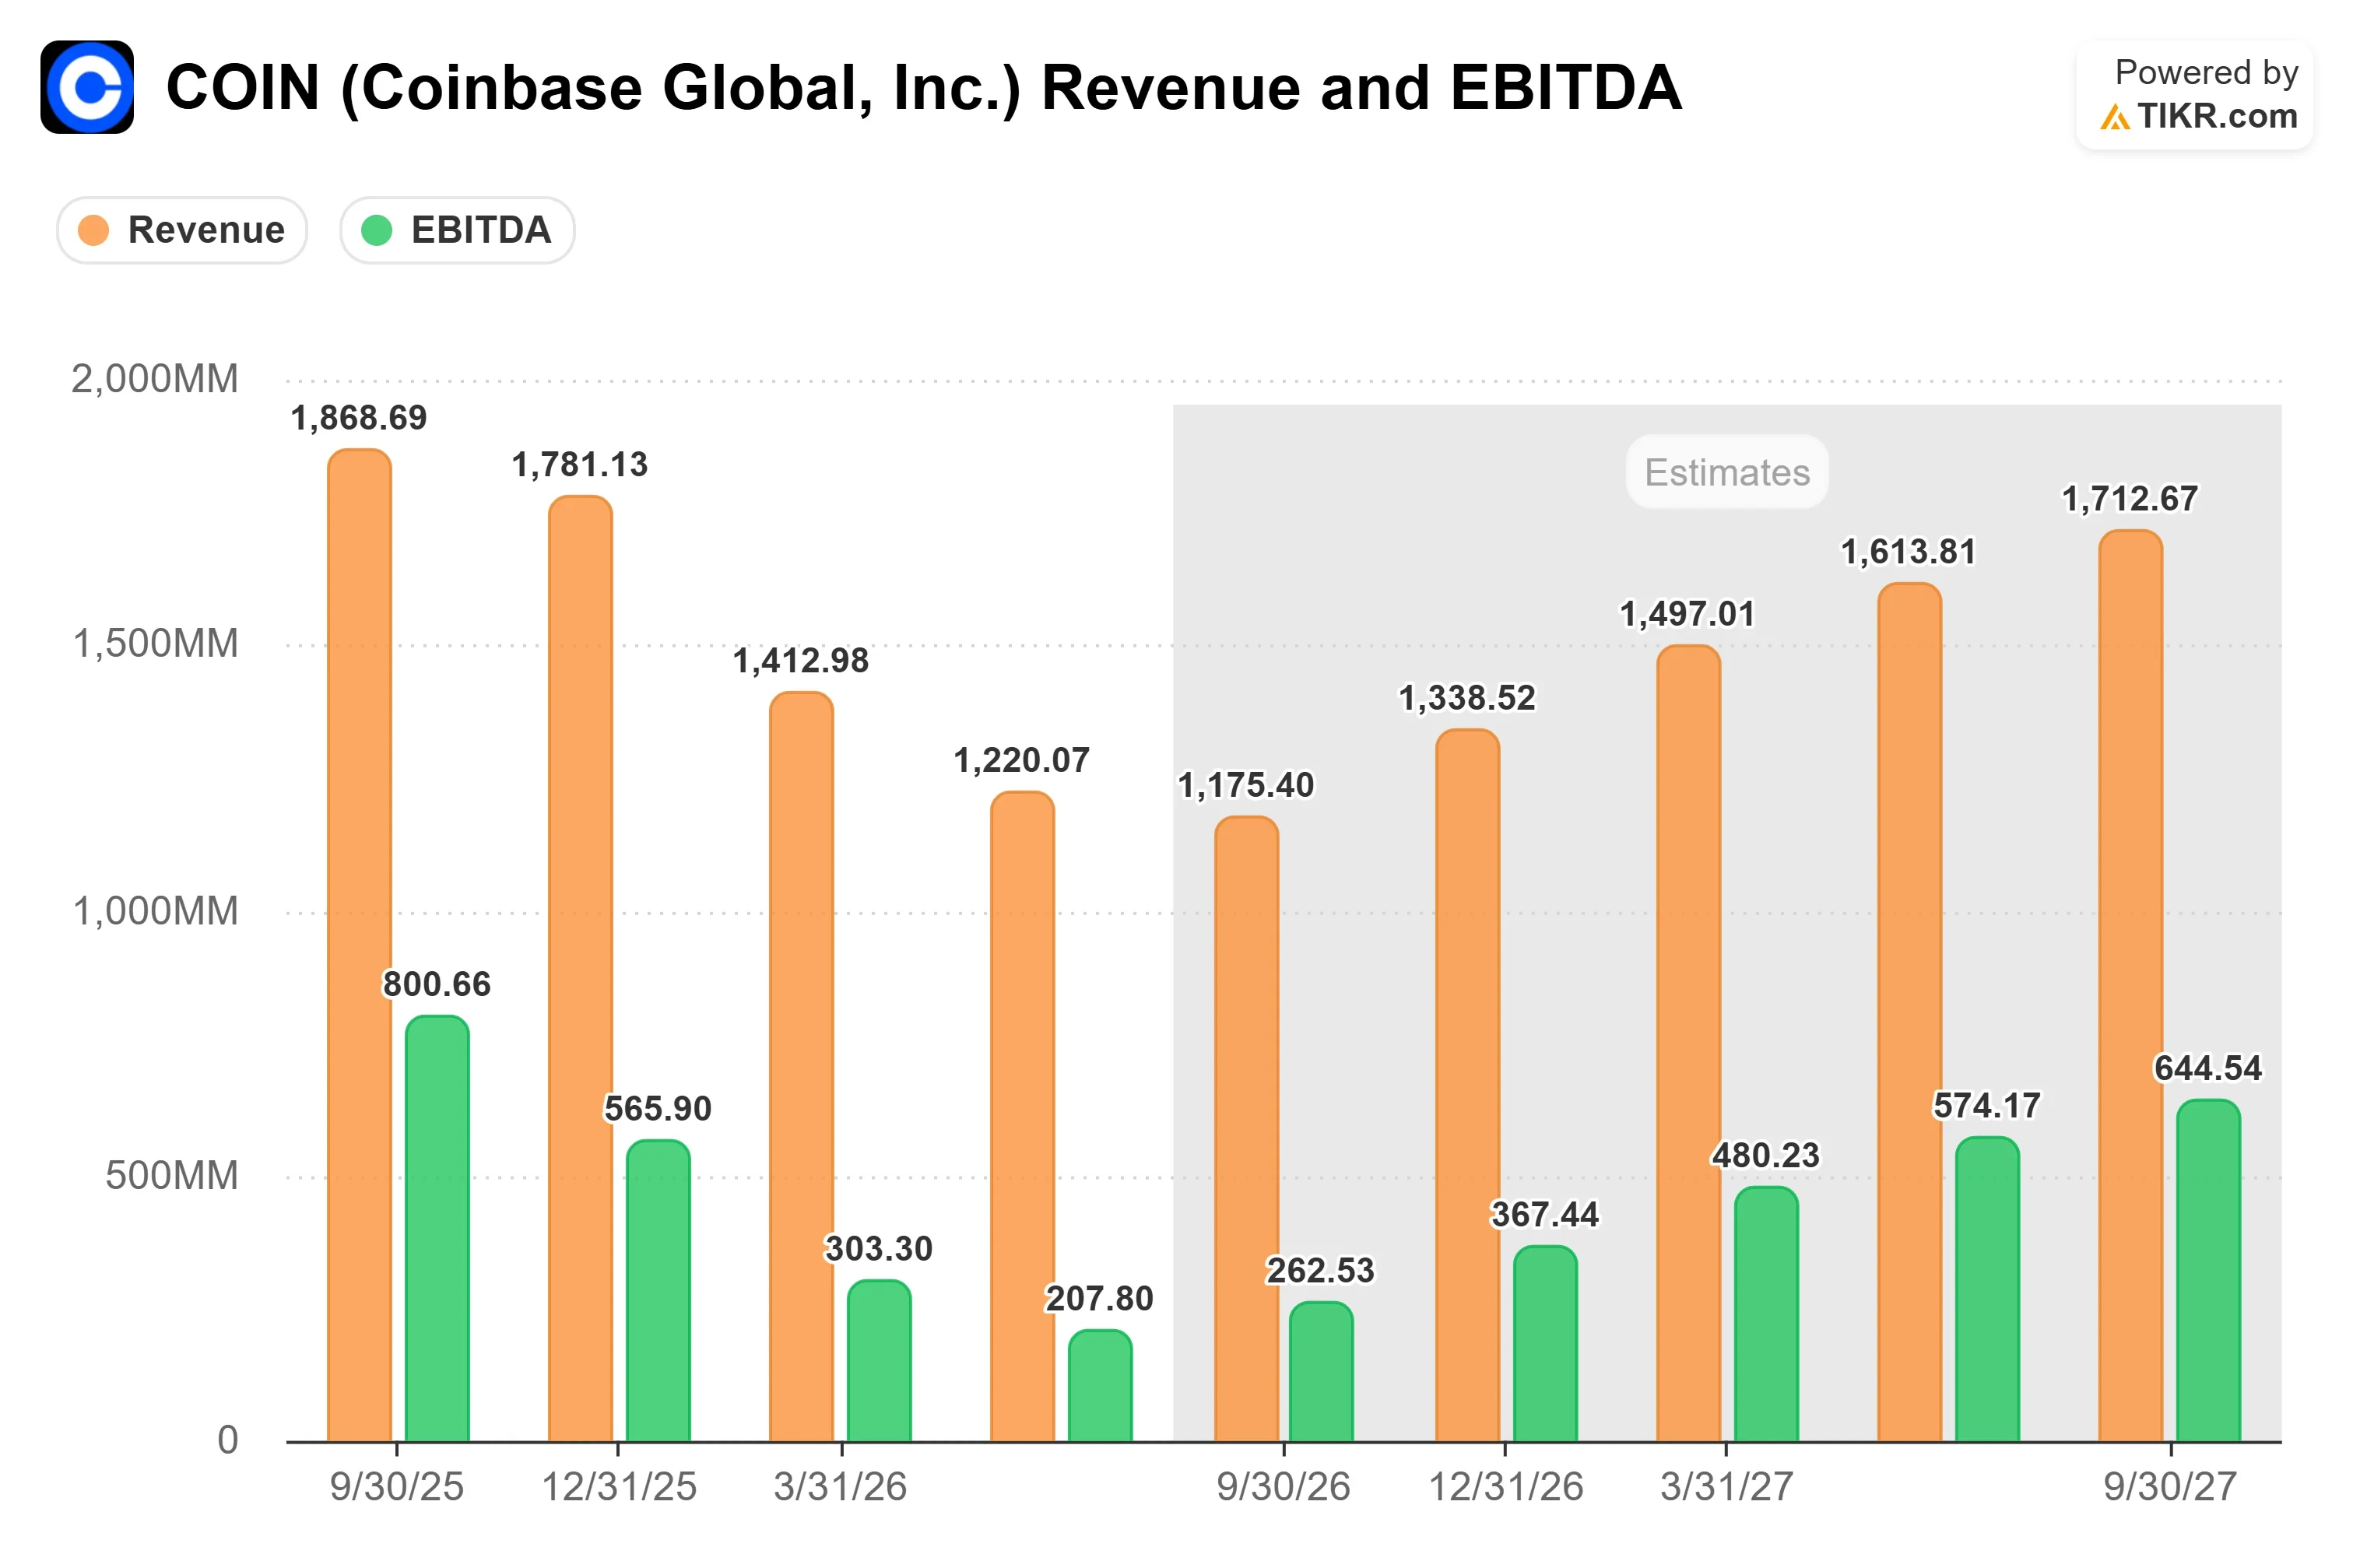
At Citi’s 2026 Global TMT Conference on September 10, CFO Alesia Haas said, “In the near term, as we’ve committed, our 2026 expenses will look very much like our 2025 expenses, absent what happens with USDC rewards.” The pledge covers 2026 only, and it arrives as revenue expectations have weakened sharply. Analysts have cut their full-year 2026 revenue estimate from about $8.5 billion at the end of 2025 to around $5.3 billion, and expect third-quarter revenue to be near $1.2 billion, down about 37% from a year earlier.
The 2027 consensus shows why costs matter. Analysts expect revenue to rise about 29% to $6.9 billion and EBITDA to more than double to $2.6 billion, lifting the EBITDA margin from about 22% to about 38%. That works out to roughly 93 cents of each added revenue dollar reaching EBITDA.
USDC cuts both ways. Haas’s pledge excludes USDC rewards, and Wells flags mixed USDC trends. The contract terms are steady, though: Haas said the Circle agreement was renewed on the same terms for another three years.
See historical and forward estimates for Coinbase stock (It’s free!) >>>
Clearing, Citi, and Prediction Markets Push Revenue Beyond Spot Fees
Wells Fargo’s pricing concern centers on consumer spot trading, the business Coinbase is working to make less central. On September 28, the CFTC approved Coinbase Clearing LLC as a derivatives clearing organization, letting Coinbase list, broker, and clear fully collateralized contracts in-house, though margined products still clear through partners. The same day, Citi expanded its partnership with Coinbase so Citi’s institutional clients can accept stablecoin payments at checkout.
Haas called derivatives a market “which is still 70-plus percent of the overall U.S. and global crypto market.” On prediction markets, she said “all of the revenue that we’ve seen to date is really incremental,” with no growth marketing behind it yet. Coinbase One passed 1 million paid subscribers in the second quarter, though its benefits still cover only spot trading.
Washington offers less help. The CLARITY Act failed a Senate cloture vote on September 15, well short of the 60 votes needed, leaving the SEC and CFTC route Haas had already said Coinbase would pursue. Separately, a Form 8-K filed after the October 2 close showed Chief Accounting Officer Jennifer Jones plans to retire, with the company citing no disagreement.
See how Coinbase performs against its peers in TIKR (It’s free!) >>>
TIKR Advanced Model Analysis
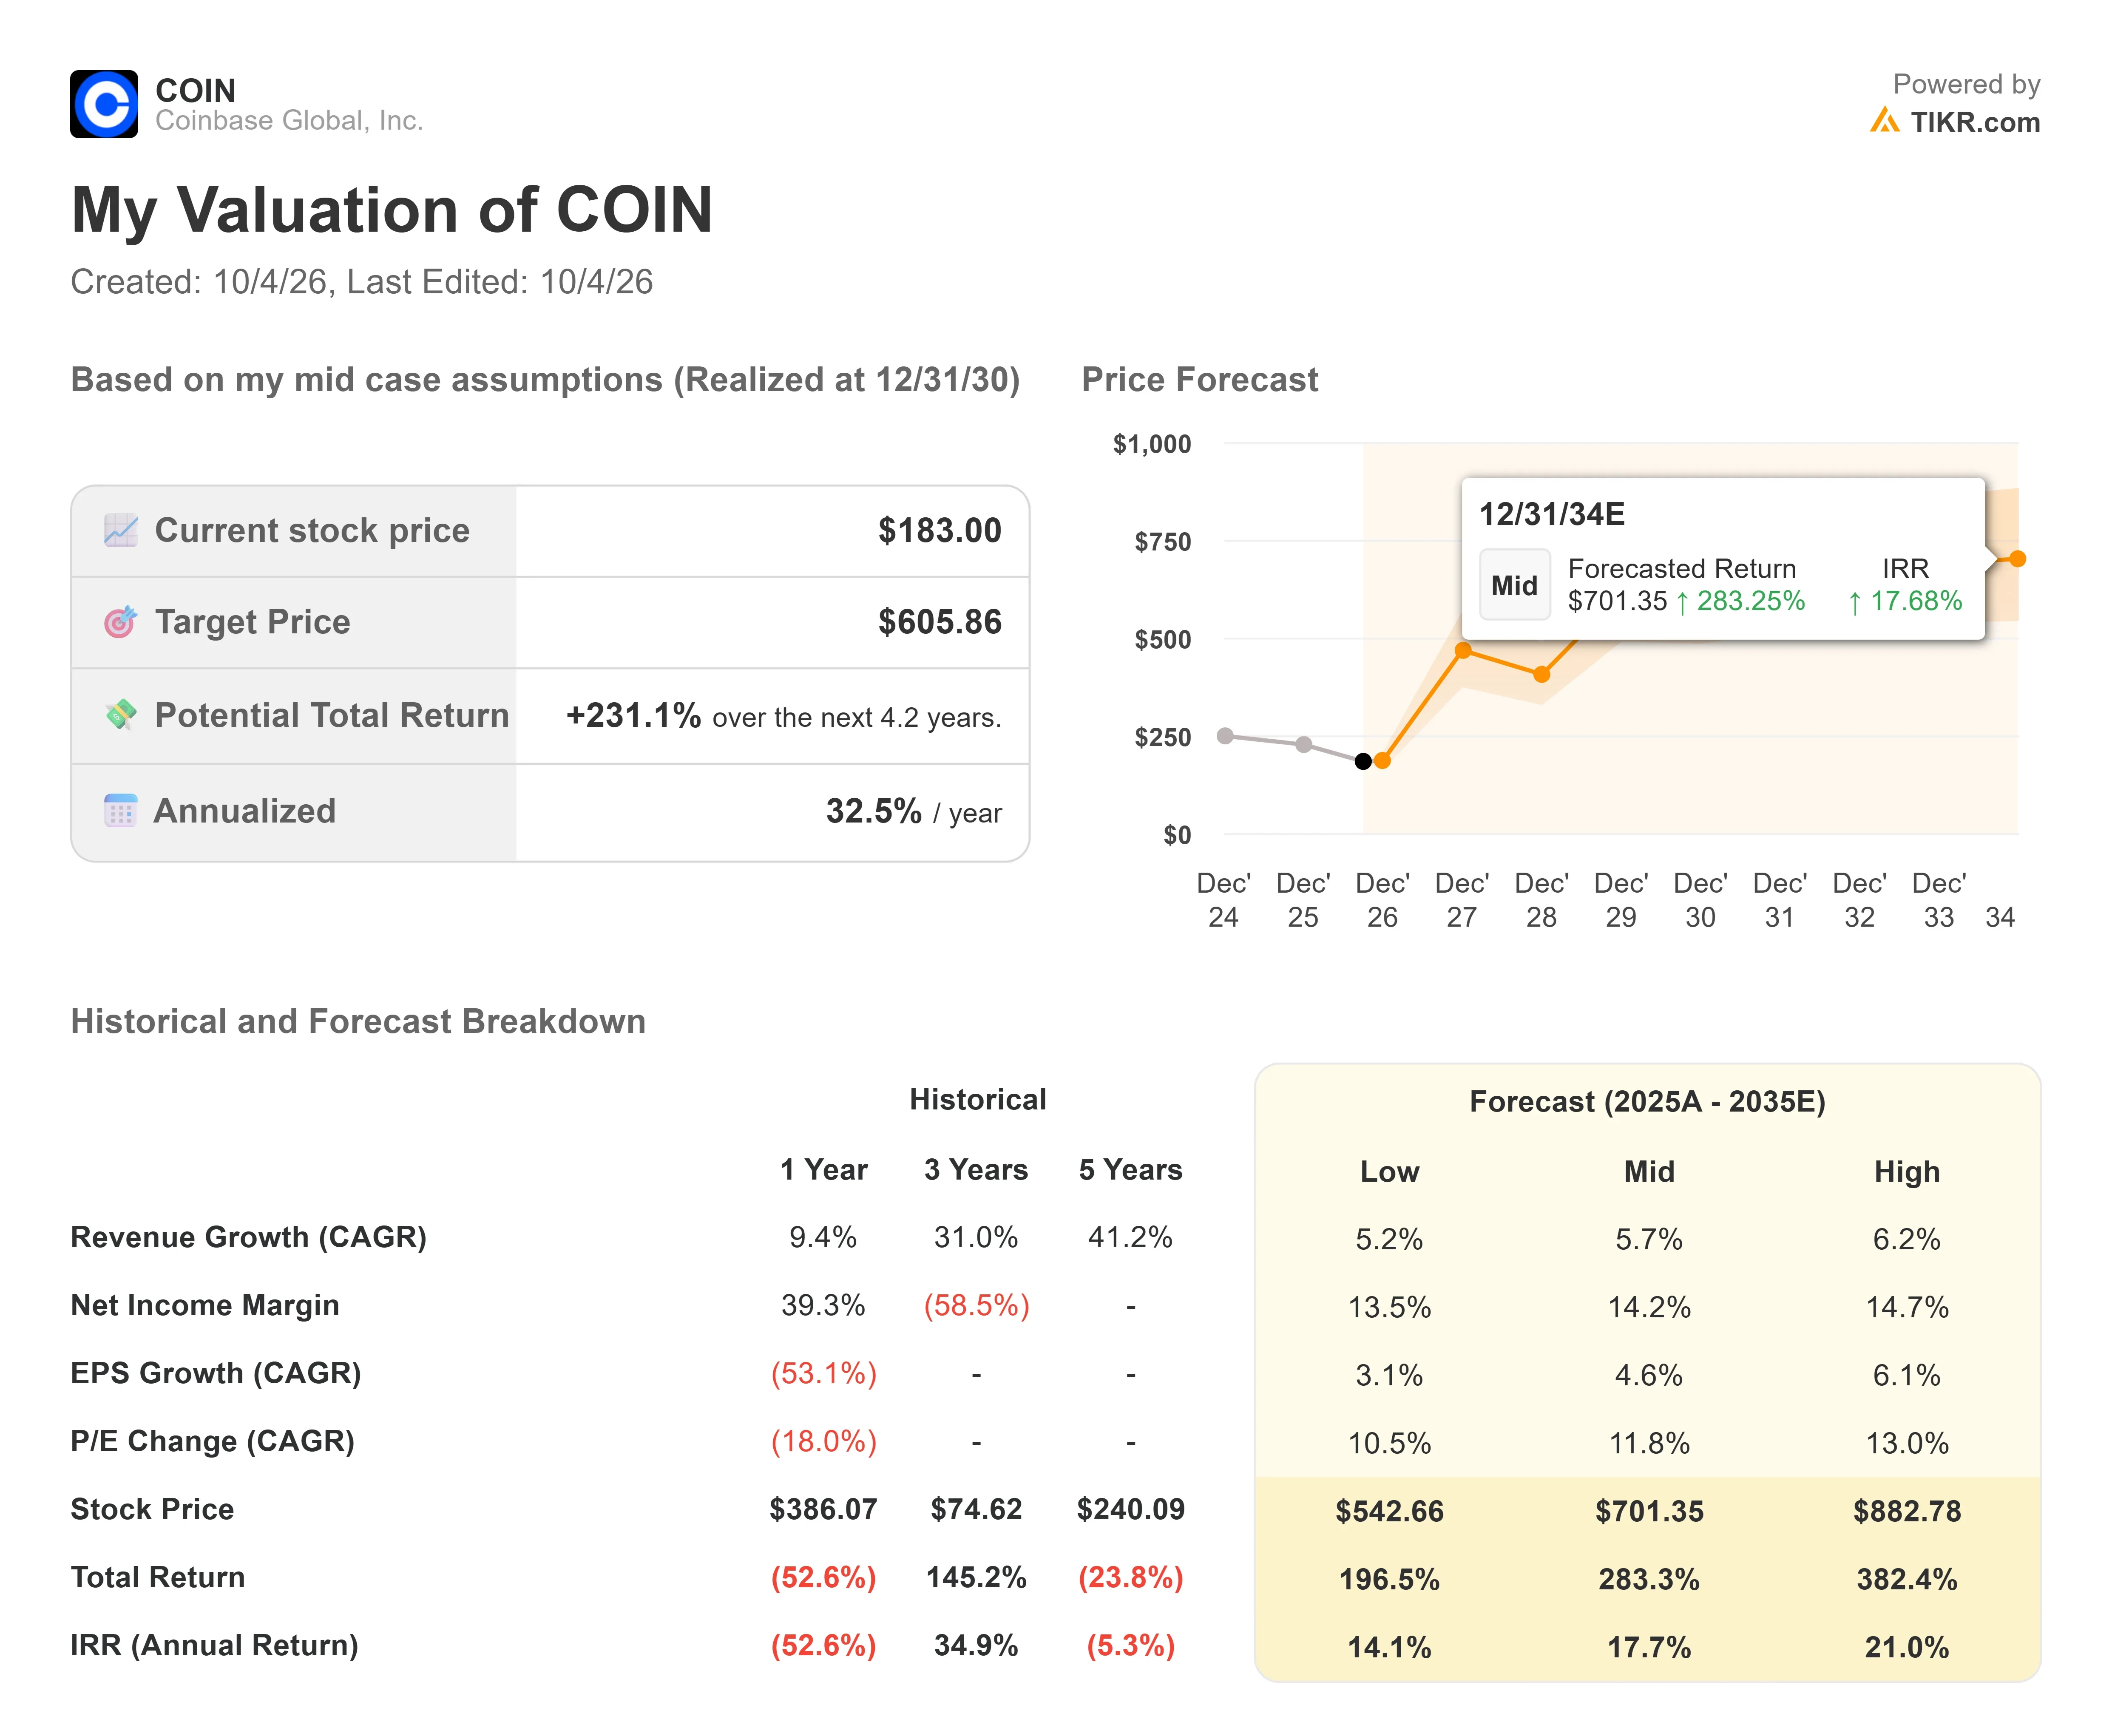
- Current Price: $183.00
- Target Price (Mid): ~$606
- Potential Total Return: ~231%
- Annualized IRR: ~33% / year
See analysts’ growth forecasts and price targets for Coinbase stock (It’s free!) >>>
The TIKR model’s mid case, the scenario on its summary card, values Coinbase at around $606 by December 31, 2030, a potential total return of about 231% from $183.00. As a cross-check, that price equals about 49 times the Street’s 2030 EPS estimate of roughly $12.50, well above the 33 times trailing earnings Coinbase traded at in September 2025.
Getting there requires earnings to swing from an expected 2026 loss to that level. The primary risk is Wells Fargo’s: activity returns without full revenue.
Upside: a volume rebound against a 2026 cost base held near 2025 levels pulls profit forward. Downside: only two analysts publish 2030 revenue forecasts, and a lower multiple would cut the target sharply. The figure is a scenario.
Conclusion
Coinbase has not announced the date, though last year’s third-quarter results came on October 30. Revenue above the roughly $1.2 billion consensus, with expenses tracking 2025 levels, would favor Haas. A miss that is led by consumer spot revenue would favor Wells Fargo.
See what stocks billionaire investors are buying so you can follow the smart money with TIKR.
So what is Coinbase stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Coinbase could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Analyze Coinbase on TIKR Free →
Looking for New Opportunities?
- See what stocks billionaire investors are buying so you can follow the smart money.
- Analyze stocks in as little as 5 minutes with TIKR’s all-in-one, easy-to-use platform.
- The more rocks you overturn… the more opportunities you’ll uncover. Search 100K+ global stocks, global top investor holdings, and more with TIKR.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!


