Key Takeaways
- Zurn Elkay shares fell 11% today because its fourth-quarter sales outlook of $430 million to $437 million outweighed 9% sales growth and an 18% dividend raise in the third quarter.
- The sell-off looks like an overreaction, since the company is still guiding to sales growth and double-digit profit growth.
- The fourth-quarter guidance points to sales growth of 6% to 7%. It also calls for adjusted EBITDA of $120 million to $123 million, up from $104 million a year ago.
- CEO Todd Adams doesn’t expect the economy to help in 2027, so analysts’ revenue estimate of $1.97 billion for that year is the number to watch.
Zurn Elkay Water Solutions (ZWS) is down 11% today after a third quarter that beat on earnings and came with an 18% dividend raise. Not usually a sentence you expect to read!
What sank it was one line from CEO Todd Adams on the fourth quarter: “it feels like a time to be conservative in our assumptions while remaining aggressive with our actions with everything that’s happening in the world right now.”
TIKR tracks 10 analysts on Zurn Elkay Water Solutions. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Zurn Elkay Water Solutions, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Zurn Elkay Water Solutions’ Analyst Ratings
Nothing wrong with the quarter
Here’s what it reported after Tuesday’s close:
- Net sales rose 9% to $495 million, with core sales up 7% and the Intellihot acquisition adding 2 points.
- Adjusted EPS climbed to $0.52, from $0.43.
- Adjusted EBITDA margin widened 150 basis points to 28.3%.
That extends a long climb: Zurn Elkay’s EBITDA margin has risen every year since 2022, from 16.6% to 22.1% in 2025…

Bracing for 2027
Zurn Elkay guided to fourth-quarter net sales of $430 million to $437 million. That’s 6% to 7% above last year’s $407 million, and it includes Intellihot, which added 2 points on its own in the third quarter. So the core business looks set to slow.
On Wednesday’s call, Adams said “the broader economy and parts of our end markets do not feel like they are going to be a tailwind for our business in 2027.”
Profits are holding up, though: management guided to fourth-quarter adjusted EBITDA of $120 million to $123 million, up from $104 million a year ago, and expects more than $350 million of free cash flow this year.
The stock just got cheaper
Analysts expect revenue to grow from $1.85 billion this year to $1.97 billion in 2027…

Management still expects to grow in 2027, helped by the roughly $400 million of served market it says it added this year, so I’d expect any cuts to that 2027 number to be small.
And the stock already traded at 24x forward earnings before today, below its five-year average of 27x. After the drop, it’s closer to 22x, near the 21x low it hit in June 2022.
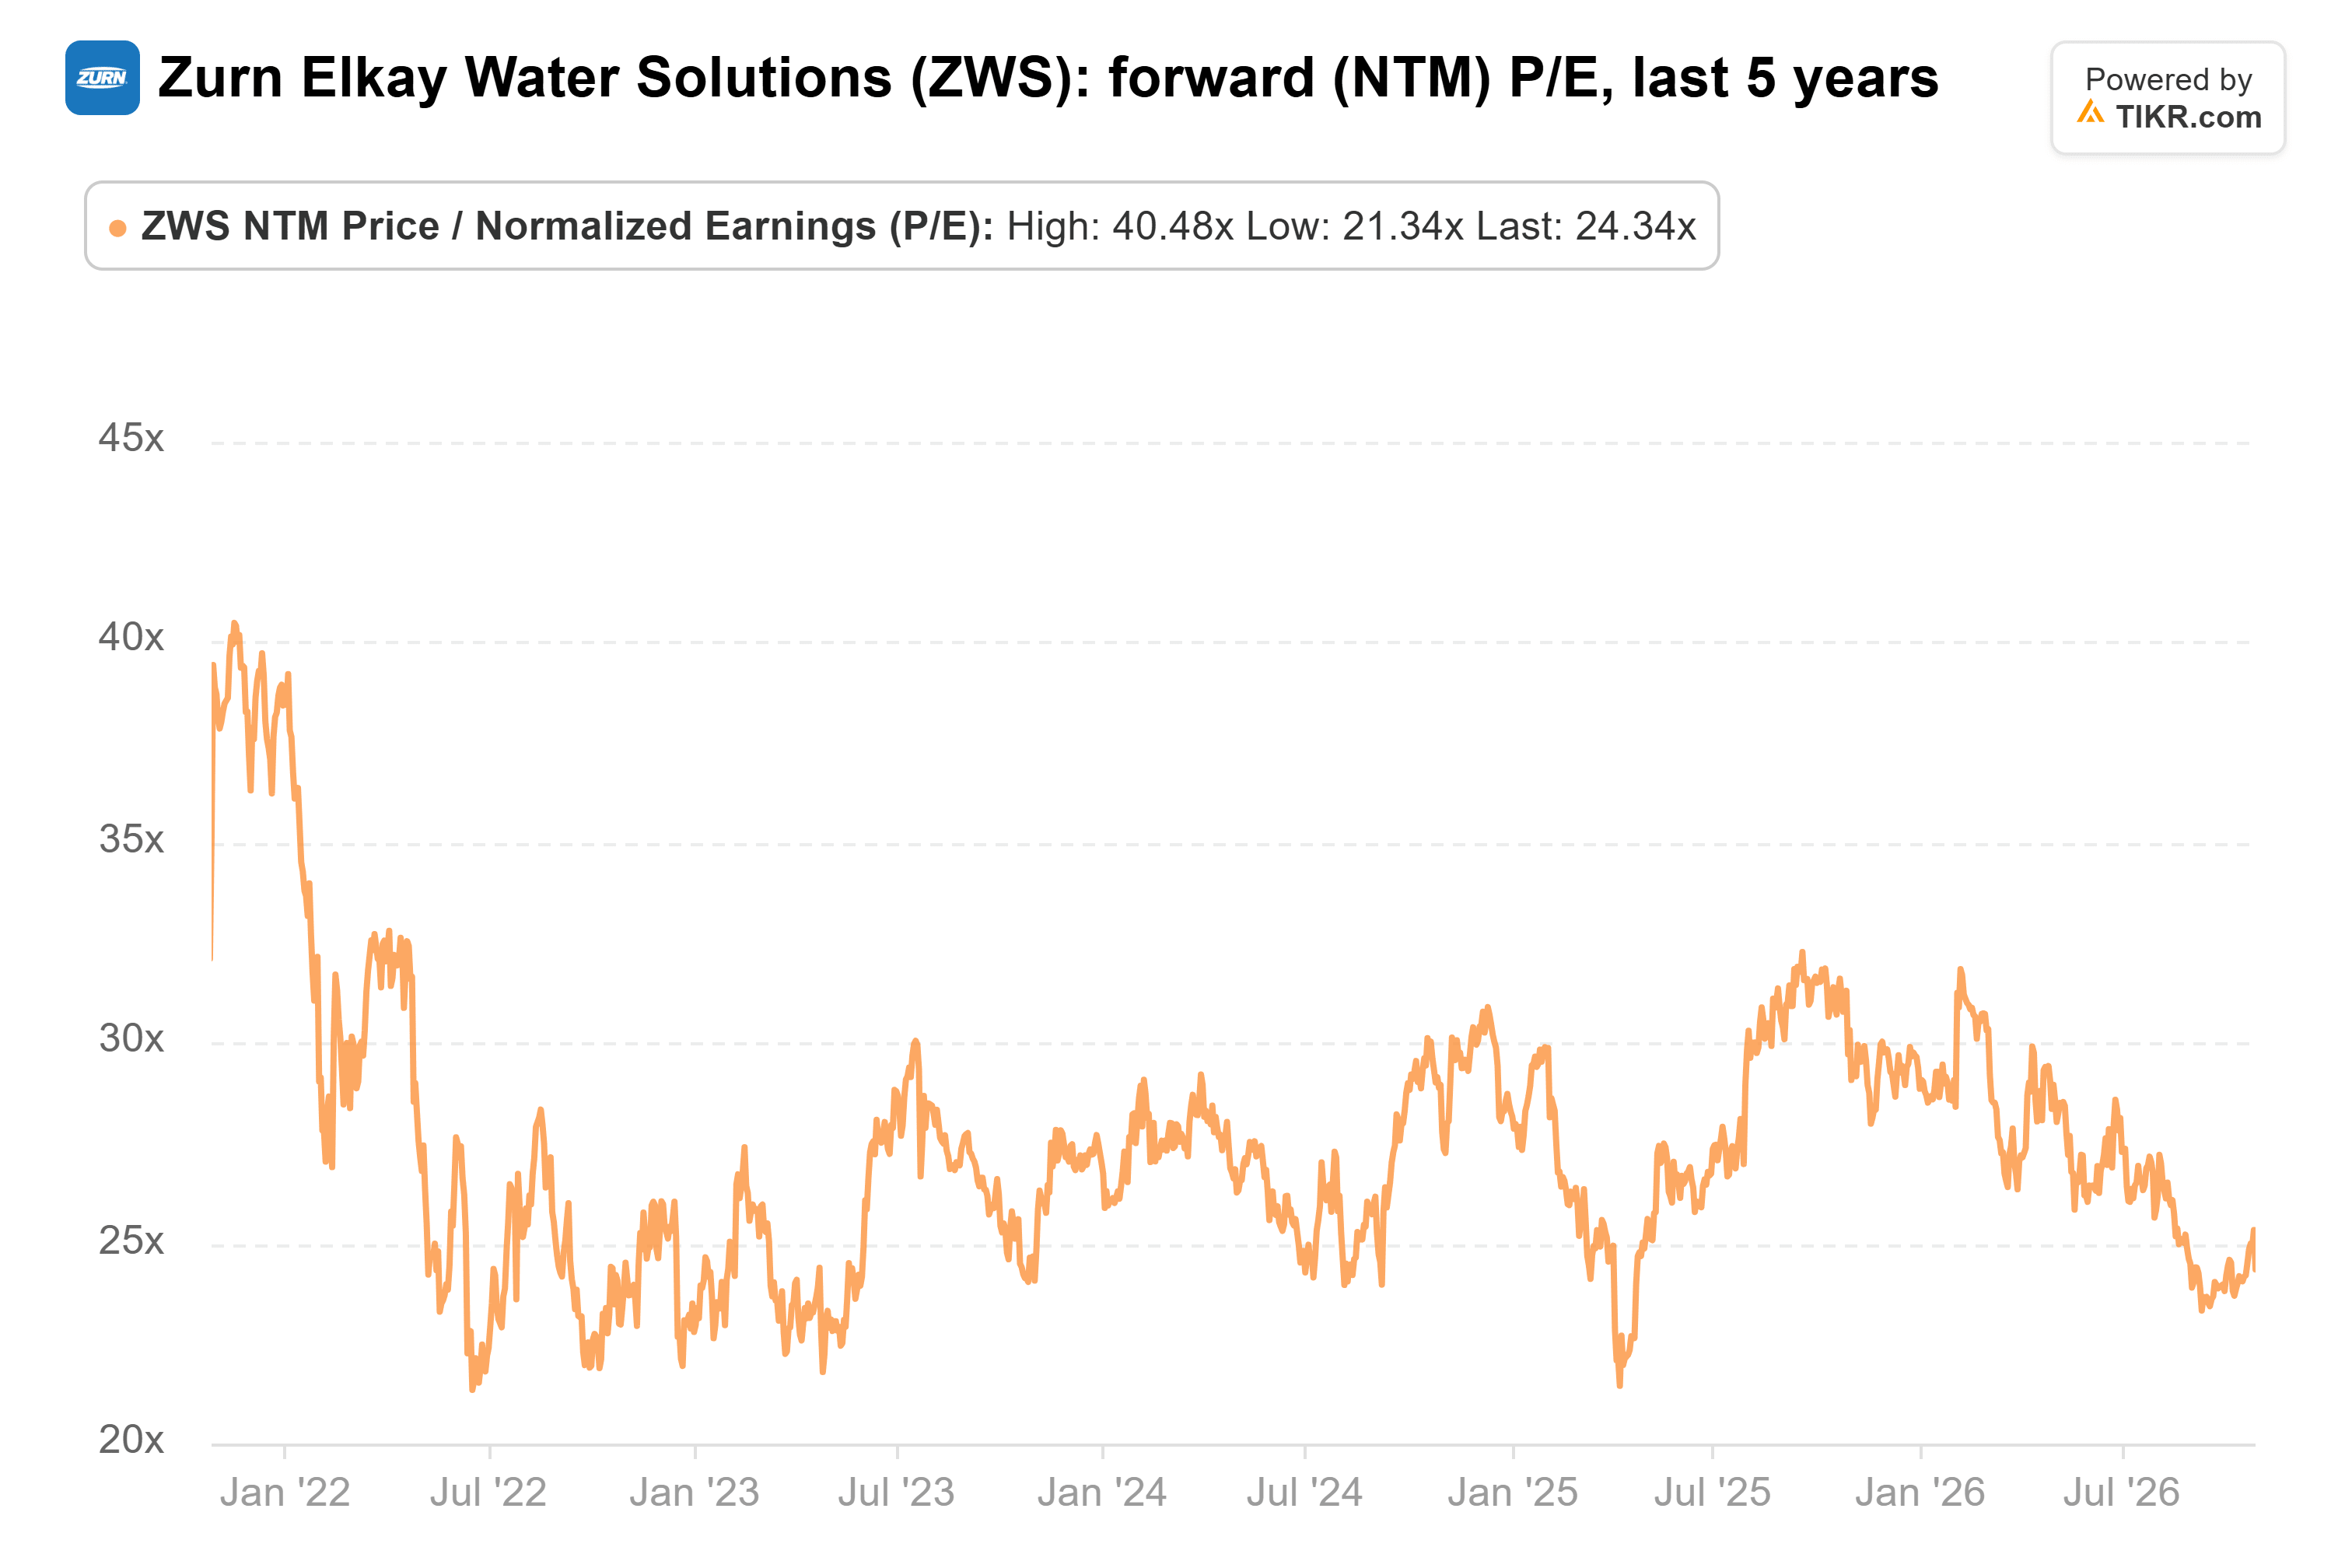
My take: a [10%] drop for a company still guiding to sales growth and double-digit profit growth looks like an overreaction, with the stock near the bottom of its five-year range.
Of course, the fourth-quarter report early next year should give a firmer read on 2027, and a weak one would test that view.
So what is Zurn Elkay stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Zurn Elkay could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!