Key Takeaways
- Tradr ETFs is closing its two leveraged funds on SK hynix’s US shares around Nov. 12, as appetite for the AI trade cools.
- SK hynix’s Oct. 28 report needs to show operating margin still rising above the second quarter’s 76%, which also tells Micron investors whether the memory boom is still going.
- Korean analysts expect a margin of about 78%, and RBC expects DRAM contract prices to rise 20% from the second quarter.
- At 3.1x forward earnings, the stock is priced for a peak, so a quarter that clears the bar gives stalled full-year estimates room to rise again.
Two leveraged funds tied to SK hynix (SKHY) are shutting down in the US just three months after they debuted, as the AI trade loses steam.
That makes Wednesday’s third-quarter report the first hard data on whether the memory boom is still accelerating, for SK hynix and for Micron (MU), which rides the same cycle.
What happened
Tradr ETFs said it will liquidate its 2X long and inverse SK hynix funds around Nov. 12. Both launched on July 28, weeks after SK hynix listed its ADRs, and their combined assets have shrunk more than 60% from the peak to about $1.3 million, Bloomberg reported.
The money is small, but it fits the mood: SK hynix’s Seoul-listed shares are down 56% from their record high.
Not everyone thinks the boom is over. RBC said on Monday that SK hynix is positioned to benefit from a prolonged memory upcycle, with AI demand still outpacing supply. And Intel’s Pushkar Ranade said on the Dwarkesh Podcast that “the world will eat up as much compute as can possibly be made and it’ll eat up as much memory as can possibly be made.”
TIKR tracks 16 analysts on SK hynix. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on SK hynix, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See SK hynix’s Analyst Ratings
Watch the margin
SK hynix’s 2026 surge came from price far more than volume. DRAM prices rose in the mid-60% range in the first quarter on flat bit shipments, then about 30% more in the second. With costs largely fixed, about 90% of the second quarter’s revenue gain over a year earlier reached operating profit.
Operating margin went from 41% in the second quarter of 2025 to 72% in the first quarter of 2026 and 76% in the second.
Micron has made the same climb: its cloud memory unit’s operating margin went from 46% to 78% in the year to its fiscal third quarter. And the leverage works just as hard in reverse when prices fall.
The bar for Wednesday
Management guided DRAM bit shipments up about 10% this quarter, and RBC expects DRAM contract prices to rise 20% from the second quarter. The Korean consensus compiled by FnGuide has operating profit at ₩77.0 trillion, a margin of about 78%.
A margin above 76% with DRAM prices up by double digits again says the upcycle is still extending. A flat margin, or a single-digit DRAM price gain, would be the first sign that pricing has peaked.
The full-year estimates need even more: they imply about ₩168 trillion of operating profit in the second half, against ₩98 trillion in the first. And those estimates have gone quiet. The 2026 EPS consensus is up 12% since June 30, but less than 1% since Sept. 30.
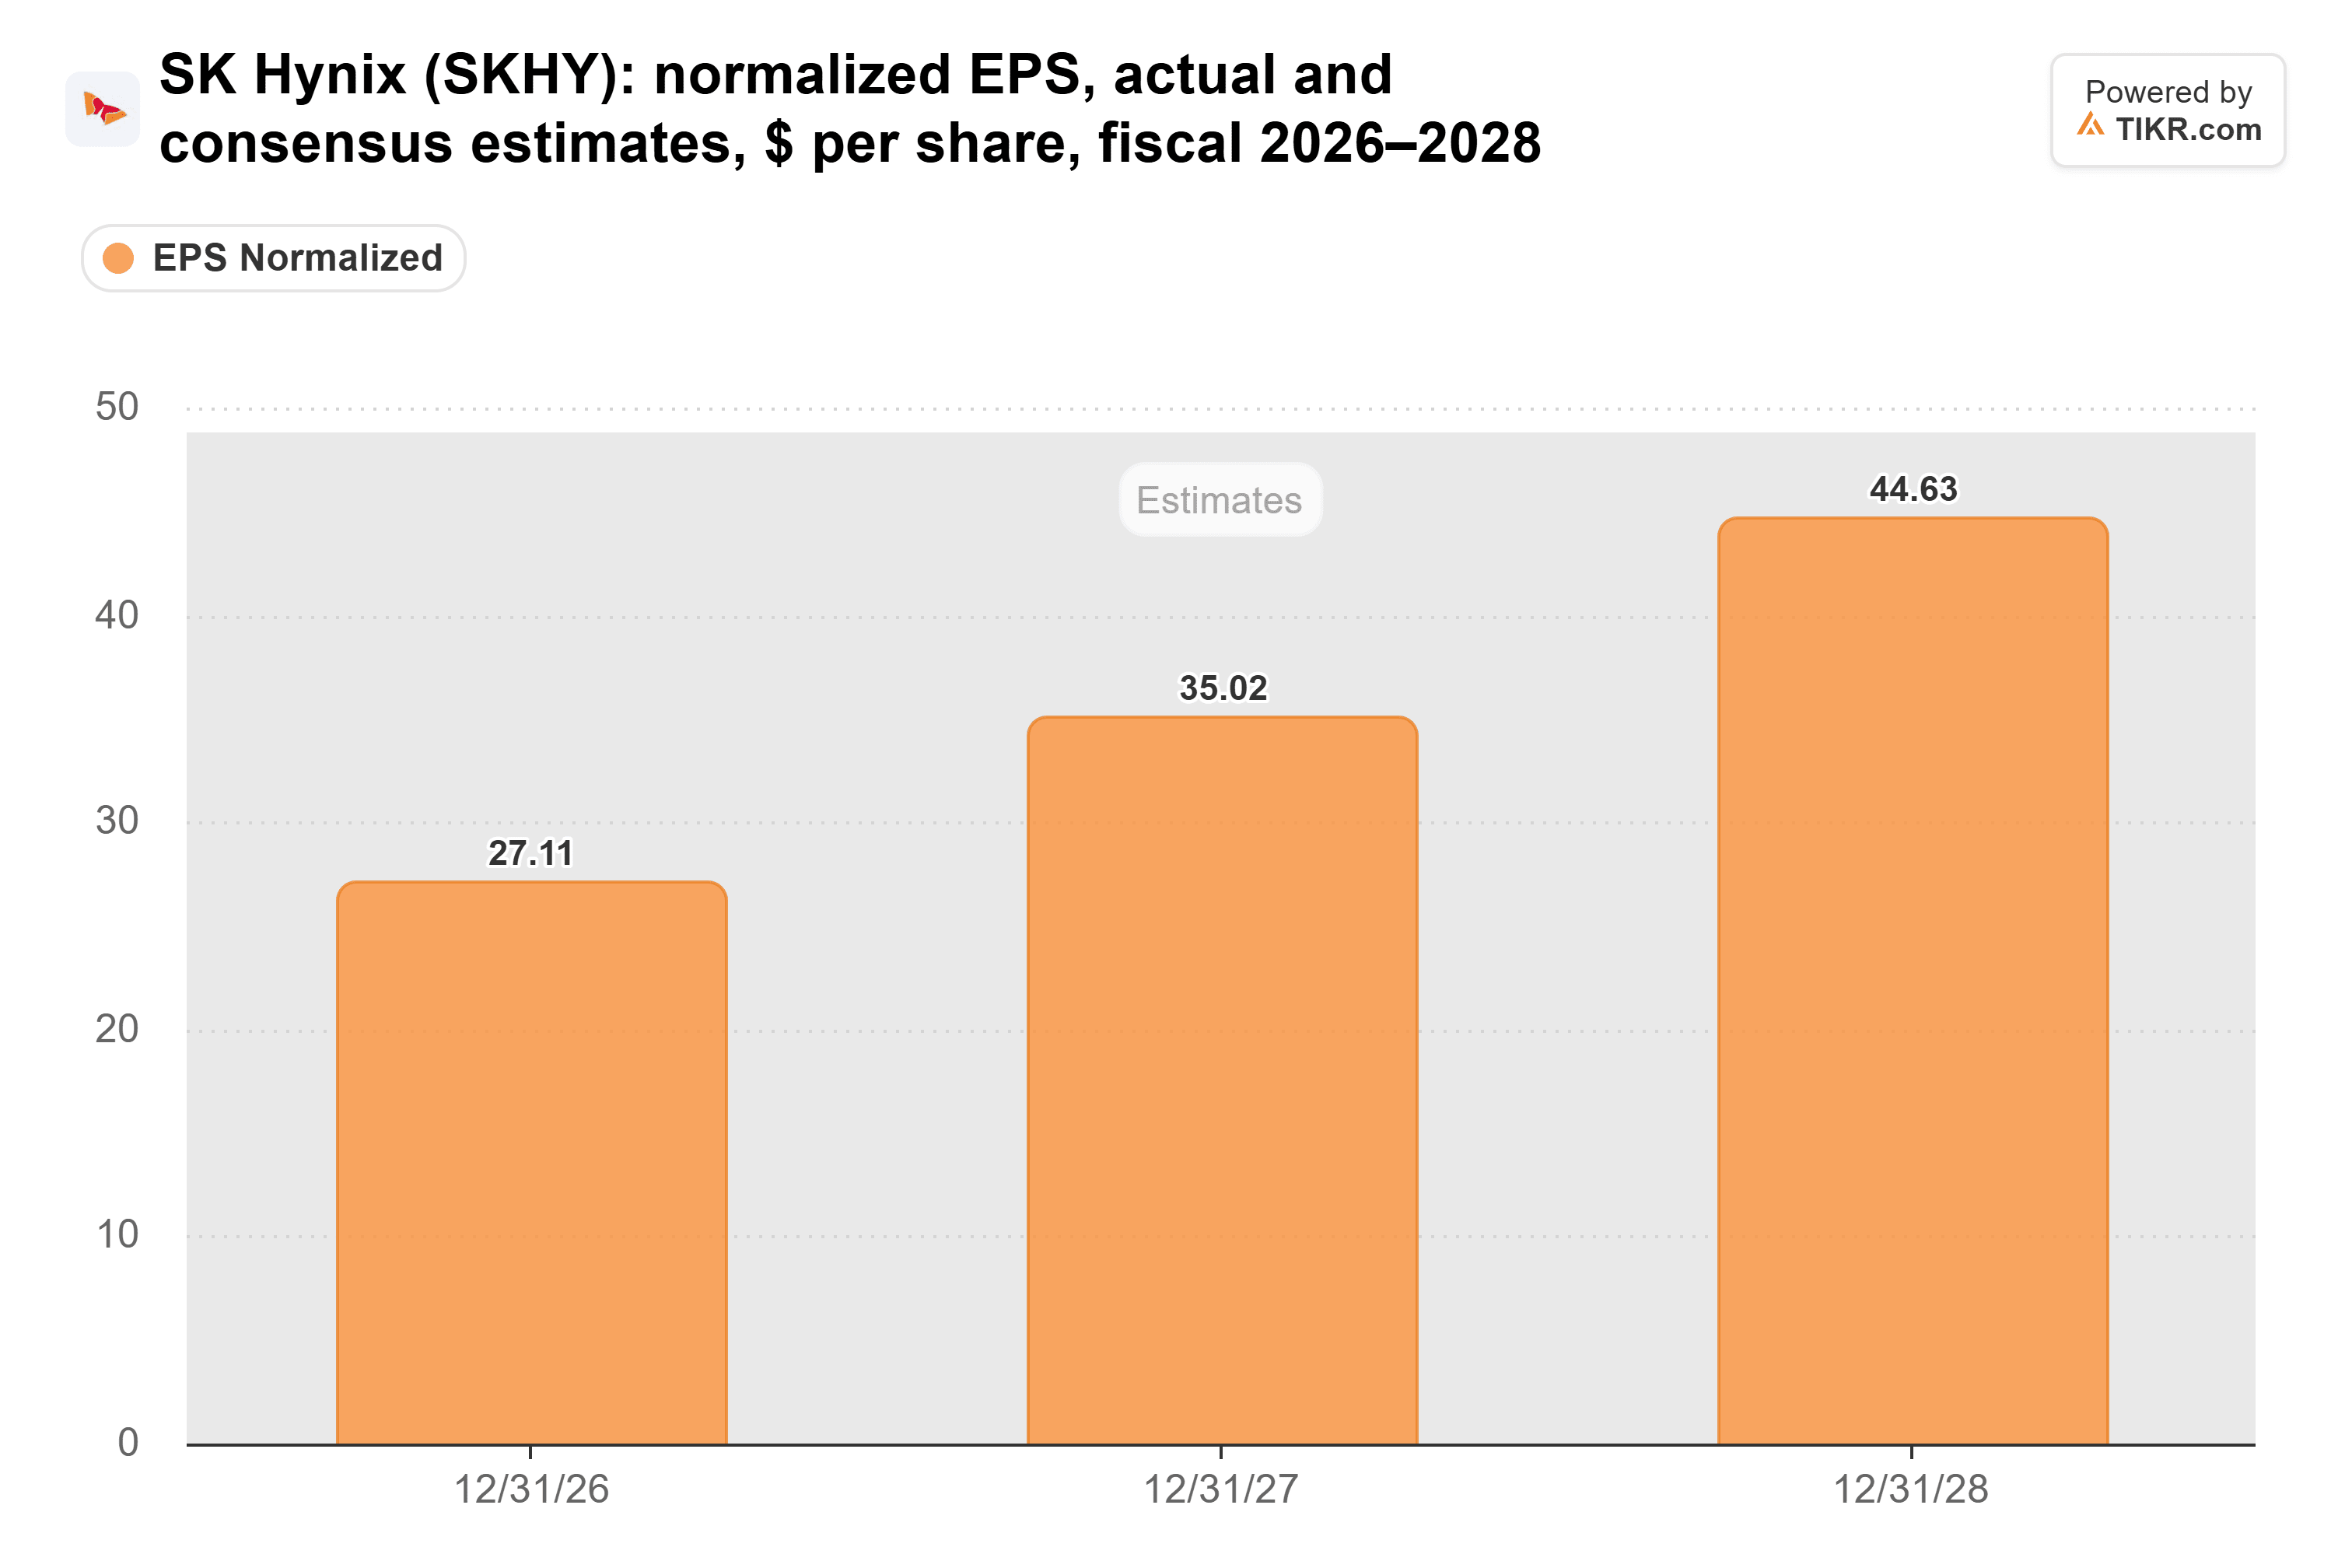
Analysts expect $27.11 per ADR this year and $35.02 in 2027. On the Korean shares, they expected 2026 EPS of ₩53,224 a year ago; now it’s ₩354,500. A rising quarter gives that number room to climb again, and a stalled one puts it at risk.
Priced for the peak
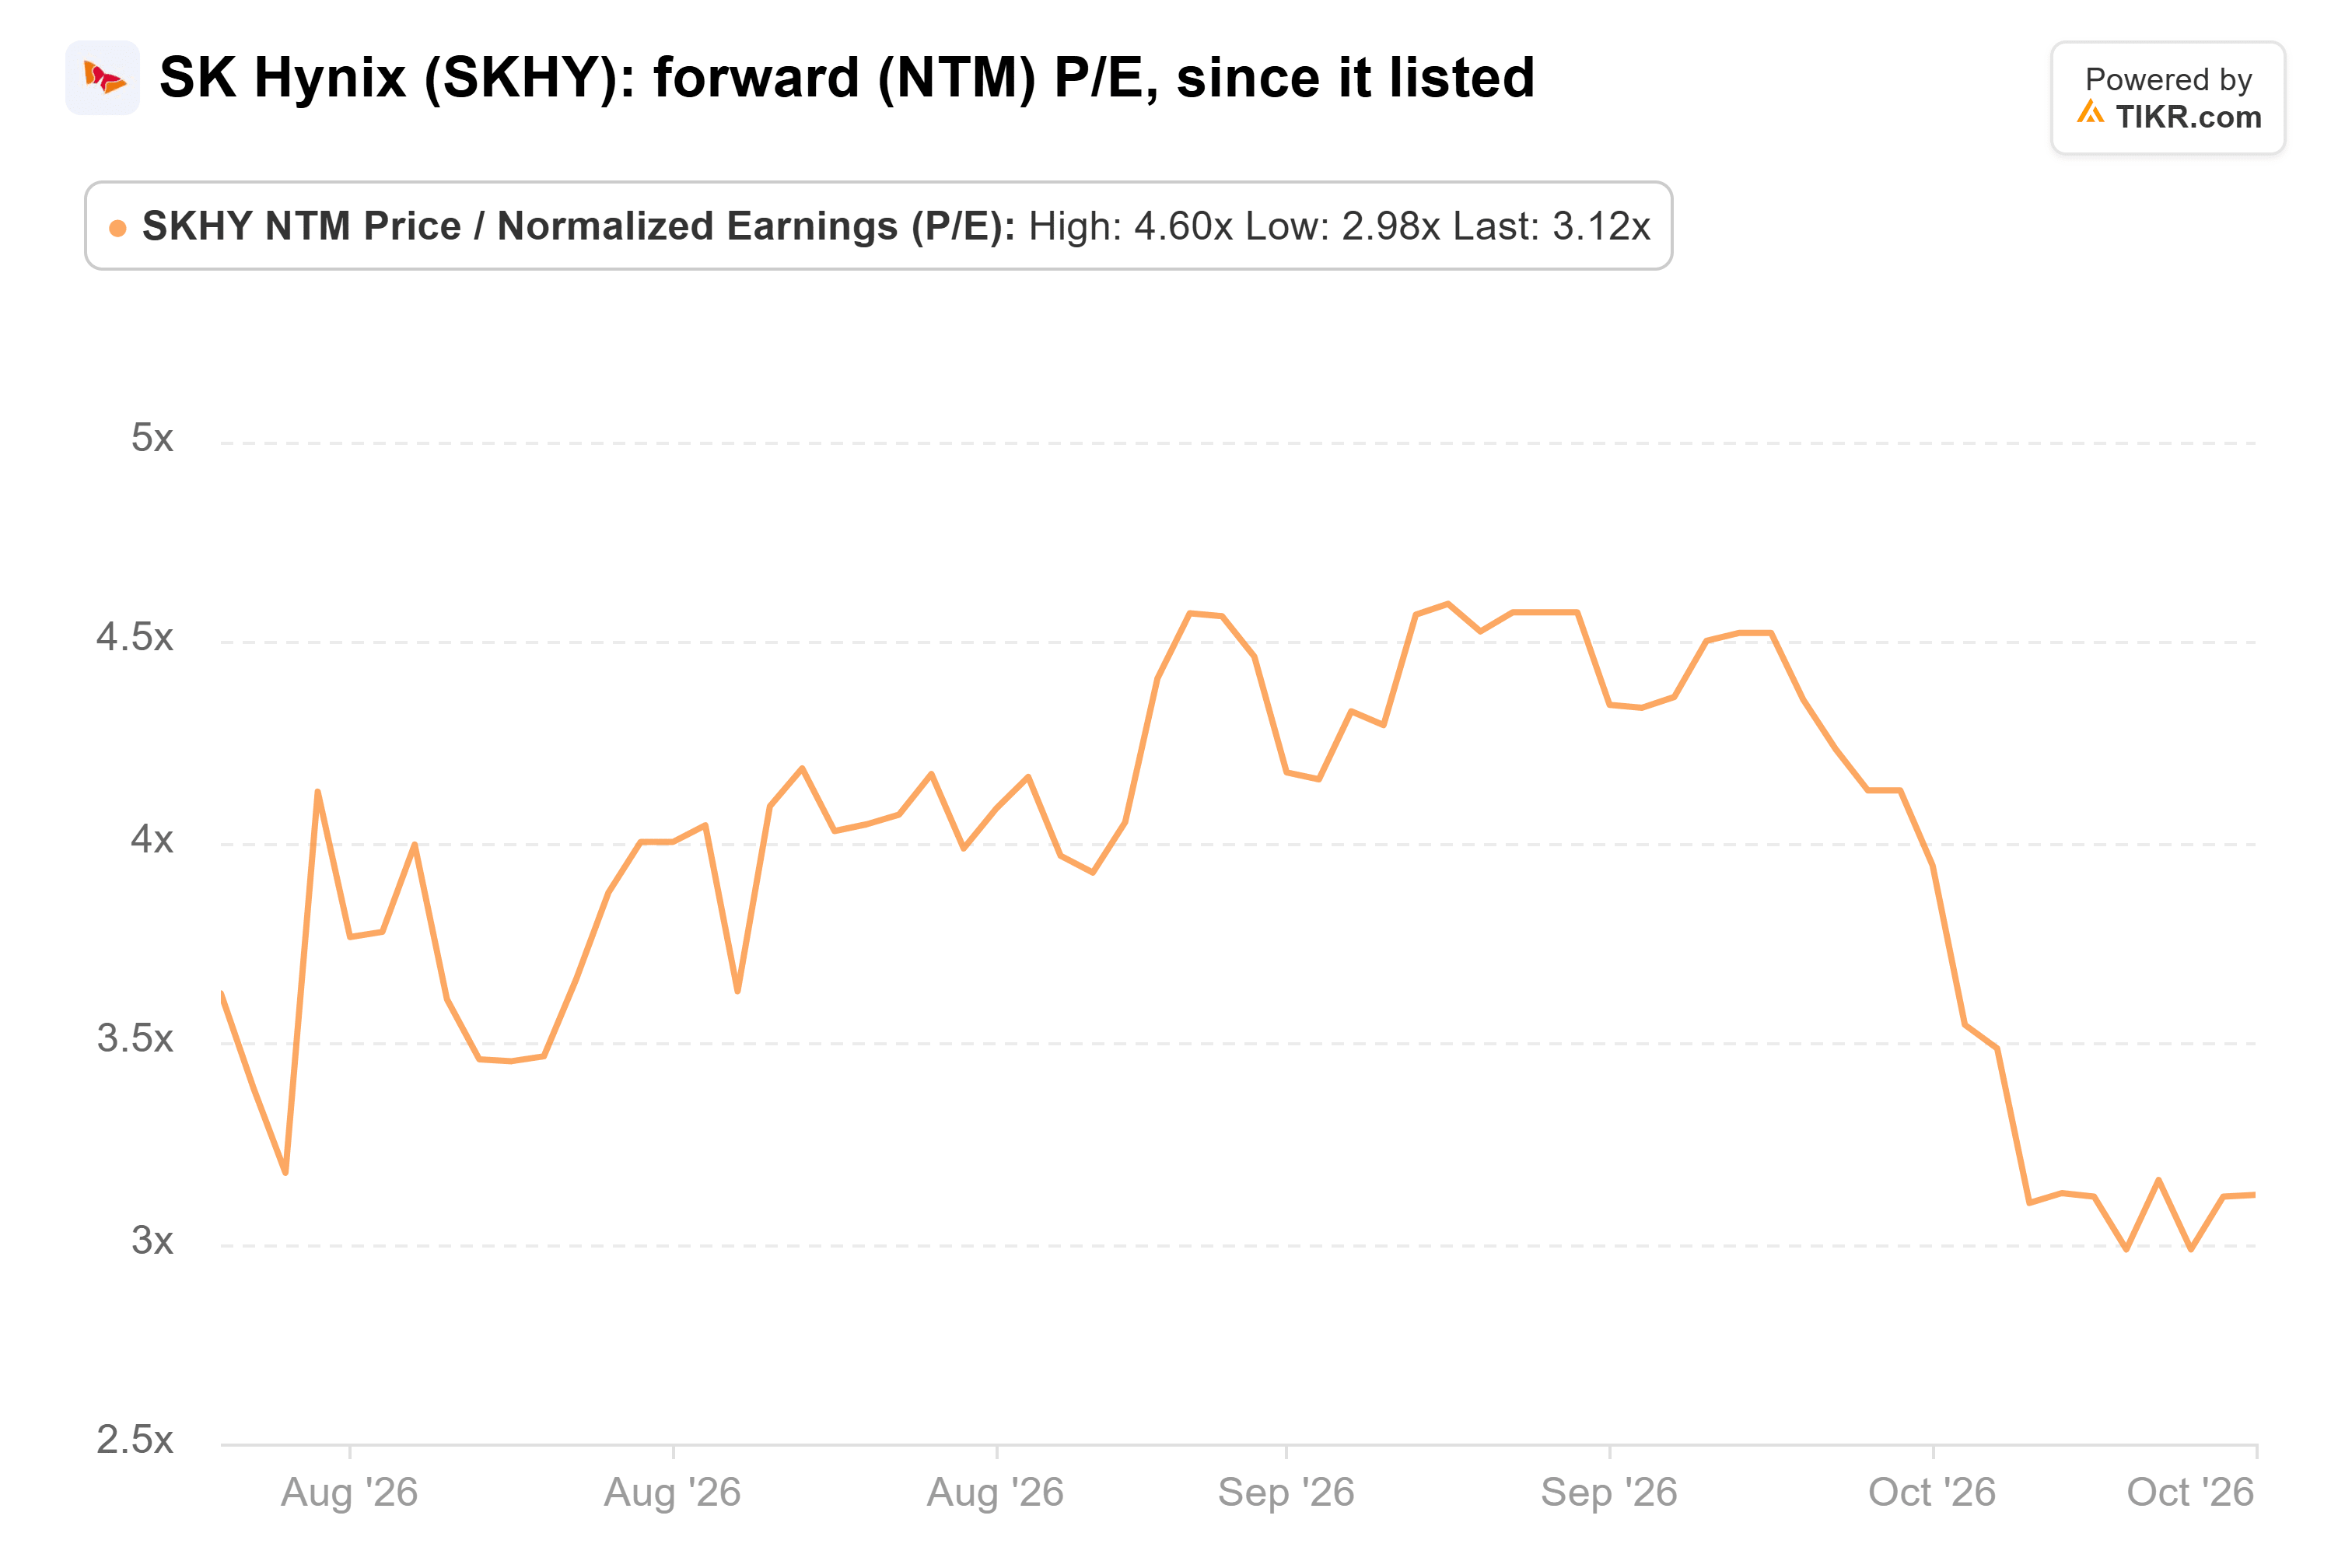
SK hynix’s ADRs trade at 3.1x forward earnings, below their 4.0x average since listing and near the 3.0x low of Oct. 20.
The Korean shares’ longer record says the same: the multiple is near the bottom of its range since 2014, close to its 2018 readings, just before operating profit fell 87% in 2019.
The payout news could still steal Wednesday’s headlines: SK hynix has confirmed it will announce new shareholder returns with the results, after Dong-A Ilbo [reported](LINK NEEDED) a special dividend of about ₩16 trillion. But a payout that size would come out of the gain on selling down its Kioxia stake, so it tells you nothing about next year’s memory prices.
My take: at 3.1x, the market is pricing a cliff. But management says customers’ HBM demand for the next three years far exceeds its capacity, and its first new Yongin cleanroom doesn’t open until February 2027. A margin above 76% on Wednesday would make that look too gloomy.
Of course, one quarter won’t settle the cycle: SK hynix hasn’t given 2027 HBM prices yet, and management has said conventional DRAM prices may sway them.
So what is SK hynix stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what SK hynix could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!