Key Takeaways
- New Oriental shares fell 12% today: fiscal first-quarter revenue rose 23%, but net income rose only 13.5%.
- The operating margin slipped to 20.0% from 20.4% because the lower-margin East Buy e-commerce business brought in a bigger share of revenue. The CFO called this an expected result of scaling new businesses.
- The education business and East Buy each widened their own operating margins, so the CFO’s explanation holds up.
- New Oriental kept its full-year forecast of 14% to 18% revenue growth, which implies about 11% to 16% growth for the rest of the year.
New Oriental Education & Technology Group (EDU) shares are down 12% today after fiscal first-quarter revenue jumped 23.1% but net income rose just 13.5%.
The margin slip came from East Buy (1797.HK), New Oriental’s livestreaming e-commerce arm, which is growing faster than the education business on thinner margins. Chief Financial Officer Stephen Zhihui Yang called it “an anticipated consequence of scaling new businesses.”
What Held Back New Oriental’s Profit
New Oriental reported results for the quarter ended Aug. 31 before today’s open:
- Revenue: $1.87 billion, up 23.1%
- Operating income: $374.7 million, up 20.5%
- Operating margin: 20.0%, against 20.4% a year ago
- Net income: $273.2 million, up 13.5%
Yang said both the education business and East Buy widened their own operating margins, and East Buy’s bigger revenue share held the total back. Most of the gap down to net income came below the operating line: a $1.8 million investment loss against a $7.8 million gain a year ago, and other income falling to $15.3 million from $20.6 million. Taxes weren’t the problem: they rose to $105.2 million from $91.5 million, in line with pretax income, at a steady rate of about 27%.
The pause stands out, since New Oriental’s operating margin had climbed every year from a loss in fiscal 2022, the year China’s tutoring crackdown hit, to 11.4% in fiscal 2026 (the summer quarter runs well above the full year):

The Forecast Stayed Put
Executive Chairman Michael Yu said the quarter’s growth beat the company’s full-year guidance range. But New Oriental only confirmed that range: revenue of $6.45 billion to $6.68 billion in fiscal 2027 (which ends in May), up 14% to 18%.
After a 23% first quarter, that leaves roughly 11% to 16% growth for the other three quarters. Deferred revenue, up 11.2% to $2.12 billion, also points to a slower pace.
TIKR Tracks 20 Analysts on New Oriental Education & Technology Group. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on New Oriental Education & Technology Group, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See New Oriental Education & Technology Group’s Analyst Ratings
Going into the report, analysts expected normalized EPS to climb about 21% this fiscal year, to $4.32:
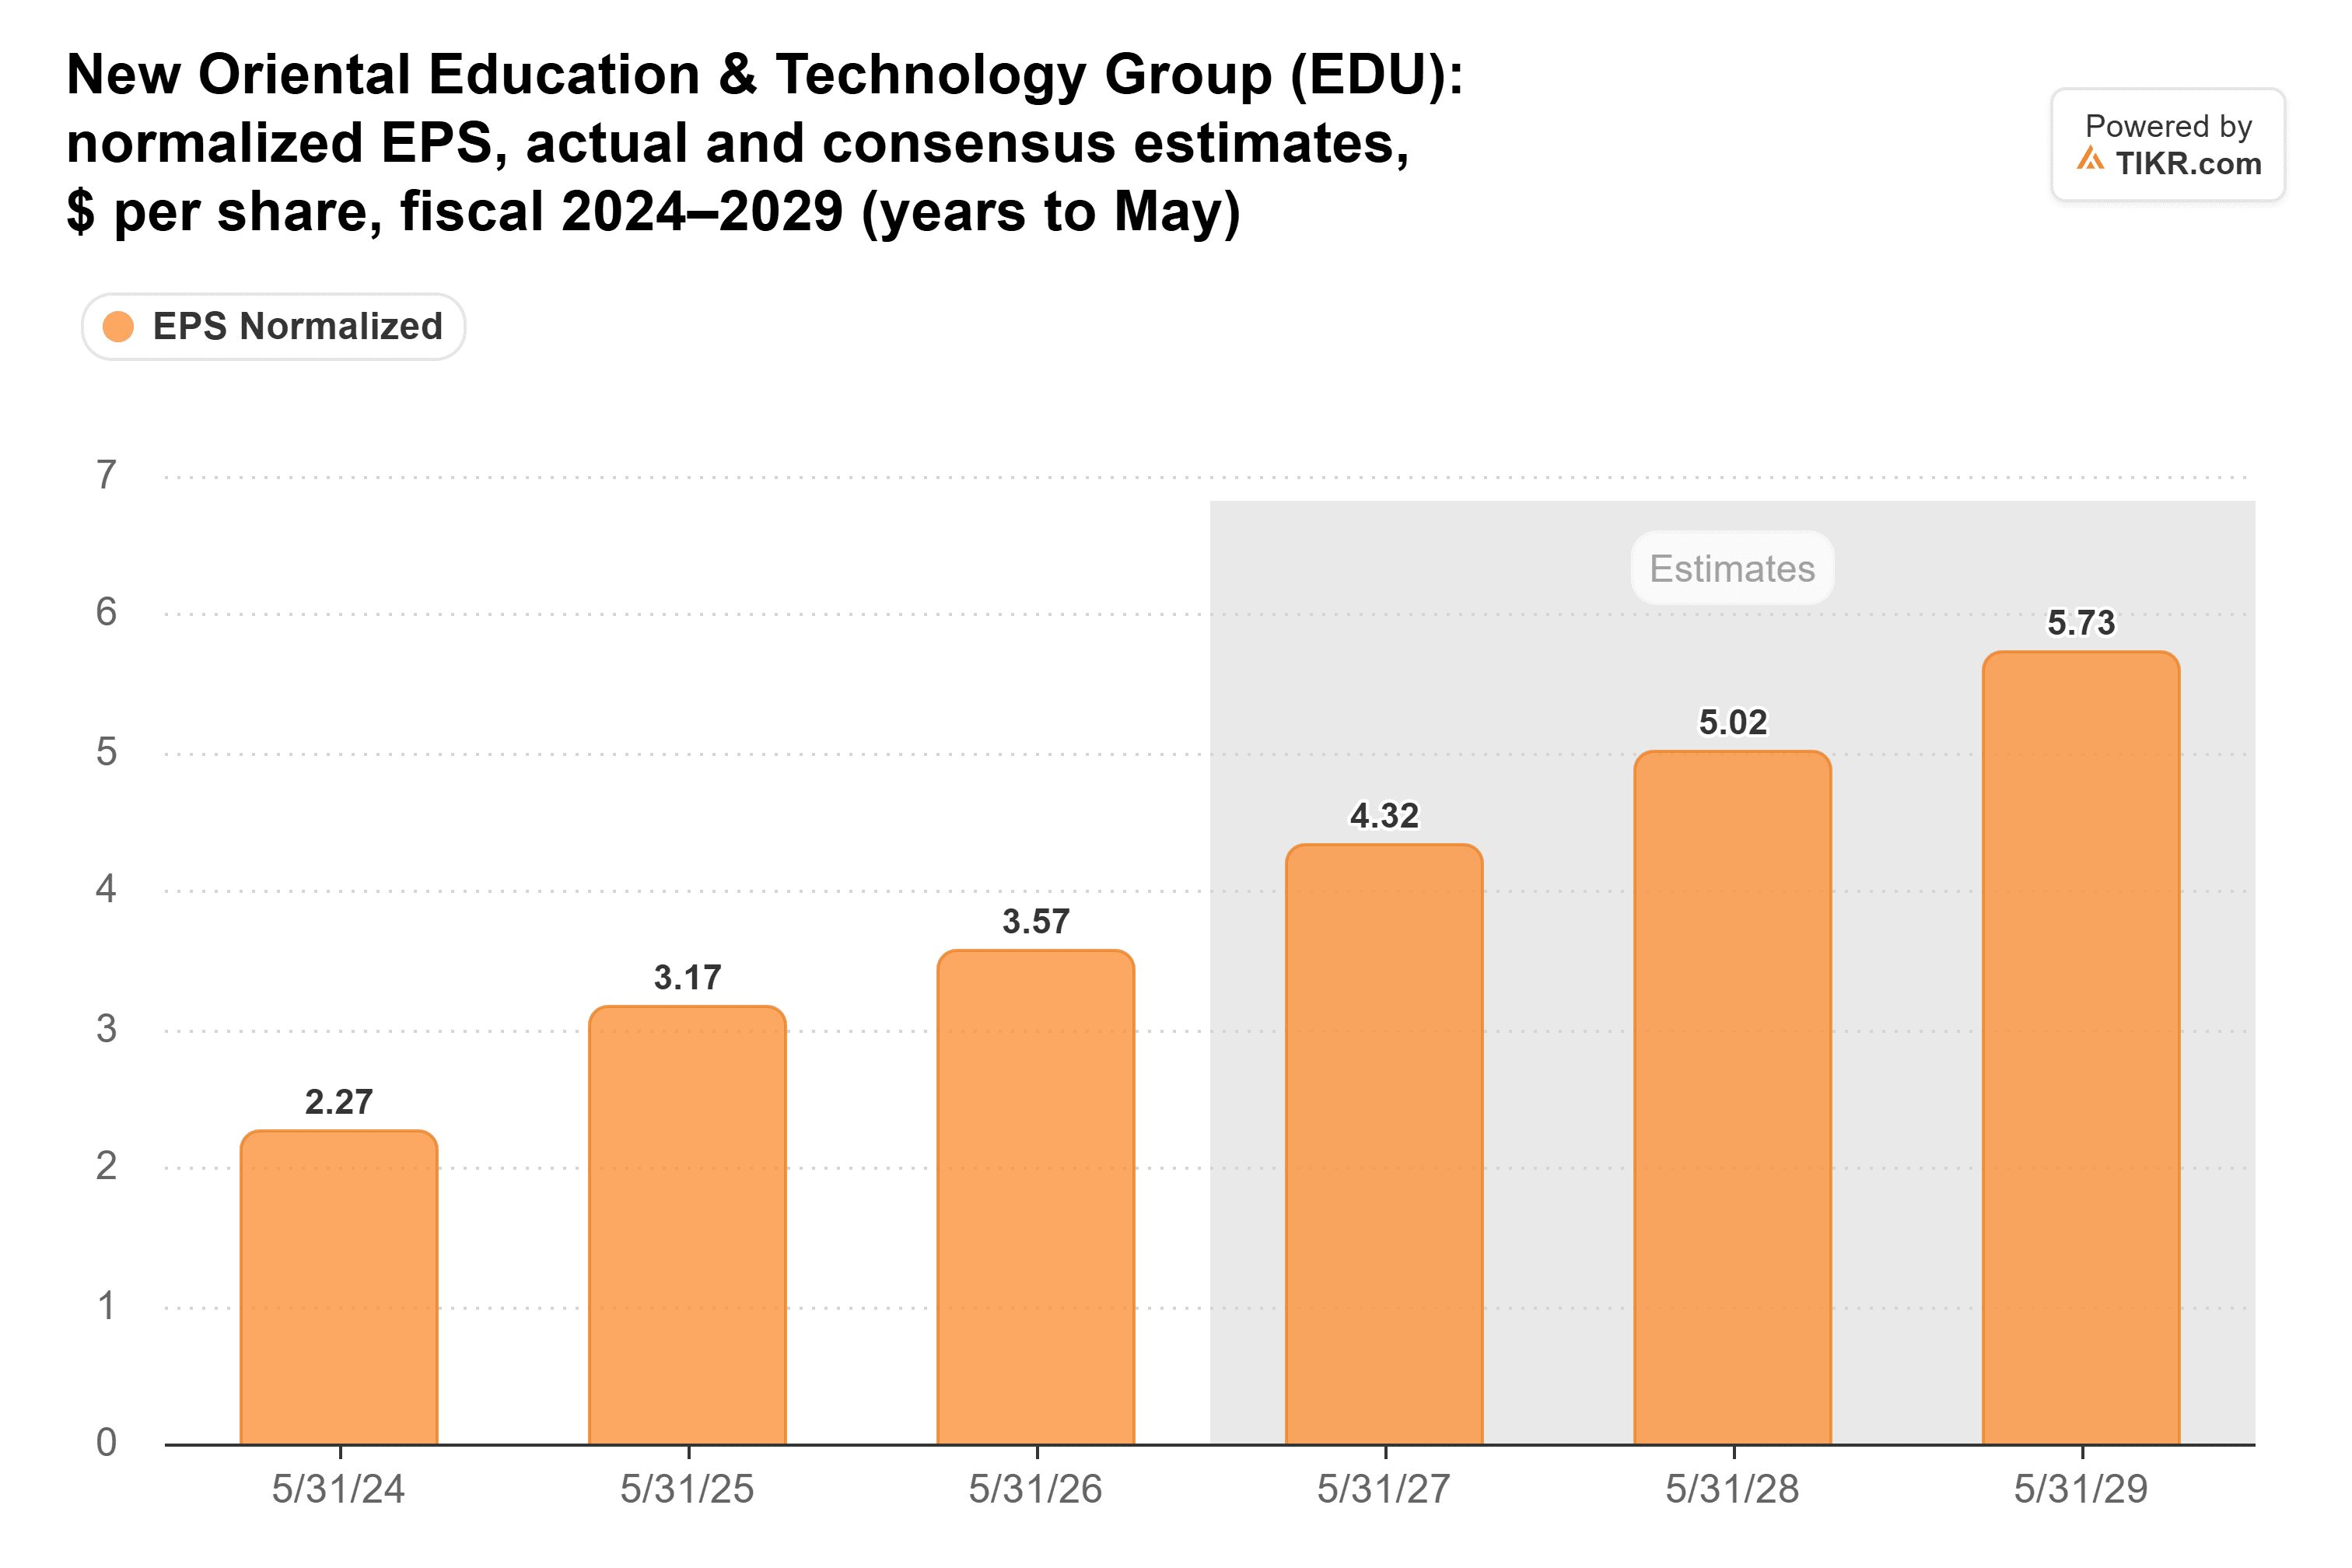
First-quarter non-GAAP EPS per ADS grew 18.7%, a little short of that pace, so I’d expect small trims at most.
New Oriental Looks Cheap Enough to Wait For
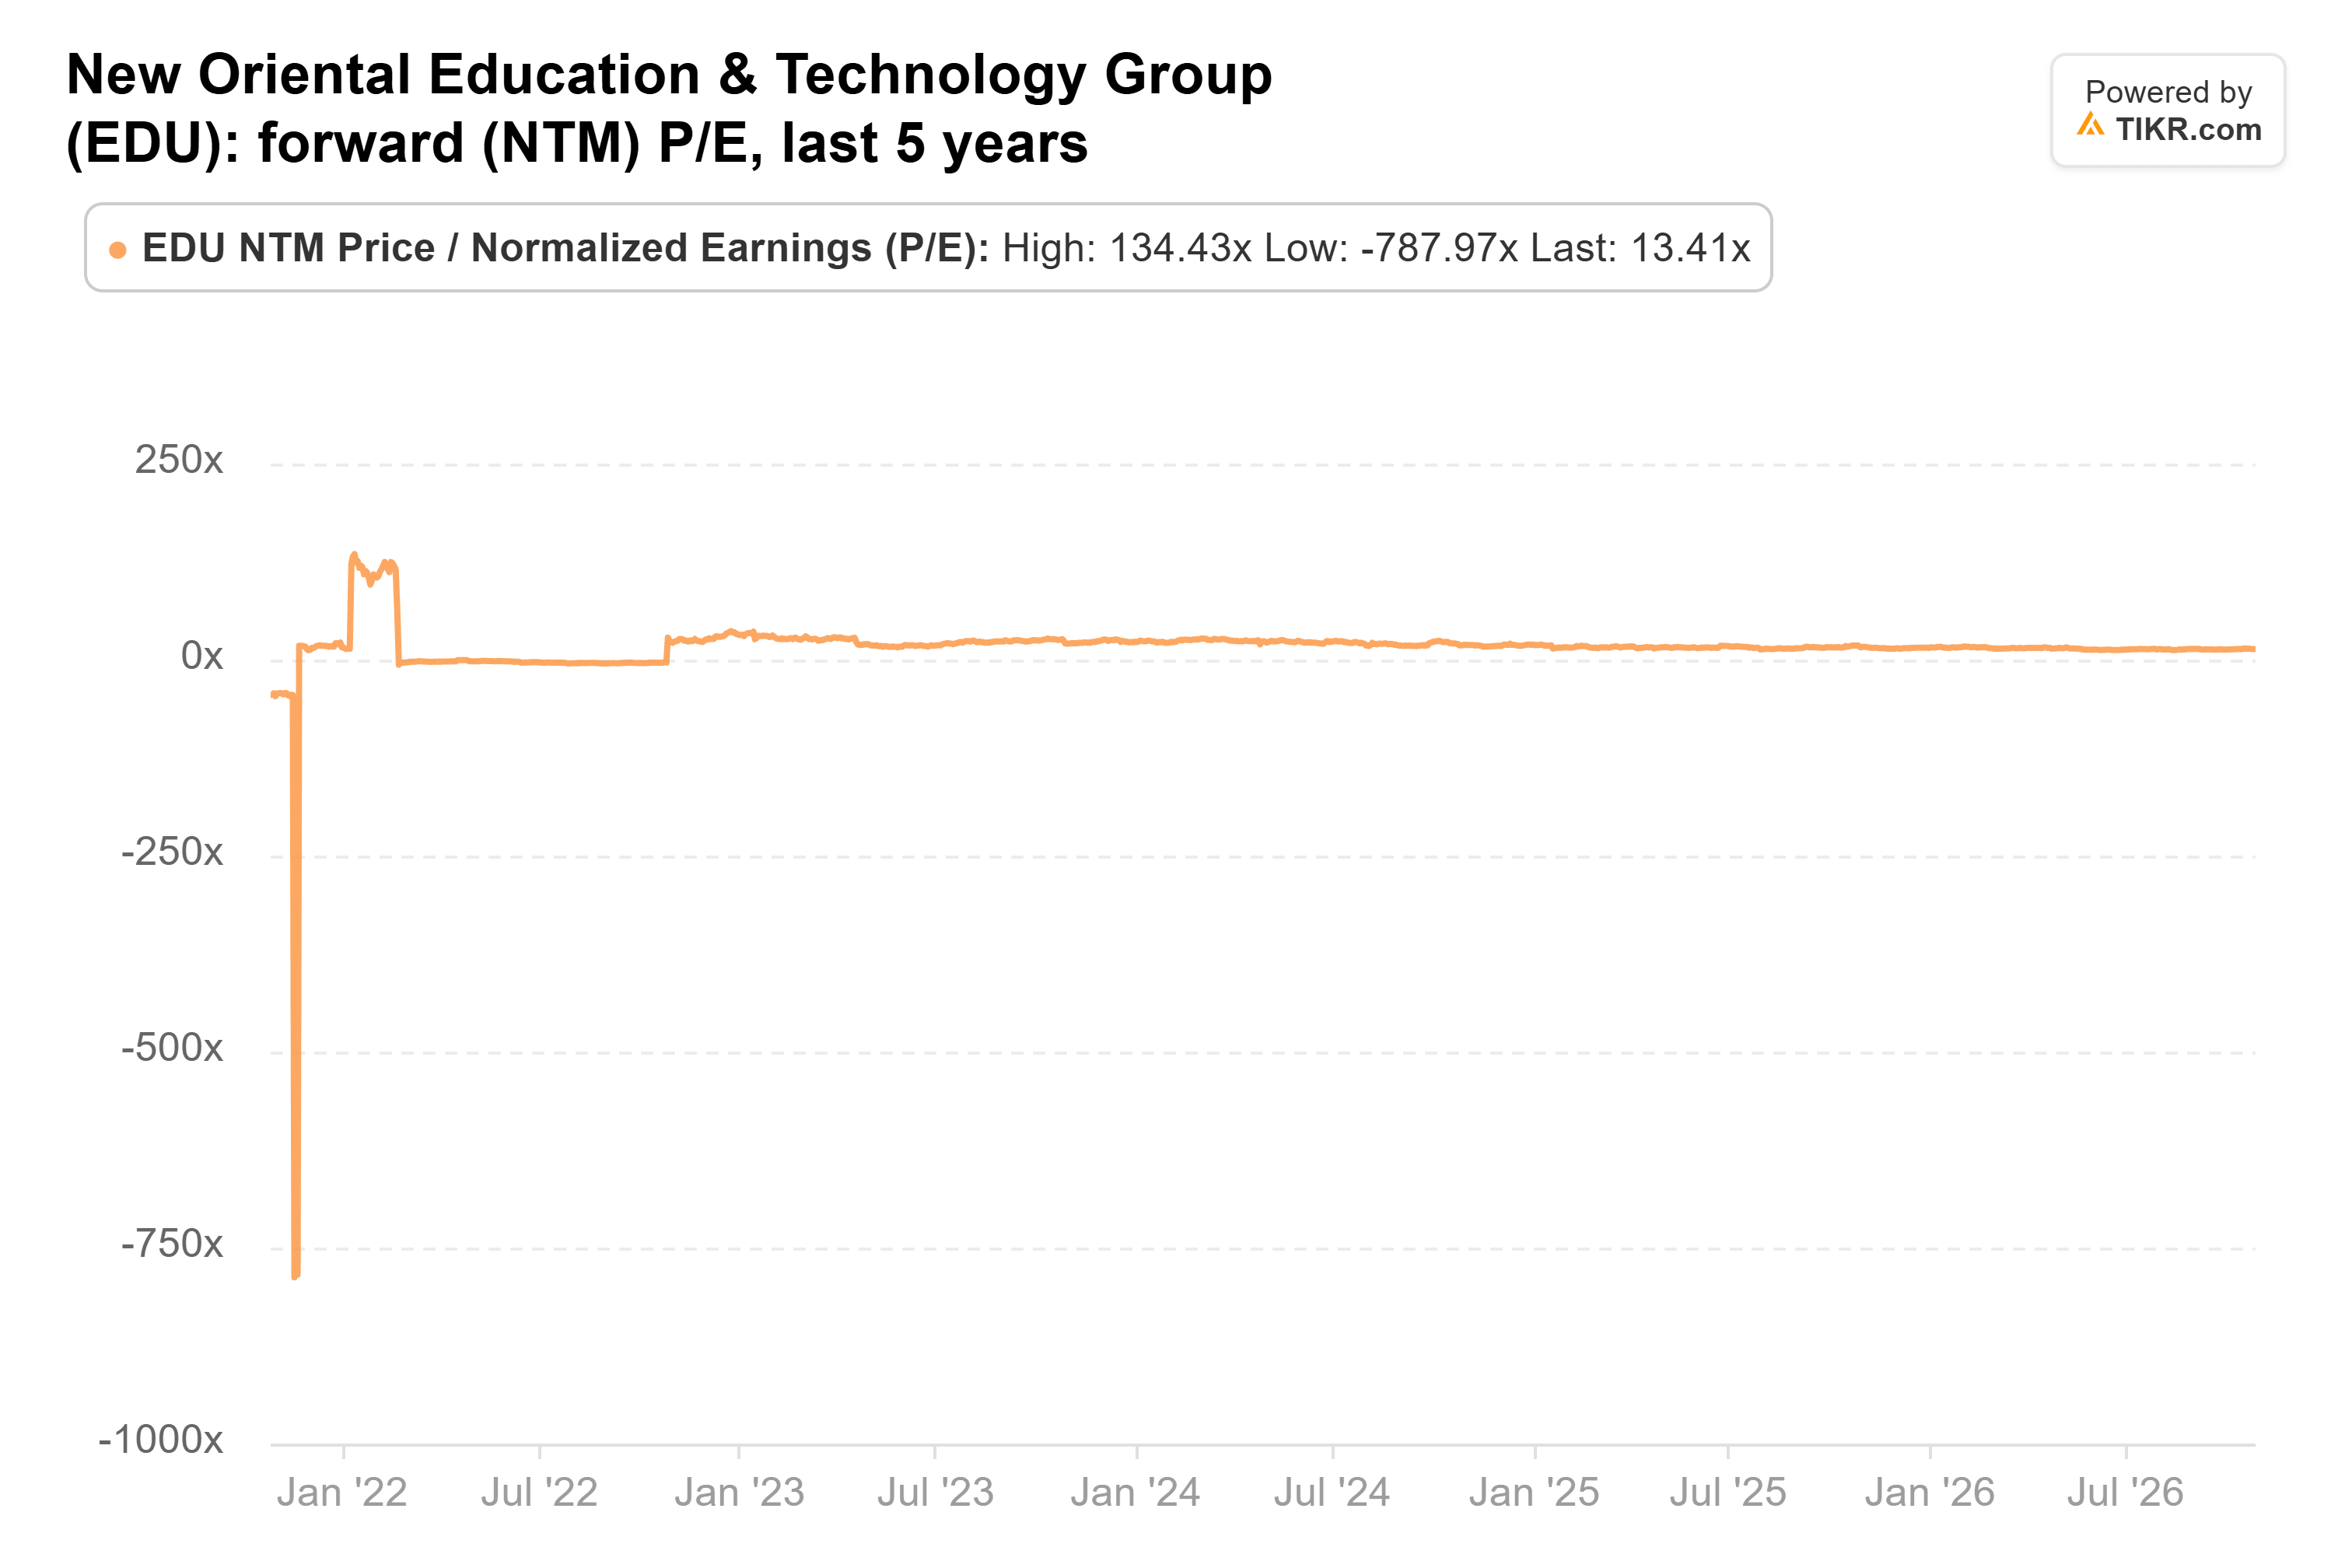
New Oriental traded at 13x forward earnings at Tuesday’s close and about 12x after today’s drop, against a five-year average of 16x:
By Oct. 27, New Oriental had used up its $300 million buyback, and a new $200 million program is ready to go, alongside a $2.00-per-ADS dividend worth about $300 million.
Yang’s explanation holds up. Both businesses got more profitable, and a 0.4-point margin dip from the mix doesn’t justify a 12% drop. The real risk is the slowdown the forecast implies, and second-quarter results, likely in late January, will show whether it’s arriving.
So what is New Oriental stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what New Oriental could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!