Key Takeaways
- Nucor shares jumped 6% today after third-quarter sales of $11.25 billion beat the $10.79 billion consensus, while EPS of $5.80 came in 3 cents short.
- The earnings miss looks like noise, since higher steel prices and record mill shipments lifted EPS 20% from the second quarter’s adjusted figure.
- Nucor expects fourth-quarter earnings in line with or modestly higher than the third, which leaves analysts’ 2026 estimates looking beatable.
- Earnings go up and down with the steel cycle: Nucor’s normalized EPS fell by more than half from 2023 to 2025, so the stock needs steel prices to hold into 2027, when its West Virginia mill starts production.
Nucor (NUE) stock is up 6% today after third-quarter sales beat Wall Street’s estimate by about $460 million, even as earnings came in a hair short.
Management isn’t worried either: Nucor expects fourth-quarter earnings to be “generally in-line with or modestly higher than the third quarter.”
What exactly happened
Nucor reported after Monday’s close:
- Net sales of $11.25 billion, up 32% from a year ago and ahead of the $10.79 billion consensus
- EPS of $5.80, against the $5.83 consensus and $2.63 a year ago
- Steel mills pre-tax earnings of $1.79 billion, more than double the $793 million of a year ago
Three cents is a rounding error
Higher steel prices drove the quarter. Nucor’s mills got an average of $1,233 a ton from outside customers, up 19% from a year ago, on record shipments for the third straight quarter.
And EPS rose 20% from the second quarter’s $4.84 (which leaves out a gain on Nucor’s stake in Helion), even without that quarter’s $130 million refund on past raw material costs.
Sales are growing again, too: analysts expect $40.5 billion this year, up from $32.5 billion in 2025.
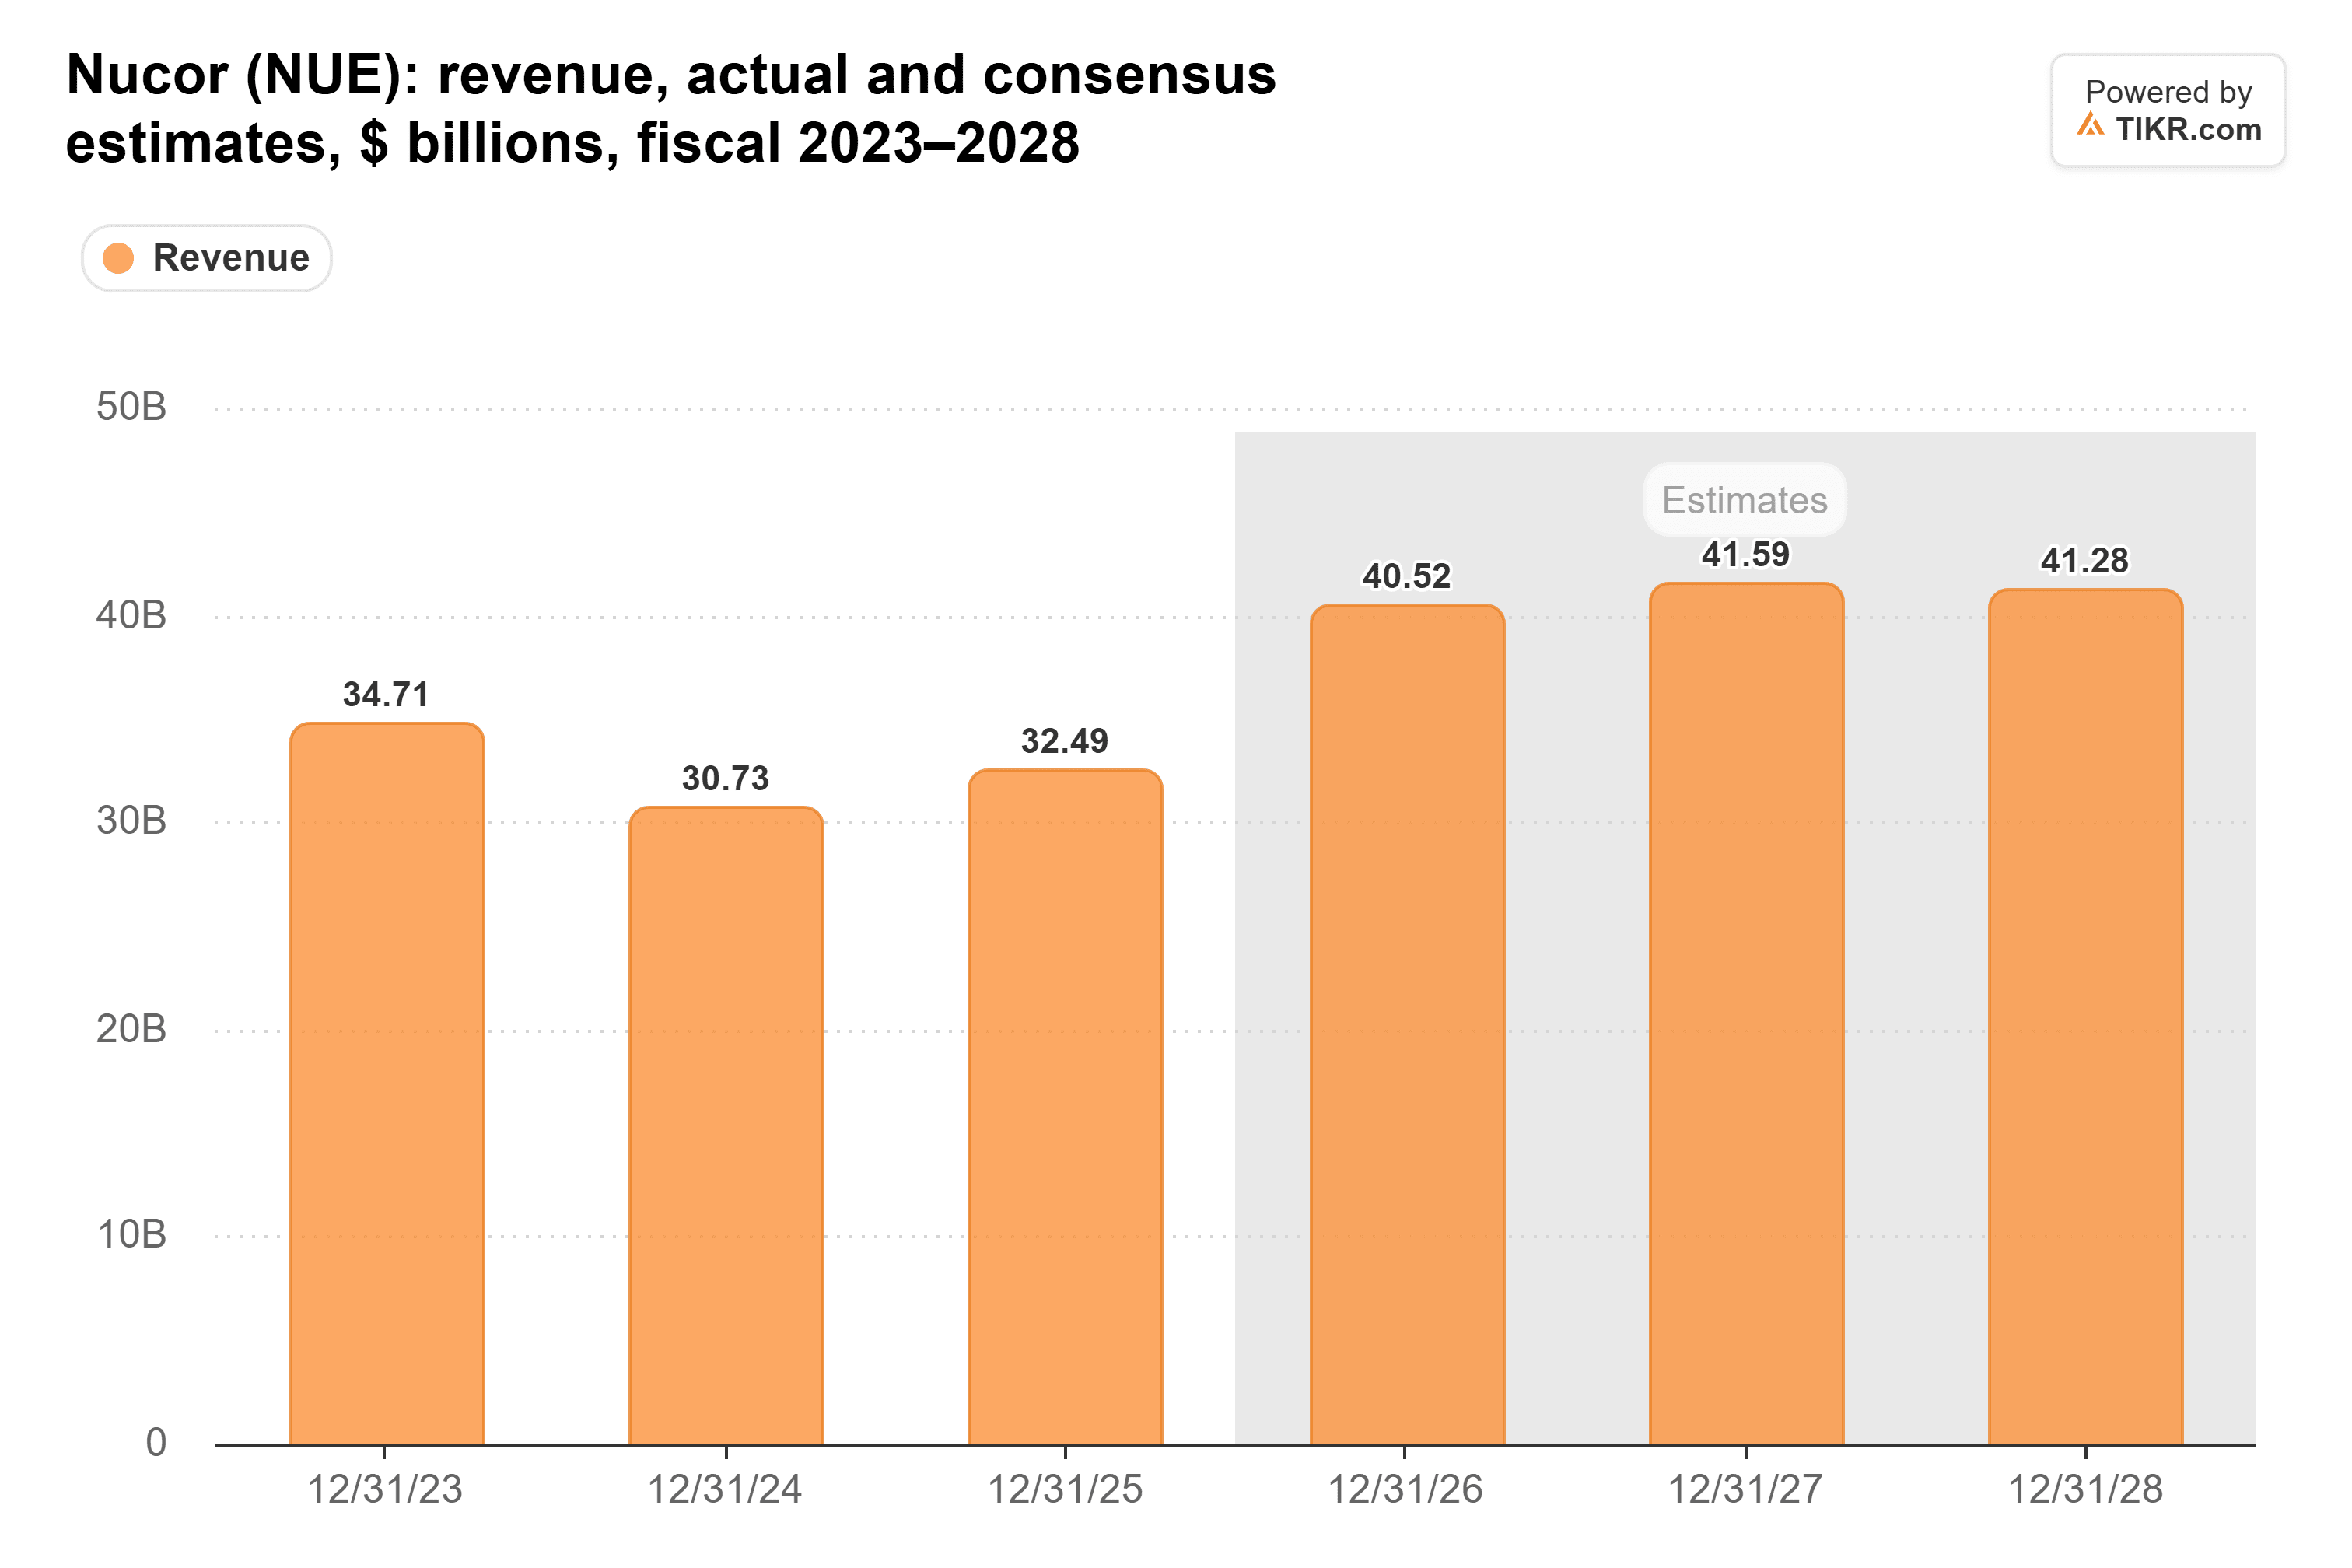
With $31.1 billion already booked through nine months and fourth-quarter pricing guided higher, I’d expect that estimate to rise.
TIKR tracks 17 analysts on Nucor. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Nucor, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Nucor’s Analyst Ratings
What’s next
Nucor sees stable fourth-quarter earnings from its mills, as higher realized pricing offsets seasonally lower volumes and higher costs.
That keeps on track the rebound analysts had already baked in: normalized EPS of $19.40 this year, up from $7.71 in 2025.
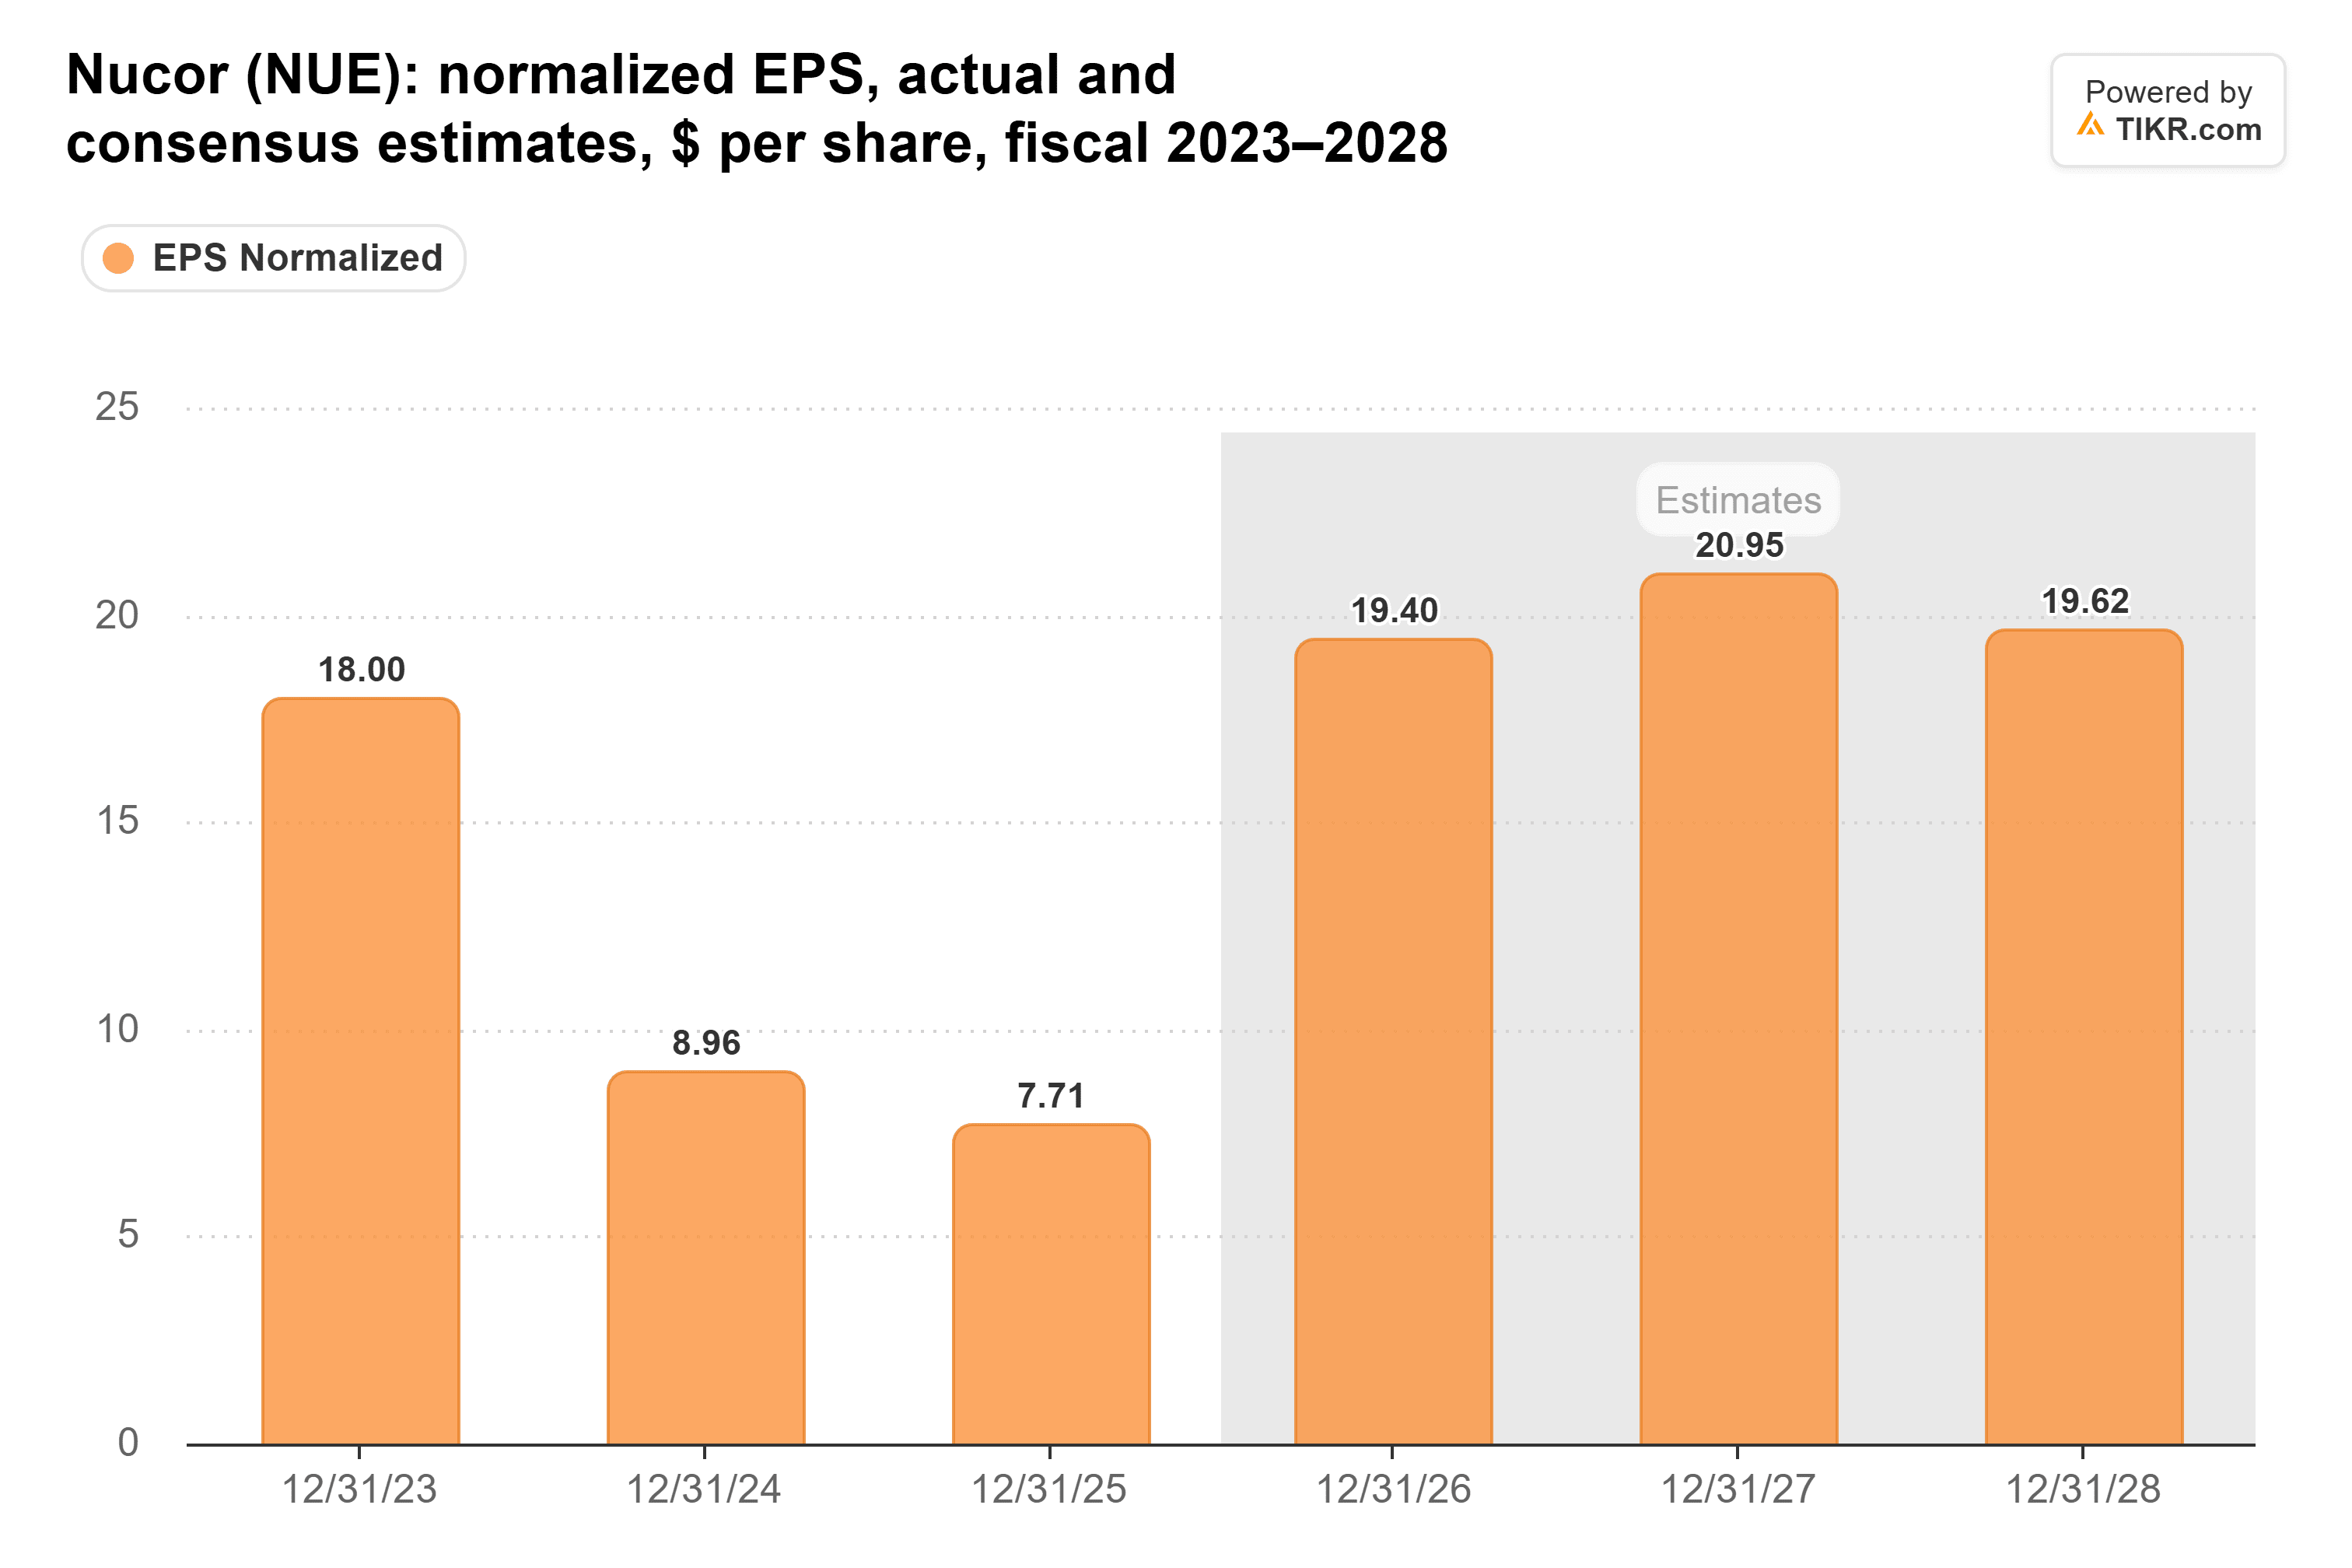
A fourth quarter in line with the third would put 2026 a little ahead of that.
Further out, the new West Virginia sheet mill, which had its first heat in September, starts production in 2027.
Priced about right after the jump
Nucor traded at 11x forward earnings at Monday’s close, just under its five-year average of 12x.
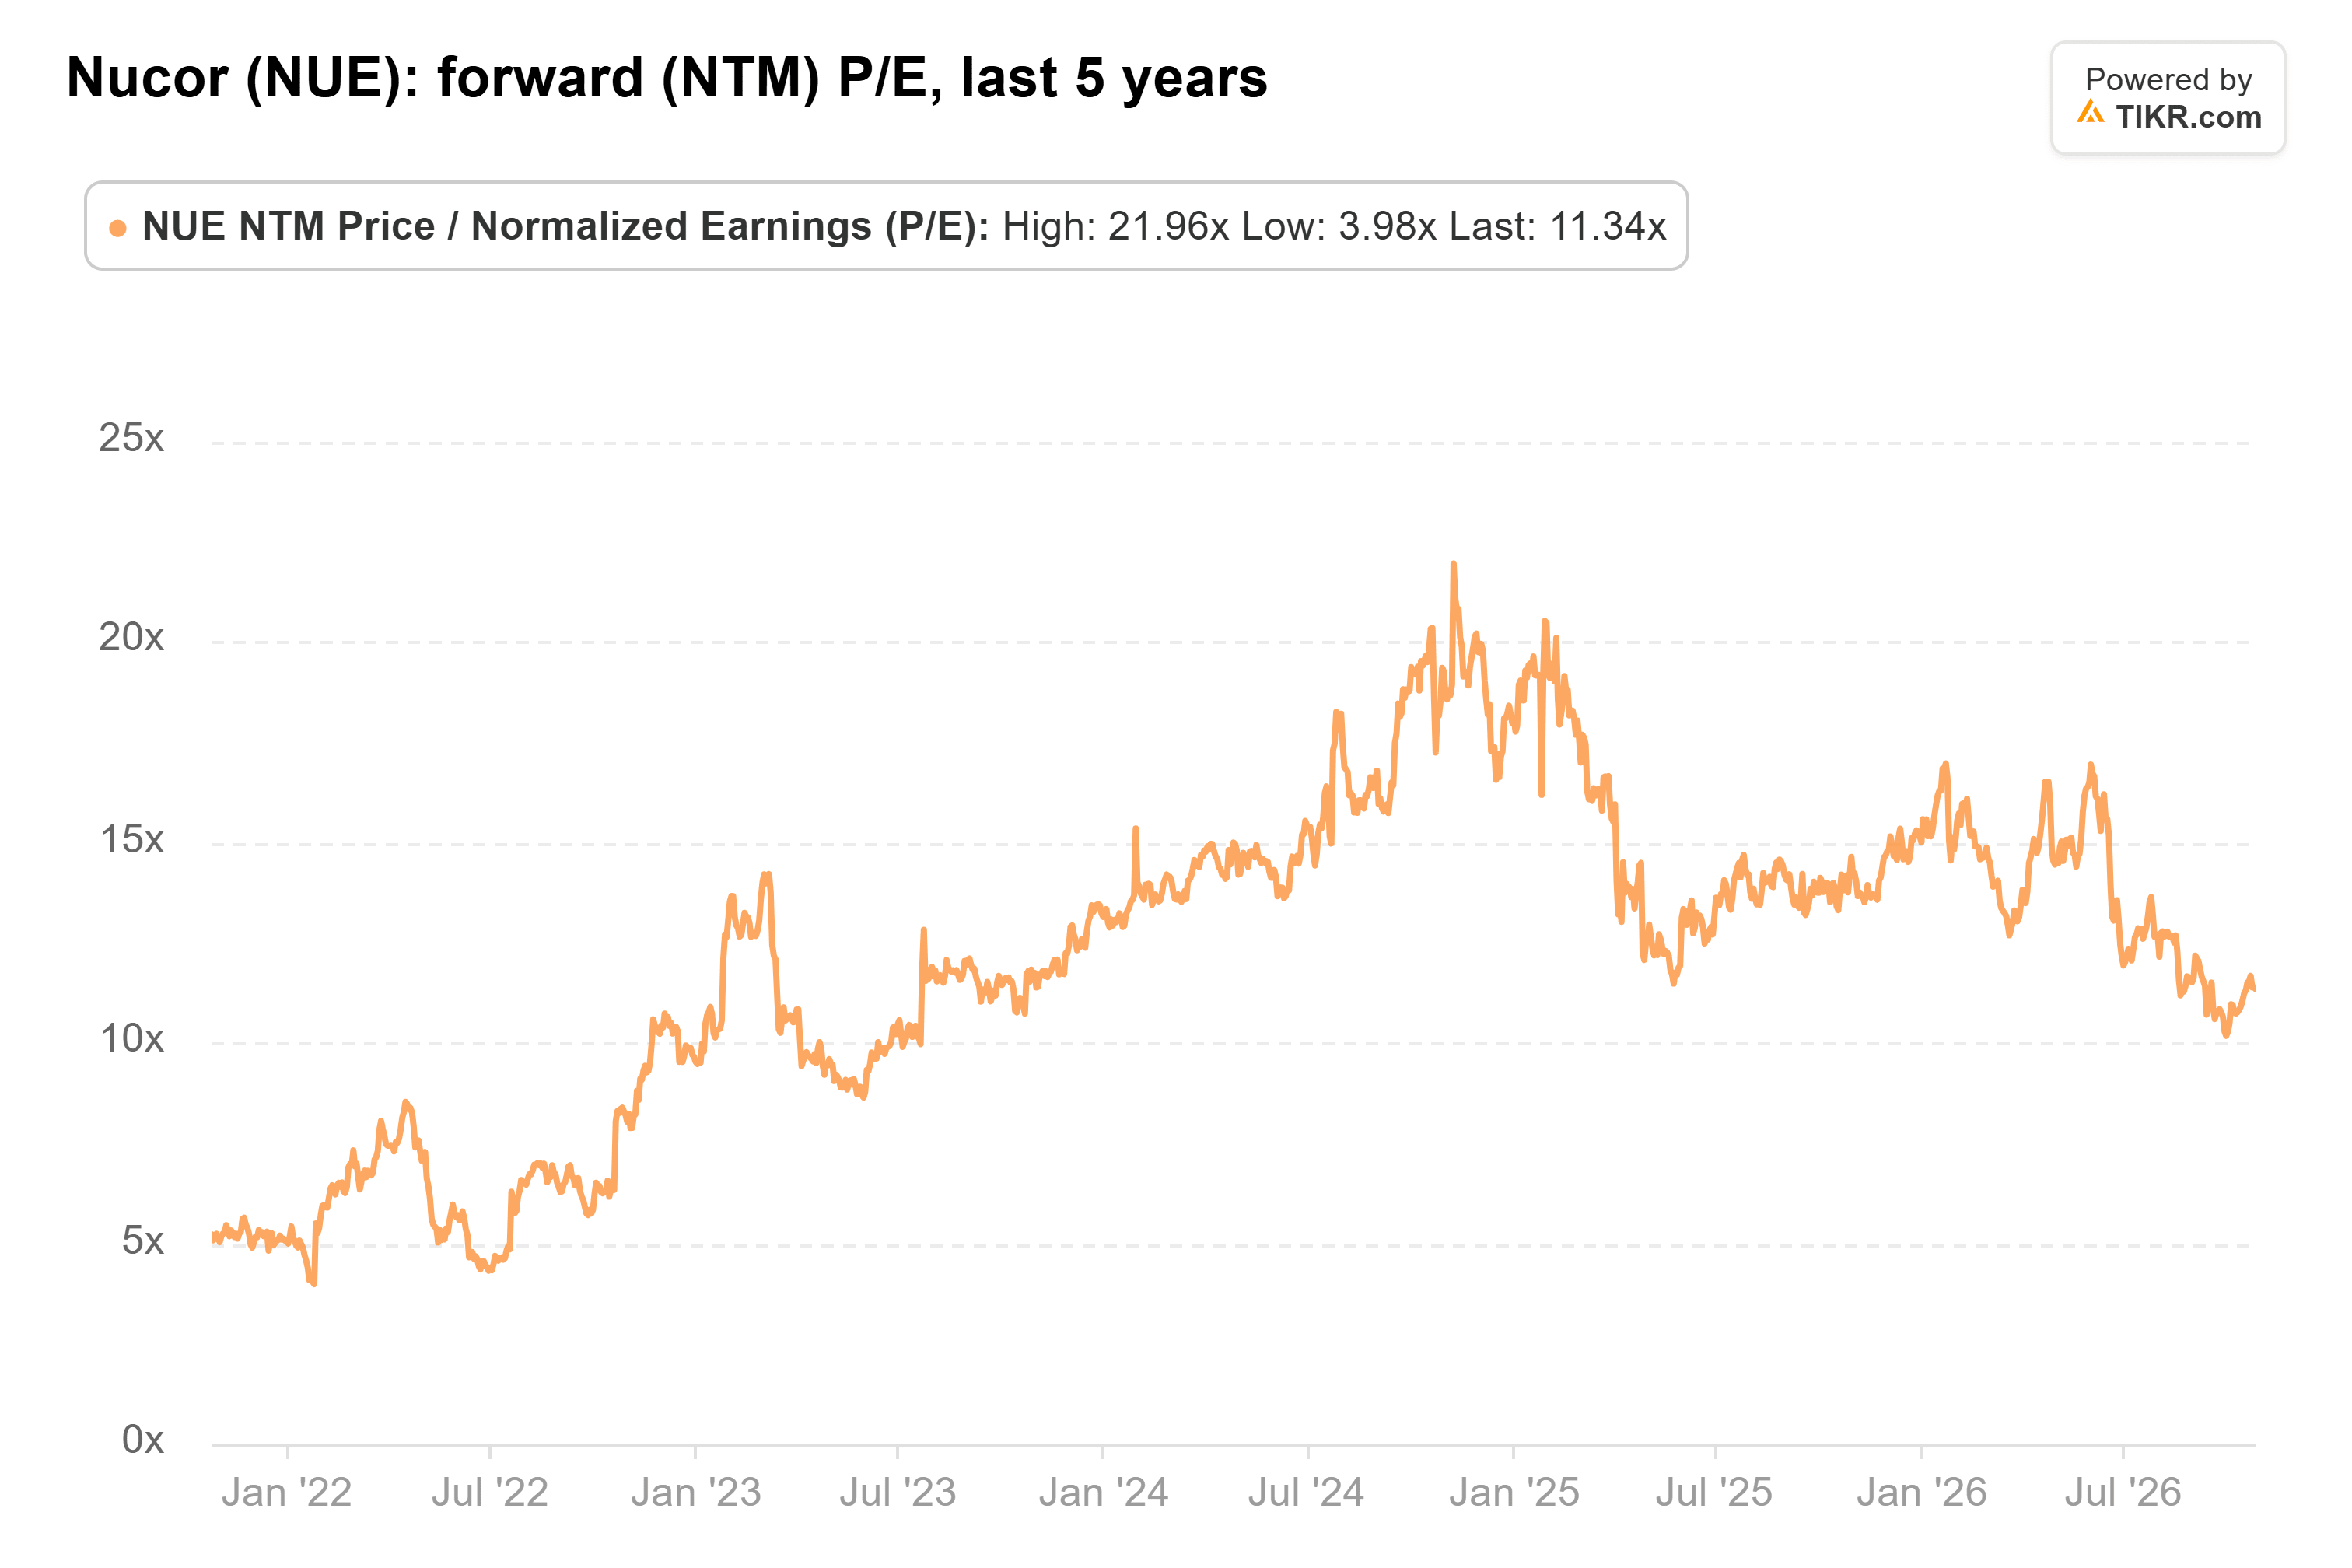
After today’s jump, it’s closer to 12x, right on that average.
Of course, a steelmaker’s earnings follow steel prices: Nucor earned $18 a share in 2023, and less than half that in 2024 and 2025.
My take: the jump is earned. A fourth quarter guided at least as strong as the third should push estimates up and pull that multiple back below its average. But from here, the stock needs steel prices to hold into 2027, when West Virginia starts adding tons.
So what is Nucor stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Nucor could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!