

Key Stats for PepsiCo Stock
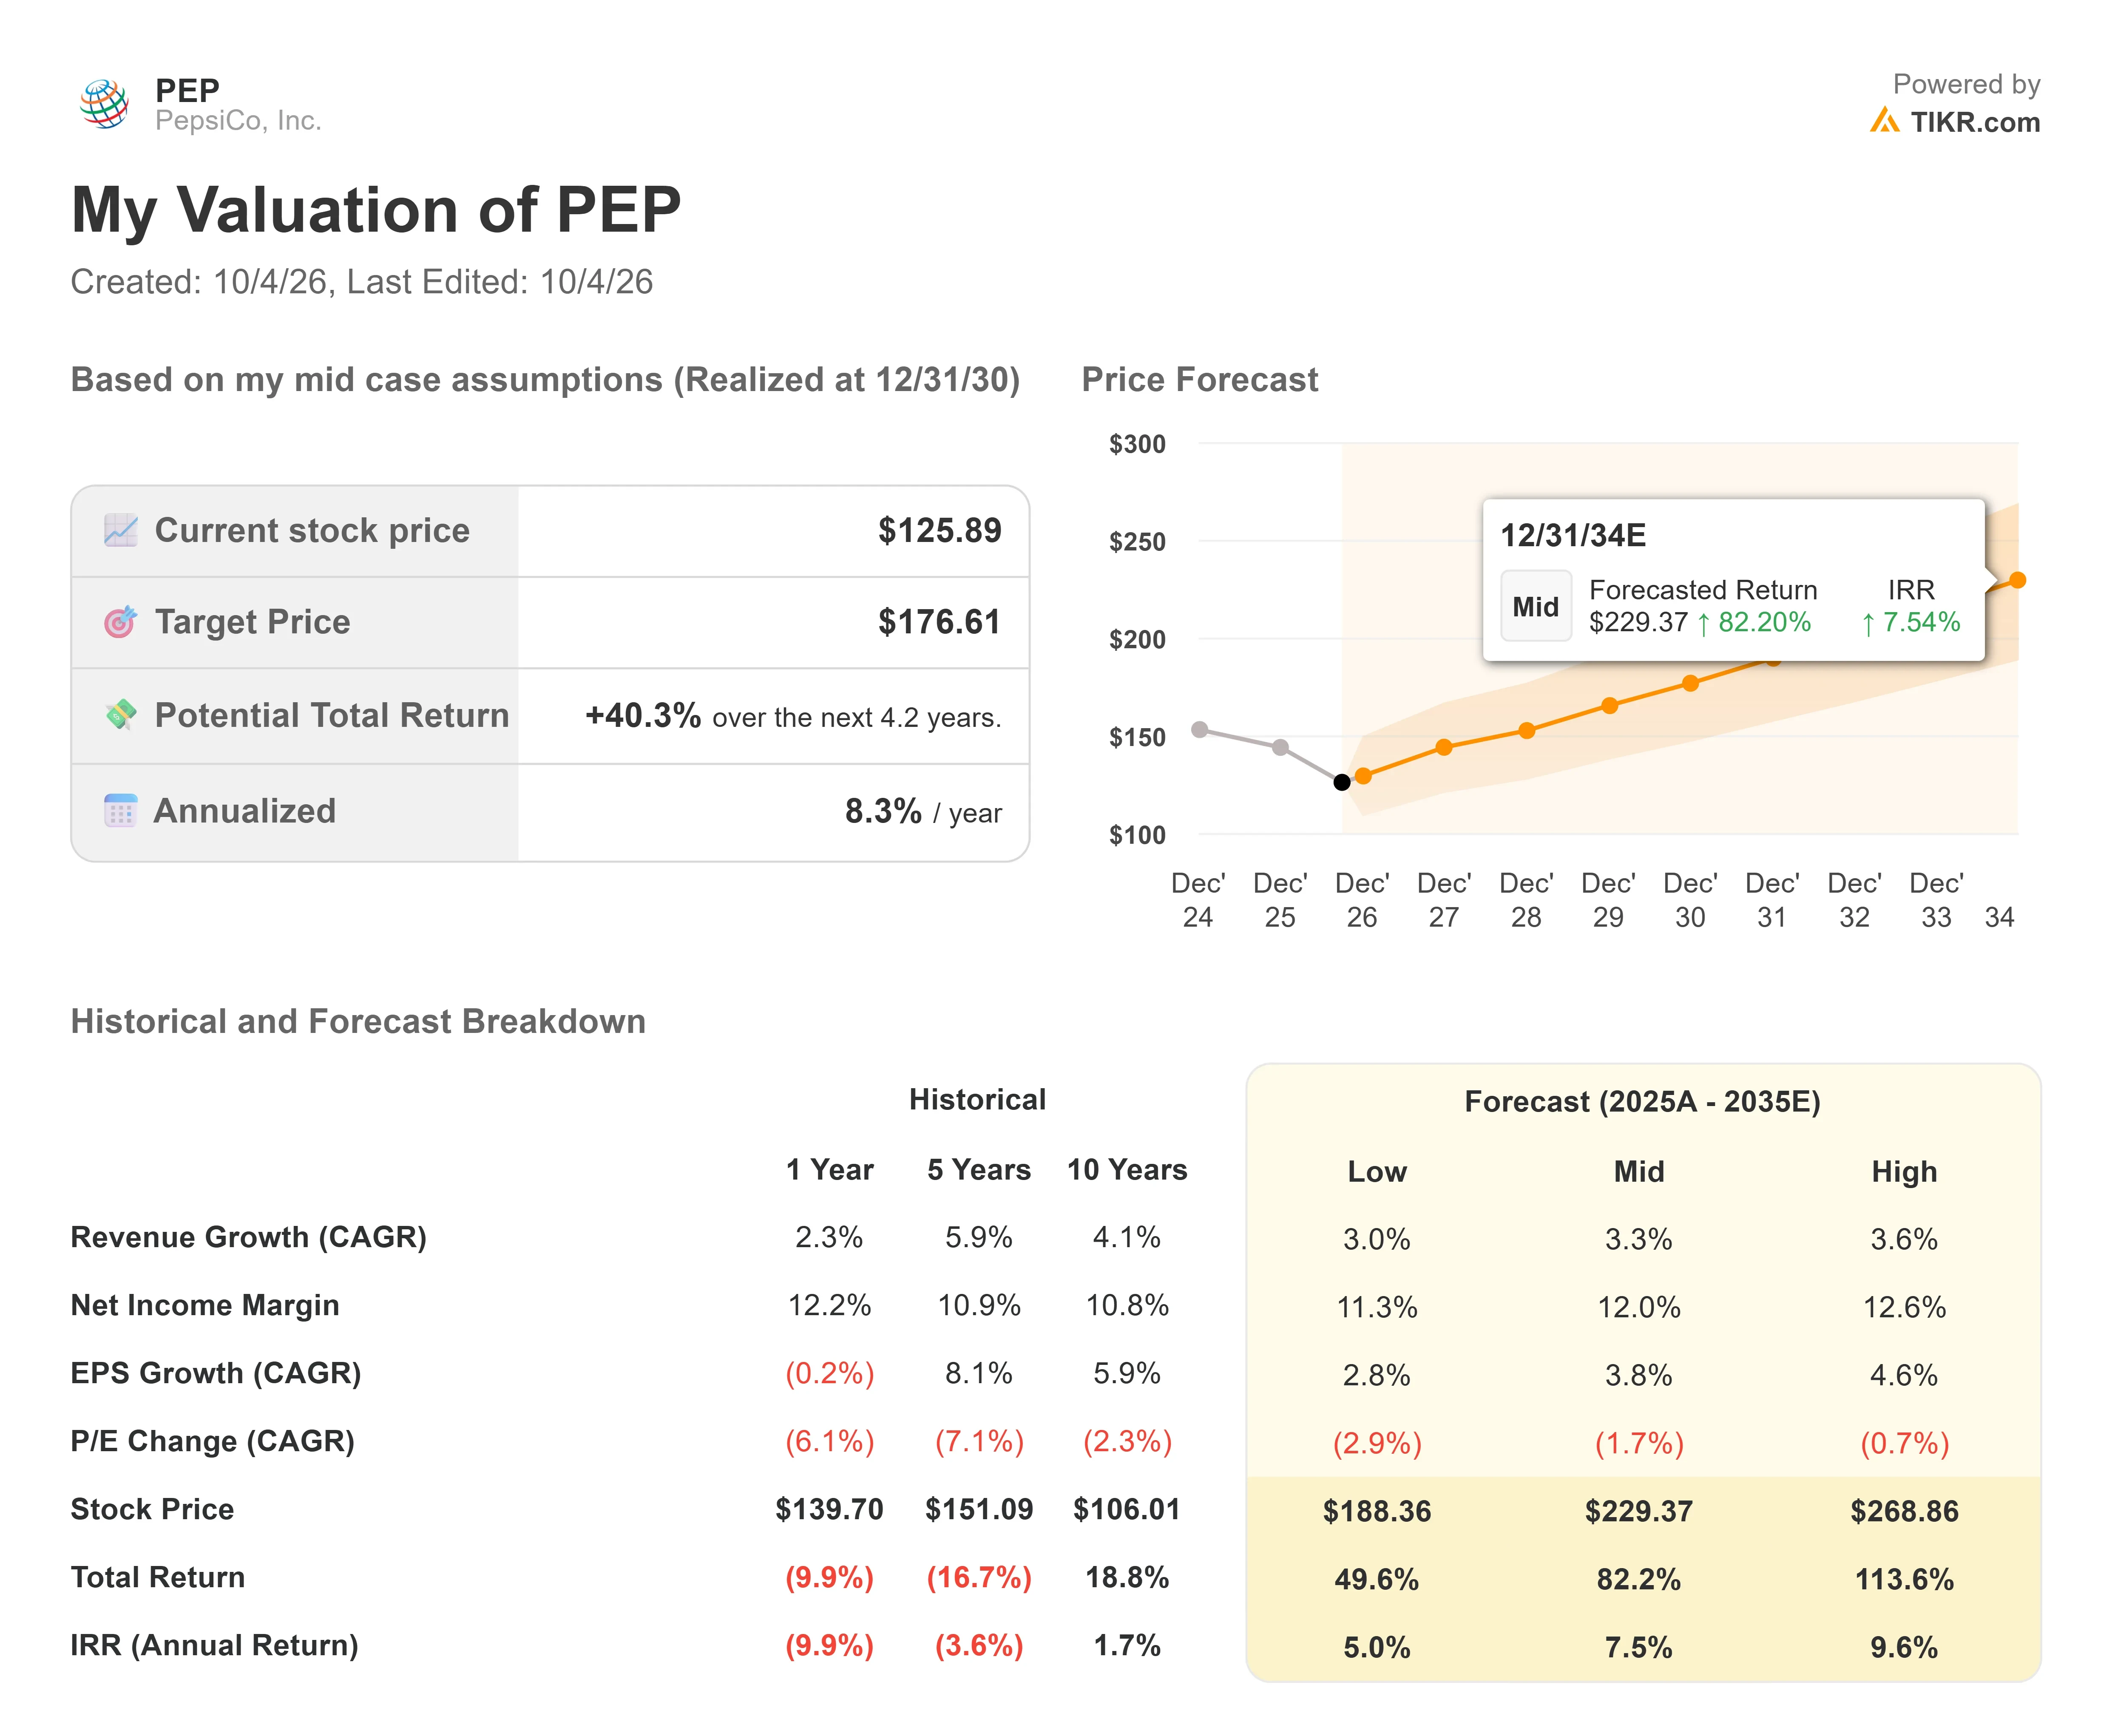
- Current Price: $125.89
- Target Price (Mid): ~$177
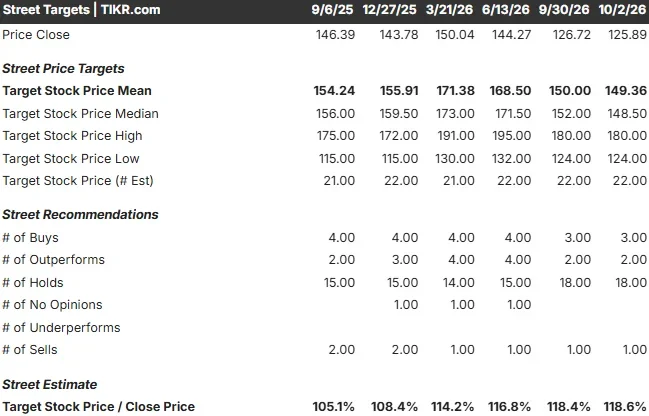
- Street Target: ~$149
- Potential Total Return: ~40%
- Annualized IRR: ~8% / year
Now Live: Discover how much upside your favorite stocks could have using TIKR’s new Valuation Model (It’s free) >>>
What Happened?
In July, Deutsche Bank analyst Steve Powers suggested on PepsiCo’s (PEP) second-quarter call that its affordability and innovation initiatives “appear largely in the market,” then asked what catalysts remained. On September 28, he downgraded the stock to Hold and cut his target to $138 from $155. JPMorgan’s Andrea Teixeira, who also questioned management on that call, followed on September 29 with a downgrade to Neutral and the same $138 target. Shares closed at $125.89 on October 2, just above an intraday 52-week low of $125.16, ahead of third-quarter results and investor relations materials due before the open on October 8.

See historical and forward estimates for PepsiCo stock (It’s free!) >>>
JPMorgan Questions the Productivity Laguarta Called a Strength
JPMorgan argues the North American snack recovery stalled after the first quarter, leaving PepsiCo to lean more heavily on productivity in the fourth quarter to deliver its earnings guidance. It also expects higher costs to offset part of those savings. Management made a related point in July but framed it as strength. “We don’t think we need any sort of reset because we have a very strong productivity, record productivity in the first half of the year,” Chairman and CEO Ramon Laguarta said.
The disagreement is about durability. Savings can fund price investments for a few quarters, but if North American volume does not respond, each quarter needs deeper cuts to hold the same earnings line. Not every analyst has moved: on TIKR’s count, five still rate the stock Buy or Outperform.
Teixeira Flagged a Flat Third Quarter in July. Consensus Matches It
On the July call, Teixeira asked management to check her math that reinvesting $0.07 to $0.09 per share of tariff-related benefit “implies more flattish 3Q.” Consensus calls for third-quarter adjusted EPS of around $2.30, against $2.29 a year earlier, on revenue of around $25 billion, up about 4%.
CFO Stephen Schmitt said he does not like to guide individual quarters, then laid out the moving parts. Tariff refund claims are worth about 1 full point of full-year EPS growth and will likely be booked in the third quarter, alongside a higher tax rate and costs timed into the period. One point of 2025’s $8.14 normalized EPS is about $0.08, so if the refund sits inside the consensus figure, the rest of the business would be earning roughly 3% less than a year ago.
The heavier lift falls on the fourth quarter, where consensus expects around $2.43, up about 8%, and Schmitt said he expects better profit performance there than in the third. He also said full-year results may land “towards the low end of the EPS range.”
See how PepsiCo performs against its peers in TIKR (It’s free!) >>>
TIKR Advanced Model Analysis
- Current Price: $125.89
- Target Price (Mid): ~$177
- Potential Total Return: ~40%
- Annualized IRR: ~8% / year
See analysts’ growth forecasts and price targets for PepsiCo stock (It’s free!) >>>
The mid case is the model’s central scenario. It values PepsiCo at around $177 by December 31, 2030, roughly 40% above $125.89, or about 8% a year over 4.2 years. That sits above both 138 downgrade targets and near the ~ 180 Street high, but it is a 2030 scenario, not a 12-month call.
One piece already compounding is the permissible snack portfolio, which Laguarta said is $3 billion and growing at almost double digits. The primary risk is that North American volume stays flat and productivity stops covering for it. Upside comes if the delayed shelf space gains he described land in the second half.
Conclusion
The deciding signal is whether PepsiCo reaffirms full-year EPS guidance with North American foods volume growing, without the tariff refund doing the heavy lifting. A clean reaffirmation would suggest the downgrades came late, while a cut would confirm productivity was covering for demand. Laguarta also said management would share more details on combining its U.S. logistics, now being tested in Texoma, “later in the year, early next year,” and hard savings figures there would show how much the productivity engine has left.
See what stocks billionaire investors are buying so you can follow the smart money with TIKR.
So what is PepsiCo stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what PepsiCo could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Analyze PepsiCo on TIKR Free →
Looking for New Opportunities?
- See what stocks billionaire investors are buying so you can follow the smart money.
- Analyze stocks in as little as 5 minutes with TIKR’s all-in-one, easy-to-use platform.
- The more rocks you overturn… the more opportunities you’ll uncover. Search 100K+ global stocks, global top investor holdings, and more with TIKR.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!


