Key Takeaways
- Alphabet’s June quarter revenue rose 24% to $119.8 billion, with Google Cloud up 82% to $24.8 billion and a backlog of $514 billion.
- TIKR’s valuation model points to around $520 by the end of 2028, a total return of around 52%, or about 20% a year.
- The catch is spending, since 2026 capex guidance runs $195 billion to $205 billion and free cash flow was negative $5.9 billion last quarter.
- The next earnings report will show whether capex and Cloud backlog are tracking the plan.
Alphabet (GOOGL) has gained around 40% over the past year, and the stock closed at $343.50 on Oct. 2. So when TIKR’s valuation model points to a total return of around 52% by the end of 2028, it’s fair to ask whether that number is a stretch.
The model is asking for less than the 52% suggests. Revenue growth lines up with what analysts already expect, and the P/E multiple shrinks to around 23x from around 28x, so the return comes from earnings and not from investors paying more. What’s worth debating is the bill, meaning how much Alphabet has to spend to get there.
| Metric | Past year | TIKR model, through 2028 |
|---|---|---|
| Revenue growth (CAGR) | 15% | 22% |
| Operating margin | 32% | 36% |
| P/E multiple | 28x | 23x |
| Stock price | $343.50 (Oct. 2 close) | Around $520 |
| Annualized return | n/a | About 20% |
Source: TIKR’s guided valuation model, with prices at the Oct. 2, 2026 close. Model outputs are rounded.
Pressure-test Alphabet’s 22% revenue growth assumption with your own inputs (Free with TIKR) >>>
Cloud is doing the heavy lifting
The June quarter is where the growth story gets hard to argue with. Alphabet grew revenue 24% to $119.8 billion, its 12th straight quarter of double-digit growth, and Google Cloud did much of the heavy lifting, with revenue up 82% to $24.8 billion and operating income of $8.8 billion.
Cloud’s backlog of signed contracts now stands at $514 billion, which is a lot of future revenue already spoken for. Search, still the core of the business, grew 17% to $63.3 billion.
The chart below shows how analysts expect that growth to carry through 2030.
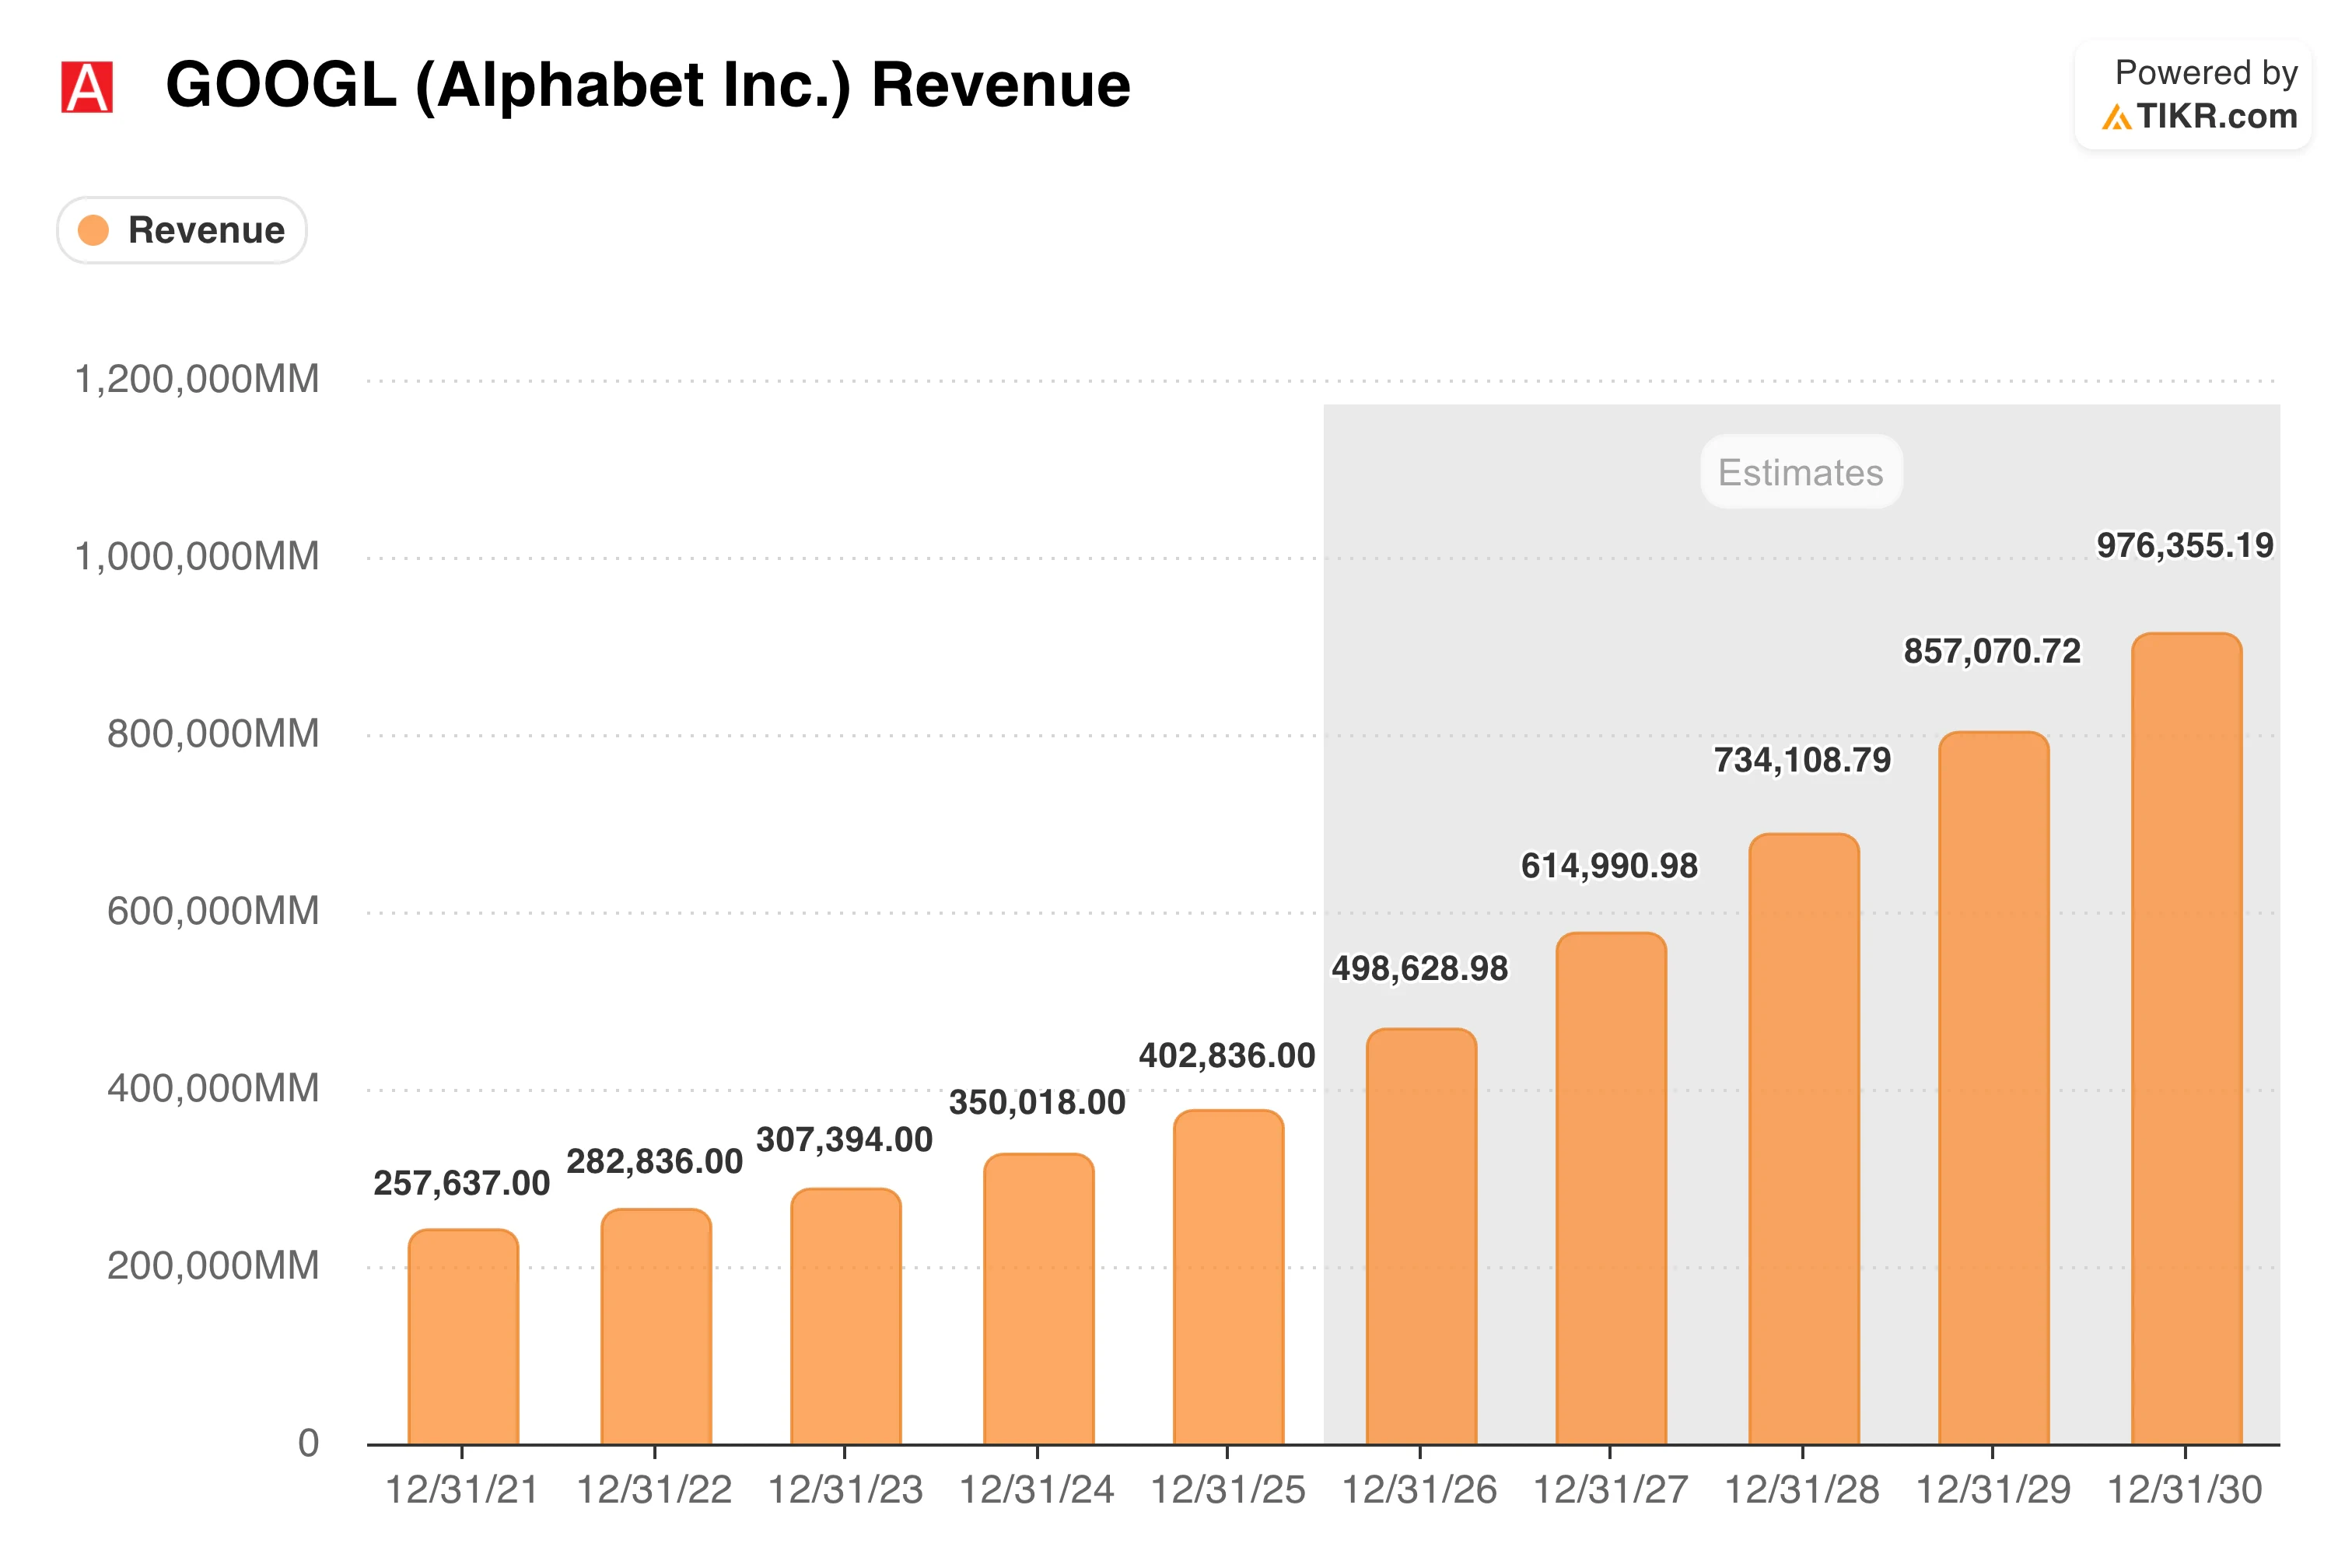
Analysts see revenue at around $500 billion this year, then around $615 billion in 2027 and around $735 billion in 2028. Growth slows along the way, from around 24% this year to around 19% by 2028, and the model’s 22% annual pace through 2028 sits right in line with those estimates. In plain terms, Alphabet doesn’t need to do much better than analysts already expect for this to work.
Microsoft (MSFT) is growing in cloud as well, though more slowly. Its Azure and other cloud services revenue rose 43% in the June quarter, off a base that already tops $100 billion a year, so Google Cloud’s 82% is nearly double that pace.
The $205 billion question
Growth like this doesn’t come cheap. In the June quarter alone, Alphabet spent $44.9 billion on capital expenditures, mostly on AI infrastructure, and free cash flow turned negative at $5.9 billion, although it was still positive at $53.3 billion over the last twelve months.
Management now expects $195 billion to $205 billion of capex for 2026 and a significant increase in 2027. Alphabet has also paused its buybacks and raised money through stock and debt, which matters when you’re asking what each share is worth.
The chart below shows the cash side of the story, with analysts expecting operating cash flow to roughly double by 2028.
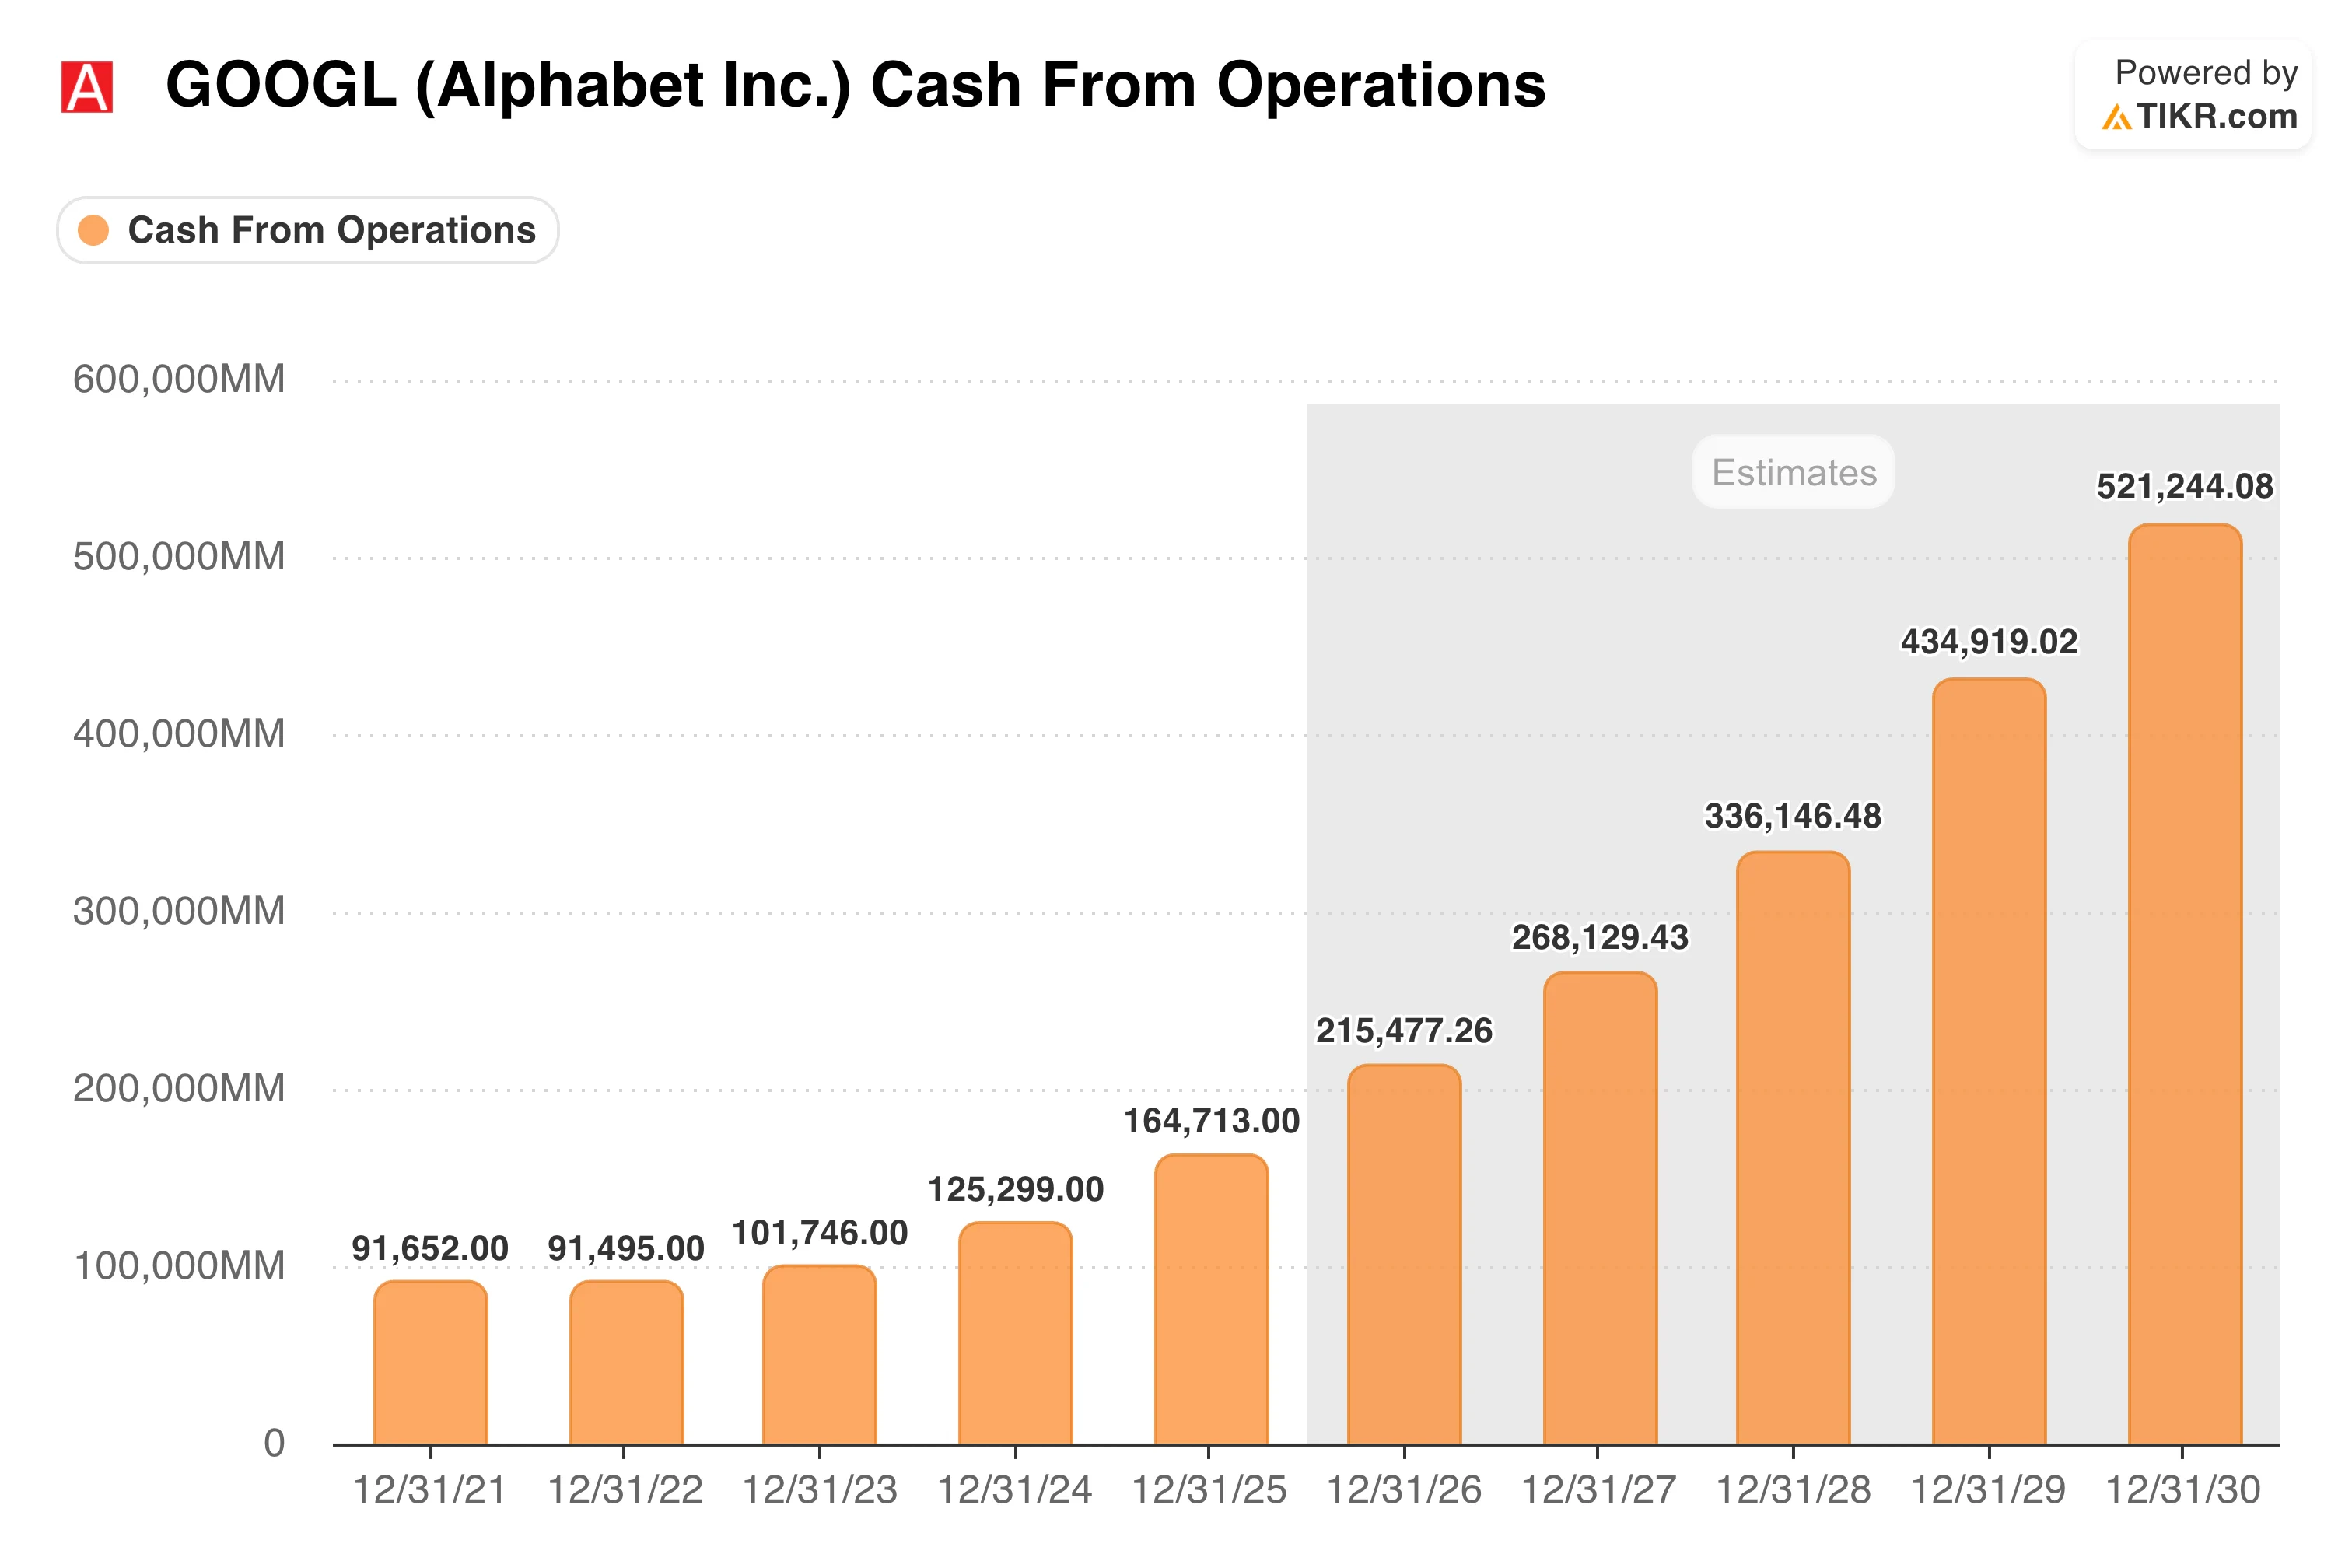
Operating cash flow was about $165 billion in 2025, and consensus has it at around $215 billion this year, around $270 billion in 2027, and around $335 billion in 2028. The comparison matters because this year’s estimate sits only modestly above the capex guide, which leaves little cushion in 2026, while the later years are where the room builds. I’d watch that gap closely.
Analyze GOOGL stock on TIKR Free→
So does the 52% hold up?
TIKR’s valuation model lands at around $520 by the end of 2028, a total return of around 52%, or about 20% a year. It gets there with revenue growing around 22% a year and operating margin edging up to around 36%, while the P/E multiple shrinks to around 23x from around 28x.
I like that the return comes from earnings growth and not from investors paying more for each dollar of profit, which makes the result less dependent on the market’s mood.
The chart below shows the path.
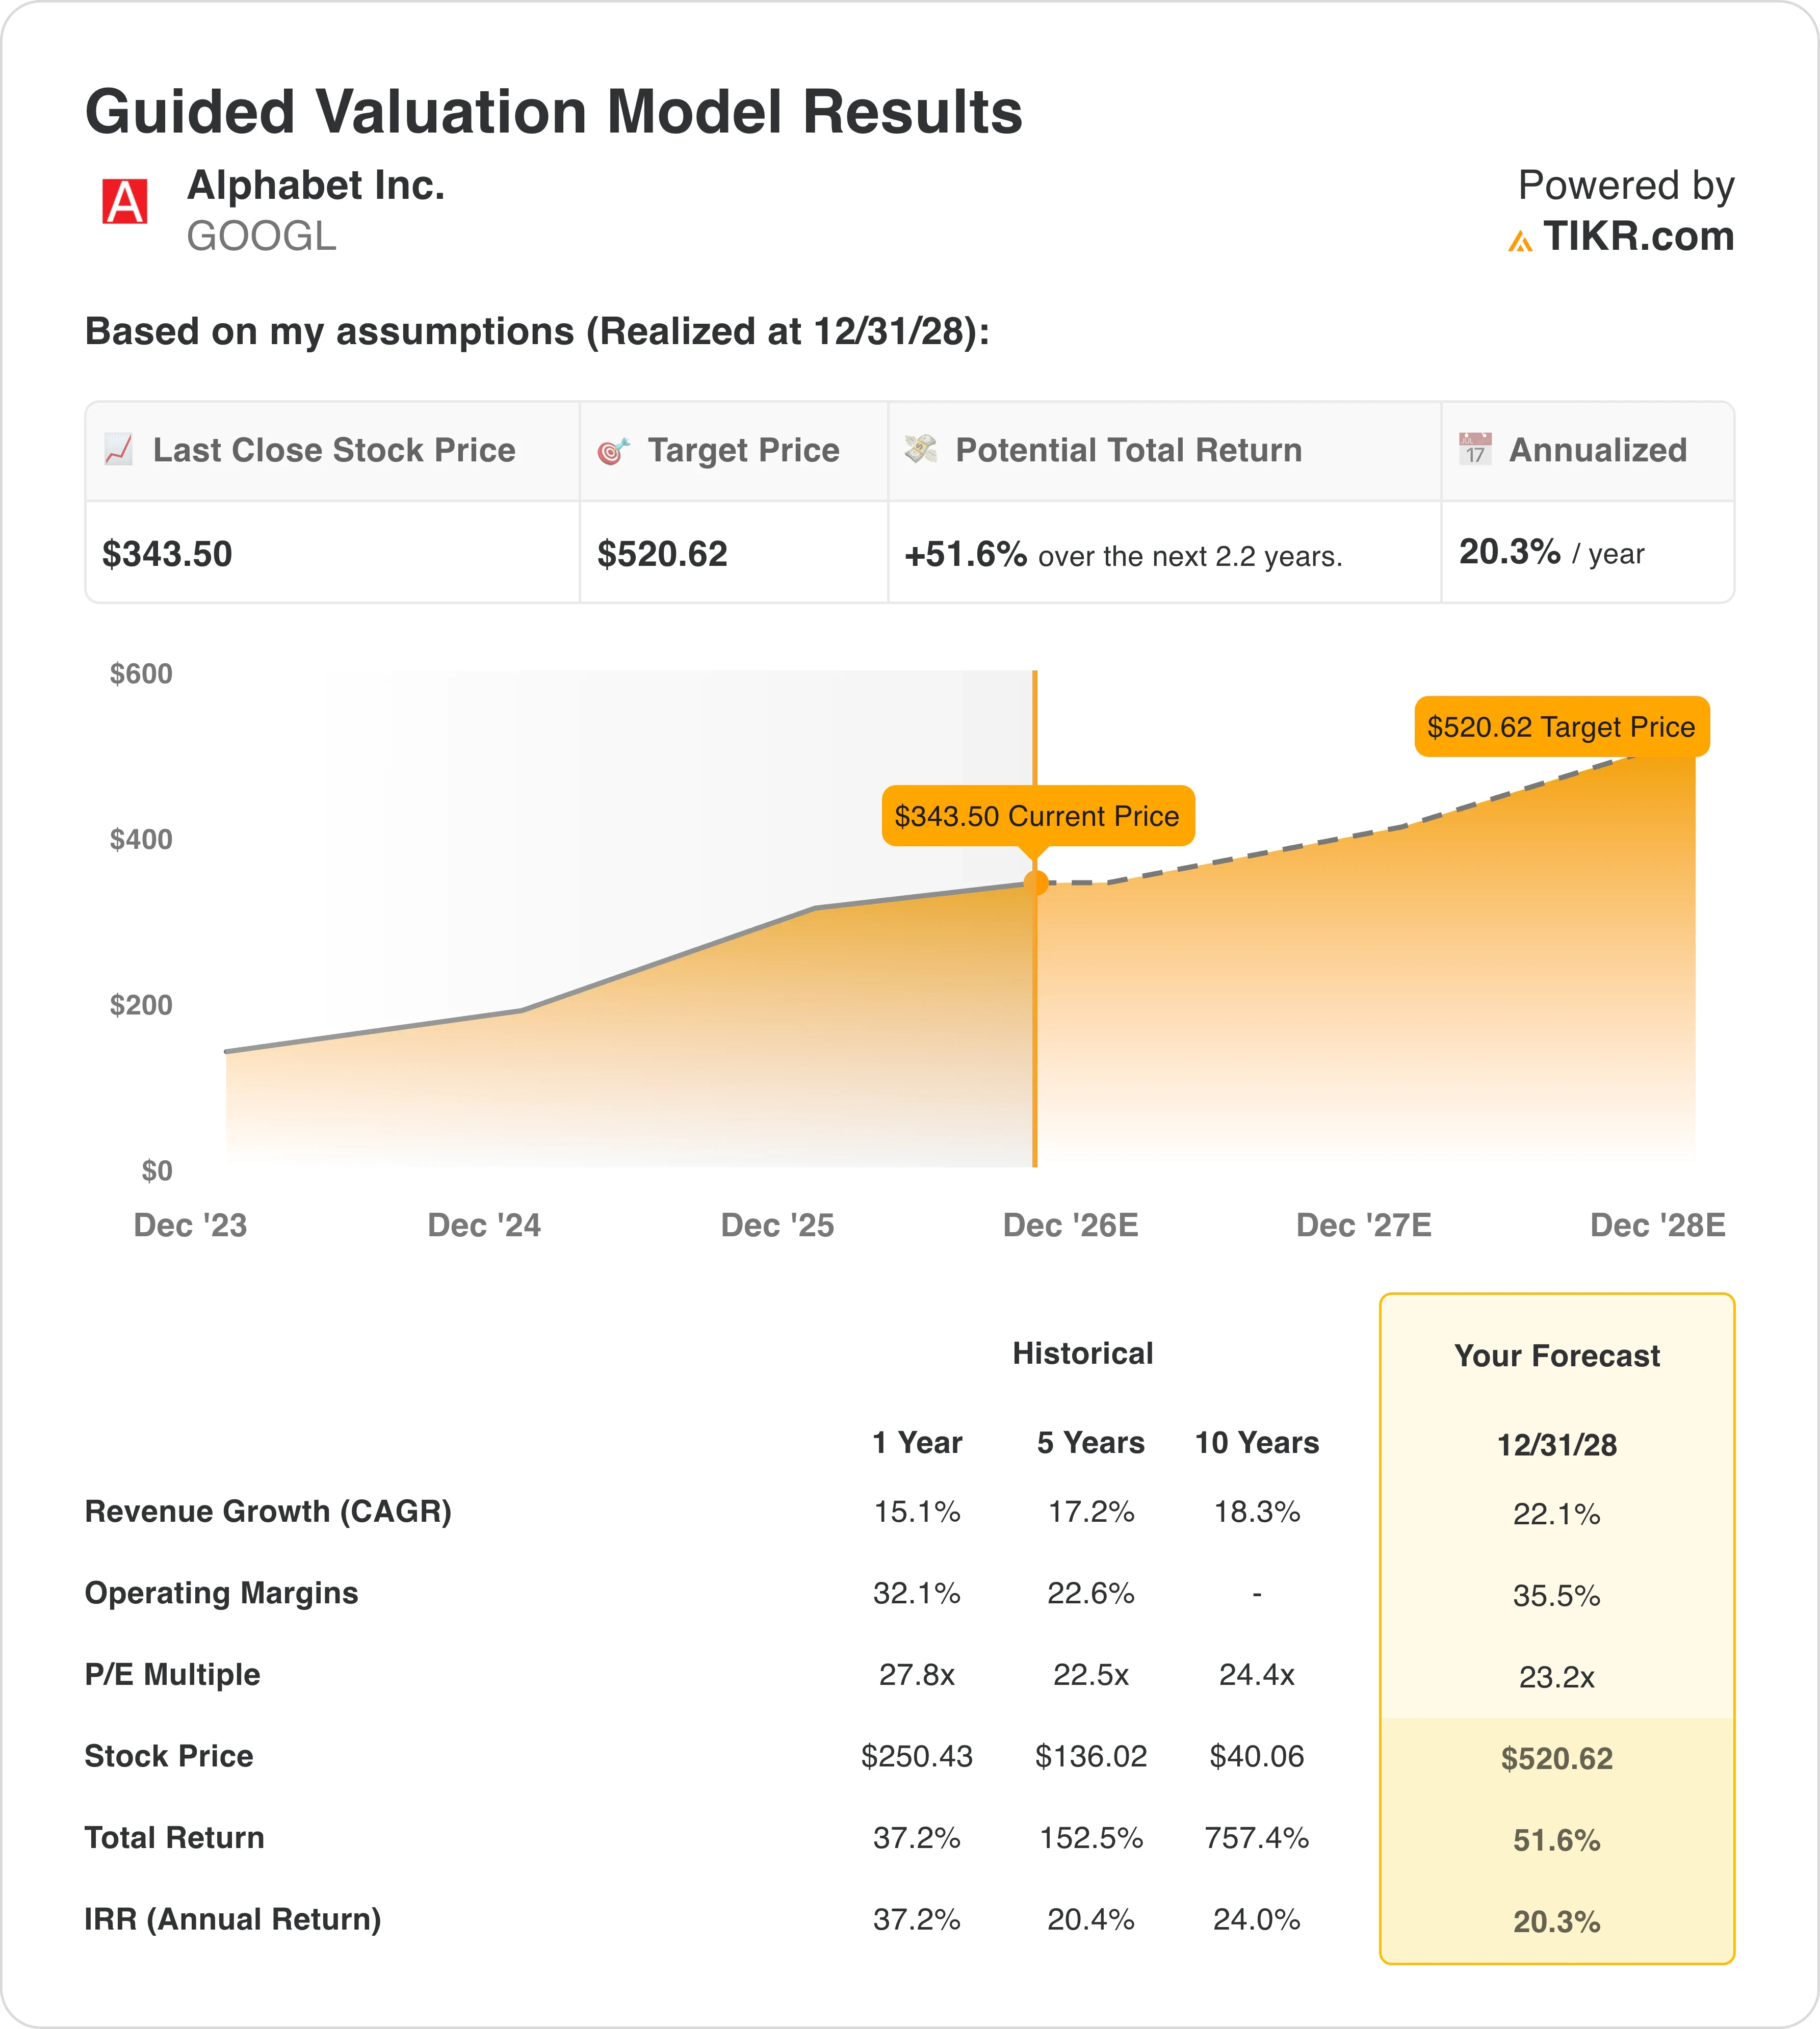
Wall Street’s average target of around $430 is a 12-month figure, which works out to about 25% upside from here, so the model’s 20% a year isn’t more aggressive than the Street’s one-year view.
On the bull side, Cloud is growing 82% with a $514 billion backlog, and Search still grew 17%, and the stock doesn’t need a richer multiple to get there. The bear case sits in the spending. If this year’s roughly $200 billion of capex doesn’t earn adequate returns, or if margins stall short of the model’s 36%, the earnings behind the target arrive later or smaller.
For me, the margin assumption is the one to watch, since the model has Alphabet earning more on each dollar of revenue while it spends at a record pace.
So what is Alphabet stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Alphabet could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!