Key Takeaways
- Pinterest fell 4.9% to $21 as Amazon veteran James Dibbo became CFO, two days before Q3 results on October 29.
- Q3 guidance calls for 13% to 15% revenue growth, down from 18% in Q2, with adjusted EBITDA of $335 million to $355 million.
- Share-based compensation rose to $324.5 million in Q2, leaving a $47 million GAAP net loss.
- The Q4 guide and Dibbo’s first comments on stock comp will show whether 9.7x forward earnings is too cheap.
Pinterest just changed finance chiefs, and the new one gets about three days to settle in.
Shares of Pinterest (PINS) fell 4.9% to $21 on Monday, the day James Dibbo officially became CFO. The stock is down roughly 40% over the past year.
Dibbo arrives from Amazon (AMZN), where he ran finance for Amazon Ads, Prime Video and Twitch. His first earnings call is Wednesday, October 29.
Nothing in the company’s filings explains Monday’s drop. My guess is pre-earnings positioning.
Q3 guidance already concedes the slowdown
Pinterest guided Q3 revenue to $1.19 billion to $1.21 billion, or 13% to 15% growth. Q2 grew 18%, so a deceleration is baked in.
Here is the setup:
- Adjusted EBITDA guidance of $335 million to $355 million, up from $311 million in Q2.
- A full-year adjusted EBITDA margin outlook of about 30%, raised from 29%.
- A record 640 million monthly active users in Q2, up 11%.
The slowdown has a clear source. Asia-based cross-border retailers cut spending as European regulators stepped up, and that pressure carried into Q3.
Shares fell about 8.7% in August because the guide only matched consensus.
The quarterly revenue path Wall Street is now underwriting looks like this:
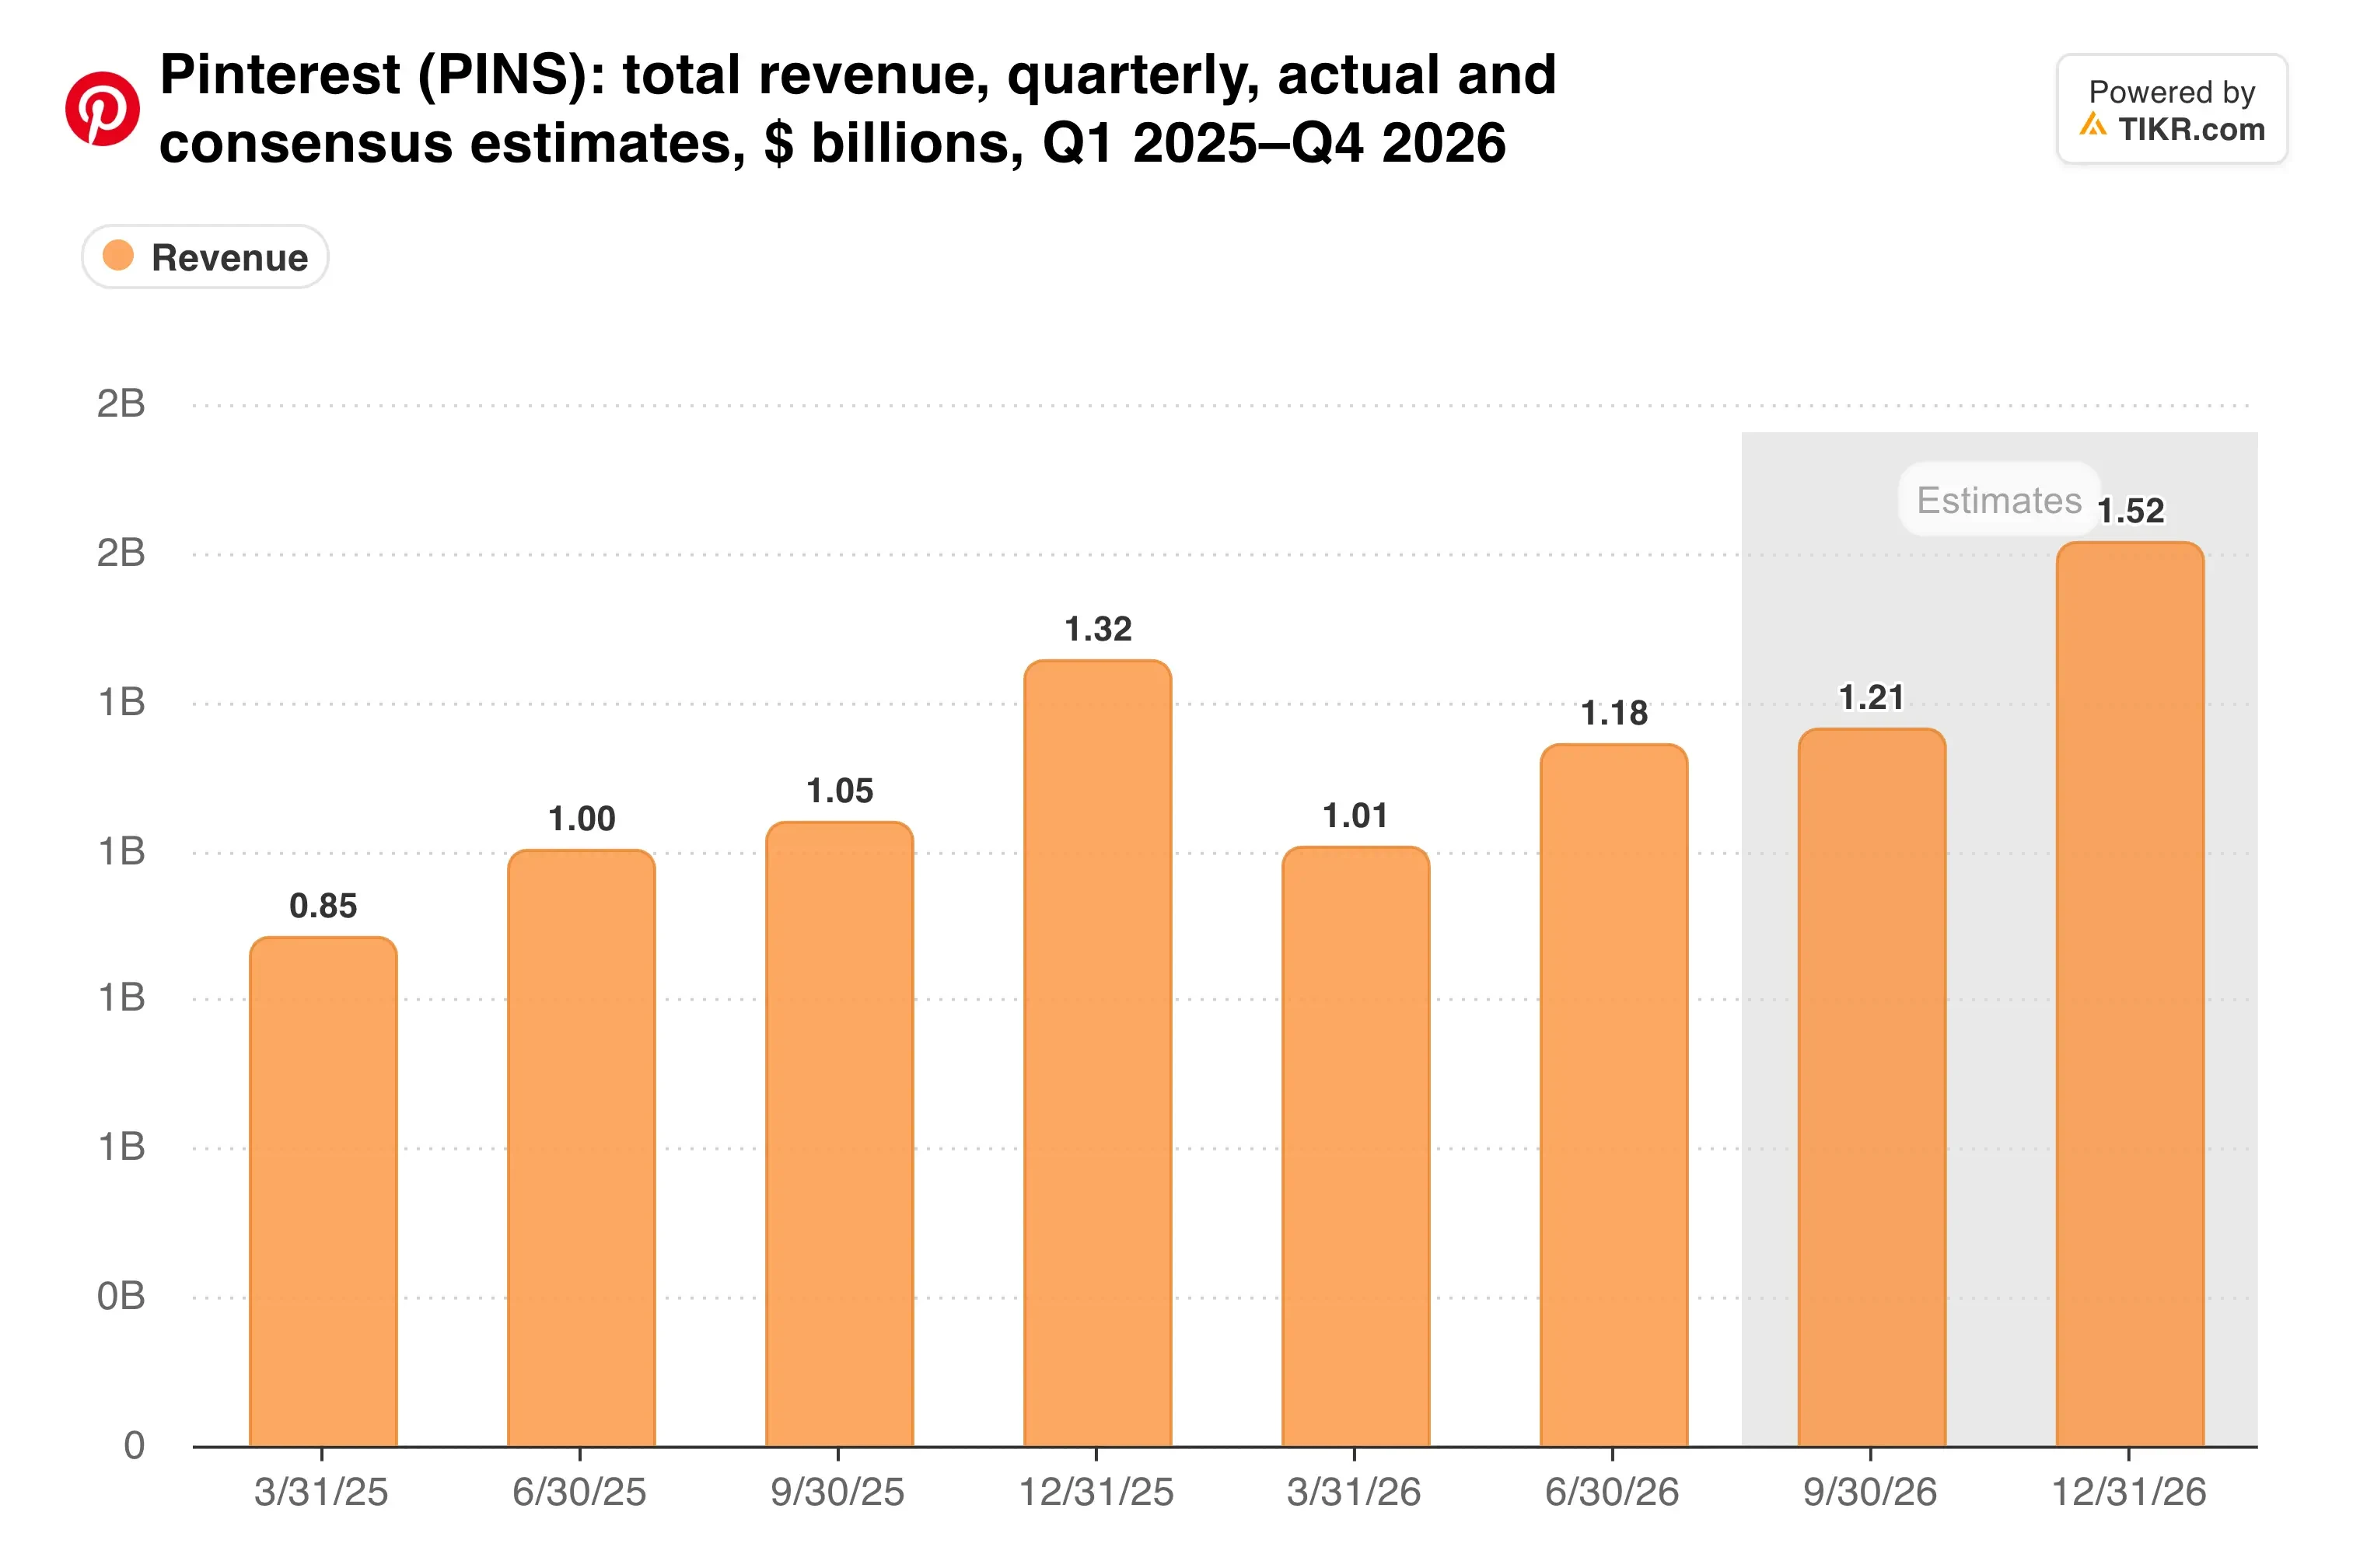
Consensus sits near the midpoint, so Q4 guidance will matter more than the Q3 print.
An ad finance chief arrives
Dibbo’s resume fits Pinterest’s oldest problem, which is turning engagement into ad dollars. CEO Bill Ready called him “an exceptional finance leader” when the hire was announced on October 5.
Ready has framed AI as the engine. “AI is at the heart of our momentum and is a clear accelerant for our business,” he said in the Q2 release.
GAAP profits lag that story. Pinterest posted a $47 million net loss in Q2, as share-based compensation rose $97.3 million to $324.5 million. Cost of revenue also climbed 25% on the tvScientific deal and more GPU capacity.
Management expects stock comp to step down starting in Q3. That gives Dibbo an early chance to make his mark.
Adjusted margins have moved in one direction…
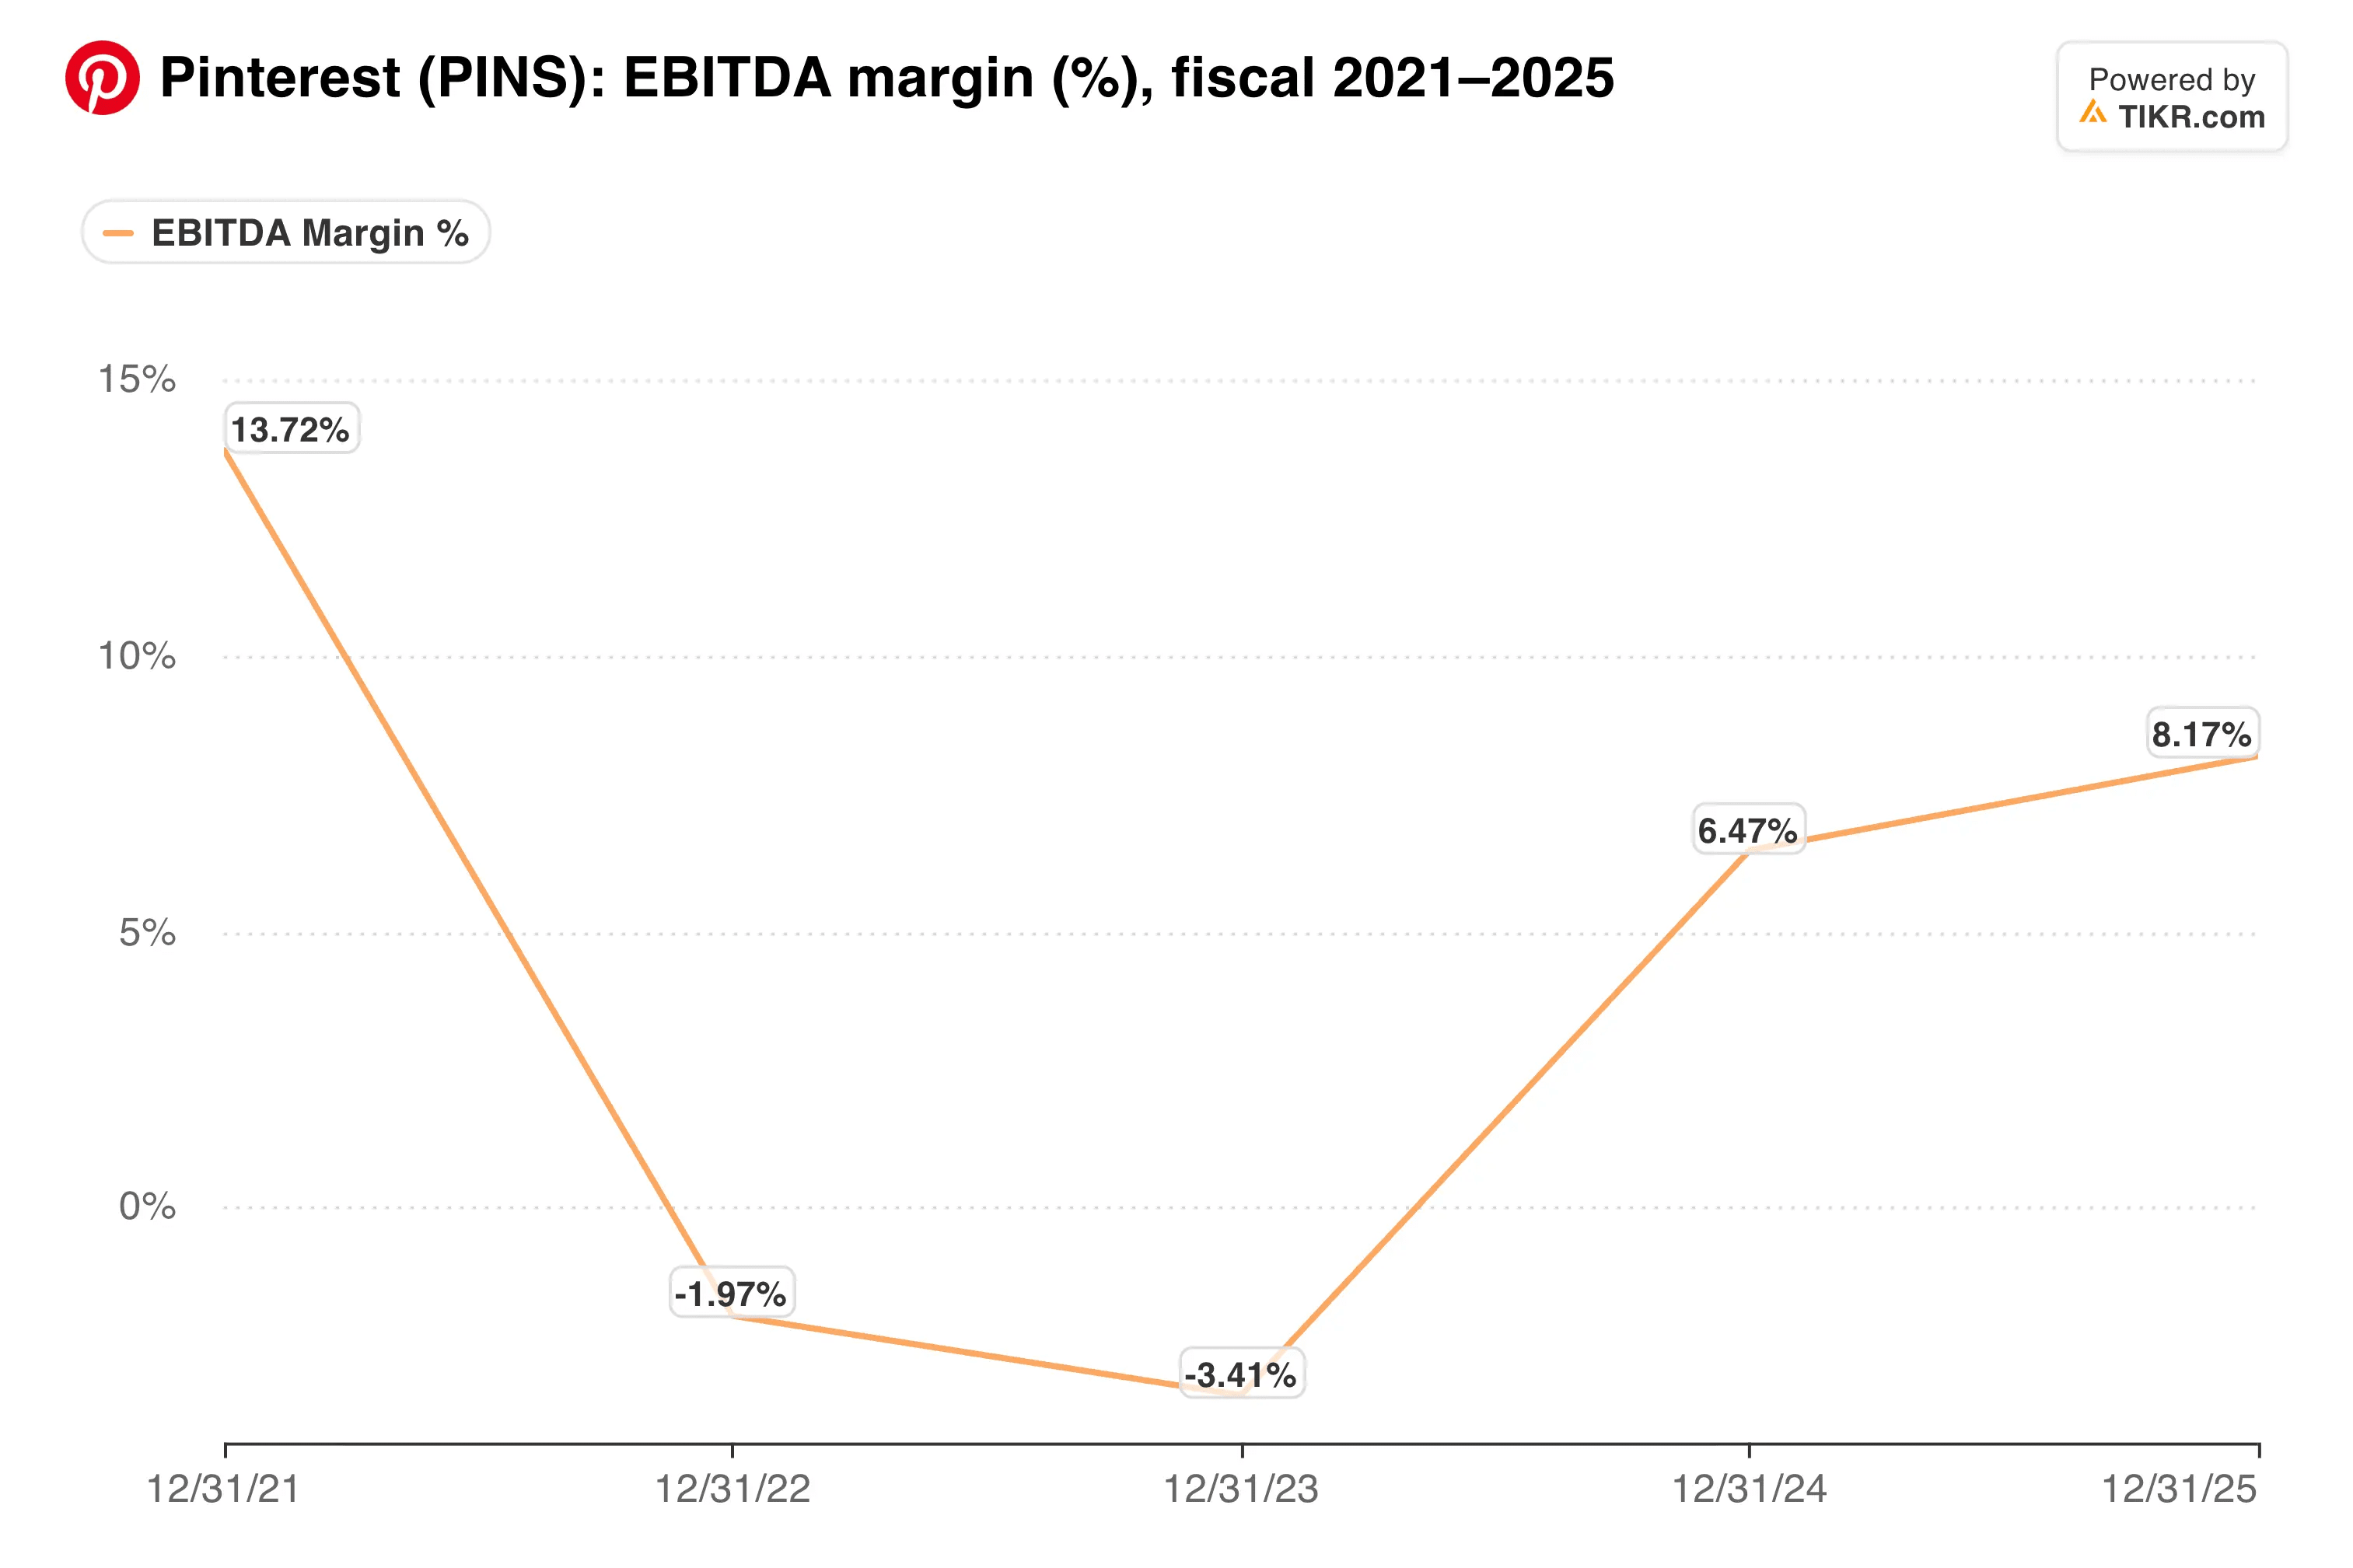
The question for Dibbo is how much of that margin survives once stock comp is counted.
TIKR tracks 39 analysts on Pinterest. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Pinterest, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Pinterest’s Analyst Ratings
Cheap shares, busy sellers
At $21, Pinterest trades at 9.7x forward earnings and 7.75x forward EV/EBITDA. The average Street target of $29 implies about 37% upside.
Management has already voted with cash. Pinterest bought back more than $2 billion of stock this year at an average of $18.17, backed by a $1 billion investment from Elliott Investment Management.
It also expanded its revolving credit facility to $700 million from $500 million in October.
Insiders are moving the other way, though. Co-founder Ben Silbermann has filed a string of share sales near $2 million each since September.
Against larger ad platforms like Meta Platforms (META) and Snap (SNAP), the discount stands out.
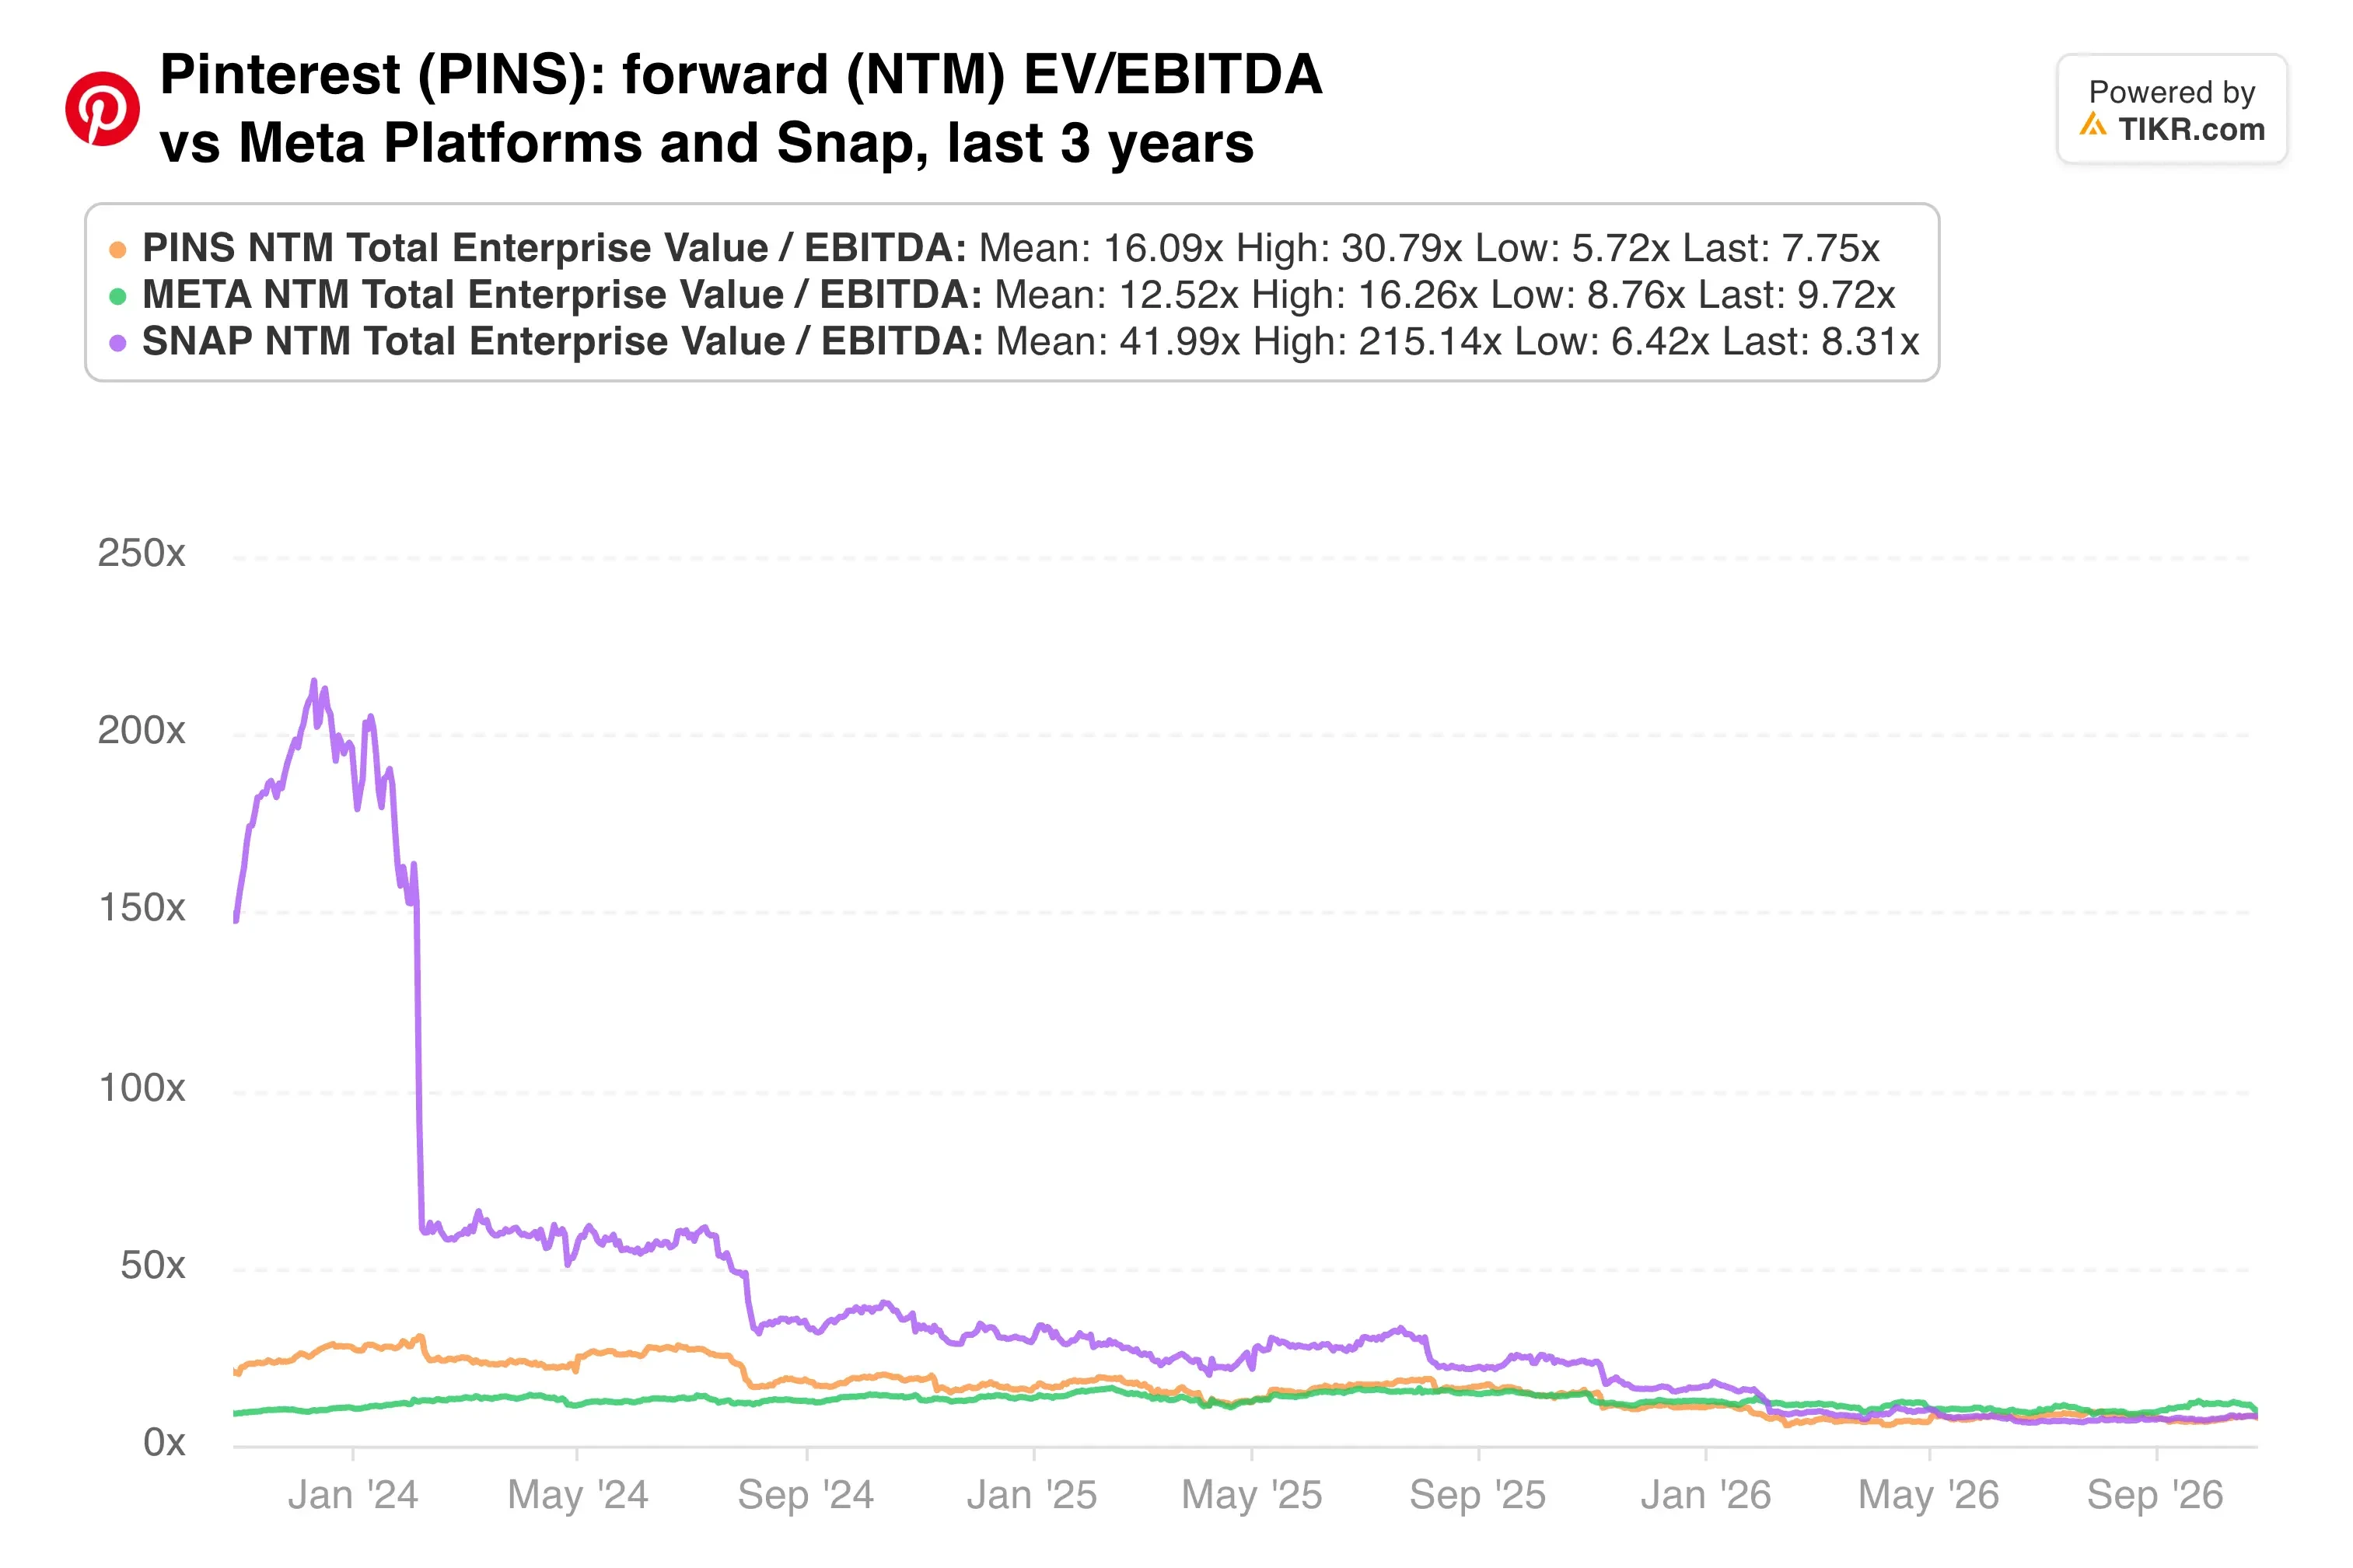
At 7.75x forward EBITDA, investors are pricing Pinterest like a business in decline, even with double-digit growth guidance.
My take: The valuation already assumes a lot can go wrong. What I need Wednesday is Q4 guidance that holds double-digit growth and some early clarity from Dibbo on stock comp. Both would make $21 look too low, while a Q4 guide drifting toward 10% would test the case behind that buyback.
Pinterest reports after the bell on October 29. The Q4 outlook and Dibbo’s first comments on spending will set the tone heading into 2027.
So what is Pinterest stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Pinterest could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!