


Key Takeaways
- AI power stocks, Oklo among them, sold off after Democrats won Congress in the midterms, and NuScale’s CEO said on its Nov. 5 call that the company isn’t reliant on data centers.
- A week earlier, Cameco’s CEO said its strategy rests on the reactors running today, with AI as upside on top.
- Analysts expect Cameco’s revenue to rise about 25% from 2025 to 2028, and its forward P/E has fallen to 47x from 111x in April.
- NuScale’s next step depends on a utility: its partner ENTRA1 still has to sign a power purchase agreement with the Tennessee Valley Authority.
NuScale Power (SMR) wants investors to know it isn’t a data-center stock.
Democrats took Congress in the midterms, and investors sold the AI power trade for a second straight day on Nov. 5, on fears the data-center buildout could stall. Oklo (OKLO) fell 13% that day, and Bloom Energy sank 16%.
NuScale reported its third quarter the same day, and an analyst asked CEO John Hopkins how a slowdown in hyperscaler spending would change his outlook for small modular reactors. Hopkins said it’s “probably too early to tell” where data centers land, “but we’re not reliant on data centers.”
A week earlier, Cameco (CCJ) CEO Timothy Gitzel went further on his company’s third-quarter call:
“Artificial intelligence and data centers can provide meaningful upside, but they are not the foundation of the nuclear investment thesis nor are they a load-bearing assumption in our strategy.”
That’s a bold thing to say in this market.
TIKR tracks 19 analysts on NuScale Power. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on NuScale Power, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See NuScale Power’s Analyst Ratings
Cameco’s numbers back him up
Gitzel’s case starts with the reactors already running, which burn fuel every day whatever the stock market does. Life extensions, restarts, uprates and reactors already under construction add to that. He even granted that data centers being built today will need power before most new large reactors can be delivered, so gas, renewables and storage will meet some of that demand first.
Much of that fuel demand is already under contract. Cameco had 230 million pounds of uranium committed to 39 customers at the end of 2025, according to its annual report, and analysts expect its revenue to climb from C$3.48 billion in 2025 to C$4.34 billion in 2028:
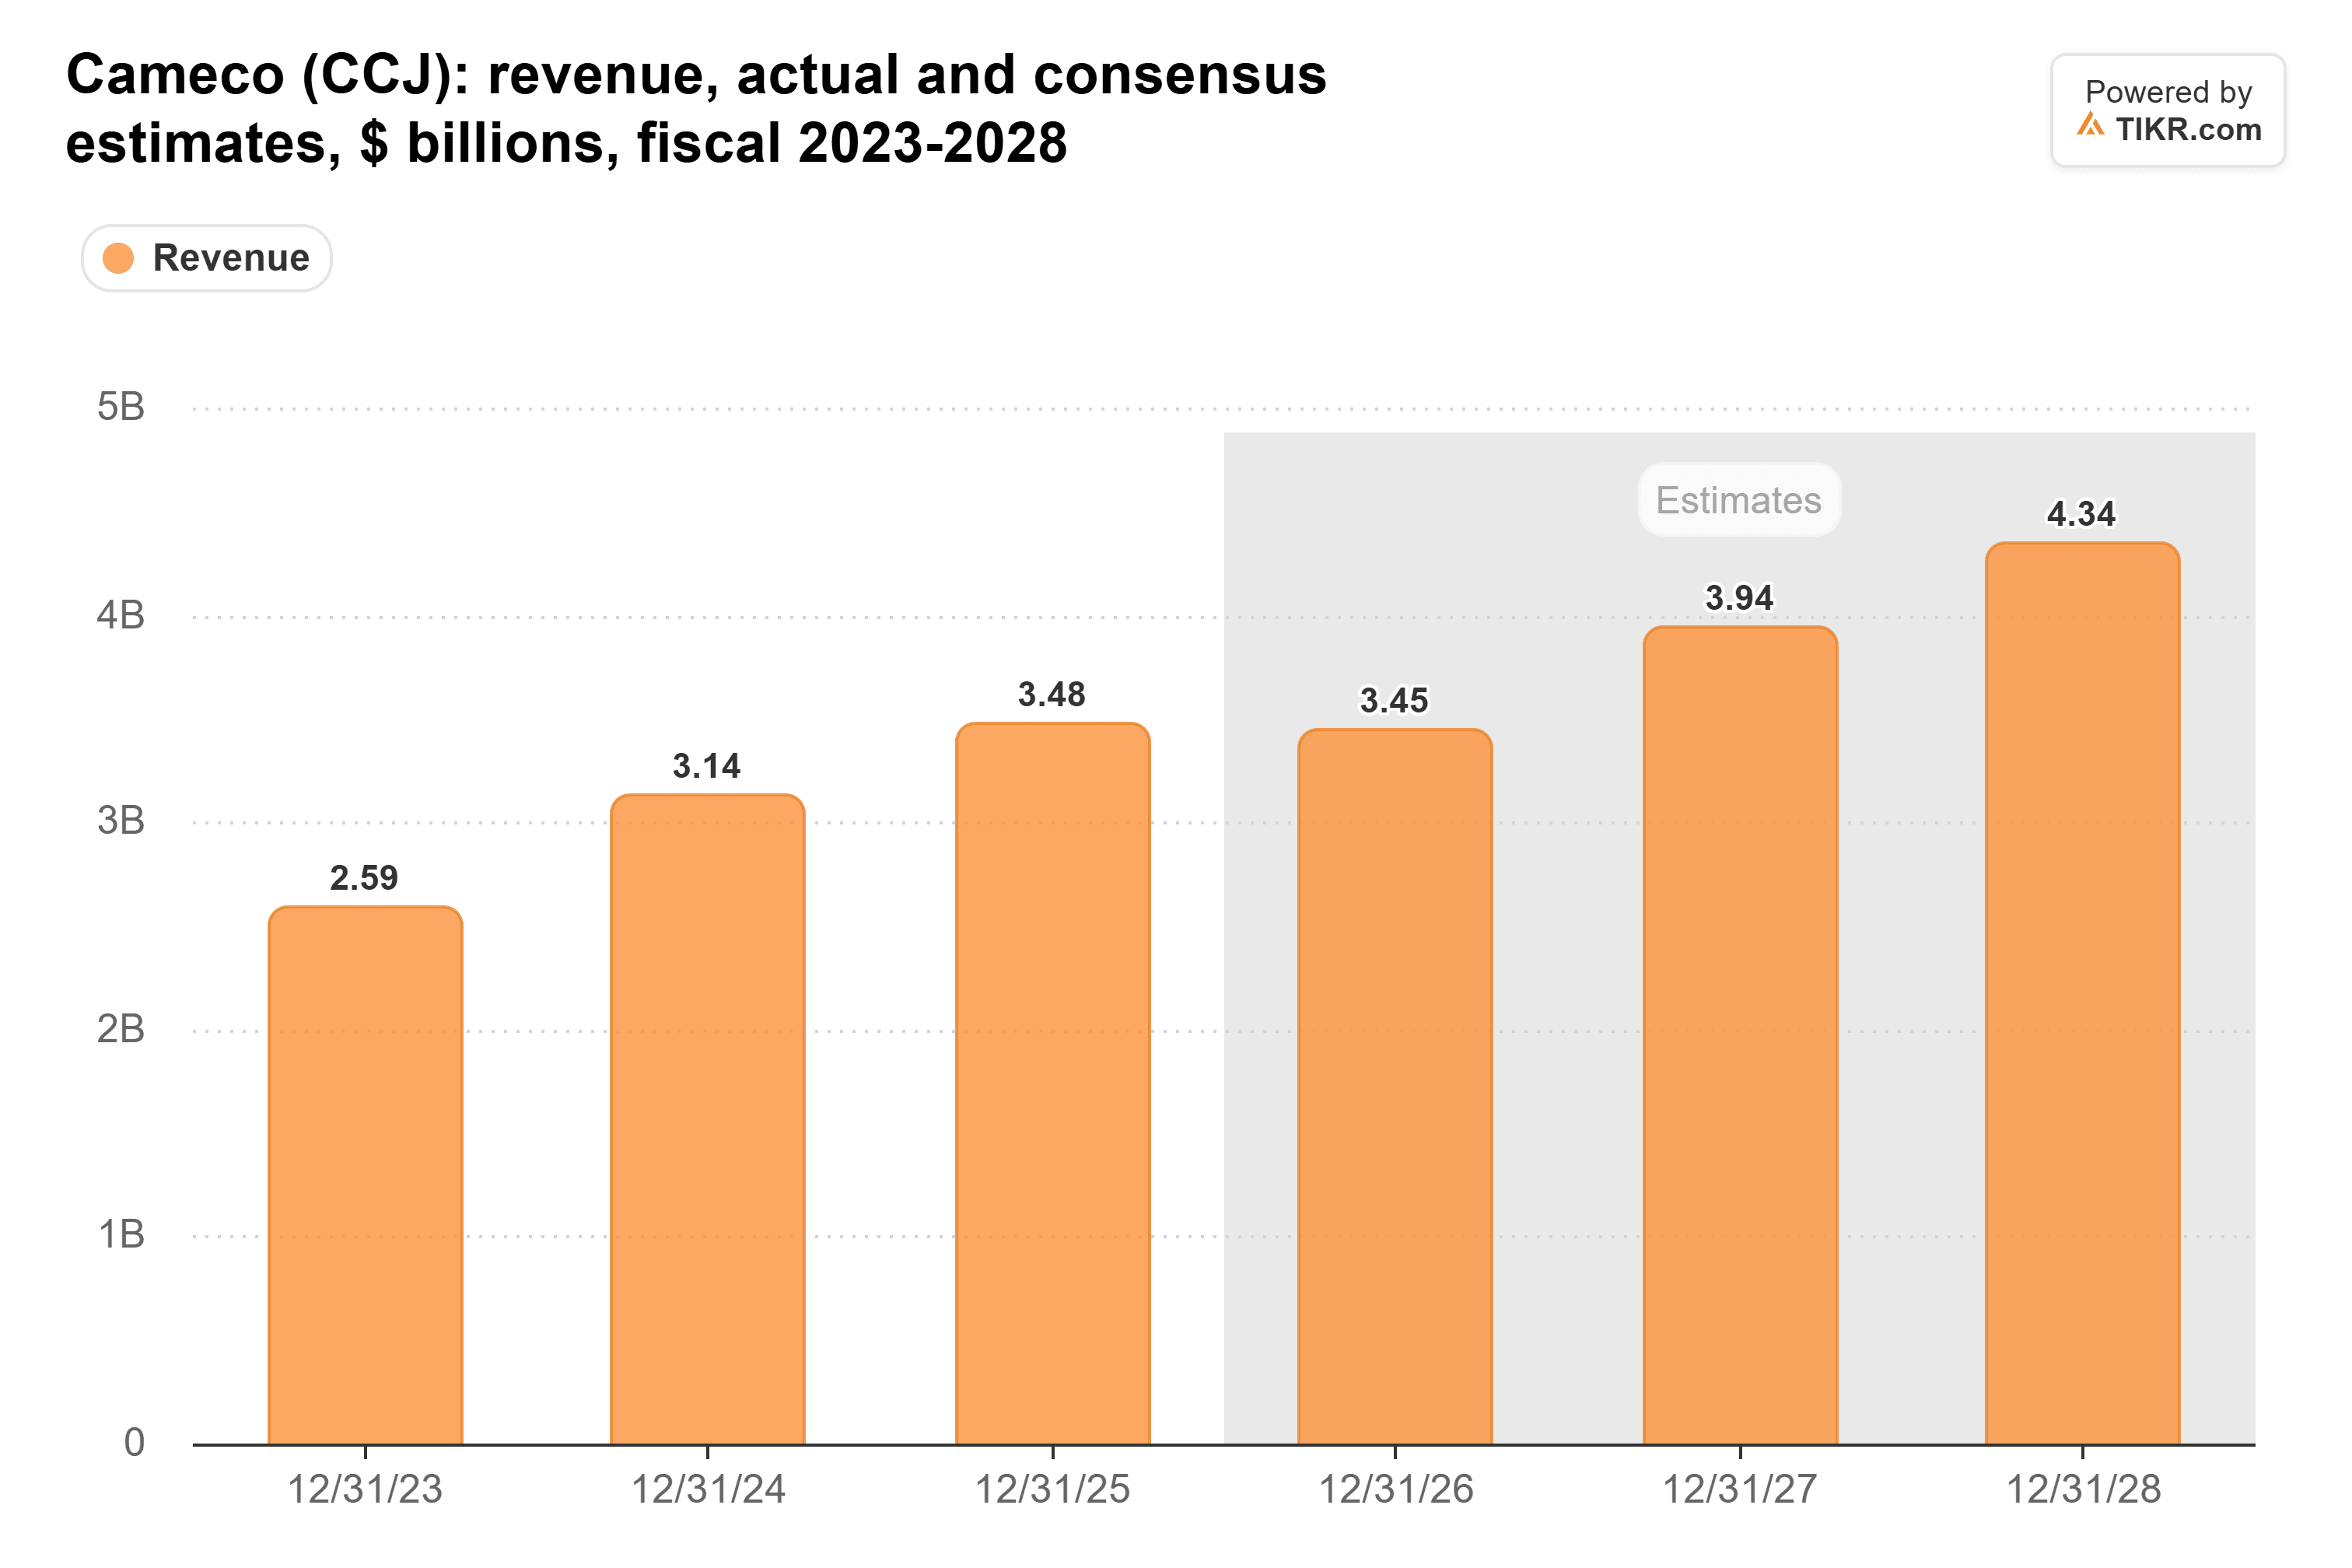
(This year’s estimate is a touch below 2025’s, after an extended shutdown at its Key Lake mill cut third-quarter production 20%.)
NuScale is counting on a utility
NuScale’s claim holds up too, for a simpler reason: it barely has revenue yet. It brought in $0.3 million in the third quarter, down from $8.2 million a year earlier, according to its third-quarter release, and ended September with $1.9 billion in cash and investments.
Analysts expect that to change fast, with revenue jumping from $20.4 million in 2026 to $127 million in 2027 and $236 million in 2028:
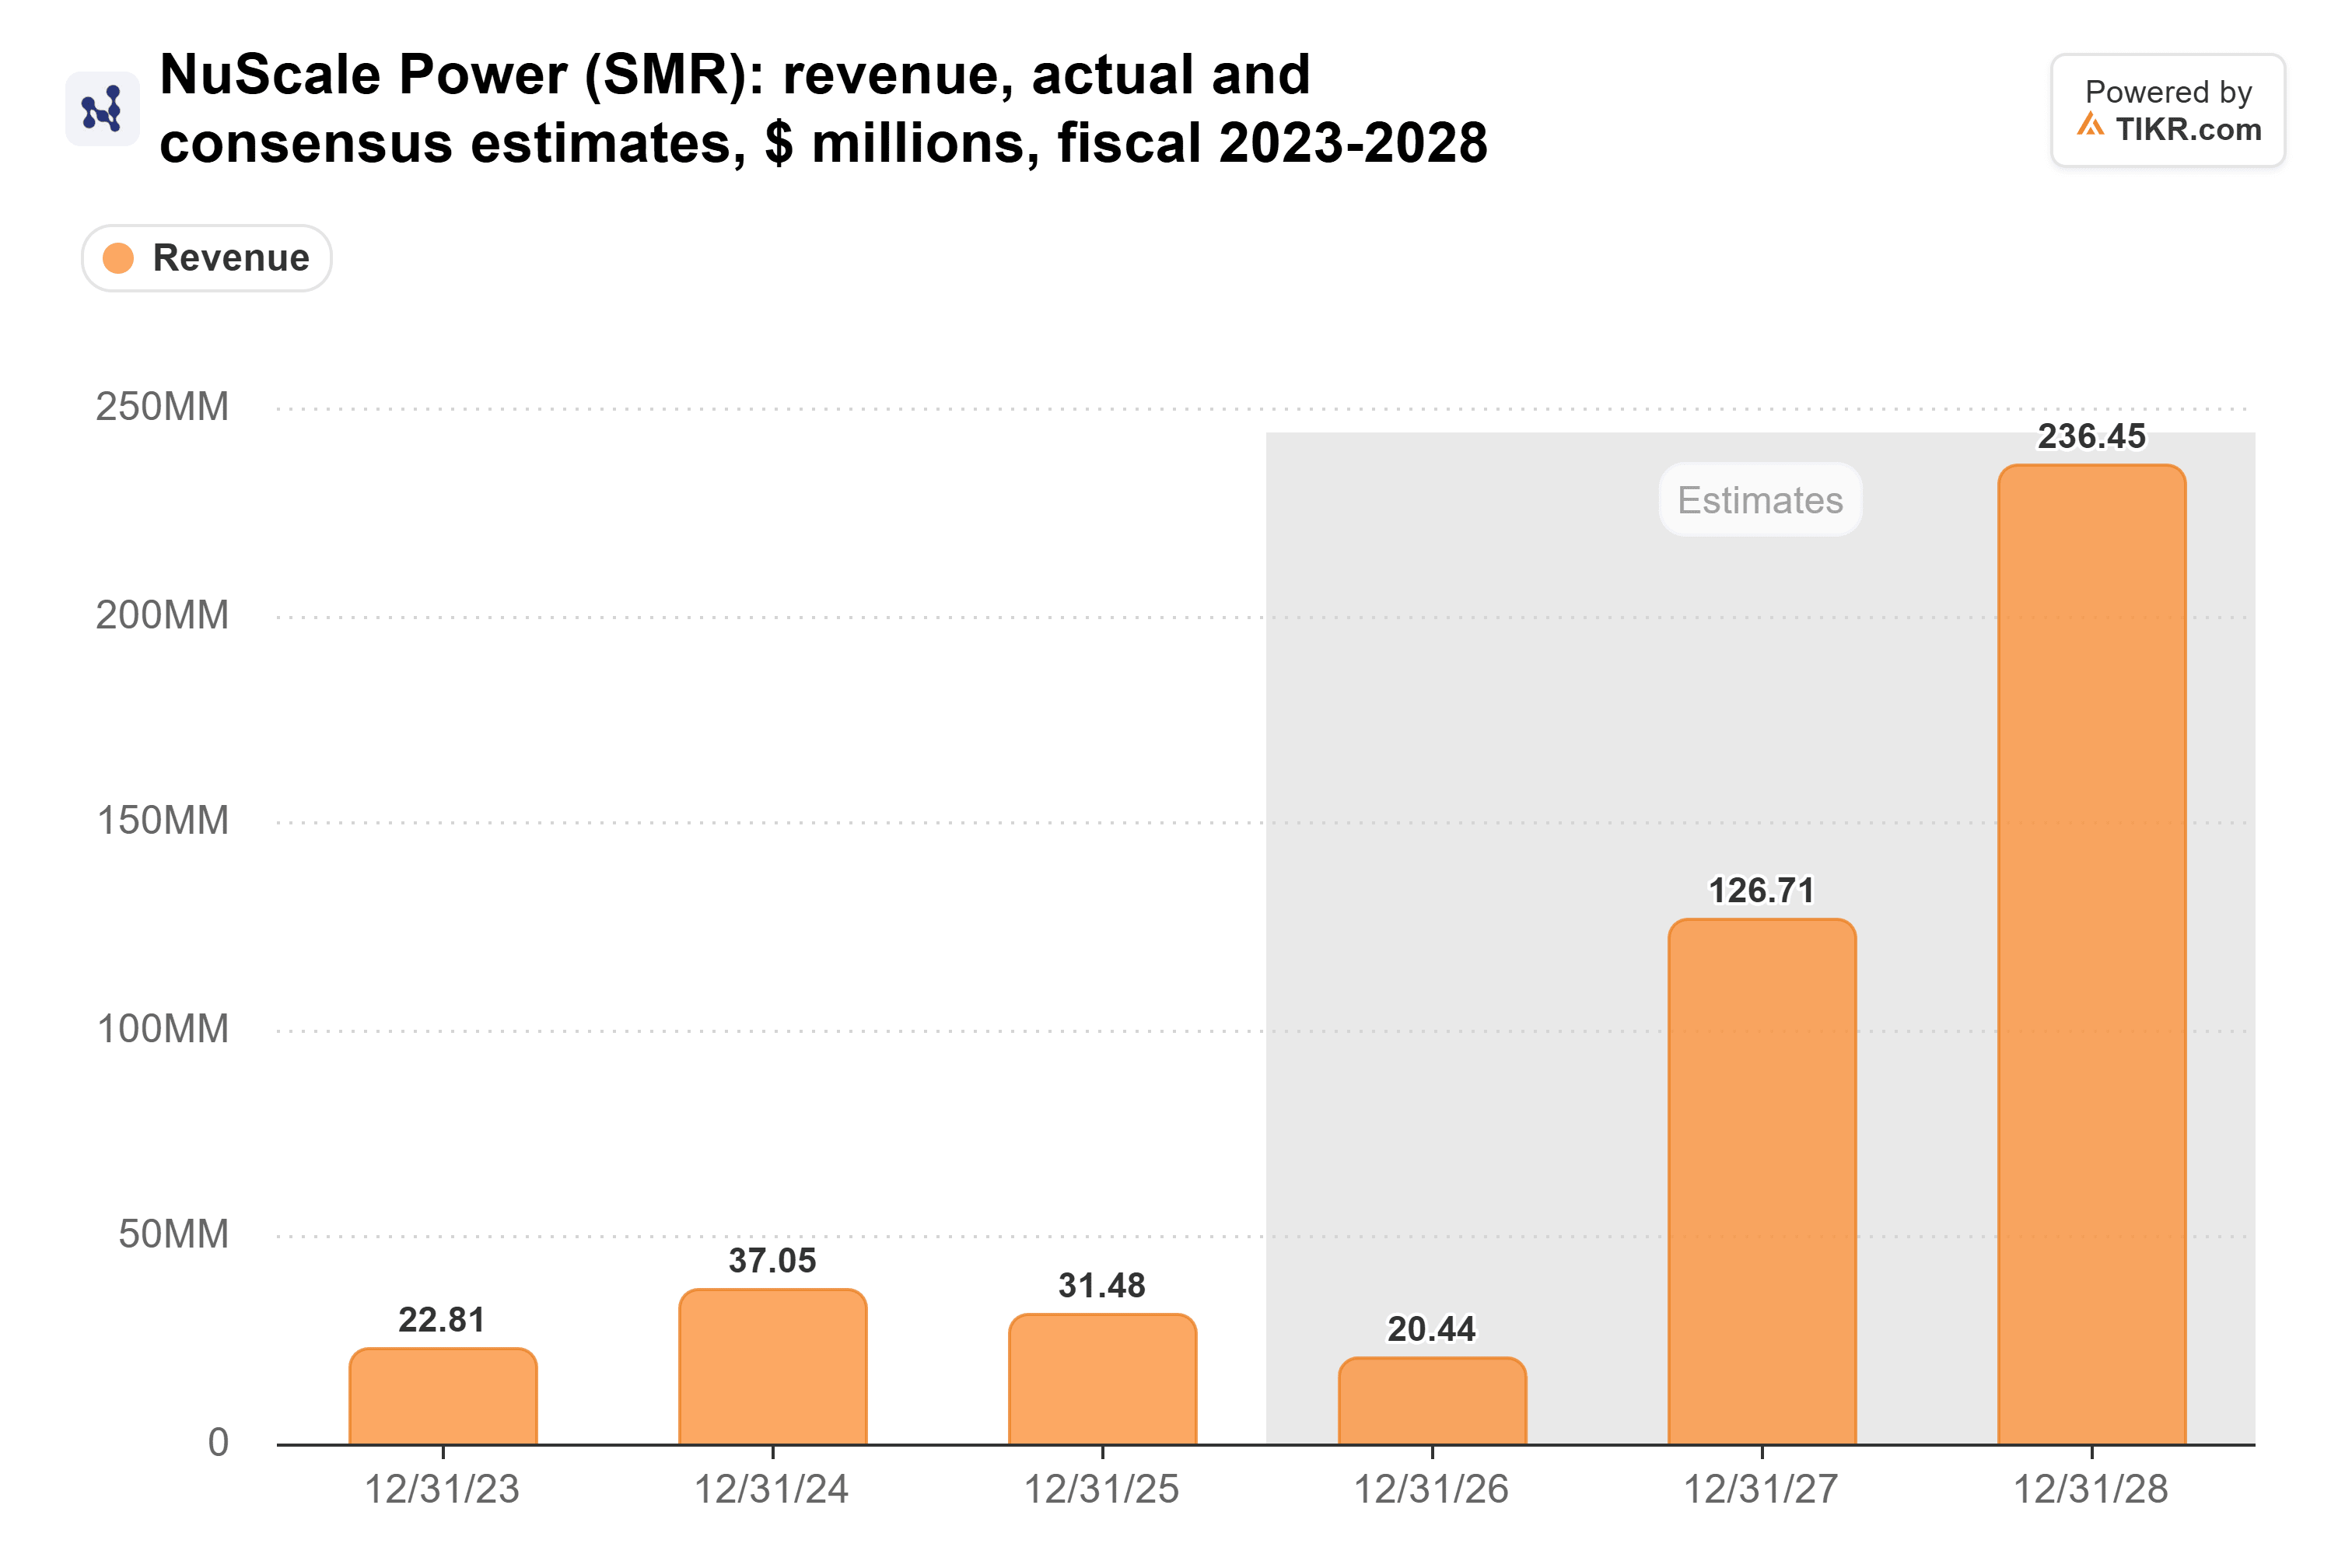
That ramp needs module orders, and the nearest ones depend on the Tennessee Valley Authority. NuScale’s partner ENTRA1 is negotiating a power purchase agreement with TVA, and Hopkins said NuScale will move straight into license work and long-lead parts once it’s signed. Management added that the agreement itself isn’t a module sale: that comes later, with an OEM agreement between NuScale and ENTRA1.
Hopkins doesn’t expect the midterms to change much, either. For the most part, he said, “both the Ds and the Rs are pro-nuclear.” Voters agree: 59% of Americans favored more nuclear power plants in Pew Research Center’s 2025 survey, up from 43% in 2020.
The market still trades them as AI stocks
None of that stops investors from lumping these stocks in with the data-center trade. Gitzel said as much himself: “Capital can easily rotate out of a theme in a day or in a week.”
Cameco’s multiple shows how far that can go. Its forward P/E hit 111x in April and has since fallen to 47x, below its three-year average of 61x:
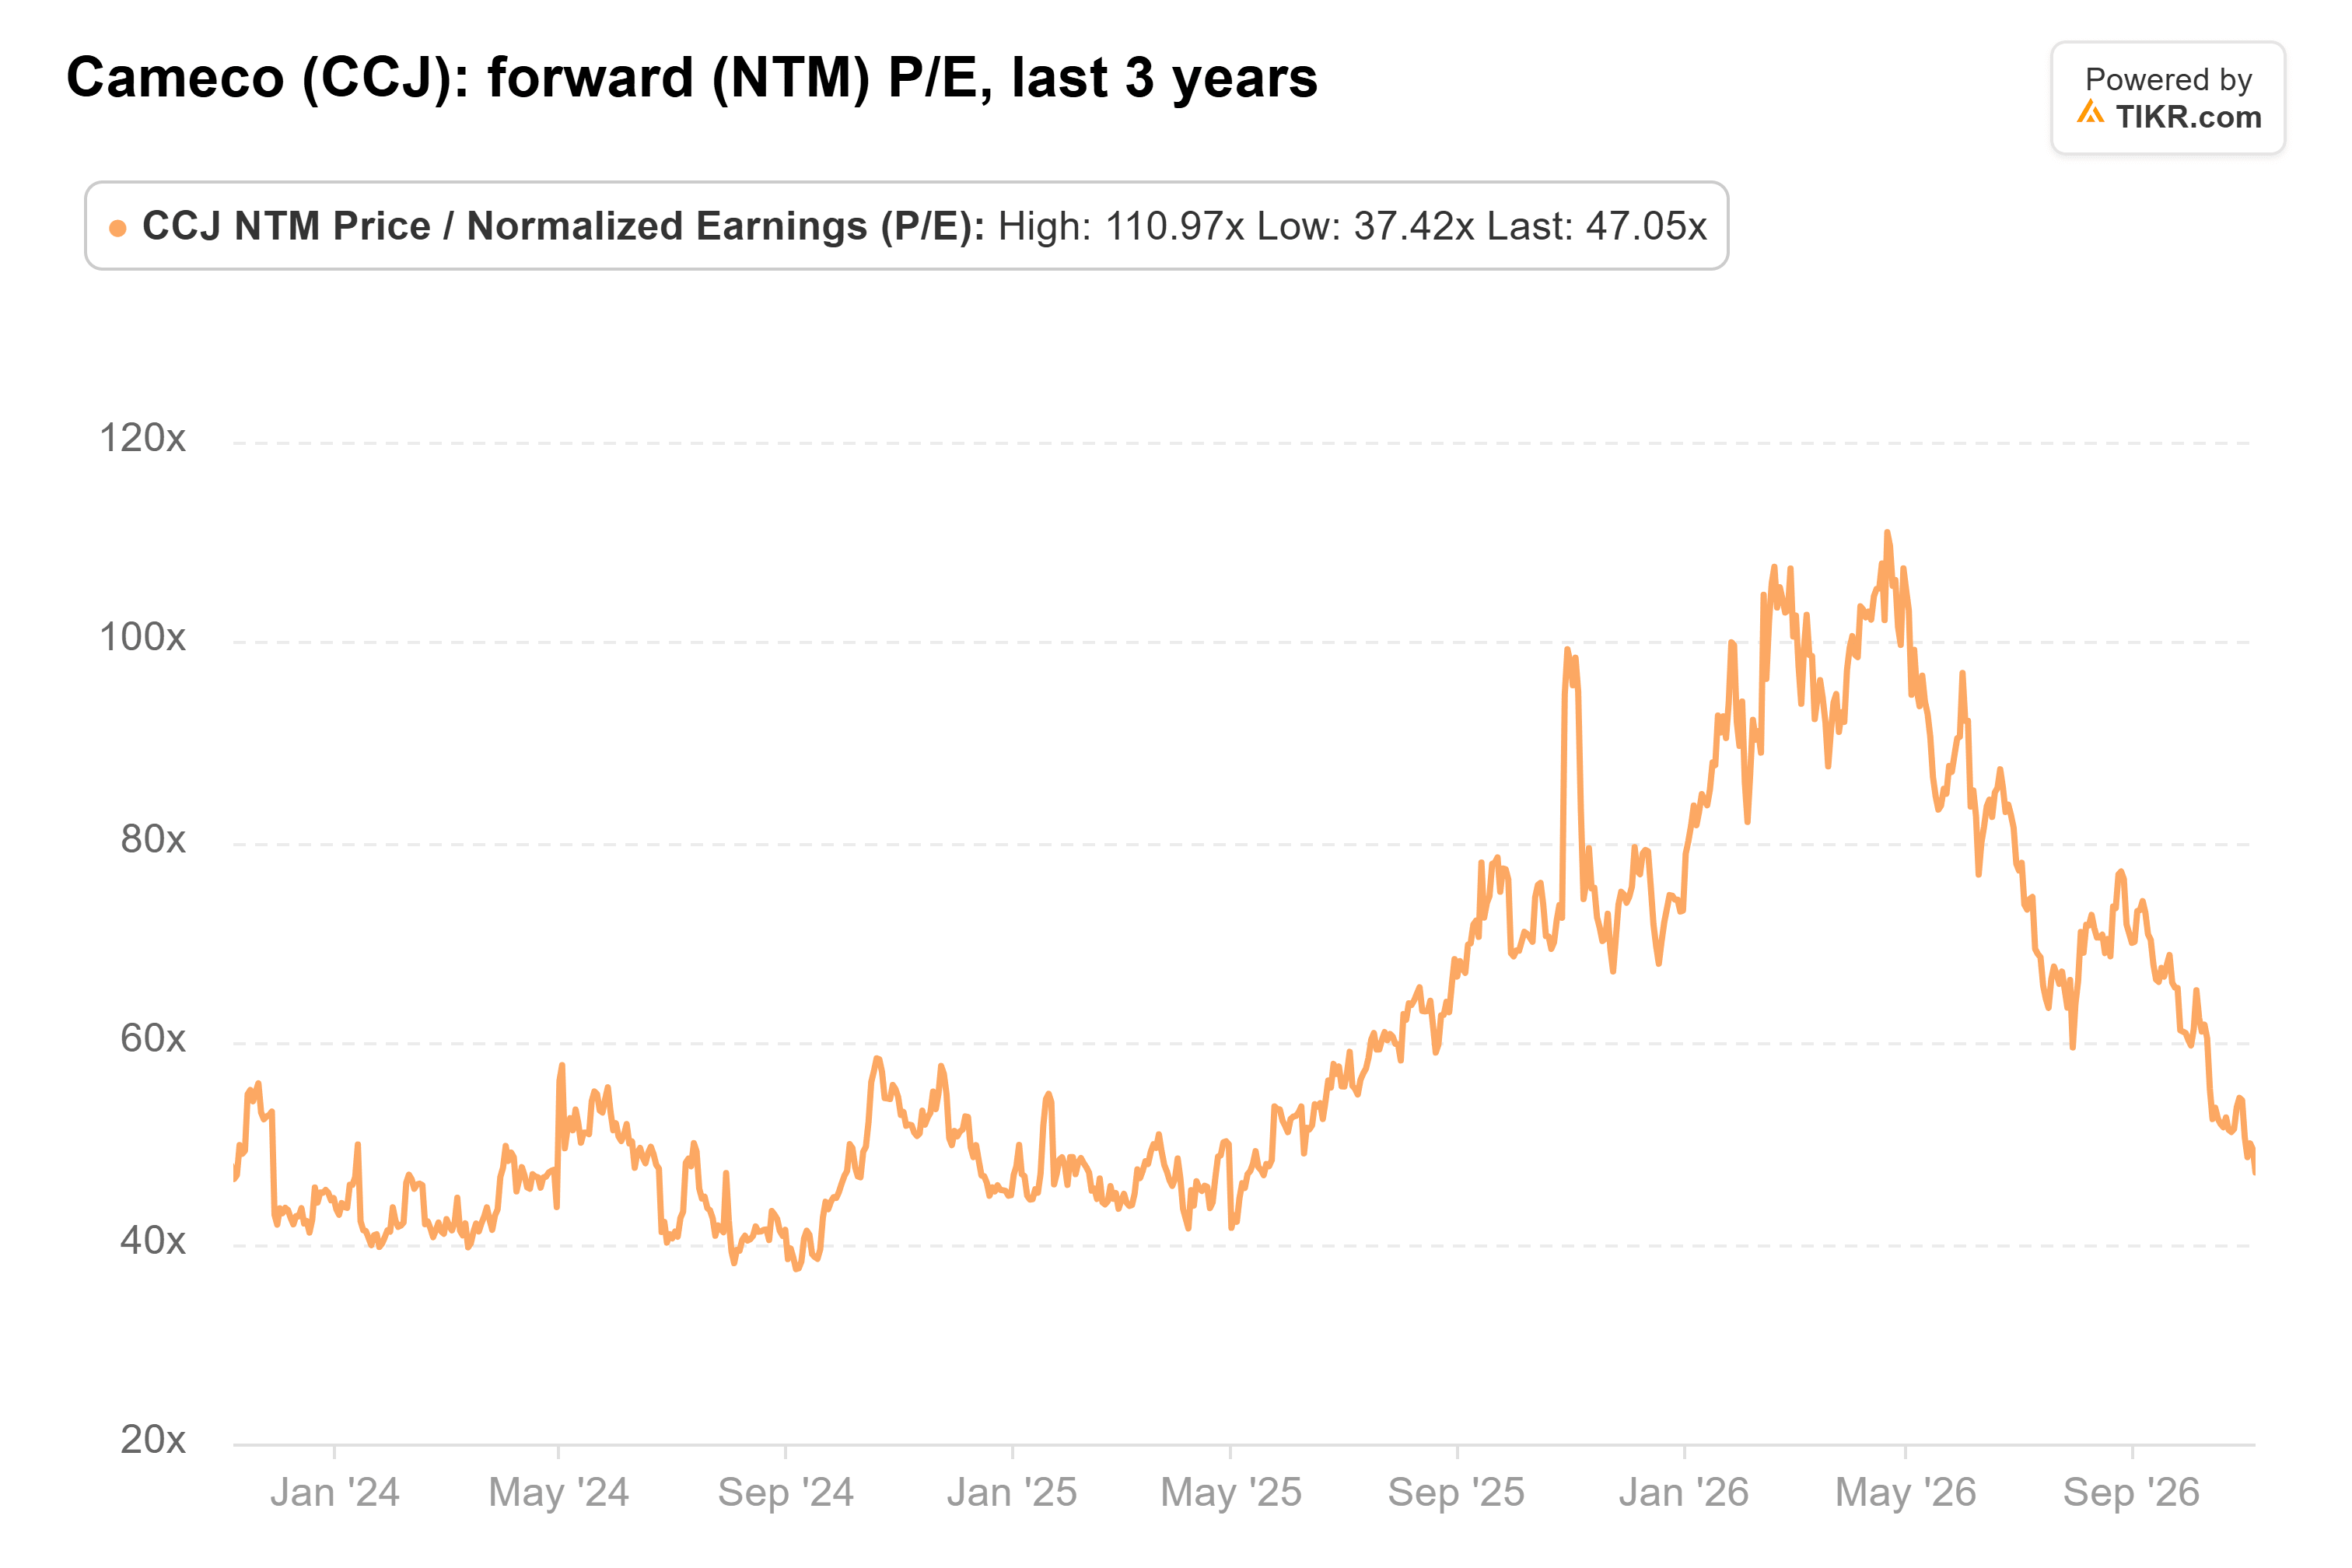
My read: most of the AI premium has already come out of Cameco’s stock, and what’s left rests on those fuel contracts.
Oklo is another matter, since it has far more riding on the buildout. Analysts expect losses of $0.98 a share this year and $1.06 next year, and the question for its own report is whether any of its data-center deals turns into a binding power contract.
The selloff got Cameco wrong
The way I see it, investors sold Cameco as if its plan hangs on data centers, and both its CEO and its estimates say otherwise.
As for NuScale, Hopkins is right that data centers aren’t what it’s waiting on. But with almost no revenue today, NuScale is a bet on TVA signing, which makes it the far riskier of the two.
Of course, if the TVA agreement slips, analysts would likely cut their 2027 estimates first.
So what is NuScale stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what NuScale could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!



