


Key Takeaways
- Anthropic’s amended S-1 shows third-quarter revenue up about 47% from the second quarter, while compute and infrastructure expenses rose about 78%.
- Jason Lemkin says Anthropic’s net new bookings fell in the third quarter, even though the company has committed $895 billion to compute.
- Broadcom has the largest share of those commitments at $161 billion, ahead of Alphabet’s Google at $121 billion and Amazon at $110 billion or more. Broadcom also guarantees part of the financing behind Anthropic’s chips.
- Broadcom trades below its five-year average forward P/E, but its growth plan still depends on Anthropic going public.
Broadcom (AVGO) has an Anthropic problem:
A customer it’s counting on for much of its growth is adding new business more slowly. That’s happening just as this week’s market correction raises doubts about Anthropic’s IPO.
Anthropic’s amended S-1 lists $895 billion of purchase and lease commitments for computing power. According to The Kobeissi Letter’s breakdown of the filing, the biggest share, $161 billion, goes to Broadcom. Google, owned by Alphabet (GOOG), is next at $121 billion, and Amazon (AMZN) has at least $110 billion.
On this week’s episode of 20VC, SaaStr founder Jason Lemkin was talking about the swings in AI stocks. He pointed to something he was surprised more people hadn’t noticed:
“Anthropic had a down quarter from net new revenue. It was down in this last quarter in terms of net new bookings over Q2.”
That’s uncomfortable news for the company at the top of that list.
Costs are outrunning revenue
Anthropic’s revenue is still climbing quickly. The amended S-1 shows $16.96 billion of third-quarter revenue, up about 47% from the second quarter.
But compute and infrastructure expenses rose about 78% over the same three months. Through the second quarter, revenue had been growing faster than those costs, so the third quarter reversed that pattern.
And half of those commitments come due within about four years: Anthropic expects to incur $448 billion of them by the end of 2030.
TIKR tracks 51 analysts on Broadcom. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Broadcom, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Broadcom’s Analyst Ratings
Broadcom has the most riding on it
Anthropic sits at the center of Broadcom’s AI plan. Management expects AI chip revenue to roughly double from $58 billion in fiscal 2026 to about $115 billion in fiscal 2027, then double again to $230 billion in fiscal 2028. Its outlines give Anthropic 5 gigawatts of capacity in 2027 and 10 more in 2028. That’s half of the roughly 30 gigawatts Broadcom sees across those two years.
Analysts expect Broadcom’s total revenue to more than quadruple from fiscal 2025 to fiscal 2028.
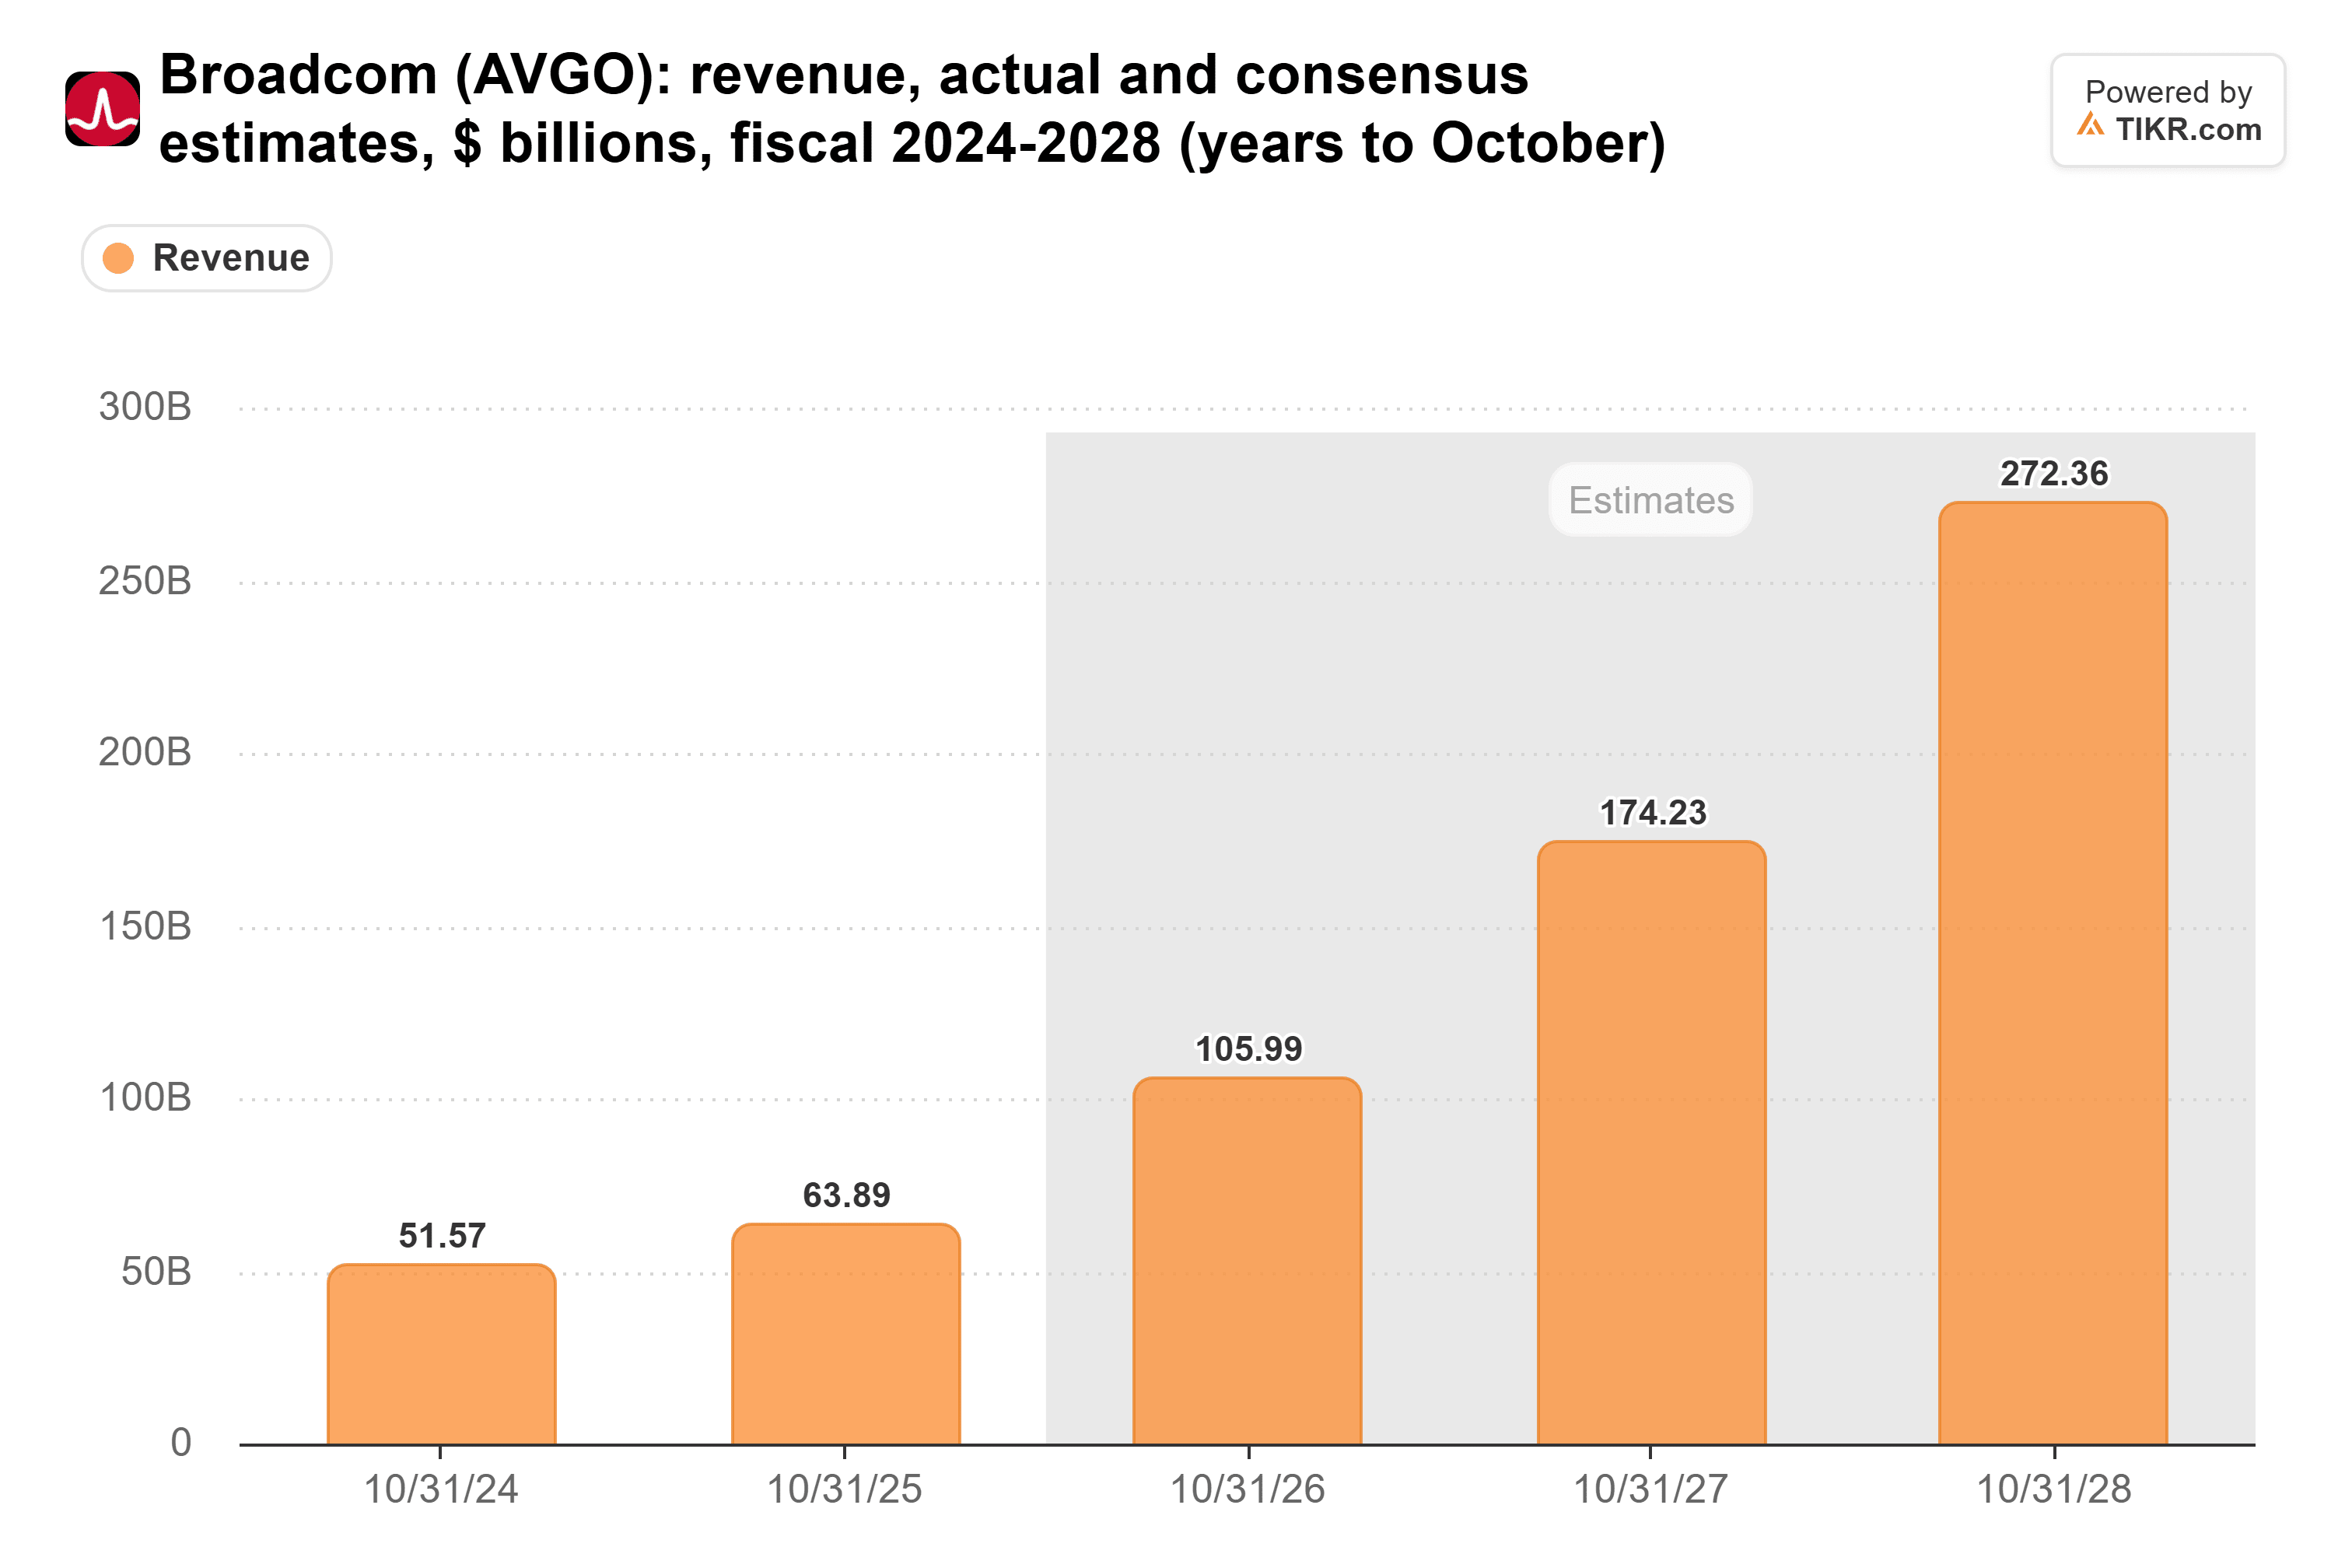
Management’s AI outlook alone accounts for about two-thirds of the fiscal 2027 estimate, so these numbers depend more on Anthropic’s pace than on anything else. One slower bookings quarter at Anthropic shouldn’t move them on its own. A second one would.
Broadcom is also helping pay for those chips. It guarantees up to about $29 billion of leases from the first financing tranche. A Broadcom filing last week put its maximum potential liability on a second package, worth $63 billion, at about $43 billion. Broadcom had $24.0 billion of cash at Aug. 2, and it calls the chance of a payout low.
Lemkin called Broadcom having to guarantee Anthropic’s debt “a little wobbly.” That’s hard to argue with.
The market has already marked Broadcom down for some of this. On Nov. 2, it traded at 19x forward earnings. That’s well below its five-year average of 24x and far from its peak of 49x last December.
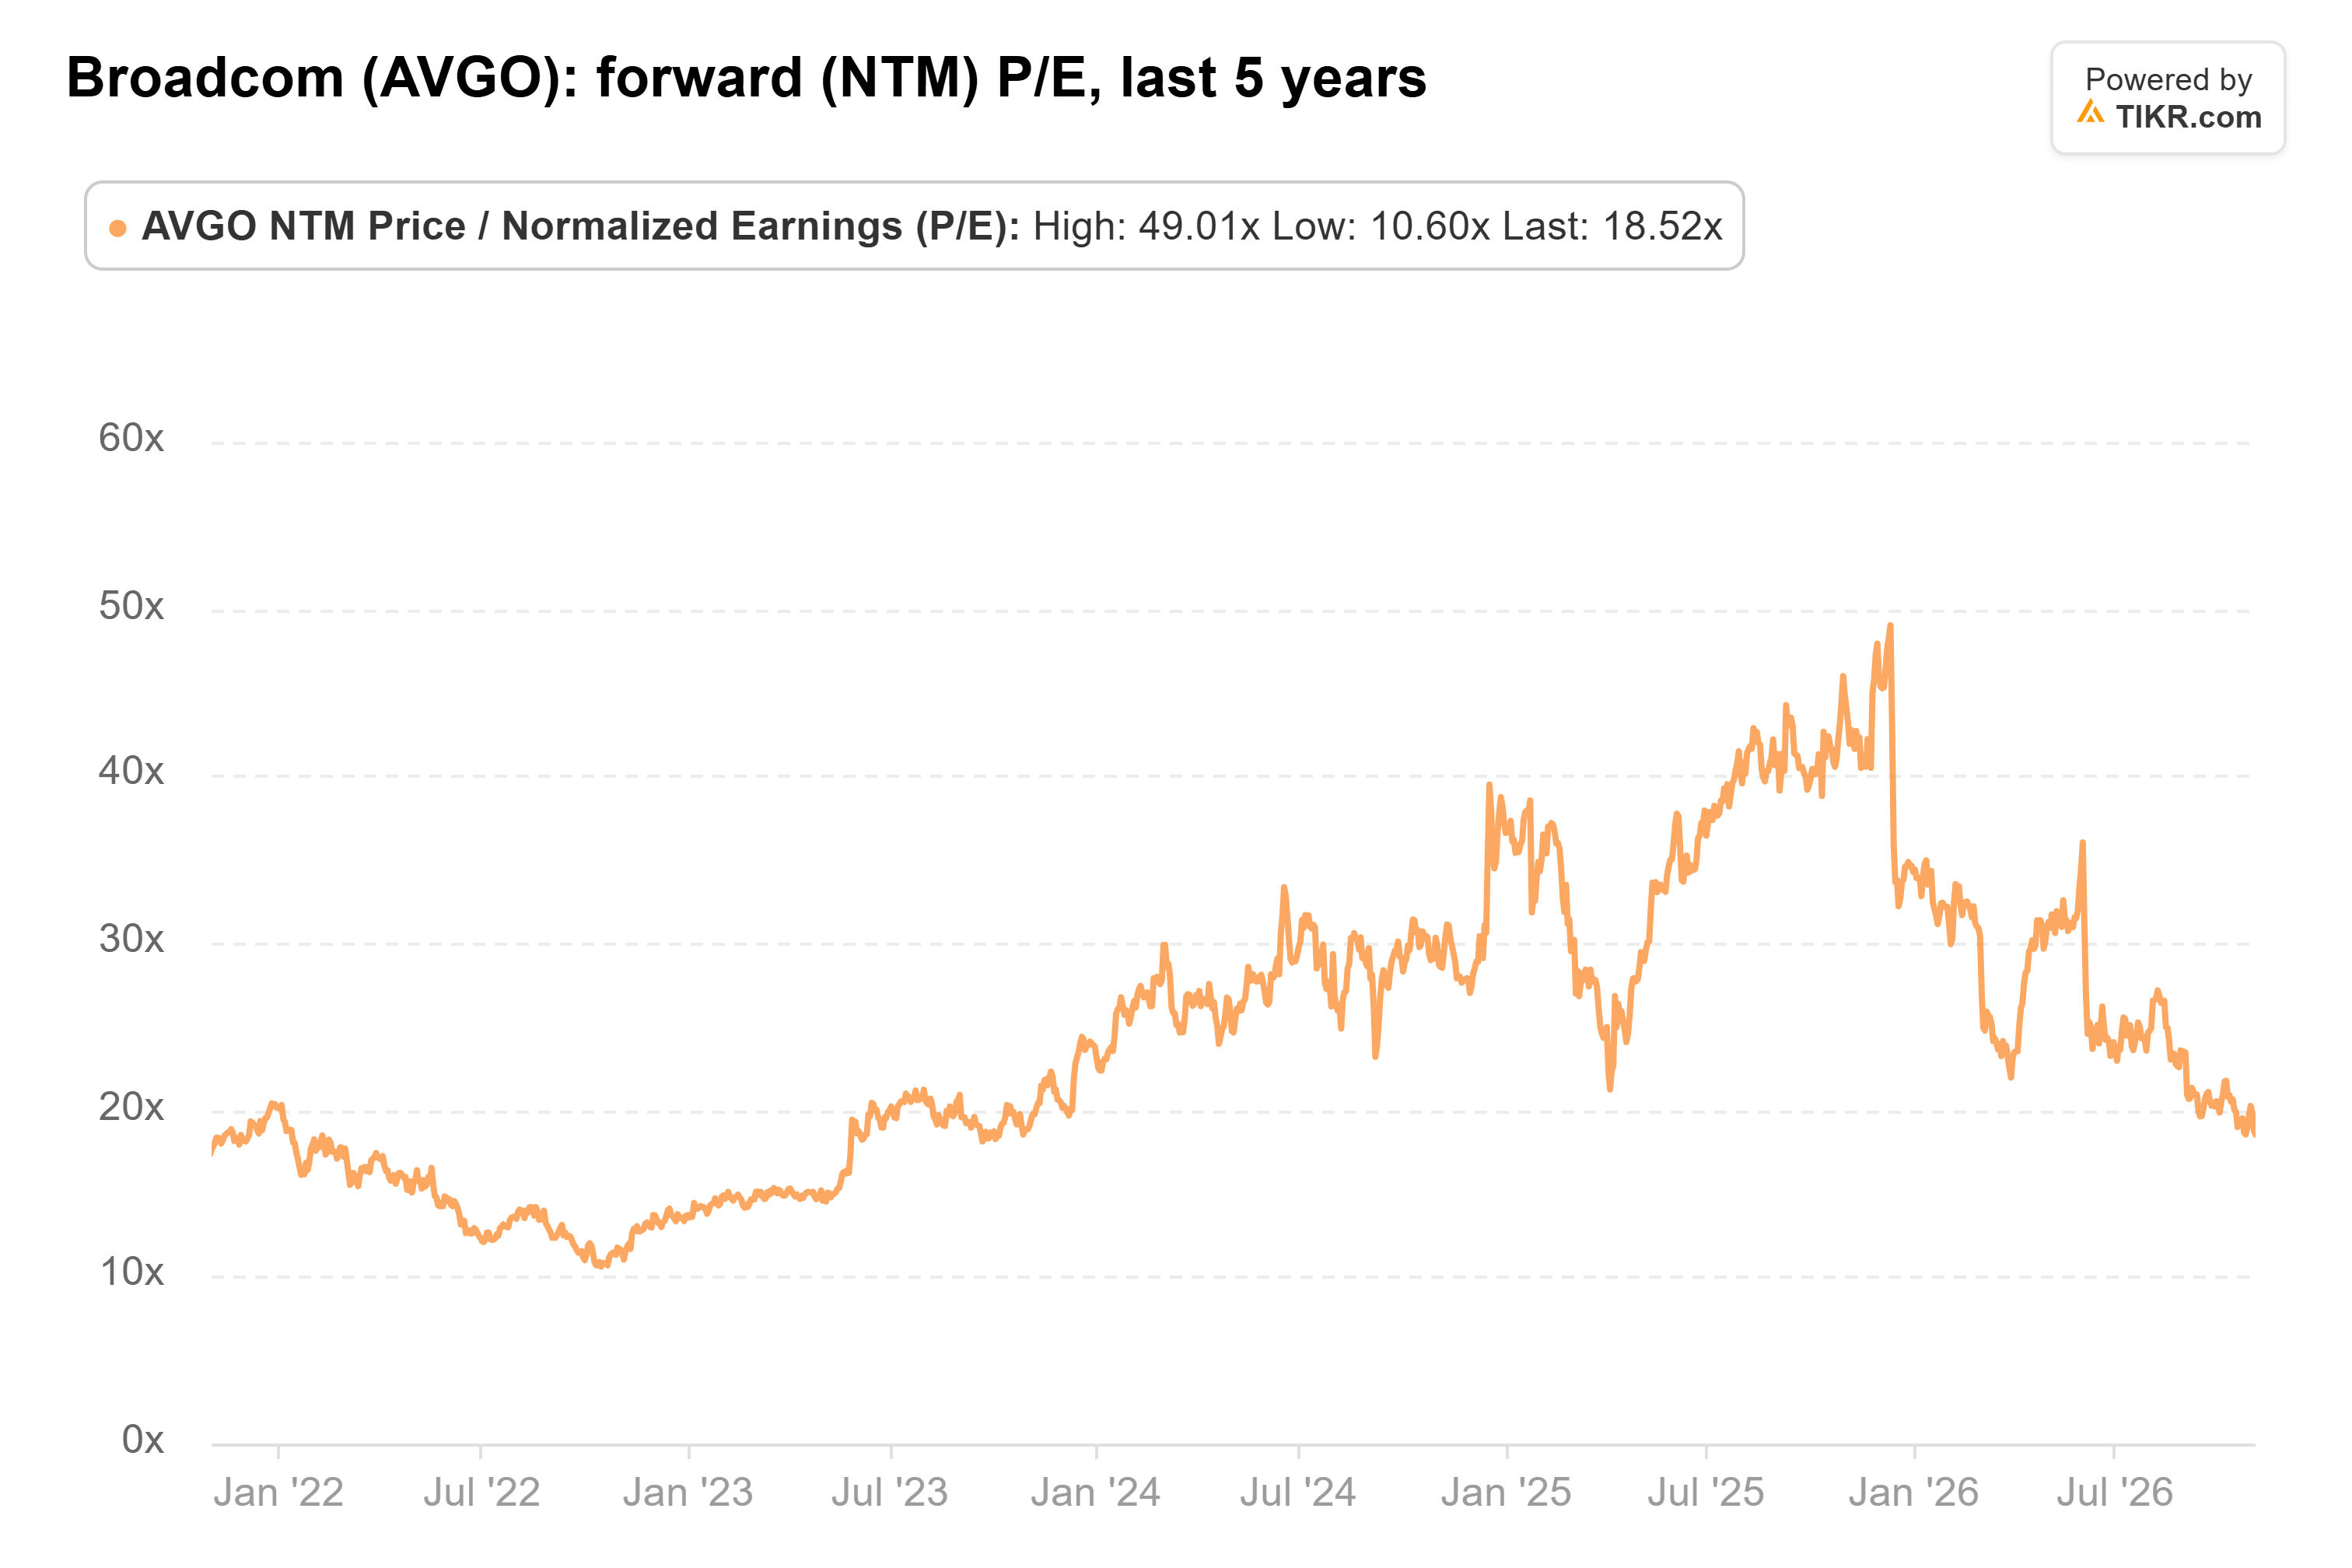
After this week’s 9% drop, the multiple is even lower today.
Google and Amazon have more cushion
Google’s $121 billion is a big number even for Alphabet, whose capital spending nearly tripled from $32.3 billion in 2023 to $91.5 billion in 2025.
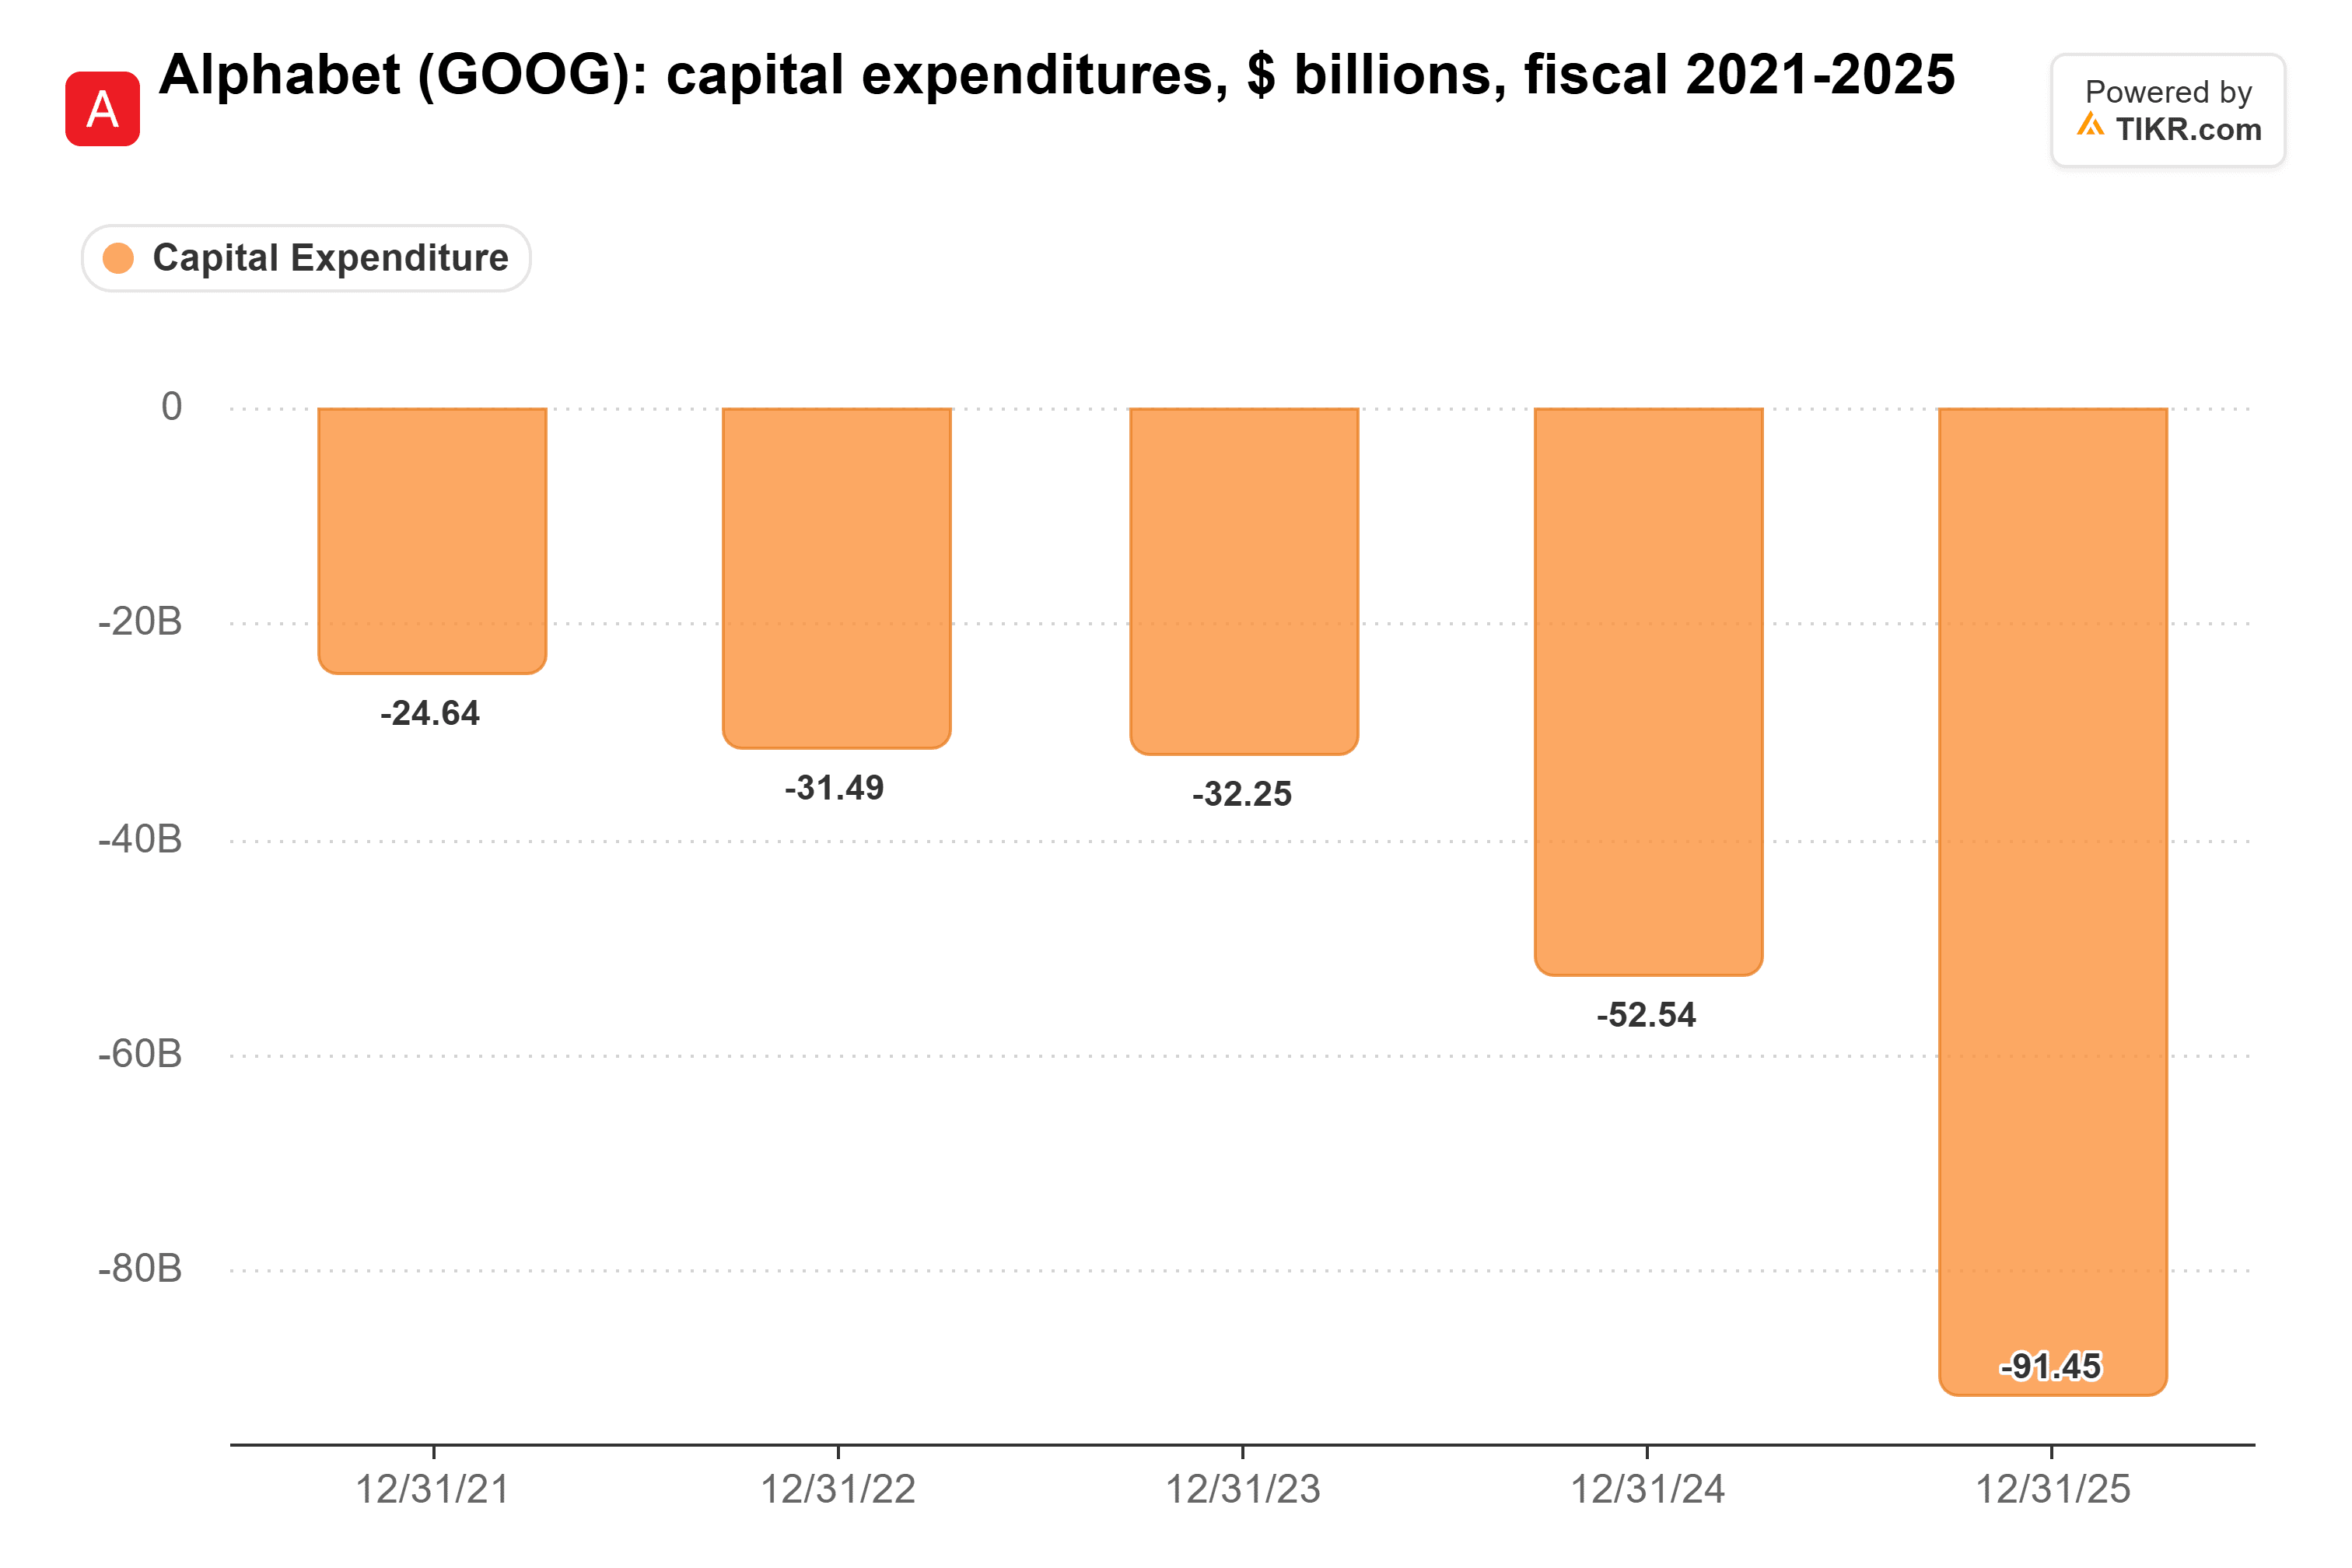
Anthropic’s commitment to Google alone is bigger than that whole year of spending. Still, neither Alphabet nor Amazon guarantees the financing behind its own sales the way Broadcom does.
And part of Google’s share flows back to Broadcom anyway. The Kobeissi Letter counts up to $150 billion more in estimated spending on Google’s AI chips, and Alphabet’s TPU and networking supply agreement with Broadcom runs through 2031.
Demand hasn’t broken
None of this means Anthropic’s customers are walking away. Its third-quarter revenue was up 1,127% from a year earlier. Its IPO filing also showed $131 billion of cash and equivalents, against about $70 billion of commitments due over the next 12 months.
The catch is that Anthropic signed those commitments expecting revenue to keep growing faster and faster. Lemkin’s down quarter is the first sign that growth might be slowing. A public listing would put far more money behind Broadcom’s biggest customer. That would make Broadcom’s guarantees much less likely to matter.
That’s why the IPO doubts sting. Gary Marcus, the cognitive scientist and longtime AI critic, wrote on X that given the size of the commitments and this week’s correction, “Anthropic’s IPO is surely somewhat threatened, and $2T as a valuation is probably off the table.”
The way I see it, Broadcom’s discount to its own history makes sense. I wouldn’t pay up for the stock until Anthropic is public and Broadcom’s guarantees start to shrink.
Of course, Broadcom gets its own say on Dec. 9, when it reports fiscal fourth-quarter results. If management stands by its fiscal 2027 AI outlook, I’d take that as a sign that Anthropic’s orders are holding up.
So what is Broadcom stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Broadcom could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!




