Key Takeaways
- Broadcom’s new backstop on a $63 billion Anthropic rack financing carries a maximum potential liability of about $43 billion, on top of an earlier $29 billion backstop.
- AI semiconductor revenue rose 221% to $16.7 billion last quarter, and management targets $115 billion of AI revenue in fiscal 2027.
- The stock fell 5.5% Friday in a chip rout and now trades at 18.7x forward earnings, the same multiple as Meta.
- The December 10 report needs $21.7 billion of AI revenue and gross margin holding near 73%.
Broadcom (AVGO) sells the custom chips inside the AI boom. Increasingly, it also stands behind the debt that pays for them.
In a filing this week, Broadcom disclosed a backstop on AI rack leases for Anthropic with a maximum potential liability of about $43 billion. The stock fell 5.5% on Friday to $326. Intel (INTC) set off a chip rout that day with a weak PC outlook, putting itself on course for its worst day ever. Broadcom now sits 34% below its 52-week high of $495.
Demand looks solid. Alphabet (GOOGL) has a TPU and networking supply agreement with Broadcom running through 2031, and OpenAI plans to buy Google’s AI chips too. So the open question is who carries the risk if a customer stumbles.
Inside the $43 billion backstop
Bank of America, Citigroup, Morgan Stanley and Blackstone lined up $63 billion to buy Broadcom’s AI racks through a special purpose vehicle that leases them to Anthropic. Deliveries begin in 2027.
Broadcom’s role is residual value support:
- If the customer defaults, Broadcom covers any shortfall between 72.5% of the outstanding lease amount and what the racks fetch on sale.
- Exposure rises as racks deploy and falls as lease payments come in.
- Broadcom calls the probability of a payout low.
This is the second deal of its kind. The first, a $35 billion tranche from June, carries a backstop of up to $29 billion at an 85% threshold. Together, that’s roughly $72 billion of maximum exposure by my math, and Broadcom is reportedly weighing more than $50 billion of financing to help OpenAI buy chips.
Bond traders noticed early. Measures of Broadcom’s credit risk climbed in August as the first backstops came together.
On the reported balance sheet, though, leverage looks light.
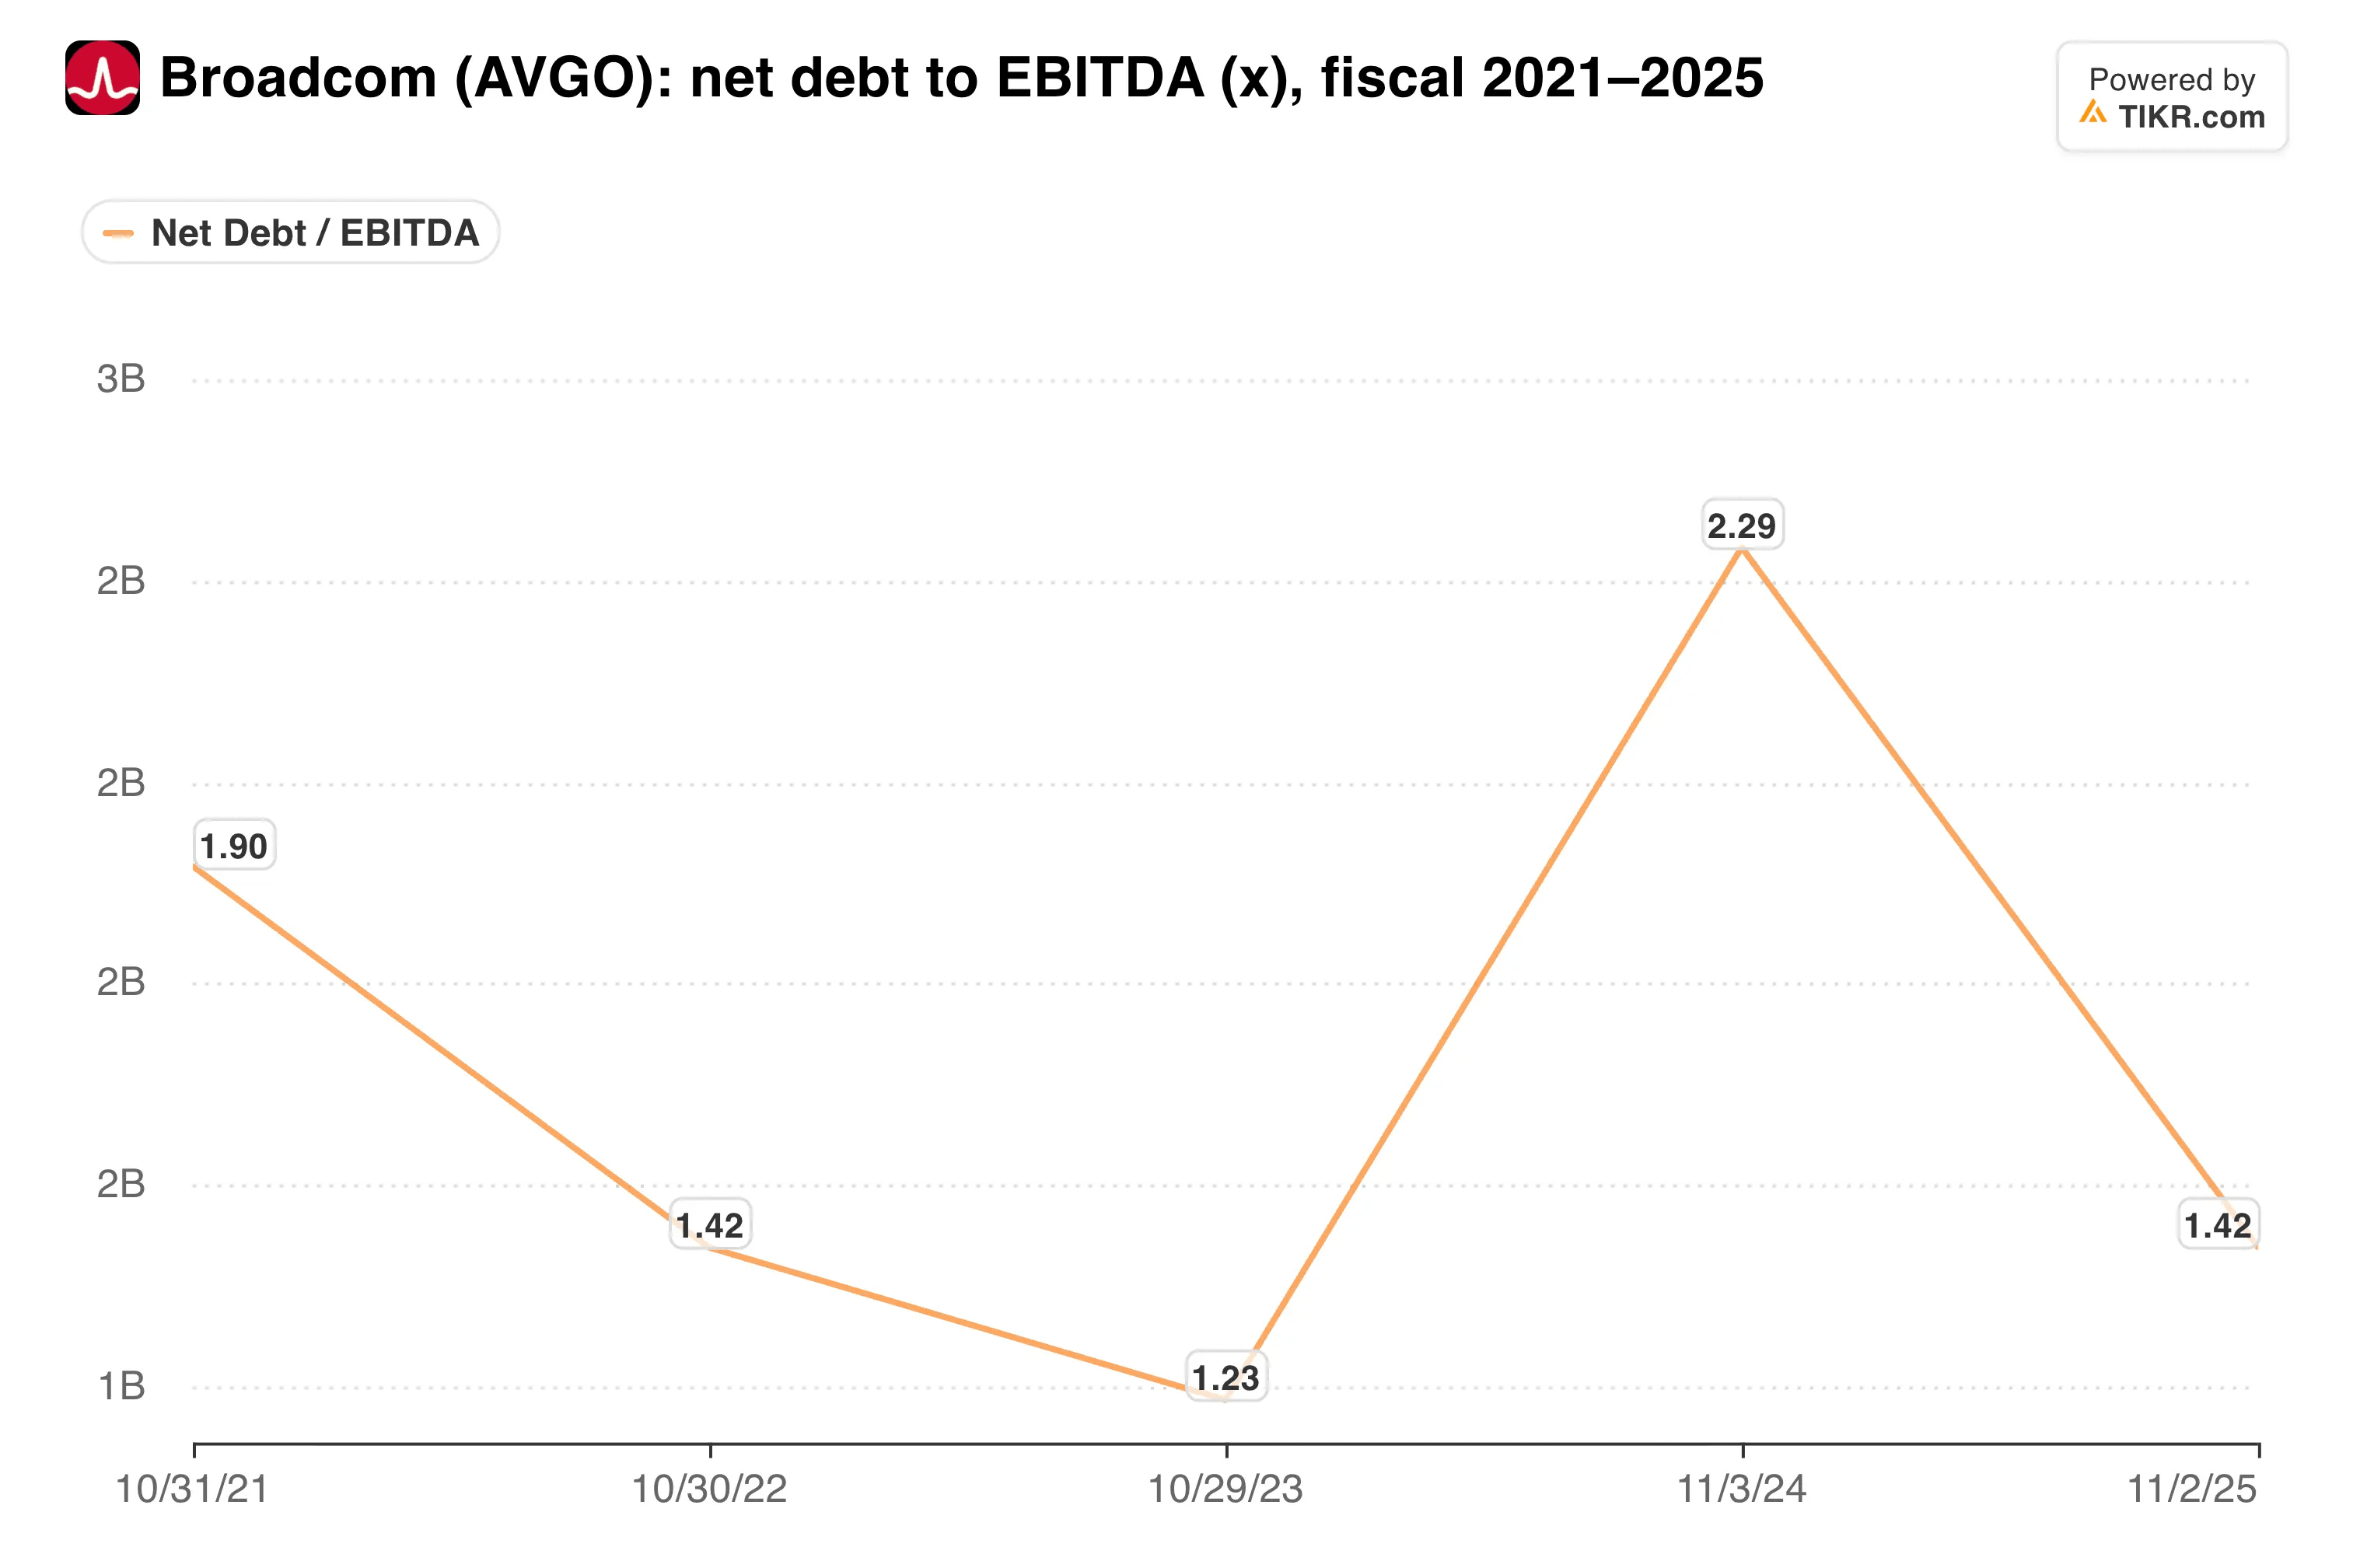
Net debt sits at just 0.68x EBITDA. None of the backstops show up in that ratio.
The orders behind the risk
Broadcom’s fiscal third quarter shows why lenders are willing to play. Revenue rose 86% to $29.6 billion, and AI semiconductor revenue jumped 221% to $16.7 billion, or 56% of the total. Infrastructure software, including VMware, grew 29% to $8.8 billion.
Remaining performance obligations reached $179.2 billion. Management also raised its fiscal 2026 AI revenue target to $58 billion and is aiming for $115 billion in fiscal 2027 and $230 billion in fiscal 2028.
Which side of the business is doing the work?

Semiconductors now bring in about 70% of revenue by my math, and AI chips account for most of the growth.
TIKR tracks 50 analysts on Broadcom. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Broadcom, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Broadcom’s Analyst Ratings
Cheap stock, concentrated customer book
The fourth-quarter guide called for $34.8 billion of revenue, a touch below the $35.03 billion consensus. AI revenue should reach $21.7 billion. Gross margin, however, is guided down to about 73% from 78% a year earlier as memory-heavy custom chips take a bigger share.
Concentration worries me more. Broadcom has only six XPU customers, and Anthropic is expected to become the largest in fiscal 2027, the same customer whose leases it now backstops.
The selloff has already squeezed the multiple…

At 18.7x forward earnings, Broadcom trades in line with Meta, yet analysts expect its EPS to grow 68.9% a year over the next two years versus 9.5% for Meta. The Street’s $529 average target implies 62% upside.
My take: The demand case is strong, and 18.7x earnings is cheap for this growth on paper. But Broadcom is increasingly underwriting its biggest customers’ ability to pay, and a combined $72 billion ceiling deserves a discount until those labs prove out their revenue. I’d buy in stages here rather than all at once.
The next checkpoint is the December 10 report. It needs $21.7 billion of AI revenue, gross margin near 73%, and some clarity on whether an OpenAI backstop comes next.
So what is Broadcom stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Broadcom could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!