

Key Takeaways
- Newell Brands shares fell 11% today despite a sales beat and a raised full-year sales outlook.
- Inflation ran hotter than expected, and full-year earnings guidance only held its midpoint.
- With $4.8 billion of debt, Newell needs sales growth to show up in profits.
- Whirlpool is raising prices to deal with cost inflation, and Stanley Black & Decker reports next week.
Newell Brands (NWL) grew sales for a second straight quarter and raised its full-year outlook this morning. The stock fell 11% anyway.
The reason is costs. CFO Mark Erceg said normalized EPS landed at the high end of guidance “despite inflation that exceeded our expectations.” Other makers of household hard goods are dealing with it too: Whirlpool (WHR) flagged rising raw material, fuel and logistics costs on Monday, and Stanley Black & Decker (SWK) reports next week.
The sales are back
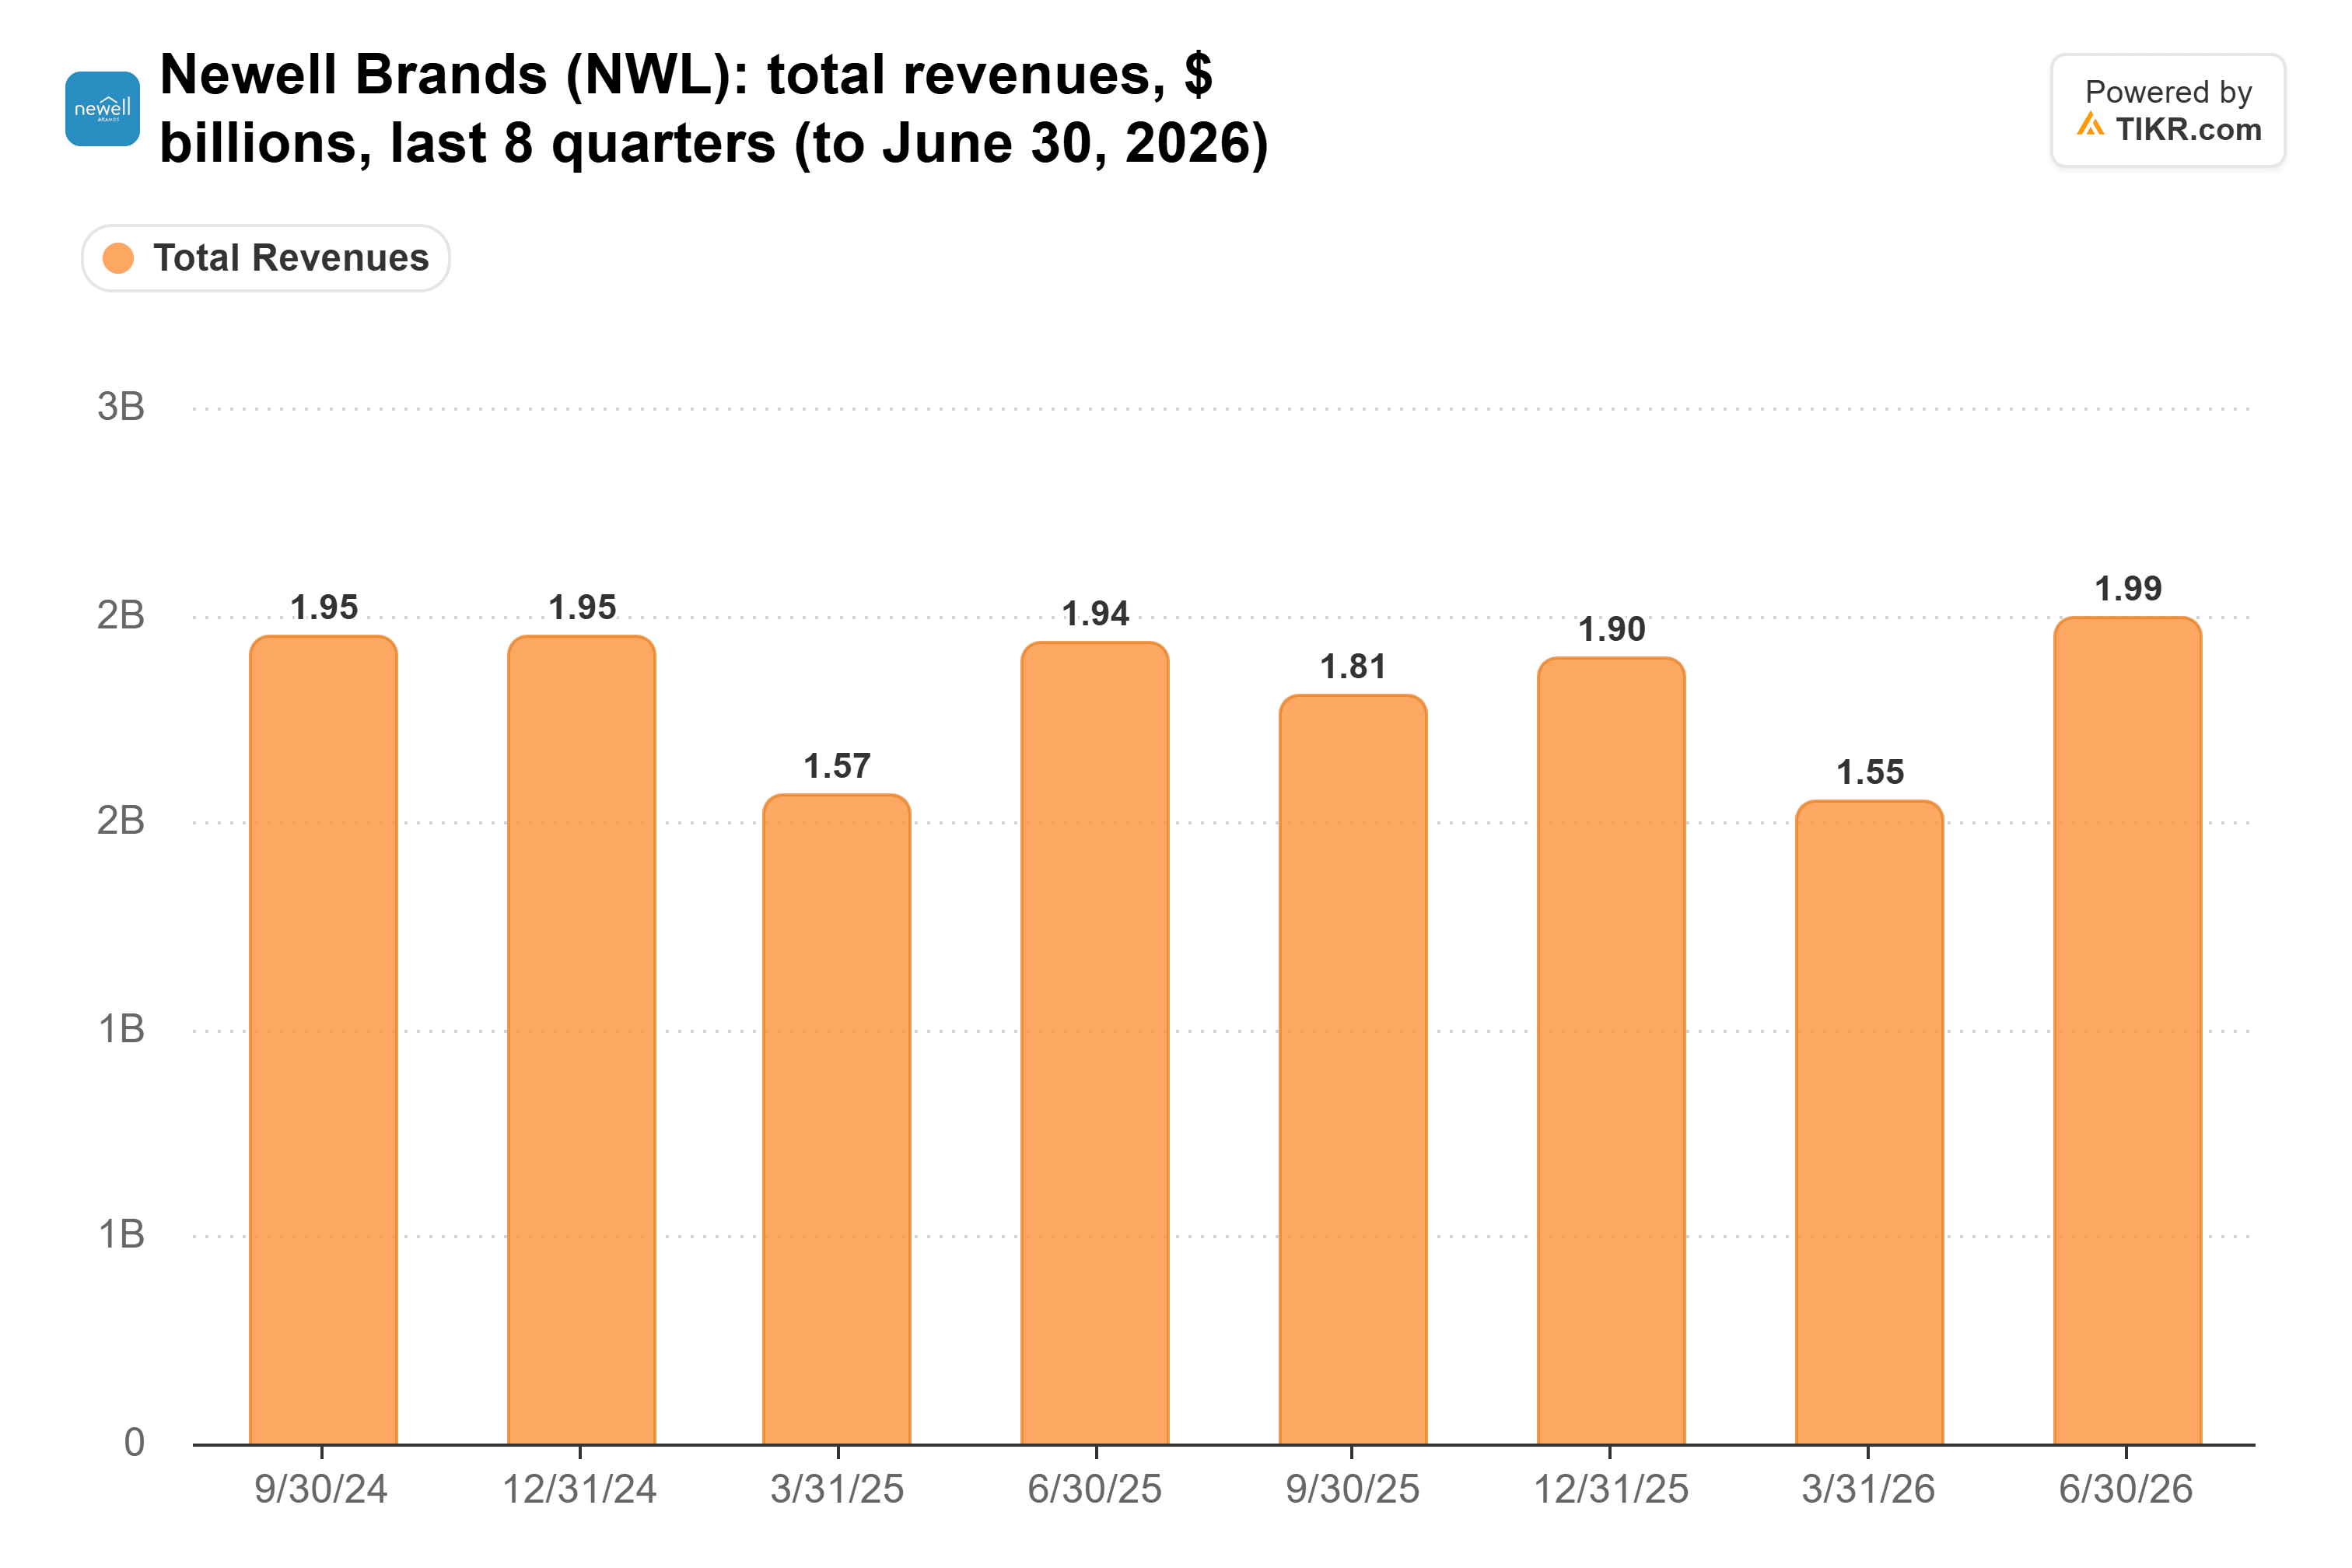
Third-quarter net sales rose 3.7% to $1.9 billion, beating the $1.86 billion analysts expected. Before that, the second quarter ended a run of three straight quarters of lower sales than a year earlier:
Newell now expects full-year net sales to grow 2% to 3%, up from 1% to 2%.
But the profits haven’t followed
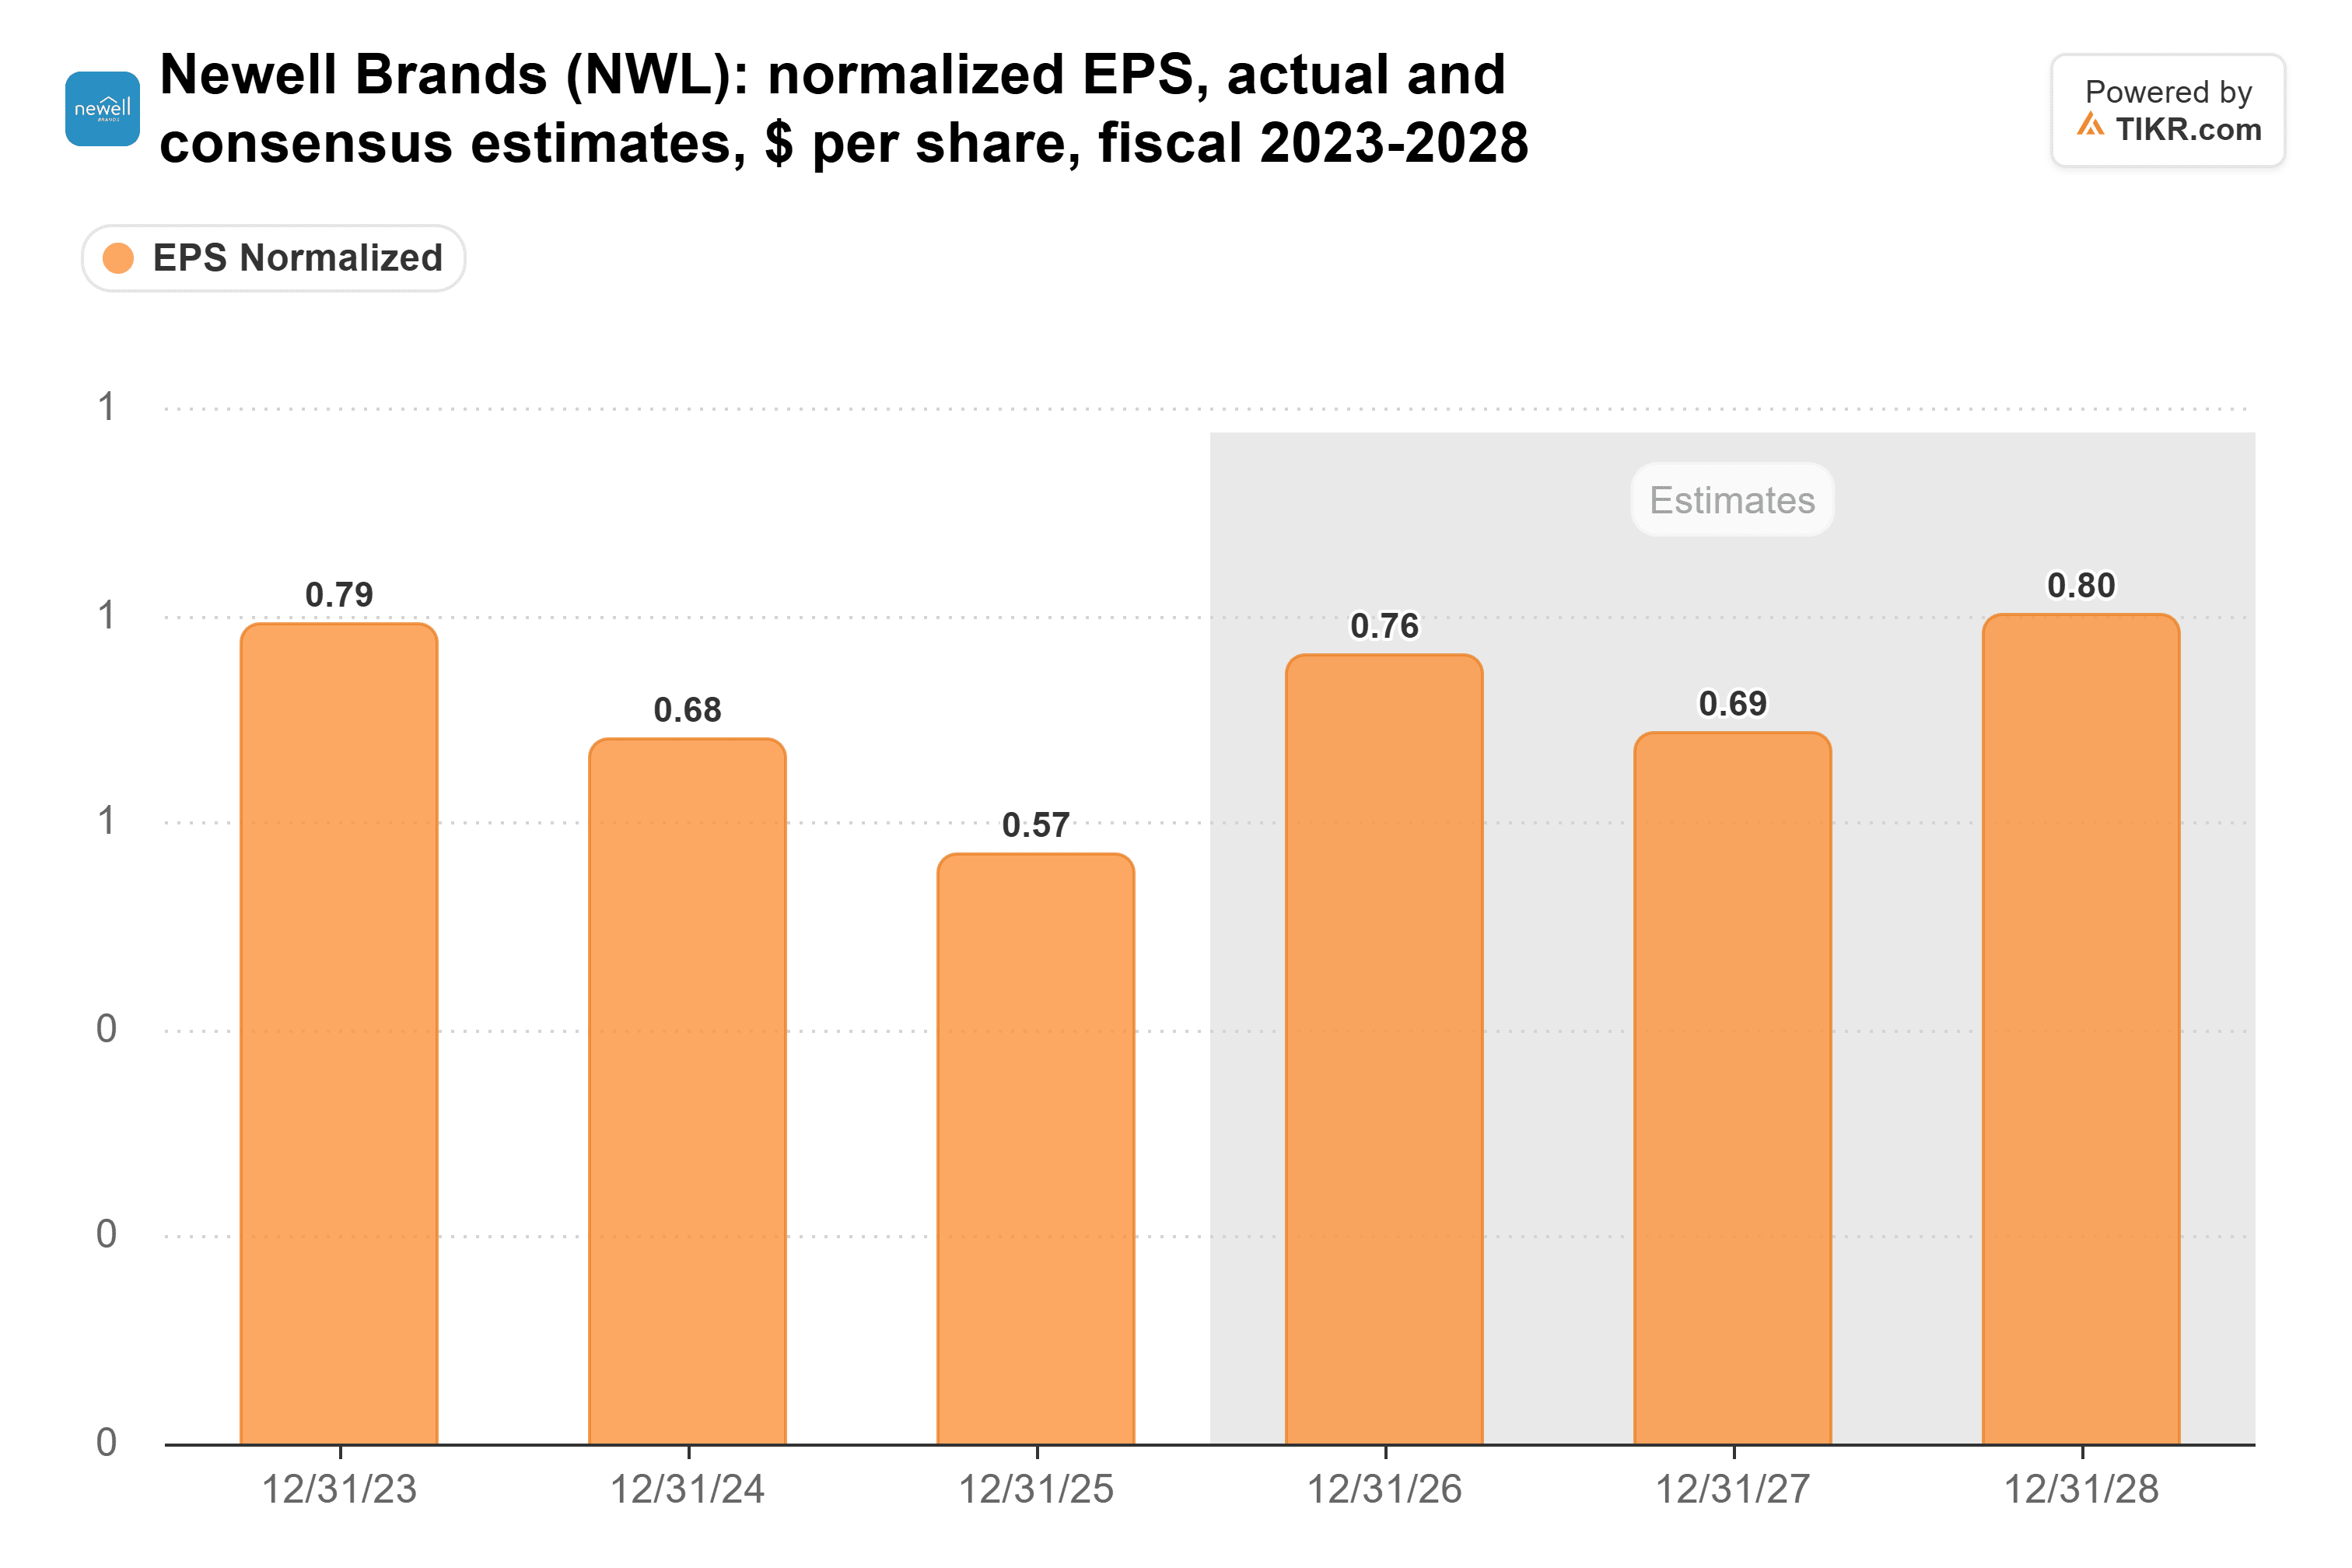
Normalized EPS rose to $0.20 from $0.17, which only matched estimates. Newell narrowed its full-year normalized EPS guide to $0.74 to $0.76, against a $0.76 consensus.
Normalized EPS has fallen every year since fiscal 2023, and analysts already expect this year’s rebound to fade in 2027:
Nothing in today’s guide argues for raising those numbers.
And the debt raises the stakes: $4.8 billion at the end of September, against a market value of roughly $2.2 billion before today.
TIKR tracks 9 analysts on Newell Brands. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Newell Brands, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Newell Brands’ Analyst Ratings
Newell has company
Whirlpool has it worse, since its sales are shrinking. Its third-quarter net sales fell 8.8%, and its ongoing EBIT margin slid to 2.6% from 4.5%. Its answer is a 7% price increase in North America this quarter. With demand this soft, the question is whether it sticks.
Stanley Black & Decker’s second-quarter gross margin jumped 6 percentage points to 33.0%, but about 2.5 points of that came from tariff refunds. Next week’s report will show whether the margin holds up without that boost.
The turnaround needs to reach the bottom line
Newell’s sales turnaround looks real. But with this much debt, it has to show up in profits. I’d stay on the sidelines until inflation stops eating the gains.
Of course, if costs cool, the fourth quarter could come in better than guided.
So what is Newell Brands stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Newell Brands could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


