Key Stats for Carnival Corporation Stock
- Current Price: $21.80
- Target Price (Mid): ~$38
- Street Target: ~$34.49
- Potential Total Return: ~76% (over ~4.2 years)
- Annualized IRR: ~14.5% / year
Now Live: Discover how much upside your favorite stocks could have using TIKR’s new Valuation Model (It’s free) >>>
What Happened?
Carnival Corporation (CCL) heads into its fiscal third-quarter report on Tuesday, September 29, down more than 25% year to date, with the stock at $21.80, just above its 52-week low of $21.52. The question is narrow: in June, CEO Josh Weinstein insisted the yield damage from the Middle East conflict was “already proving to be transitory.” Tuesday’s numbers are the first hard read on whether he was right.
Analysts expect roughly $8.4 billion in revenue, up from $8.15 billion a year ago, and adjusted EPS near $1.35, down from $1.43. That EPS step-down against higher revenue is the tension, and the cost line under scrutiny is the fuel.
The Fuel Line Under the Microscope
In Q2, prices ran nearly 30% above the prior year, and management still delivered net income of $569 million, up more than 20% year-over-year. Since the June 23 report, oil has climbed further, and analysts, including Jefferies, flag higher fuel as the main risk to fourth-quarter and full-year guidance.
CFO David Bernstein described “hundreds of little things,” from renegotiated supplier rates to running one fewer forklift on embarkation day across multiple ships, and said, “the overwhelming majority of what we’re doing is for the long term.” The Q3 print shows whether that cost engine absorbs another leg higher in oil while the company holds its Q3 adjusted EBITDA guidance of about $2.88 billion. Its operating margin held in the low teens through Q2, even under the fuel pressure, which tells you cost discipline has been doing real work.
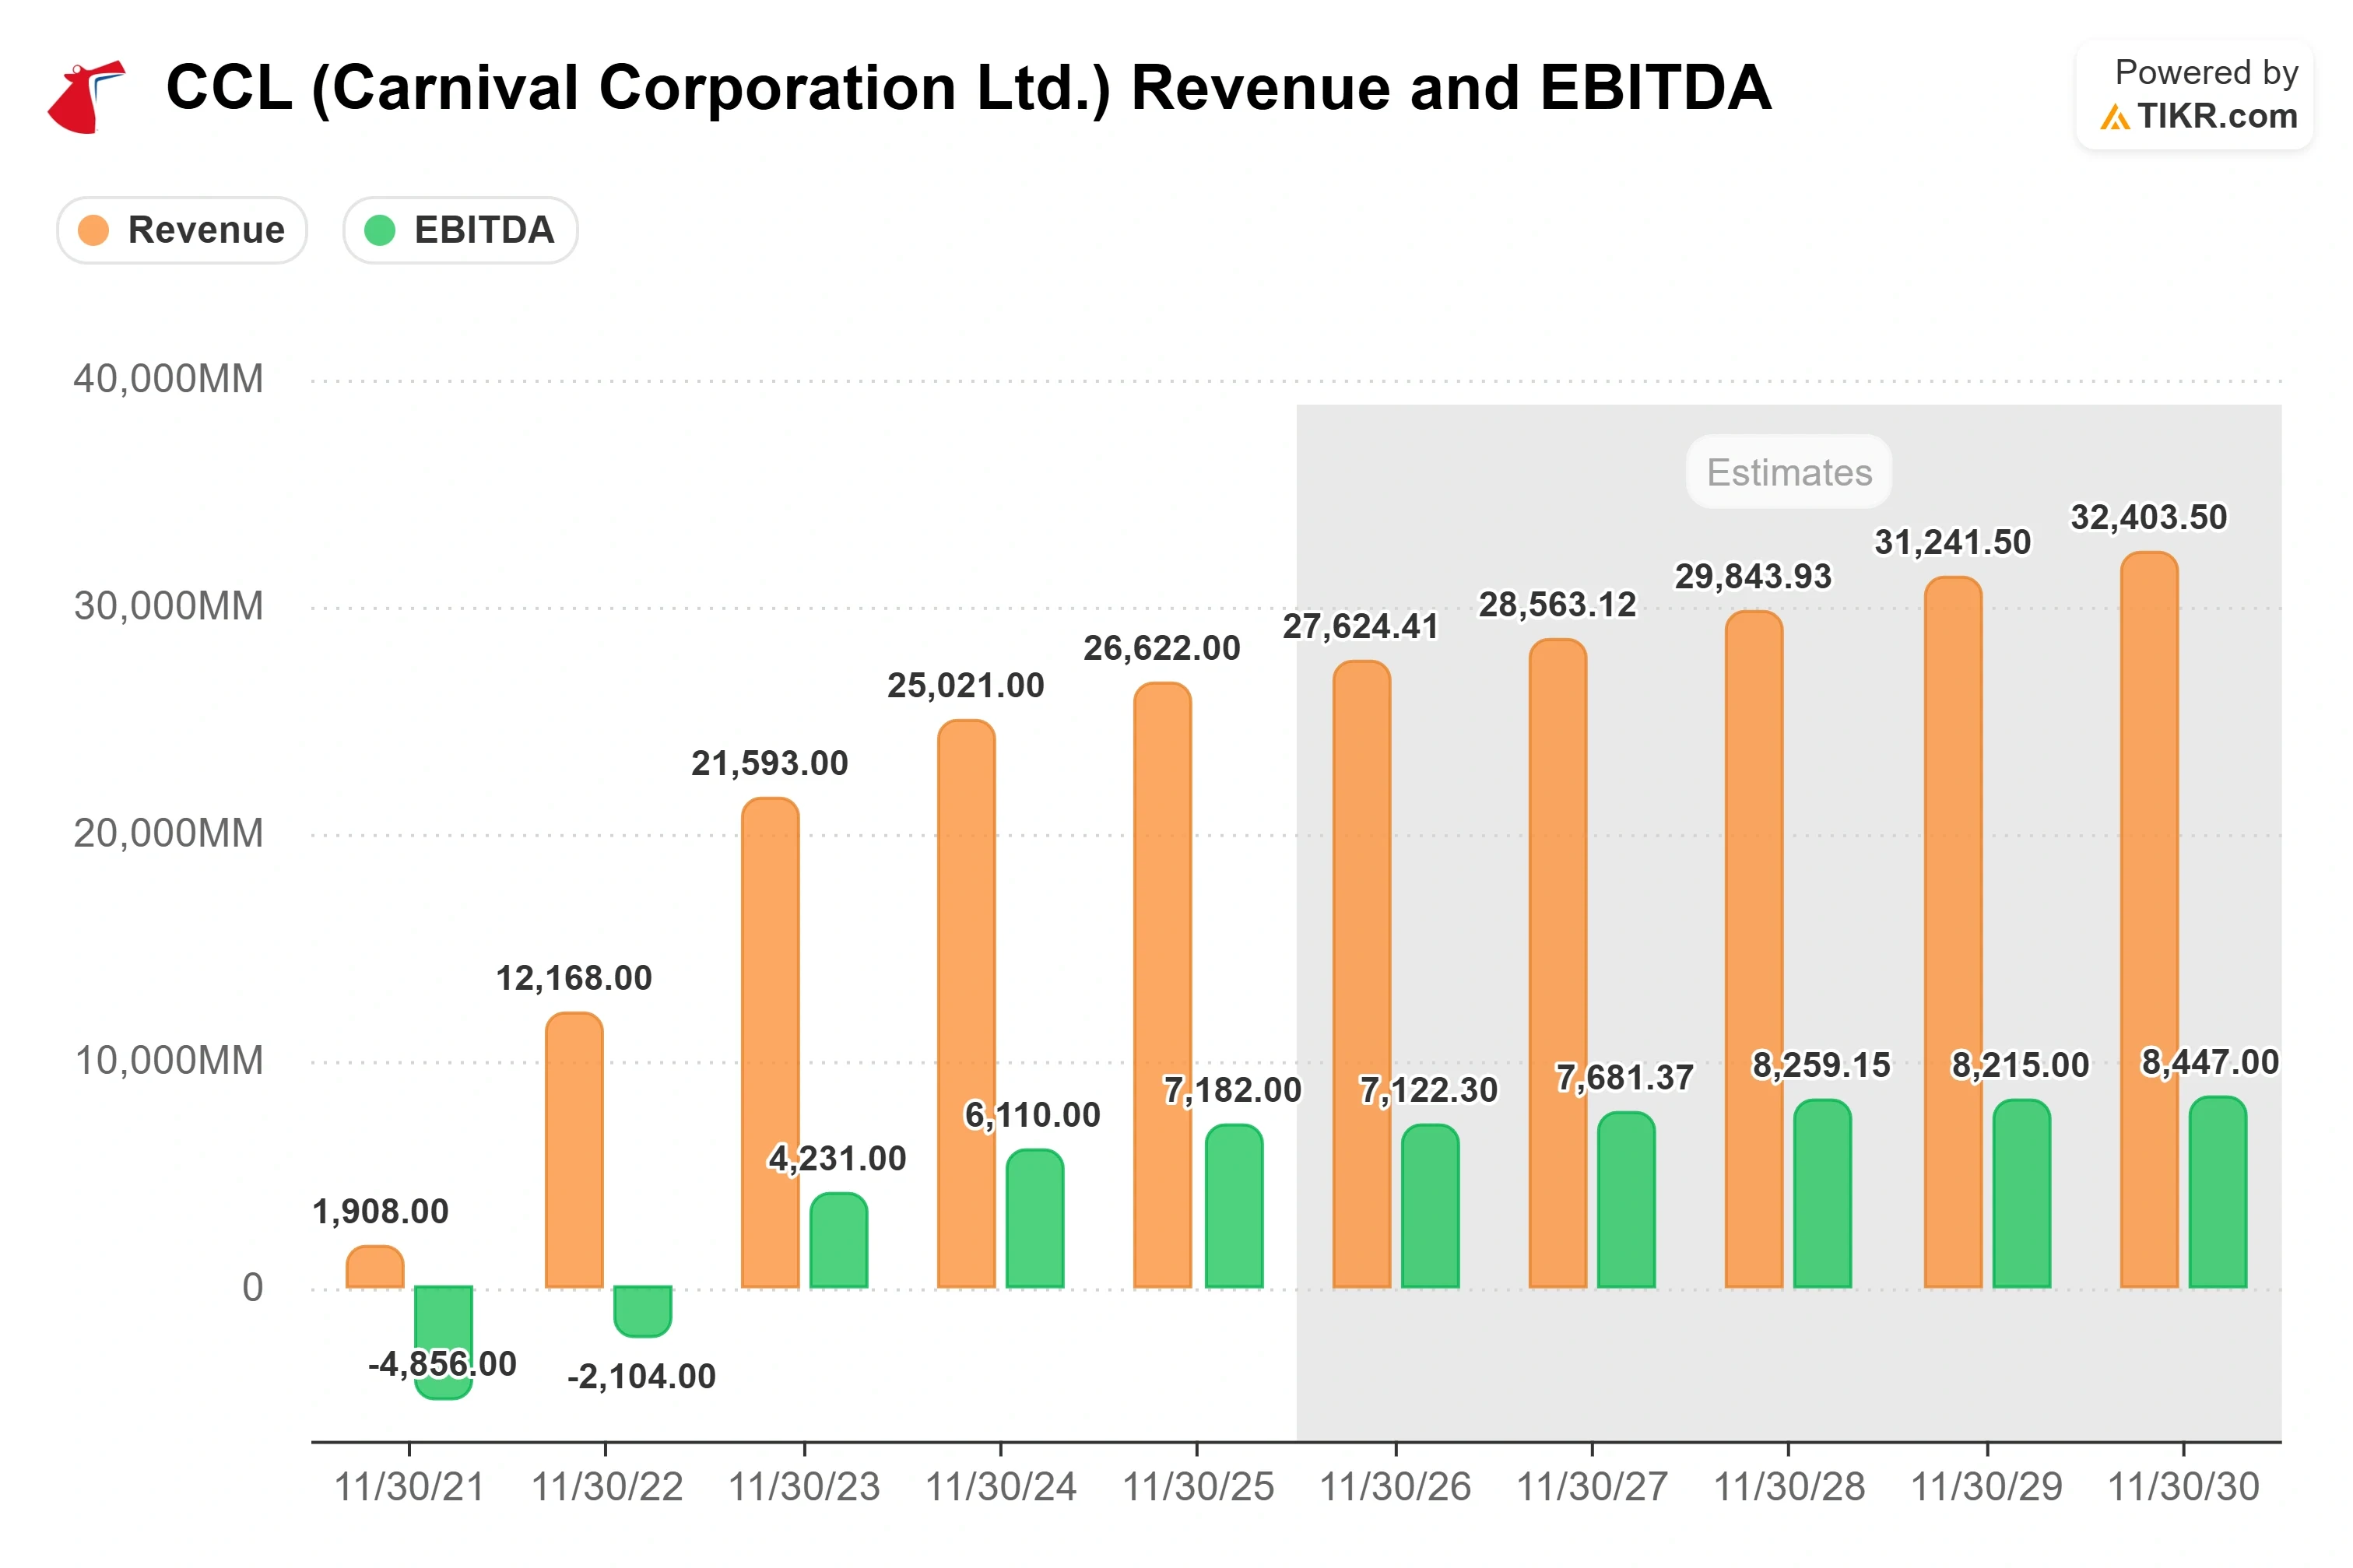
See historical and forward estimates for Carnival Corporation stock (It’s free!) >>>
What “Transitory” Has to Prove
In June, Carnival cut full-year normalized yield growth to about 2.25%, roughly a point below prior guidance, and pinned nearly all of it on Mediterranean deployments. The mechanism matters: rather than discount, management took Europe occupancy down about two points to protect pricing, a deliberate trade Weinstein called “the healthiest thing for the business.” He also said booking trends suggested “we are already beginning to see a reversal of these headwinds,” with 2027 European bookings running “up year-over-year in mid-teens percentages at higher prices.”
Hold the full-year EPS target of $2.22 and confirm Europe firming into Q4, and the transitory thesis survives. Trim guidance or flag more softness, and the debate shifts to how much of 2027 is at risk. Wall Street has braced for the second outcome: in mid-September, Deutsche Bank cut its target to $29, Goldman Sachs to $30, and Barclays to $33, all citing fuel and softer European and Caribbean pricing, though none moved to Sell.
Jefferies called the $2.88 billion EBITDA guide conservative and kept a Buy at $33; Deutsche Bank sees only a small beat and no near-term catalyst. Same fuel curve, opposite reads. Carnival’s discount frames the stakes: about 7.5x NTM EV/EBITDA versus Royal Caribbean near 10.5x and Norwegian around 9x, per TIKR’s Competitors data, even as net debt to adjusted EBITDA has fallen to 3.1x from 3.4x at year-end.
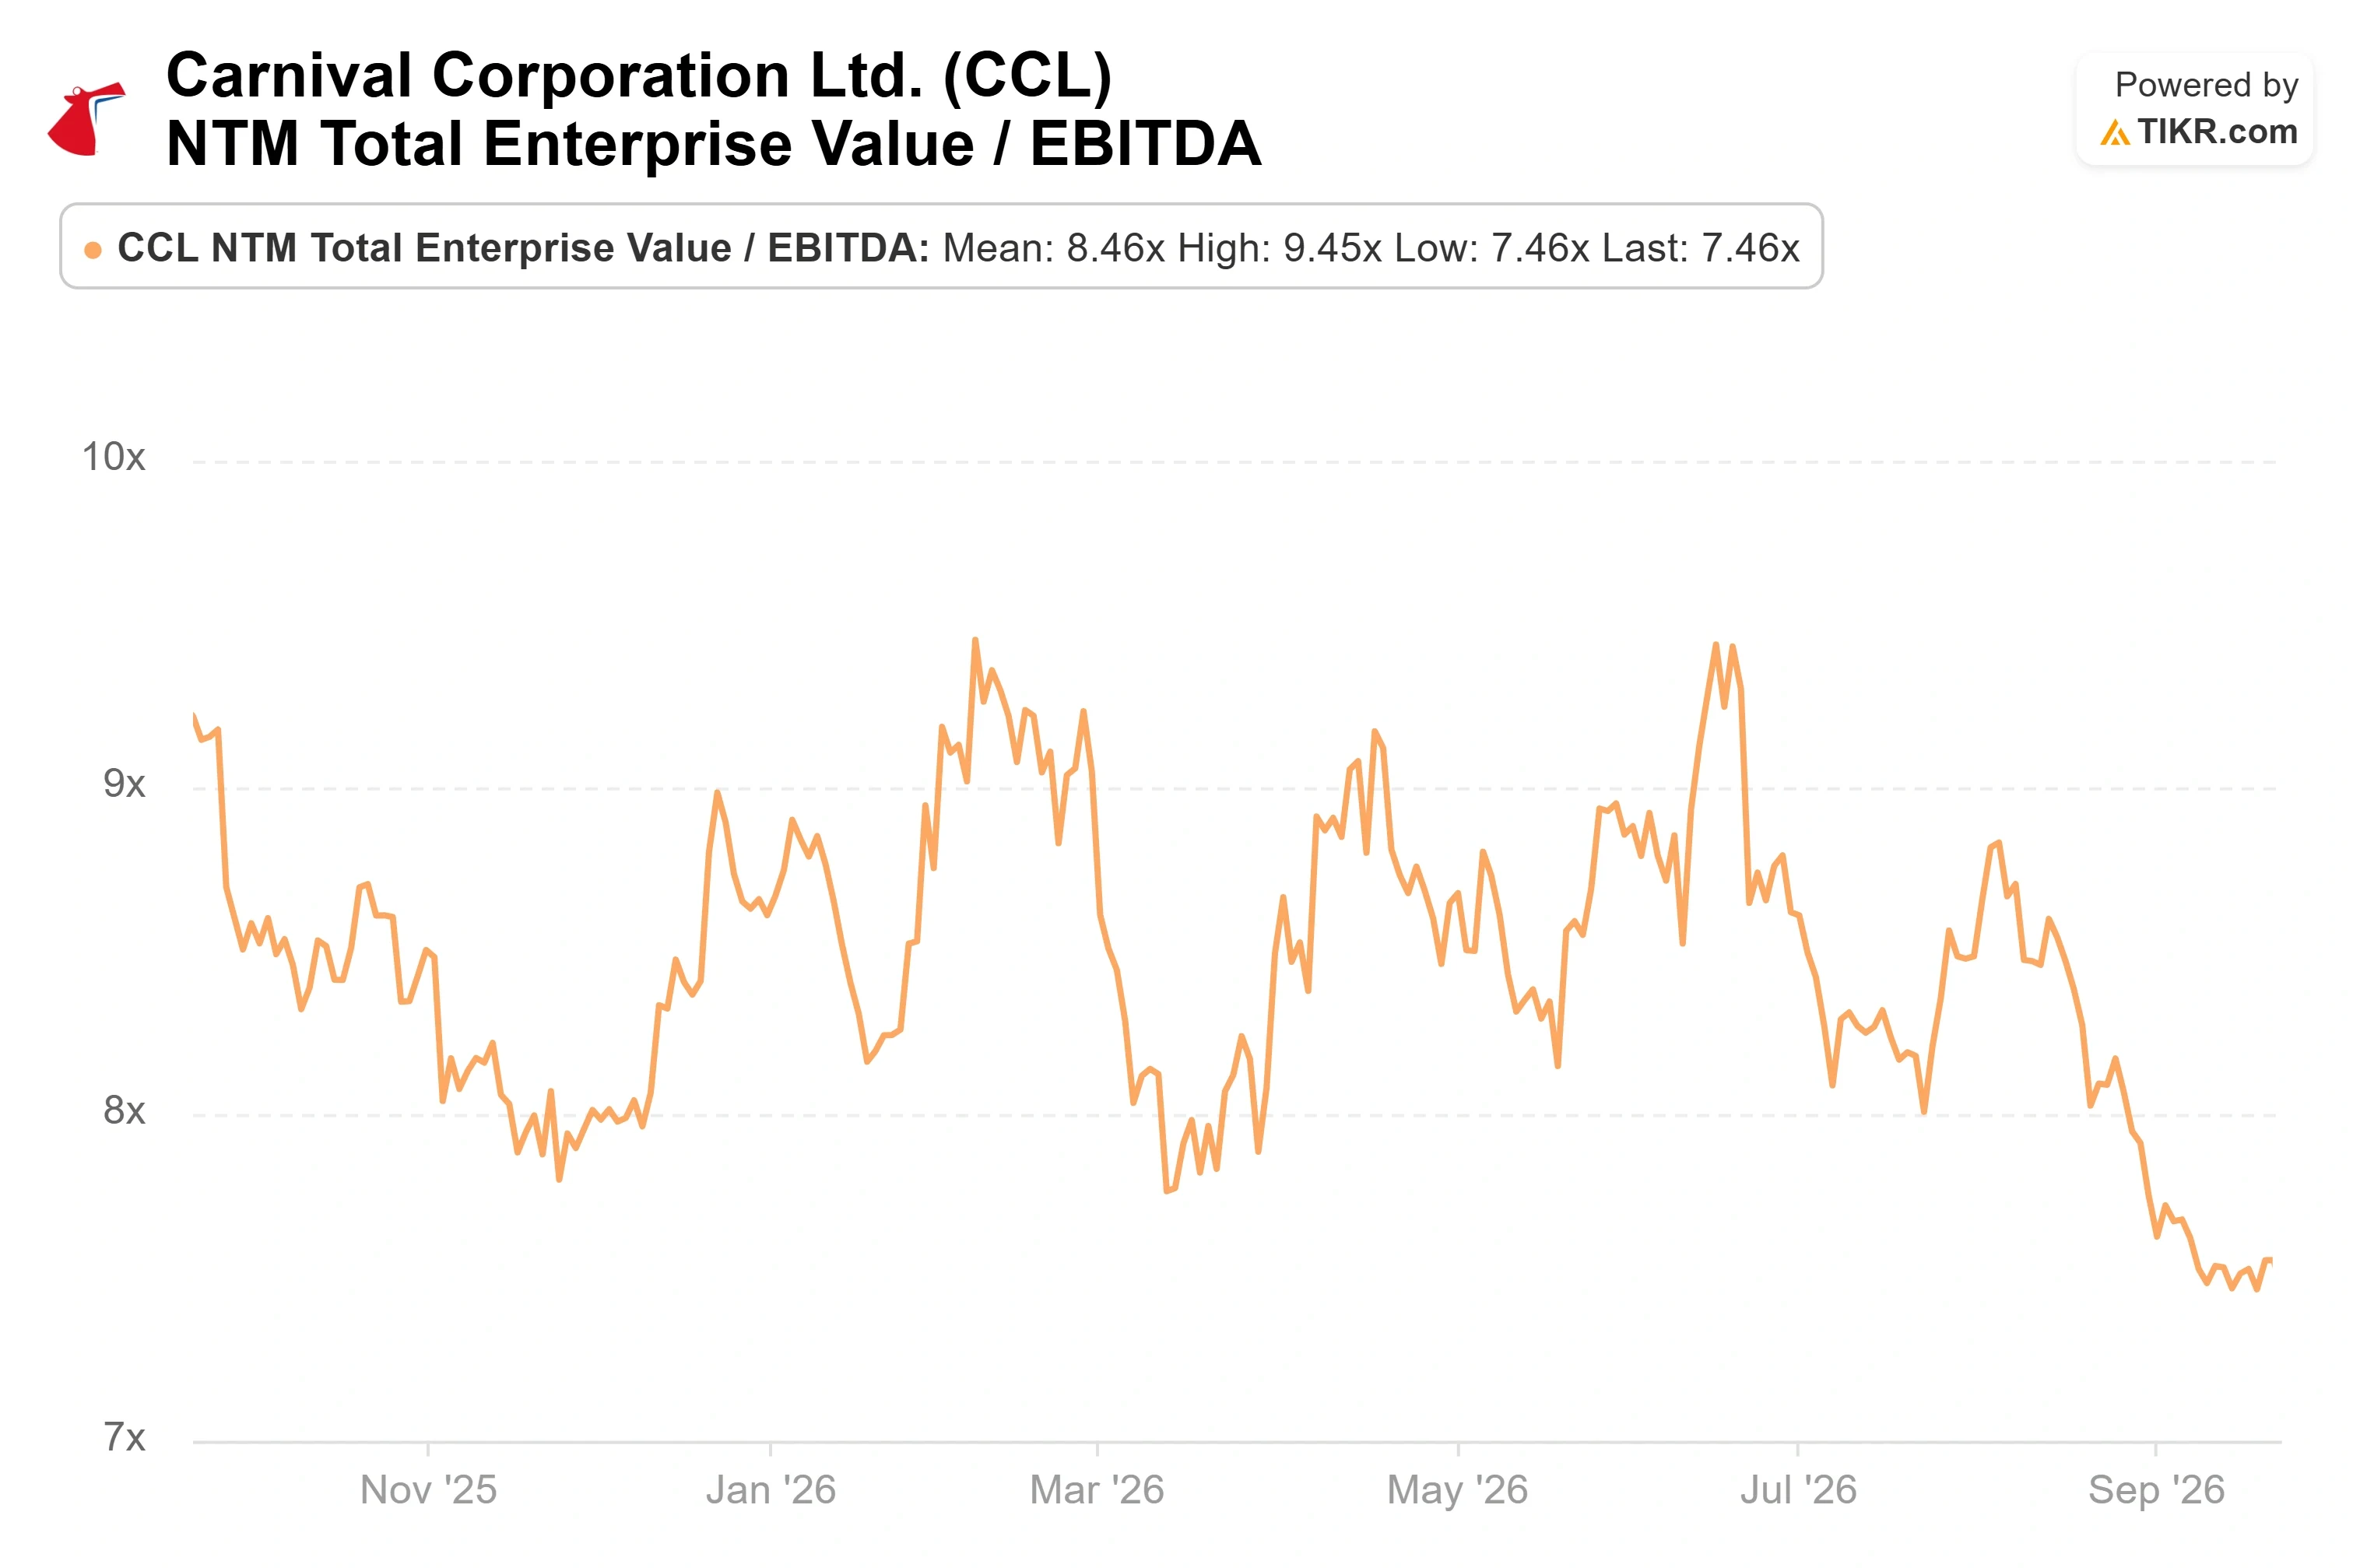
See how Carnival Corporation performs against its peers in TIKR (It’s free!) >>>
TIKR Advanced Model Analysis
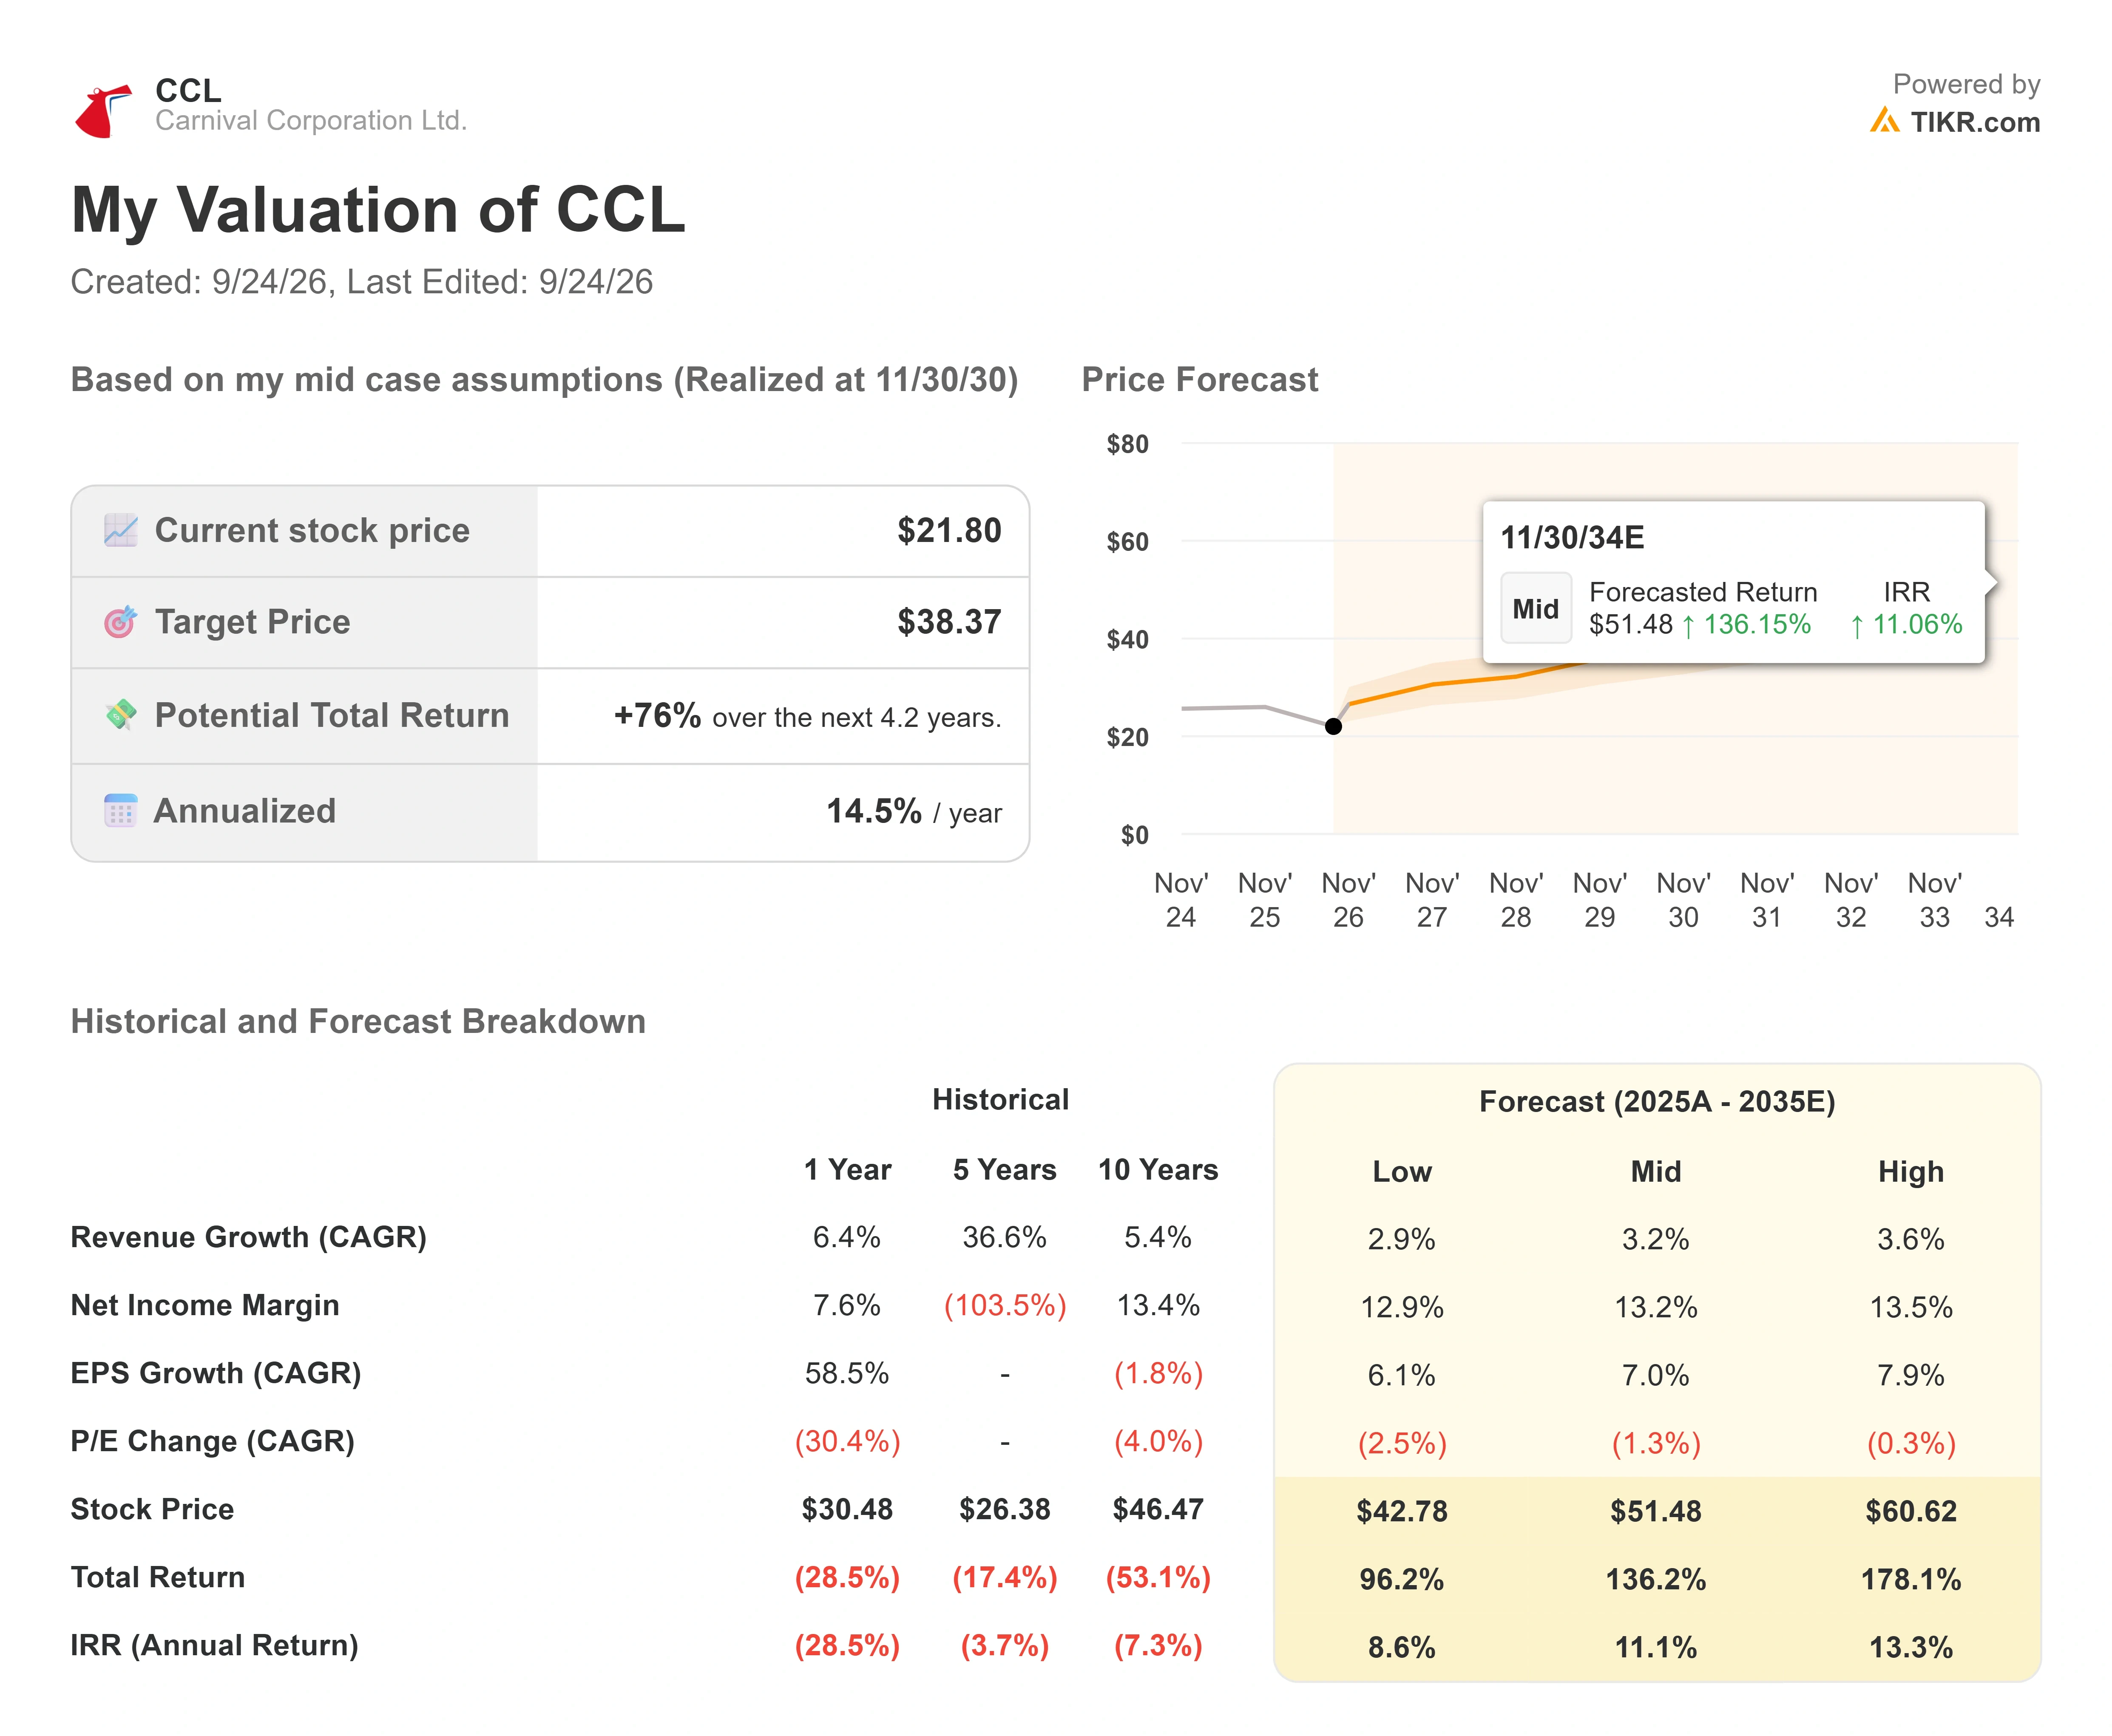
- Current Price: $21.80
- Target Price (Mid): ~$38
- Potential Total Return: ~76% (over ~4.2 years)
- Annualized IRR: ~14.5% / year
See analysts’ growth forecasts and price targets for Carnival Corporation stock (It’s free!) >>>
TIKR’s mid-case values Carnival at around $38, about a 76% total return from $21.80 over roughly 4.2 years, or a 14.5% annualized IRR. Two revenue drivers are already visible: the extended booking curve (93% of 2026 on the books at record prices as of June) and the destination build-out, with Celebration Key and RelaxAway at Half Moon Cay expected to lift Paradise Collection guest visits past 9 million next year. The margin driver is the structural cost program Bernstein detailed. The primary risk is its mirror image: a higher fuel bill against a rising oil curve can compress free cash flow and force a guidance cut that resets the outer years.
The upside: if the transitory call proves out and oil stabilizes, a business printing record yields at a single-digit EBITDA multiple re-rates fast. The downside: another quarter of Europe softness plus fuel makes the cheap multiple a justified one and stalls the deleveraging story.
Conclusion
Watch two lines before the open on September 29. First, full-year EPS guidance of $2.22: hold or raise it, and the transitory story survives; cut it, and the market’s caution was right. Second, the Europe yield commentary, where “firming into Q4” is the good outcome and “still soft” is the tell that recovery slipped a quarter. Fuel is the pressure either way, but guidance is where management backs its June conviction or quietly walks it back.
See what stocks billionaire investors are buying so you can follow the smart money with TIKR.
Should You Invest in Carnival Corporation?
The only way to really know is to look at the numbers yourself. TIKR gives you free access to the same institutional-quality financial data that professional analysts use to answer exactly that question.
Pull up Carnival Corporation, and you’ll see years of historical financials, what Wall Street analysts expect for revenue and earnings in the quarters ahead, how valuation multiples have moved over time, and whether price targets are trending up or down.
You can build a free watchlist to track Carnival Corporation alongside every other stock on your radar. No credit card required. Just the data you need to decide for yourself.
Analyze Carnival Corporation on TIKR Free →
Looking for New Opportunities?
- See what stocks billionaire investors are buying so you can follow the smart money.
- Analyze stocks in as little as 5 minutes with TIKR’s all-in-one, easy-to-use platform.
- The more rocks you overturn… the more opportunities you’ll uncover. Search 100K+ global stocks, global top investor holdings, and more with TIKR.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!