MGM Resorts International (MGM) is having a rough morning. Shares are down 10% after Barry Diller’s People Inc. (PPLI) pulled its offer to take the casino giant private.
I have some thoughts, but first let’s cover the backstory:
What exactly happened
Back in June, People offered to buy every MGM share it didn’t already own. Last night, it walked away:
- The offer was $48.30 per share in cash, valuing MGM at more than $18 billion
- People already owns about 27% of MGM (66.8 million shares) and is (so far) keeping all of it
- The deal was negotiated for months with a special committee of MGM’s board
- Diller reportedly had trouble lining up equity backing from outside co-investors, according to Bloomberg.
Diller’s explanation was…not exactly detailed:
“There are lots of ingredients that go into a proposal of this kind on its way to completion. We didn’t feel the mix was coming together in the way we had hoped and have decided not to pursue taking the company private at this time.”
The bigger backdrop
The deal was never fully priced-in by the market: MGM closed Wednesday at $37.85, roughly 22% below the $48.30 offer price. A gap that wide on a cash bid usually means investors had real doubts it would close.
And those were, as it turns out, appropriate.
Now MGM goes back to being judged on its business alone, and the picture there is mixed. MGM’s properties make up roughly 40% of the Las Vegas Strip, but US foot traffic has been sluggish. Macau and digital (including BetMGM, its 50-50 joint venture with Entain) have been the bright spots, but in general MGM’s growth hasn’t been amazing:
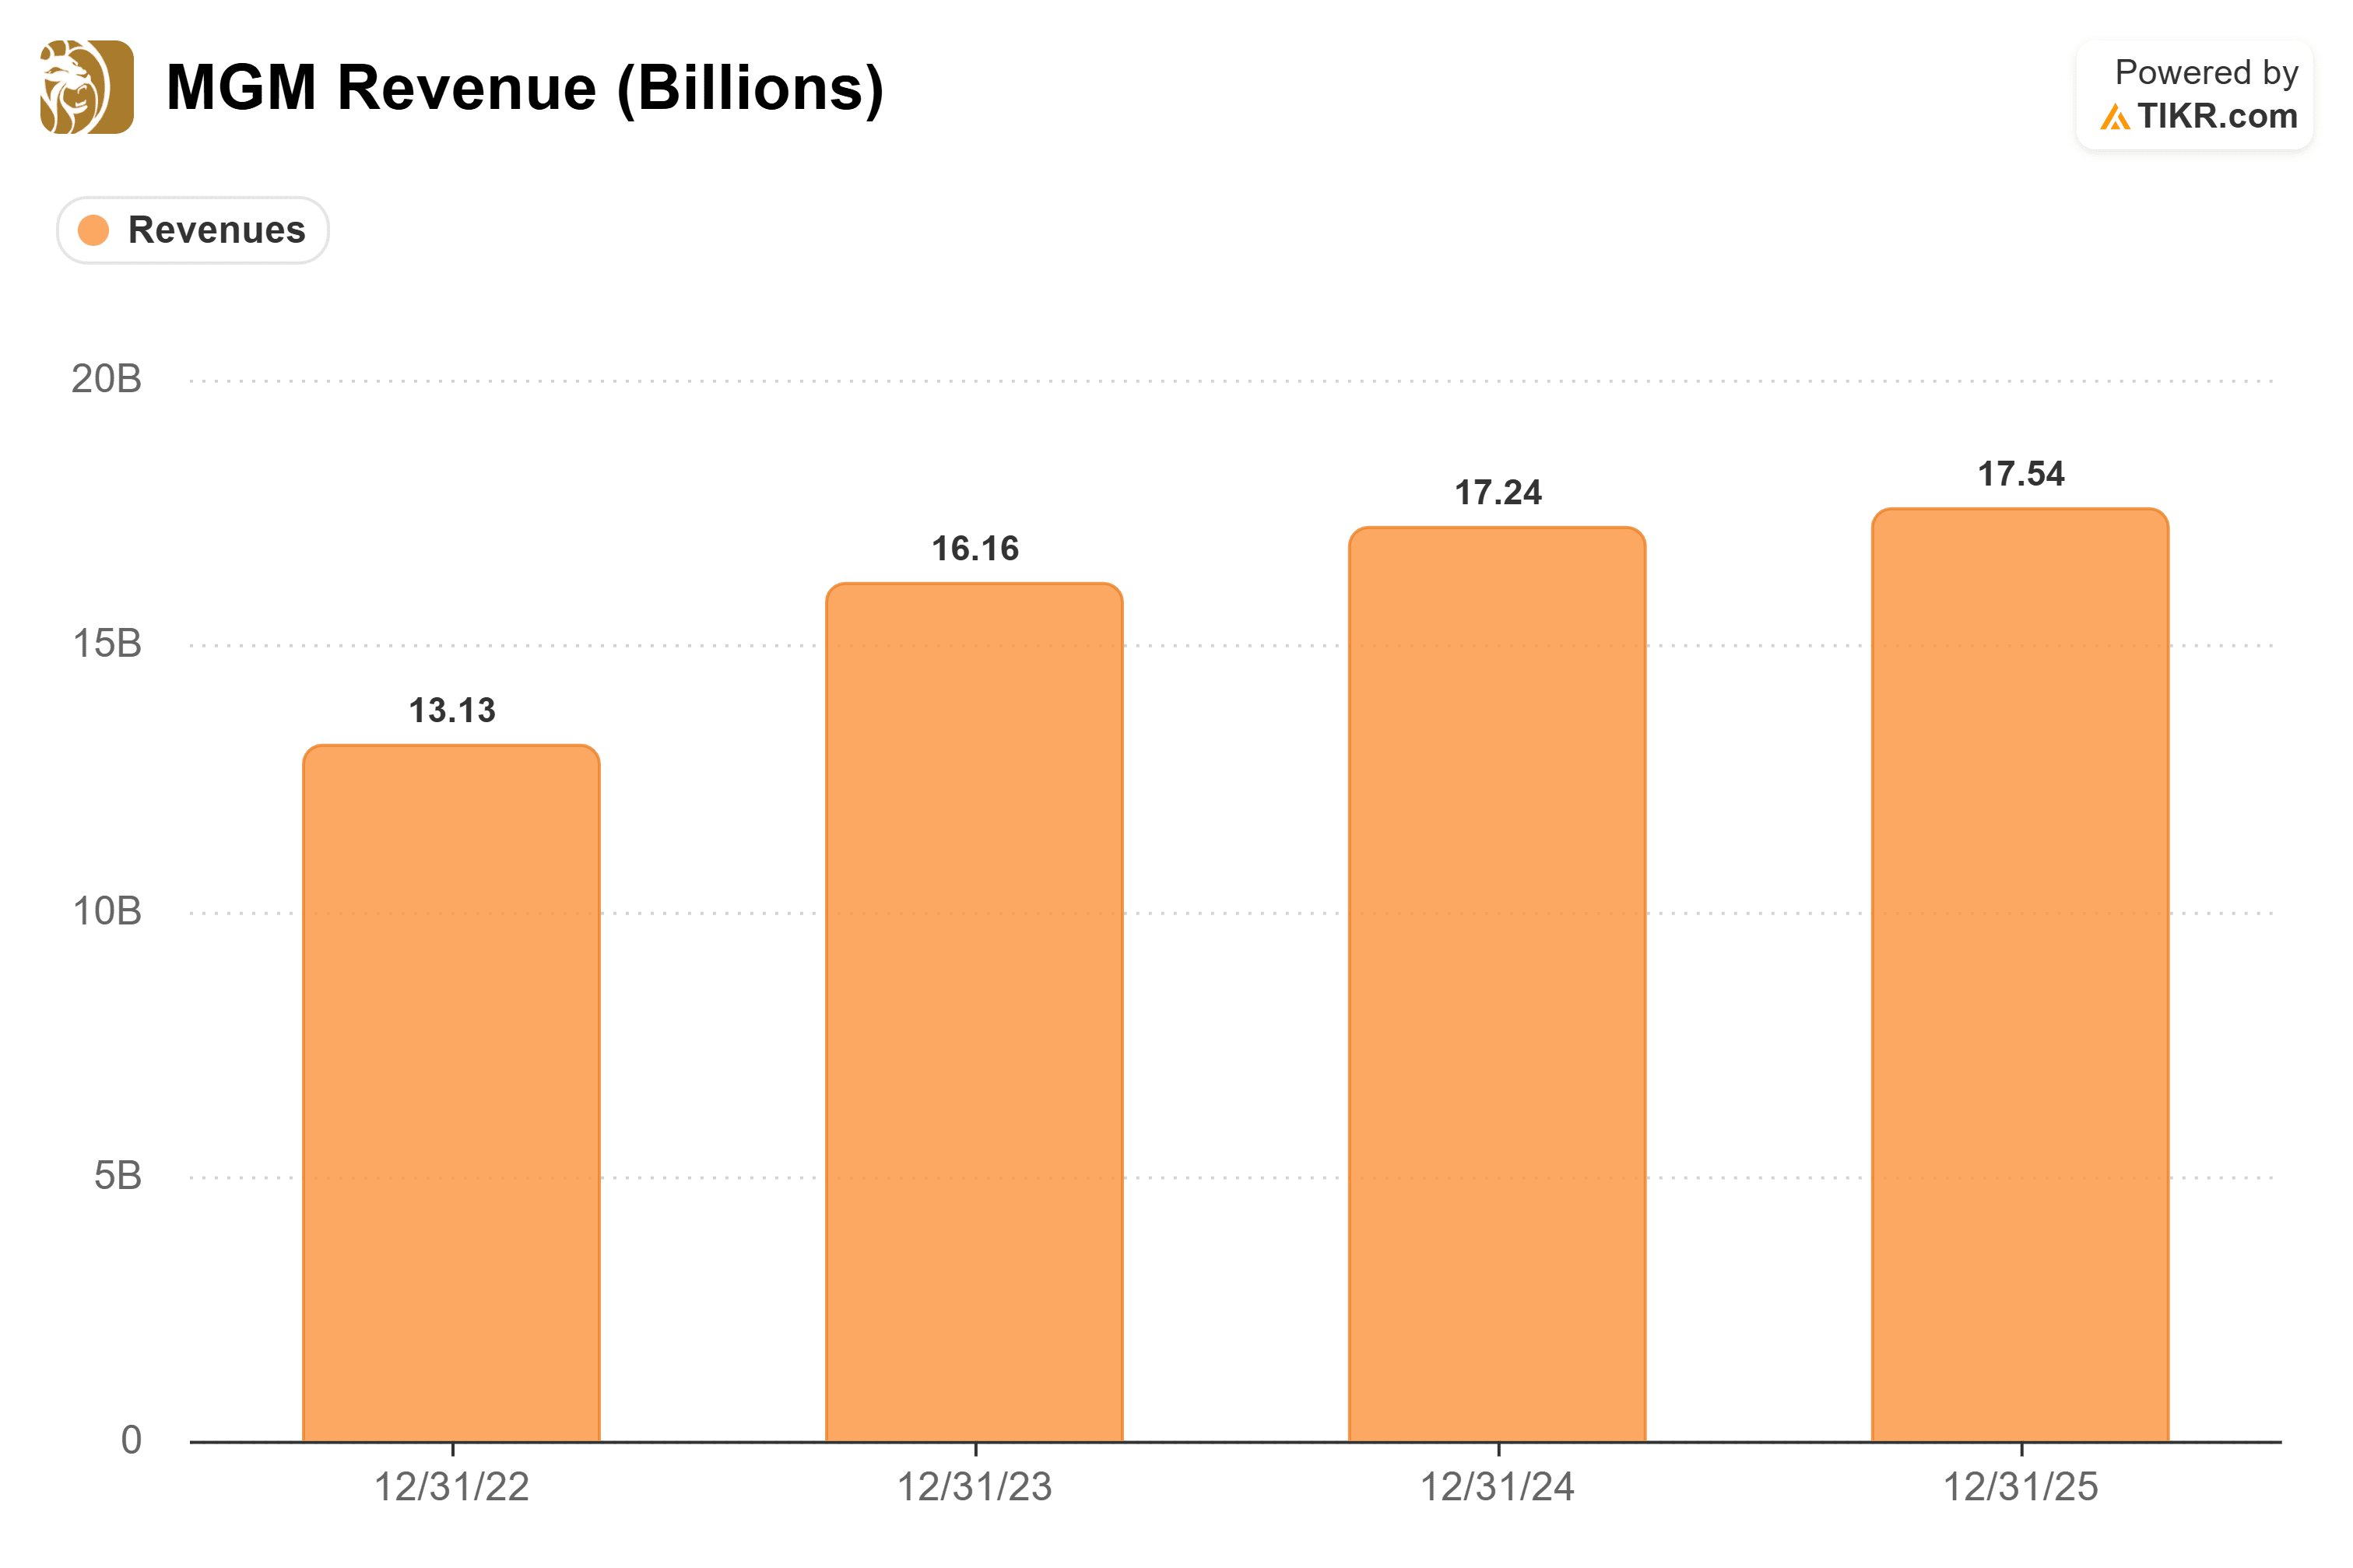
Doesn’t scream “fundamentally mispriced asset” to me.
What’s next
Diller hasn’t slammed the door. People says it looks forward “to considering a range of alternatives,” and he called his belief in MGM’s future “undimmed.”
Which, maybe that’s a good sign of future engagement (albeit likely at a lower price if the background chatter is true), or maybe it’s just playing nice on day one.
I guess we’ll see.
My view is that online betting continues to be a material headwind for casinos, and until that changes, MGM’s going to be a tough business to bet on.
So what’s MGM actually worth?
I ran a quick analysis using TIKR’s proprietary valuation model. (Click the link to build your own using TIKR’s institutional-quality data; it’s free.) The model takes three inputs (and you can just use consensus estimates from Wall Street analysts if you like, or write in your own thesis!) and spits out a full-fledged model.
I used consensus; mine implies a fair value of shares at $40 in three years. So call it $6 per share upside from here, or about 18%.
If that’s accurate, might as well just buy Treasuries!
Disagree? Want to check my math? Build your own model here. It’s free!
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!