Key Takeaways
- Block reports third-quarter results after the close on Tuesday, Nov. 3. Analysts now expect $4.05 of normalized EPS for 2026, up 15% from a year earlier.
- Block’s forward P/E has fallen to 17x. That’s below its three-year average of 20x and far below its five-year average of 37x.
- Morgan Stanley downgraded Block on Oct. 28. It expects Cash App Borrow lending to slow and longer loans to raise credit losses.
- The forecasts hold up if Block beats its guidance for gross profit and adjusted operating income and its loss growth slows. If that happens, the cheaper multiple is the mistake.
Analysts expect Block (XYZ) to earn more this year than they did a year ago. Yet the stock trades at a lower multiple of those earnings than it did at the end of 2025.
Block reports third-quarter results after the close on Tuesday, Nov. 3, and its margins will tell us which of the two is wrong.
Analysts keep raising the bar
Wall Street expects Block’s normalized EPS to grow from $4.05 this year to $6.48 in 2028:
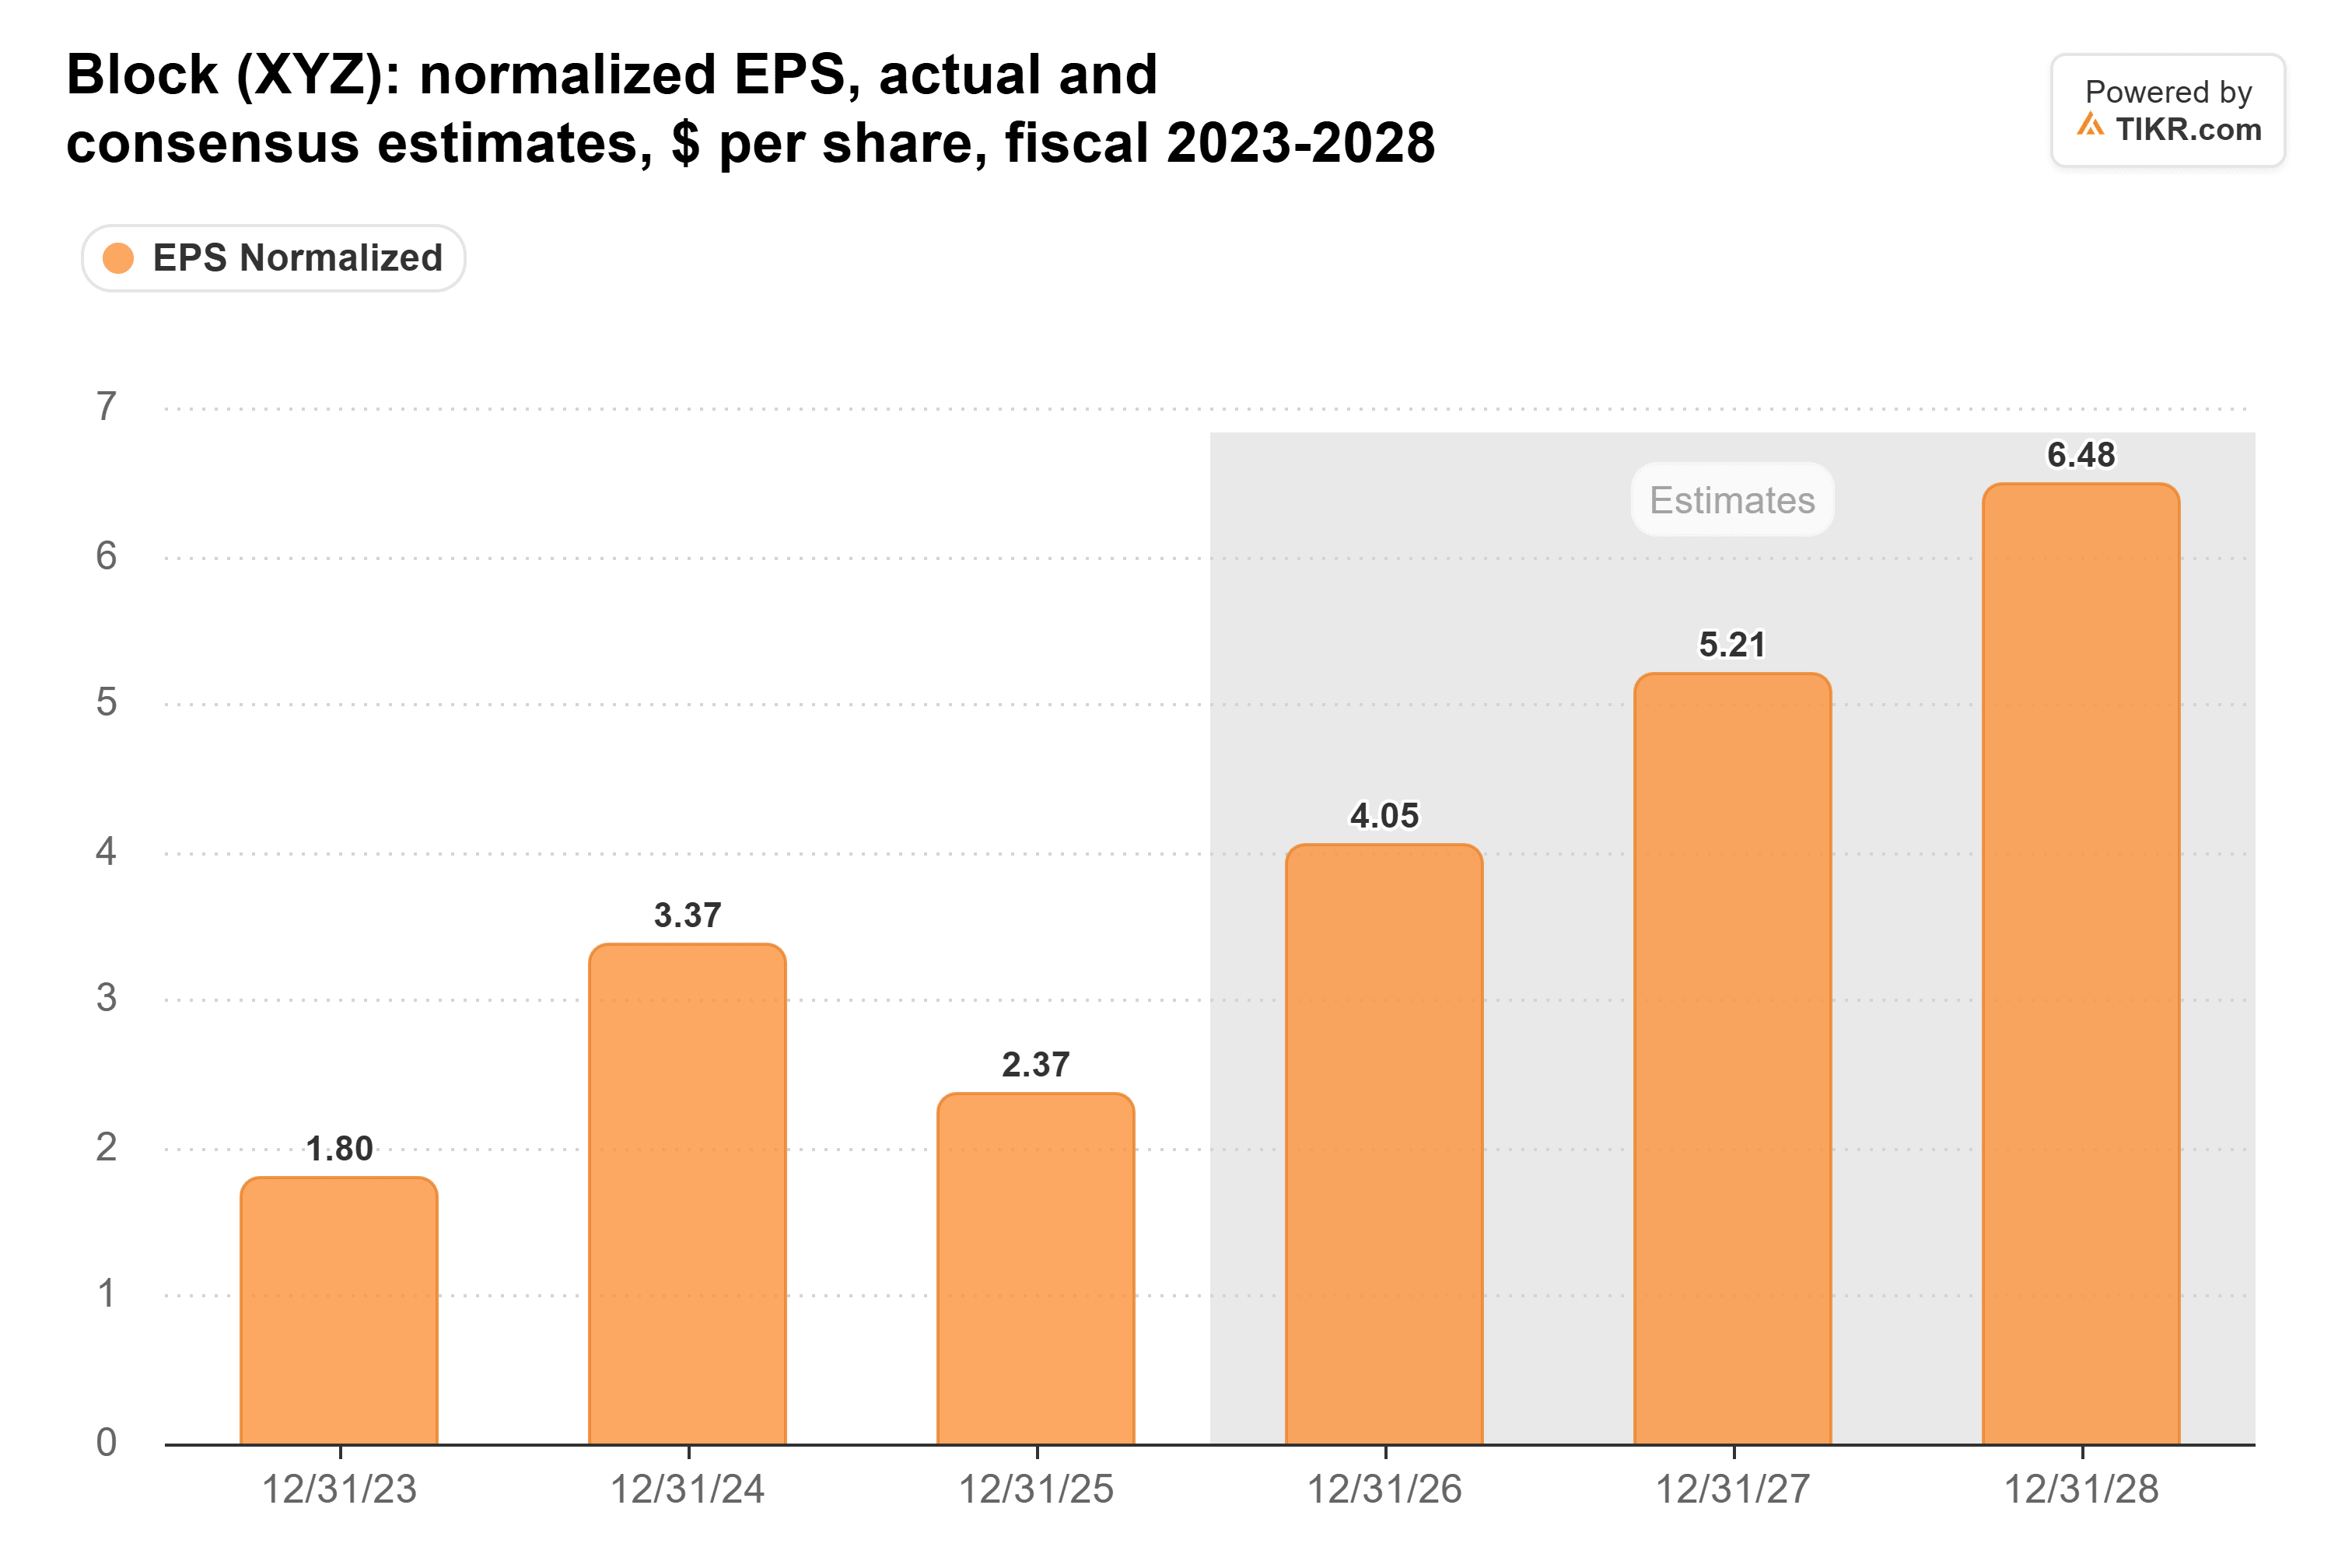
Those estimates have gone up all year. At Sept. 30, 2025, the consensus for 2026 was $3.52, and it’s 15% higher now. The 2027 and 2028 figures have risen by about as much.
Block has given analysts good reason. It has beaten its own guidance every quarter since the third quarter of 2025. It has also raised its 2026 adjusted EPS outlook three times, from $3.20 at its November 2025 investor day to $4.02 in August. Cutting more than 40% of its staff in February helped: adjusted operating income reached 27% of gross profit in the second quarter, up from 22% a year earlier.
TIKR tracks 47 analysts on Block. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Block, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Block’s Analyst Ratings
The stock went the other way
At Friday’s close, Block traded at 17x forward earnings. That’s far below its five-year average of 37x, and closer to its April 2025 low of 11x than to its 2021 peak of 153x:

It’s also below its three-year average of 20x, so the stock is cheap against its more recent history too.
On Wednesday, Morgan Stanley’s James Faucette downgraded Block to Equal Weight from Overweight and cut his price target to $80 from $90. He expects Cash App Borrow originations to slow in the near term as Block moves to longer loans and faces tougher comparisons in the second half. He also thinks those longer loans could push credit losses higher.
Block’s loss expense is already rising fast. Transaction, loan and consumer receivable losses nearly doubled in the second quarter to $585 million, or 18% of gross profit, up from 12% a year earlier. The reserve on consumer loans rose to 14.7% of the book at June 30, from 10.7% at the end of 2025.
What Block has to clear on Tuesday
For the third quarter, management guided for:
- gross profit of $3.13 billion, up 18%
- adjusted operating income of $875 million, or 28% of gross profit
- adjusted EPS of $1.02, up 89%
For the forecasts to hold, Block needs to beat all three and keep its full-year outlook at $4.02 or higher, close to the $4.05 consensus.
Lending growth needs to come in a little cooler too. Loss expense grew 99% in the second quarter. It needs to grow much more slowly and fall as a share of gross profit. Cash App’s gross profit grew 31% in the second quarter, and it needs to keep growing above 20% as Borrow laps origination growth of 134% from a year earlier.
Reported profit is worth checking as well. Block’s GAAP operating margin has been roughly 6%-8% of revenue in six of the past eight quarters:

The first half of 2026 included $495 million of restructuring charges and a $526 million accrual for a Justice Department matter. GAAP operating income was $275 million for the half, against $1.59 billion adjusted. A third-quarter margin above last year’s 6.9% would tell us the staff cut is reaching reported profit.
I’d watch Cash App’s user count just as closely. Monthly transacting actives have been 59 million since December, and I suspect a drop would hurt the stock whatever the margins say.
I’d bet on the forecasts
Here’s where I land: the market has 2026 wrong. Block has beaten its guidance quarter after quarter, and the consensus is just 3 cents above management’s own outlook. Analysts aren’t reaching for this year.
I’d worry more about 2027 and 2028. The 2028 consensus of $6.48 is already 18% above the $5.50 of adjusted EPS that management targeted at its investor day. If Borrow slows the way Morgan Stanley expects, I’d expect analysts to cut those years first.
So if Block beats all three guided numbers and its loss growth slows, 17x looks like the mistake. If it misses on gross profit, or beats only because costs landed later, I’d side with the market.
Of course, Tuesday only covers this year. Block’s 2027 outlook comes with its fourth-quarter results early next year, and that’s when we’ll see how much of the staff-cut savings it keeps.
So what is Block stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Block could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!