


Key Takeaways
- Astera Labs fell 11.6% in the past week (through Monday’s close). It had no news of its own, and worries about inflation and AI debt hit chip stocks.
- Stifel kept its Buy rating and $460 price target through the drop, about 60% above Monday’s close.
- Second-quarter free cash flow fell by about half from a year earlier even as revenue forecasts kept rising, and that’s the main risk.
- At about 51x forward earnings, the stock trades well below its one-year average, and third-quarter results on Nov. 3 need to show cash catching up.
Astera Labs (ALAB) lost 11.6% in the past week (through Monday’s close). That’s roughly three times the Nasdaq 100’s 3.7% drop, and Astera put out no news.
The stock is now 43% below its 52-week high, though it’s still up 72% in 2026.
Astera didn’t give anyone a reason to sell
The slide started just before the week did. Astera fell 9% on Oct. 8 after a [Financial Times report](LINK NEEDED) put OpenAI’s revenue below estimates, and Northland downgraded it to Market Perform on valuation the next morning.
Then two sessions did most of the damage. On Wednesday, Oct. 14, a hot inflation report raised bets on Fed rate hikes. A benchmark chip index fell 4.3%, and Astera dropped 7.7%. Marvell (MRVL) fell 8.7% the same day.
On Friday, worries about AI debt at the neoclouds knocked 2.14% off the Nasdaq Composite, and Astera lost another 5.3%.
Over the week, Marvell fell 11% and Credo Technology (CRDO) 14%. Credo fell even more than Astera, so this was a sector sell-off, and a stock with a five-year beta near 4 takes those hard.
Stifel isn’t flinching
Stifel’s Tore Svanberg kept his Buy rating and $460 price target on Friday, the day of the second drop. That’s about 60% above Monday’s close, and above the $388 consensus target.
The forecasts are moving his way. Consensus 2026 revenue has risen 23% since June 30, to $1.91 billion, with $2.98 billion expected in 2027.

Cash flow has to catch up
The catch is cash. Second-quarter free cash flow was $67.2 million, about half the year before and well short of what analysts expected. It was flat with the first quarter even as revenue grew 27%.
Here’s what’s next
Astera reports third-quarter results after the close on Tuesday, Nov. 3. Management guided to $540 million to $560 million of revenue, and free cash flow needs to land clearly above the second quarter’s. Samples of Aries 7, its new PCIe 7 chips, follow in the fourth quarter.
The stock also got cheaper: 50.9x forward earnings on Friday, down from about 62x on Oct. 8 and well below its 73.9x average over the past year.
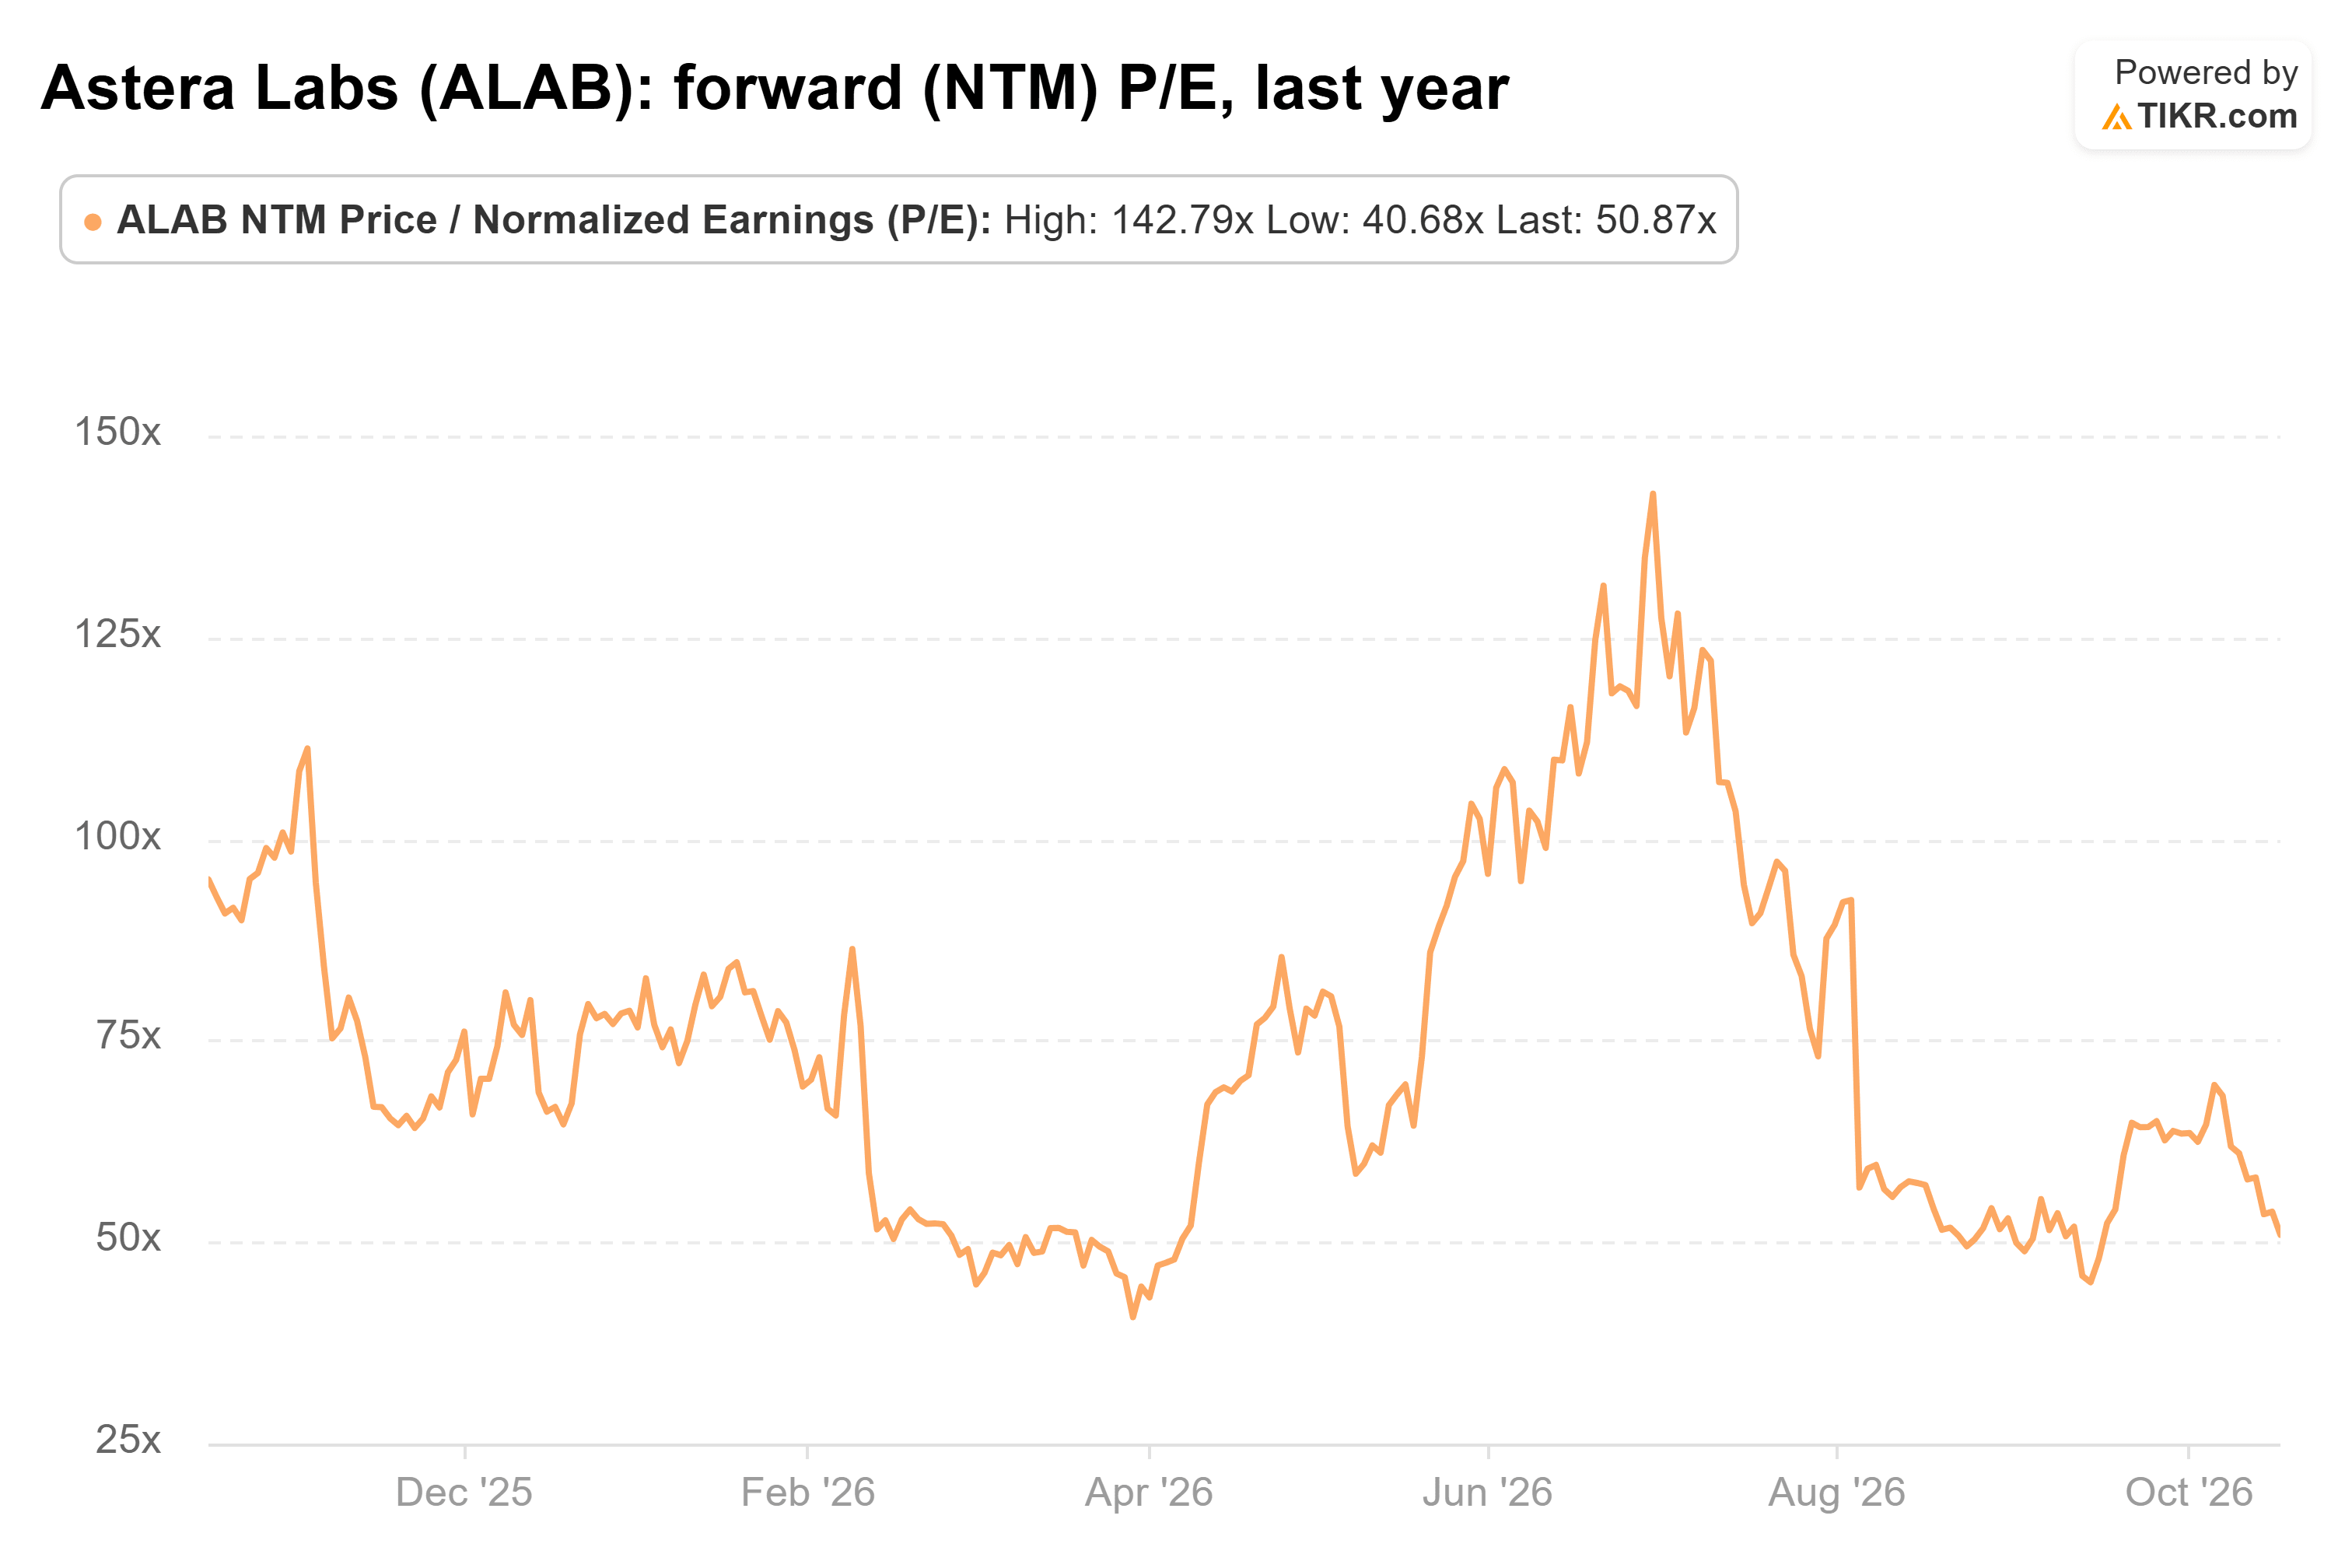
My take: At roughly 51x, Astera looks like a buy for investors who can stomach the swings, and Stifel’s call looks reasonable. But the cash has to show up on Nov. 3, and another flat quarter would make $460 a lot harder to reach.
So what is Astera Labs stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Astera Labs could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


