Key Takeaways:
- AI Networking Demand: Arista posted its first $3 billion quarter, with revenue up 37.7%.
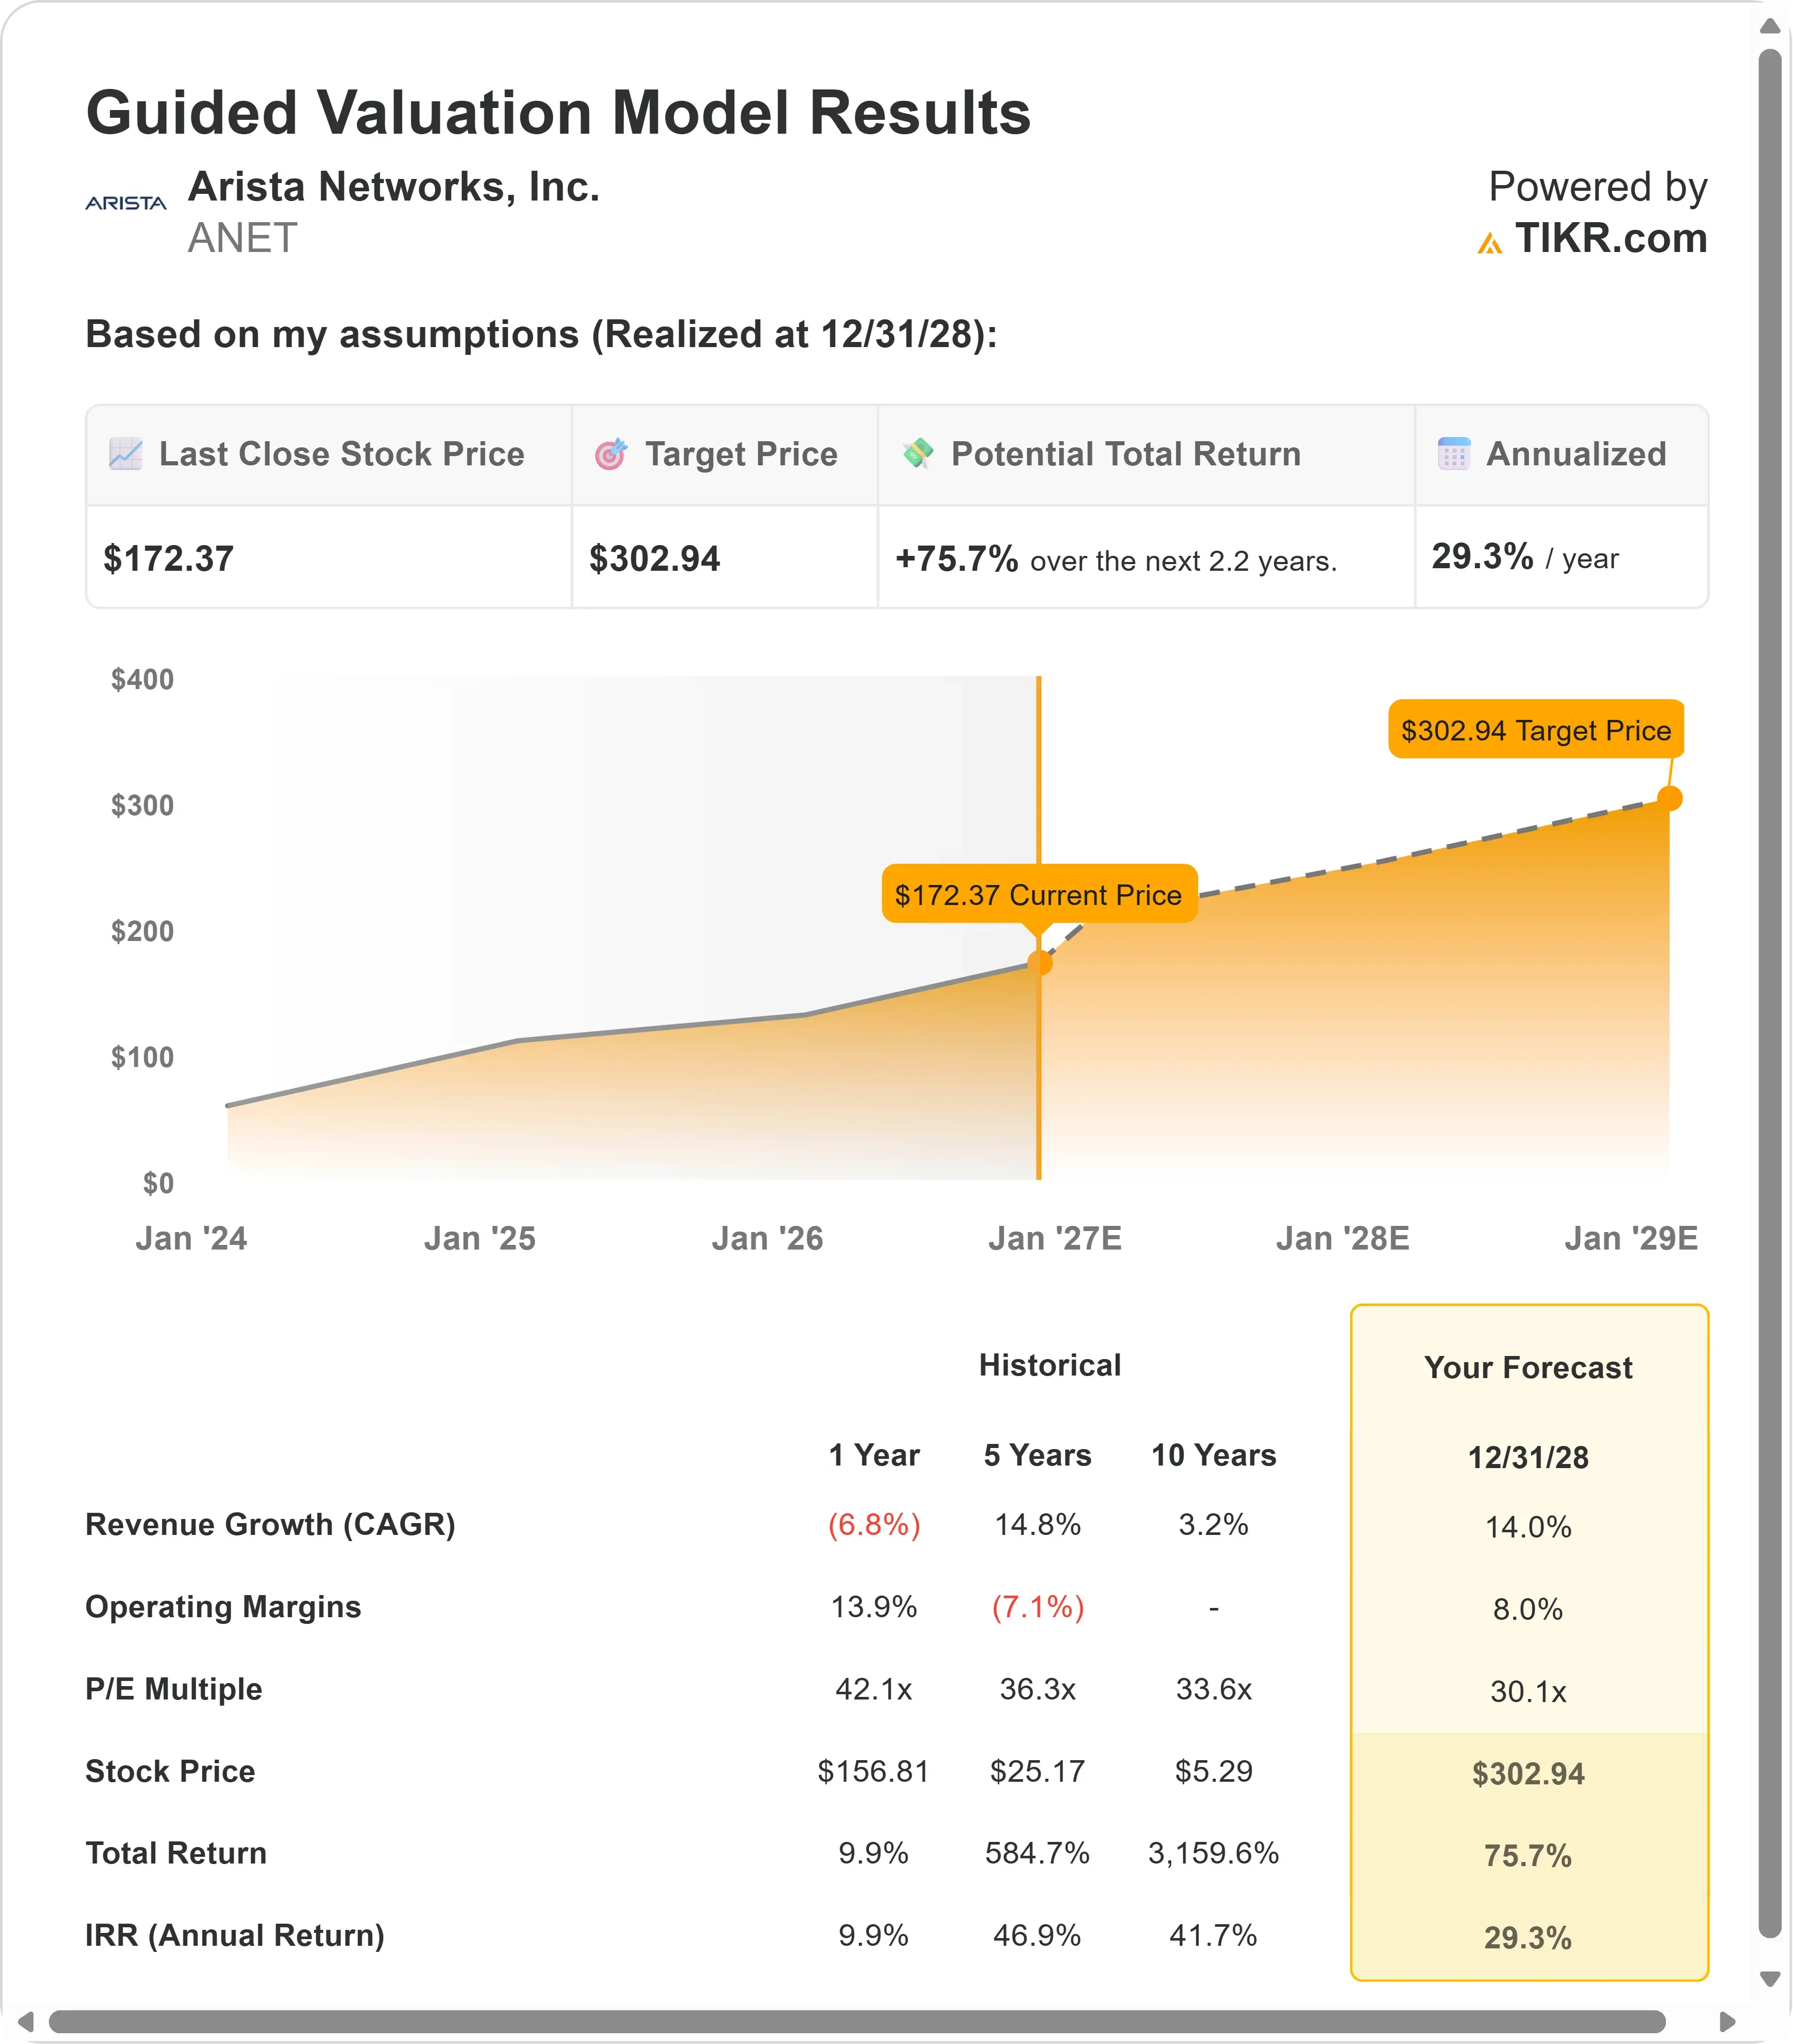
- Price Projection: Based on current execution, ANET stock could reach $303 by December 2028.
- Potential Gains: This target implies a total return of 76% from the current price of $172.37.
- Annual Return: Investors could see roughly 29% growth per year over the next 2.2 years.
Now Live: Discover how much upside your favorite stocks could have using TIKR’s new Valuation Model (It’s free)>>>
Arista Networks (ANET) delivered its best quarter yet in Q2 as revenue topped $3 billion, up 37.7% from a year ago. That was well above the company’s own guidance of $2.8 billion.
Earnings per share rose 39.7% to $1.02 and operating income reached $1.5 billion, a 49.9% margin.
Management raised its 2026 revenue outlook for the third time this year. The new target is about $12.6 billion, or 40% growth, $1.1 billion higher than the May forecast.
Demand is also spreading. More than 100 customers now use Arista’s Etherlink AI switches, and in 2024, there were only four or five.
The company ended the quarter with $13.3 billion in cash and marketable securities.
Even so, the stock has gained only about 13% in the past year. At $172.37, investors may still find value here.
See analysts’ full growth forecasts and estimates for ANET stock (It’s free) >>>
What the Model Says for Arista Networks Stock
We looked at Arista as AI data centers grow larger and more spread out.
Power and space are scarce, so AI companies are linking data centers across regions. Arista calls this “scale-across,” and its 7800 switch is the flagship product for it.
The market for this is forecast at $15 billion to $20 billion by 2030. Today it is roughly $3 billion to $4 billion. Scale-across should make up about 30% of Arista’s AI target this year.
Arista’s software also gives it an edge. It lets customers upgrade switches without downtime. CEO Jayshree Ullal says buyers prefer this over cheaper “white box” hardware, which needs more staff to run.
Using a forecast of 14% annual revenue growth and 8% operating margins, our model projects the stock will rise to $302.94 by December 31, 2028. This assumes a 30.1x price-to-earnings multiple.
That is below today’s 37.1x forward P/E. It is also well below the one-year average of 42.1x.
Our Valuation Assumptions
Estimate a company’s fair value instantly (Free with TIKR) >>>
Our Valuation Assumptions
TIKR’s Valuation Model lets you plug in your own assumptions for a company’s revenue growth, operating margins, and P/E multiple, and calculates the stock’s expected returns.
Here’s what we used for Arista Networks stock:
1. Revenue Growth: 14%
Arista’s five-year revenue growth rate is 14.8%, and our estimate sits just below it.
It is far below the 40% growth management expects in 2026, as we assume that pace will cool over time.
Still, the growth drivers are real. Arista expects one, maybe two, customers to account for over 10% of sales, on top of Microsoft and Meta.
Its next-generation 1.6T switches enter trials in the second half of 2026. Production should follow in 2027. Price increases should also start helping late this year or next.
2. Operating margins: 8%
Operating margin of 11.1% over the last twelve months, and we use a cautious 8%.
Arista’s own results run much higher. Its Q2 operating margin was 49.9%, and it now targets 48% to 49% for 2026.
Costs are a risk, though. Memory and chip prices are rising, and gross margin is guided at 62% to 64%.
Arista has also tripled its purchase commitments to $9.7 billion. Ullal says industry supply problems may last until 2028.
3. Exit P/E Multiple: 30.1x
The market values Arista at 37.1x forward earnings, while we assume this falls to 30.1x.
That is below the 10-year average of 33.6x and the five-year average of 36.3x.
Lower multiples are common as growth slows. Even so, Arista’s AI exposure and strong cash flow should keep some premium in place.
Build your own Valuation Model to value any stock (It’s free!) >>>
What Happens If Things Go Better or Worse?
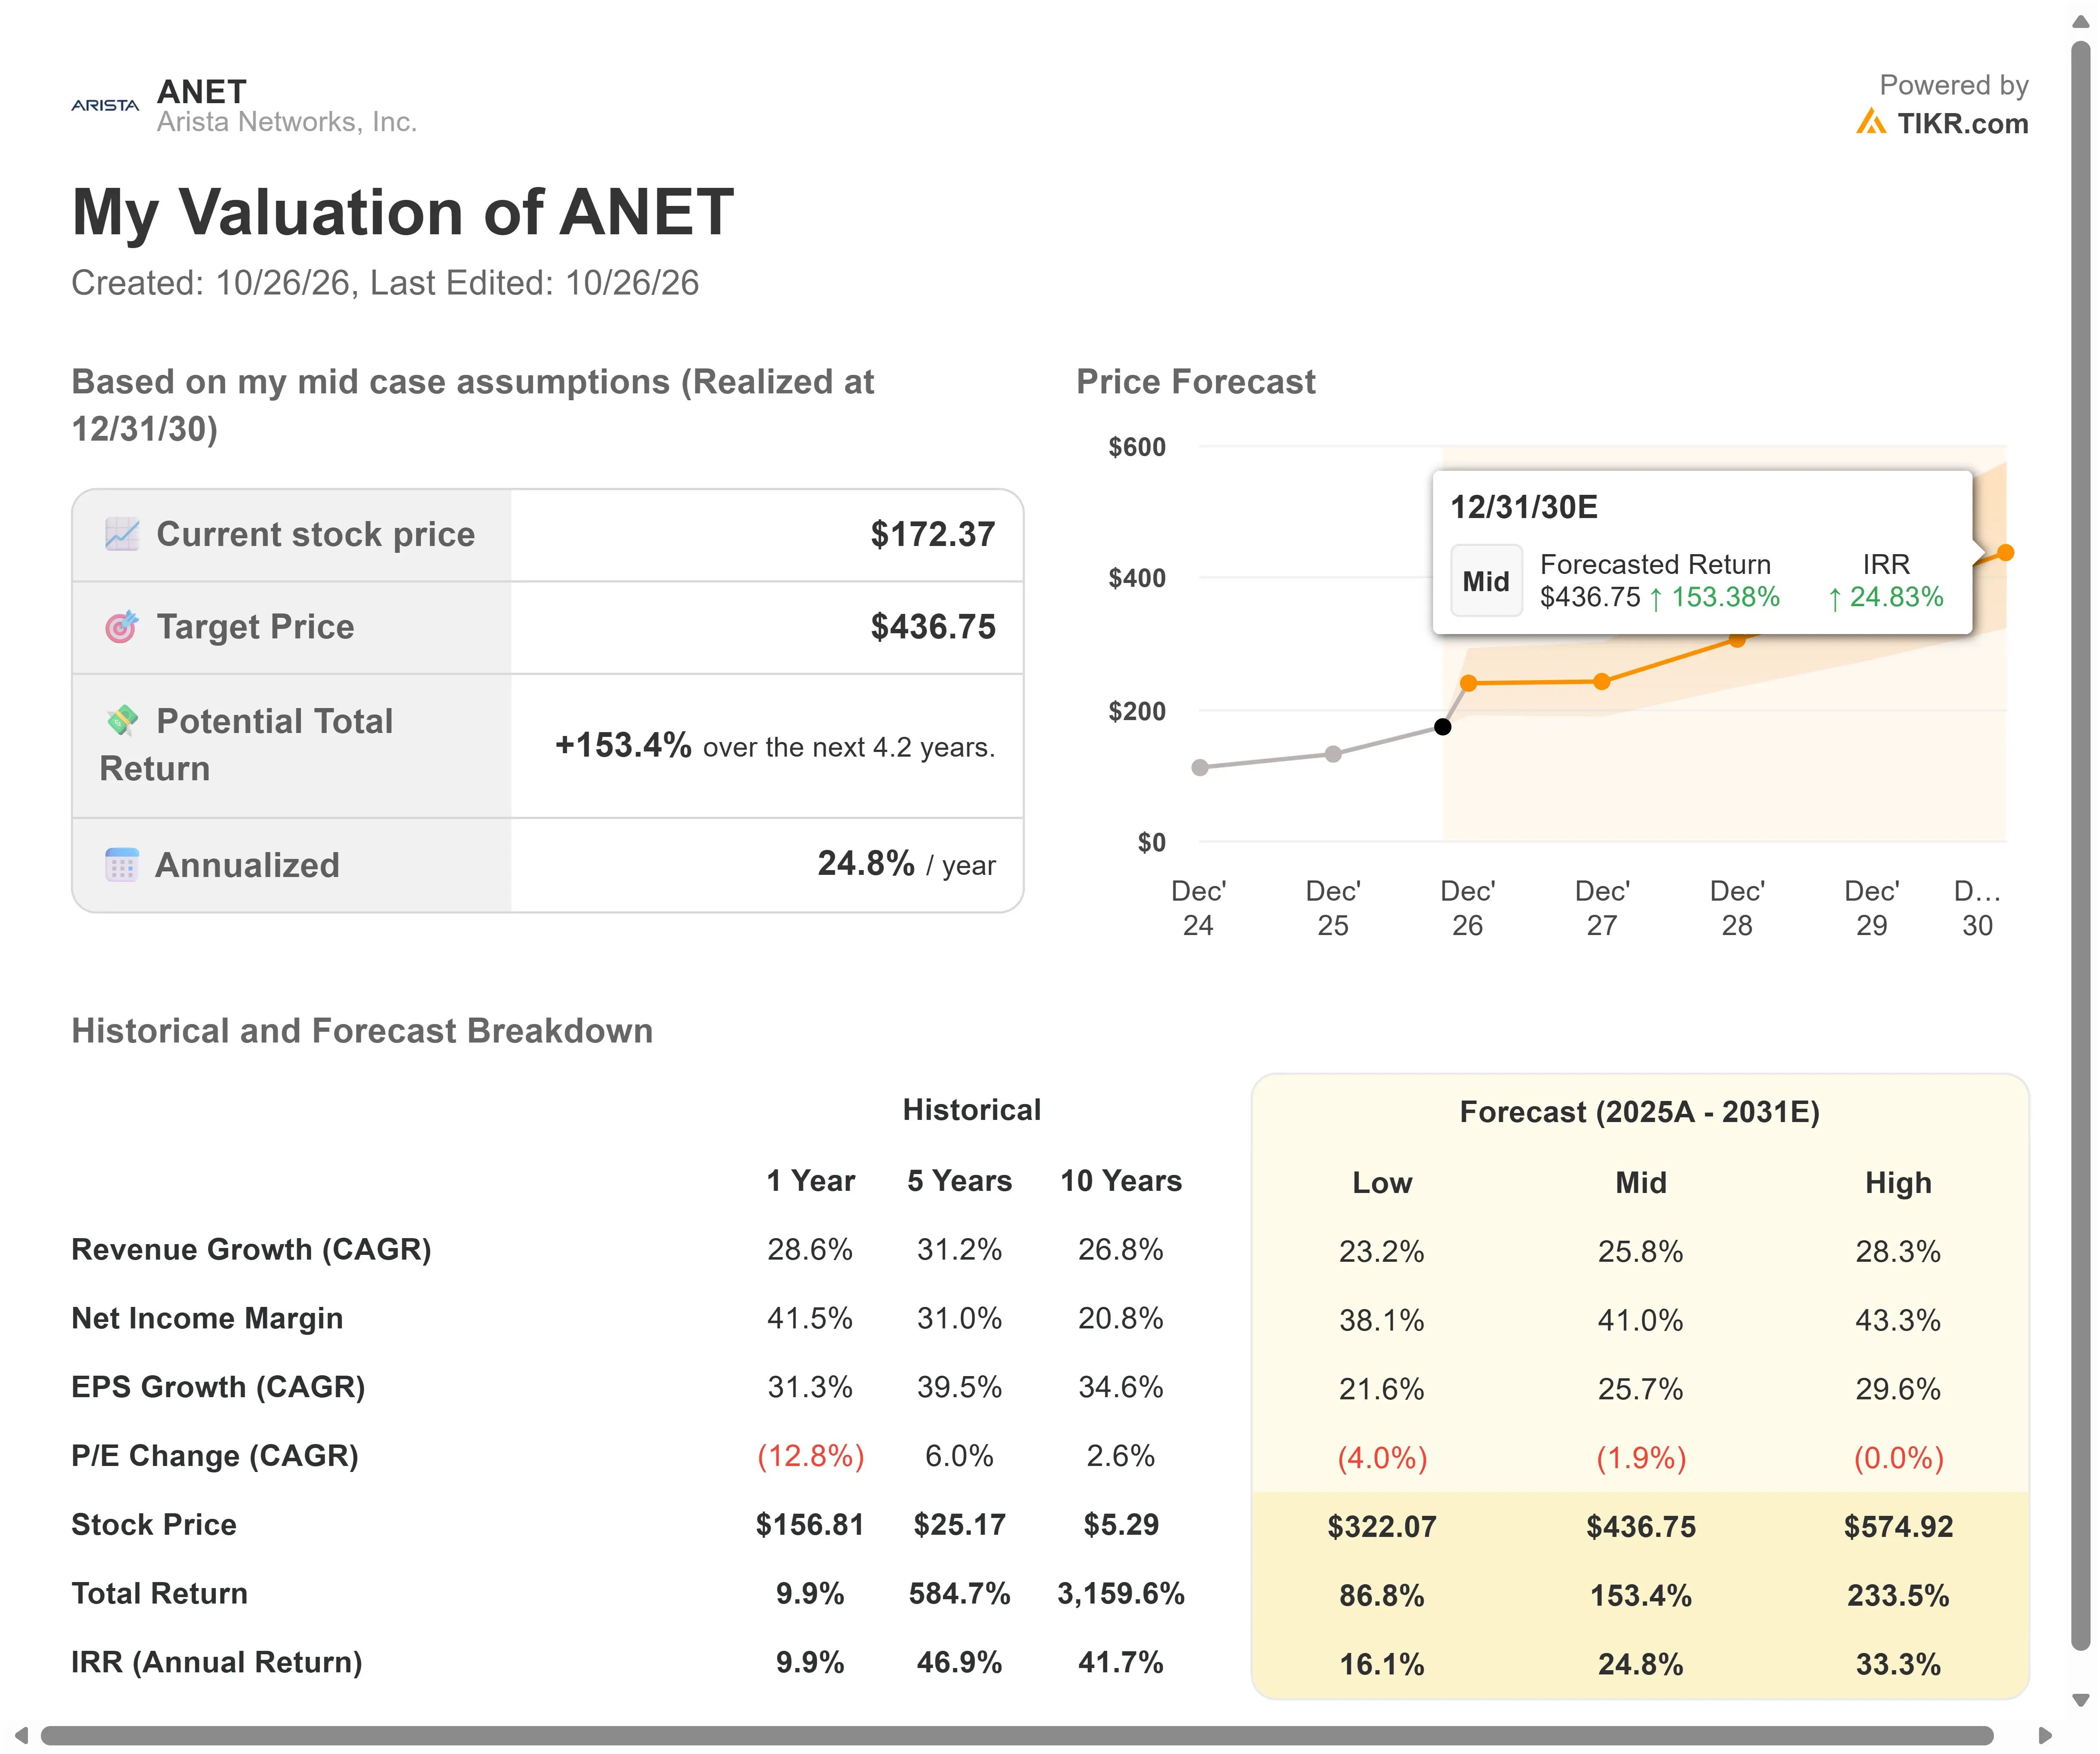
Networking demand moves in cycles, and AI spending can slow. Here’s how Arista stock might perform under different scenarios through December 2030:
- Low Case: If revenue growth slows to 23.2% and net income margins fall to 38.1%, investors still see an 86.8% total return (16.1% annually). That implies a price of $322.07.
- Mid Case: With 25.8% growth and 41.0% margins, we expect a total return of 153.4% (24.8% annually). That implies a price of $436.75.
- High Case: If growth reaches 28.3% and margins hold at 43.3%, returns could hit 233.5% total (33.3% annually). That implies a price of $574.92.
See what analysts think about ANET stock right now (Free with TIKR) >>>
The range depends on how long AI data center spending lasts.
In the low case, supply shortages limit shipments or big customers cut orders.
In the high case, Arista wins more AI labs and cloud customers. Scale-across demand also grows faster than expected.
How Much Upside Does Arista Networks Stock Have From Here?
With TIKR’s new Valuation Model tool, you can estimate a stock’s potential share price in under a minute.
All it takes is three simple inputs:
- Revenue Growth
- Operating Margins
- Exit P/E Multiple
If you’re not sure what to enter, TIKR automatically fills in each input using analysts’ consensus estimates, giving you a quick, reliable starting point.
From there, TIKR calculates the potential share price and total returns under Bull, Base, and Bear scenarios so you can quickly see whether a stock looks undervalued or overvalued.
See a stock’s true value in under 60 seconds (Free with TIKR) >>>
Looking for New Opportunities?
- See what stocks billionaire investors are buying so you can follow the smart money.
- Analyze stocks in as little as 5 minutes with TIKR’s all-in-one, easy-to-use platform.
- The more rocks you overturn… the more opportunities you’ll uncover. Search 100K+ global stocks, global top investor holdings, and more with TIKR.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!