Key Stats for Apple Stock
- Current Price: $343.99
- Target Price (Mid): ~$485
- Street Target: ~$328
- Potential Total Return: ~41%
- Annualized IRR: ~9% / year
Now Live: Discover how much upside your favorite stocks could have using TIKR’s new Valuation Model (It’s free) >>>
What Happened?
Apple (AAPL) has reportedly raised its iPhone Duo shipment target about 44%, a day before the $1,999 foldable reaches stores on October 23. DigiTimes reported on October 22 that, according to supply chain sources, Foxconn and component makers received instructions lifting the 12-month target from 9.7 million to 14 million units. Apple has not confirmed the report. It lands two days after Loop Capital cut the stock to Hold from Buy, arguing Apple will not recover iPhones trimmed from its second-half plans, and with shares at $343.99 at the October 21 close, above Wall Street’s average target of around $328.
A Bigger Duo Build Meets a 7% December Bar
DigiTimes said output still depends on assembly progress after earlier hinge and display problems, and the fast preorder sellout partly reflects thin launch supply: an Apple spokesperson said stores will have only limited walk-in stock. The 14 million figure covers 12 months, and estimates for calendar 2026 run lower: JPMorgan analysts see 8 million to 9 million Duos, according to CNBC, and China’s Securities Times reported on October 12 that supply for the rest of 2026 would stay under 10 million even after a 30% order increase. Apple is also adding U.S. suppliers, committing up to $100 million over three years for titanium from Pennsylvania-based Perryman, a small sum next to $416.2 billion in fiscal 2025 revenue.
None of this shows up in the numbers on November 2, when Apple reports fiscal fourth-quarter results after the market close. The September quarter ended September 26, so the Duo falls into the December quarter, where Street estimates on TIKR sit around $153 billion, roughly 7% growth after 16% a year earlier. The September event introduced only the iPhone 18 Pro, 18 Pro Max, and Duo, with no new base model, so this holiday’s only new iPhones are Apple’s three most expensive. Profit is expected to lag sales: Street estimates on TIKR put December-quarter operating income (EBIT) up only about 0.5% and adjusted EPS at around $2.87, about 1% above last year’s $2.84. Apple has said it expects to pay more for memory chips.

TIKR tracks 44 analysts on Apple. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Apple, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Apple’s Analyst Ratings
Services Gets an AI Lever as Regulators Target Its Fees
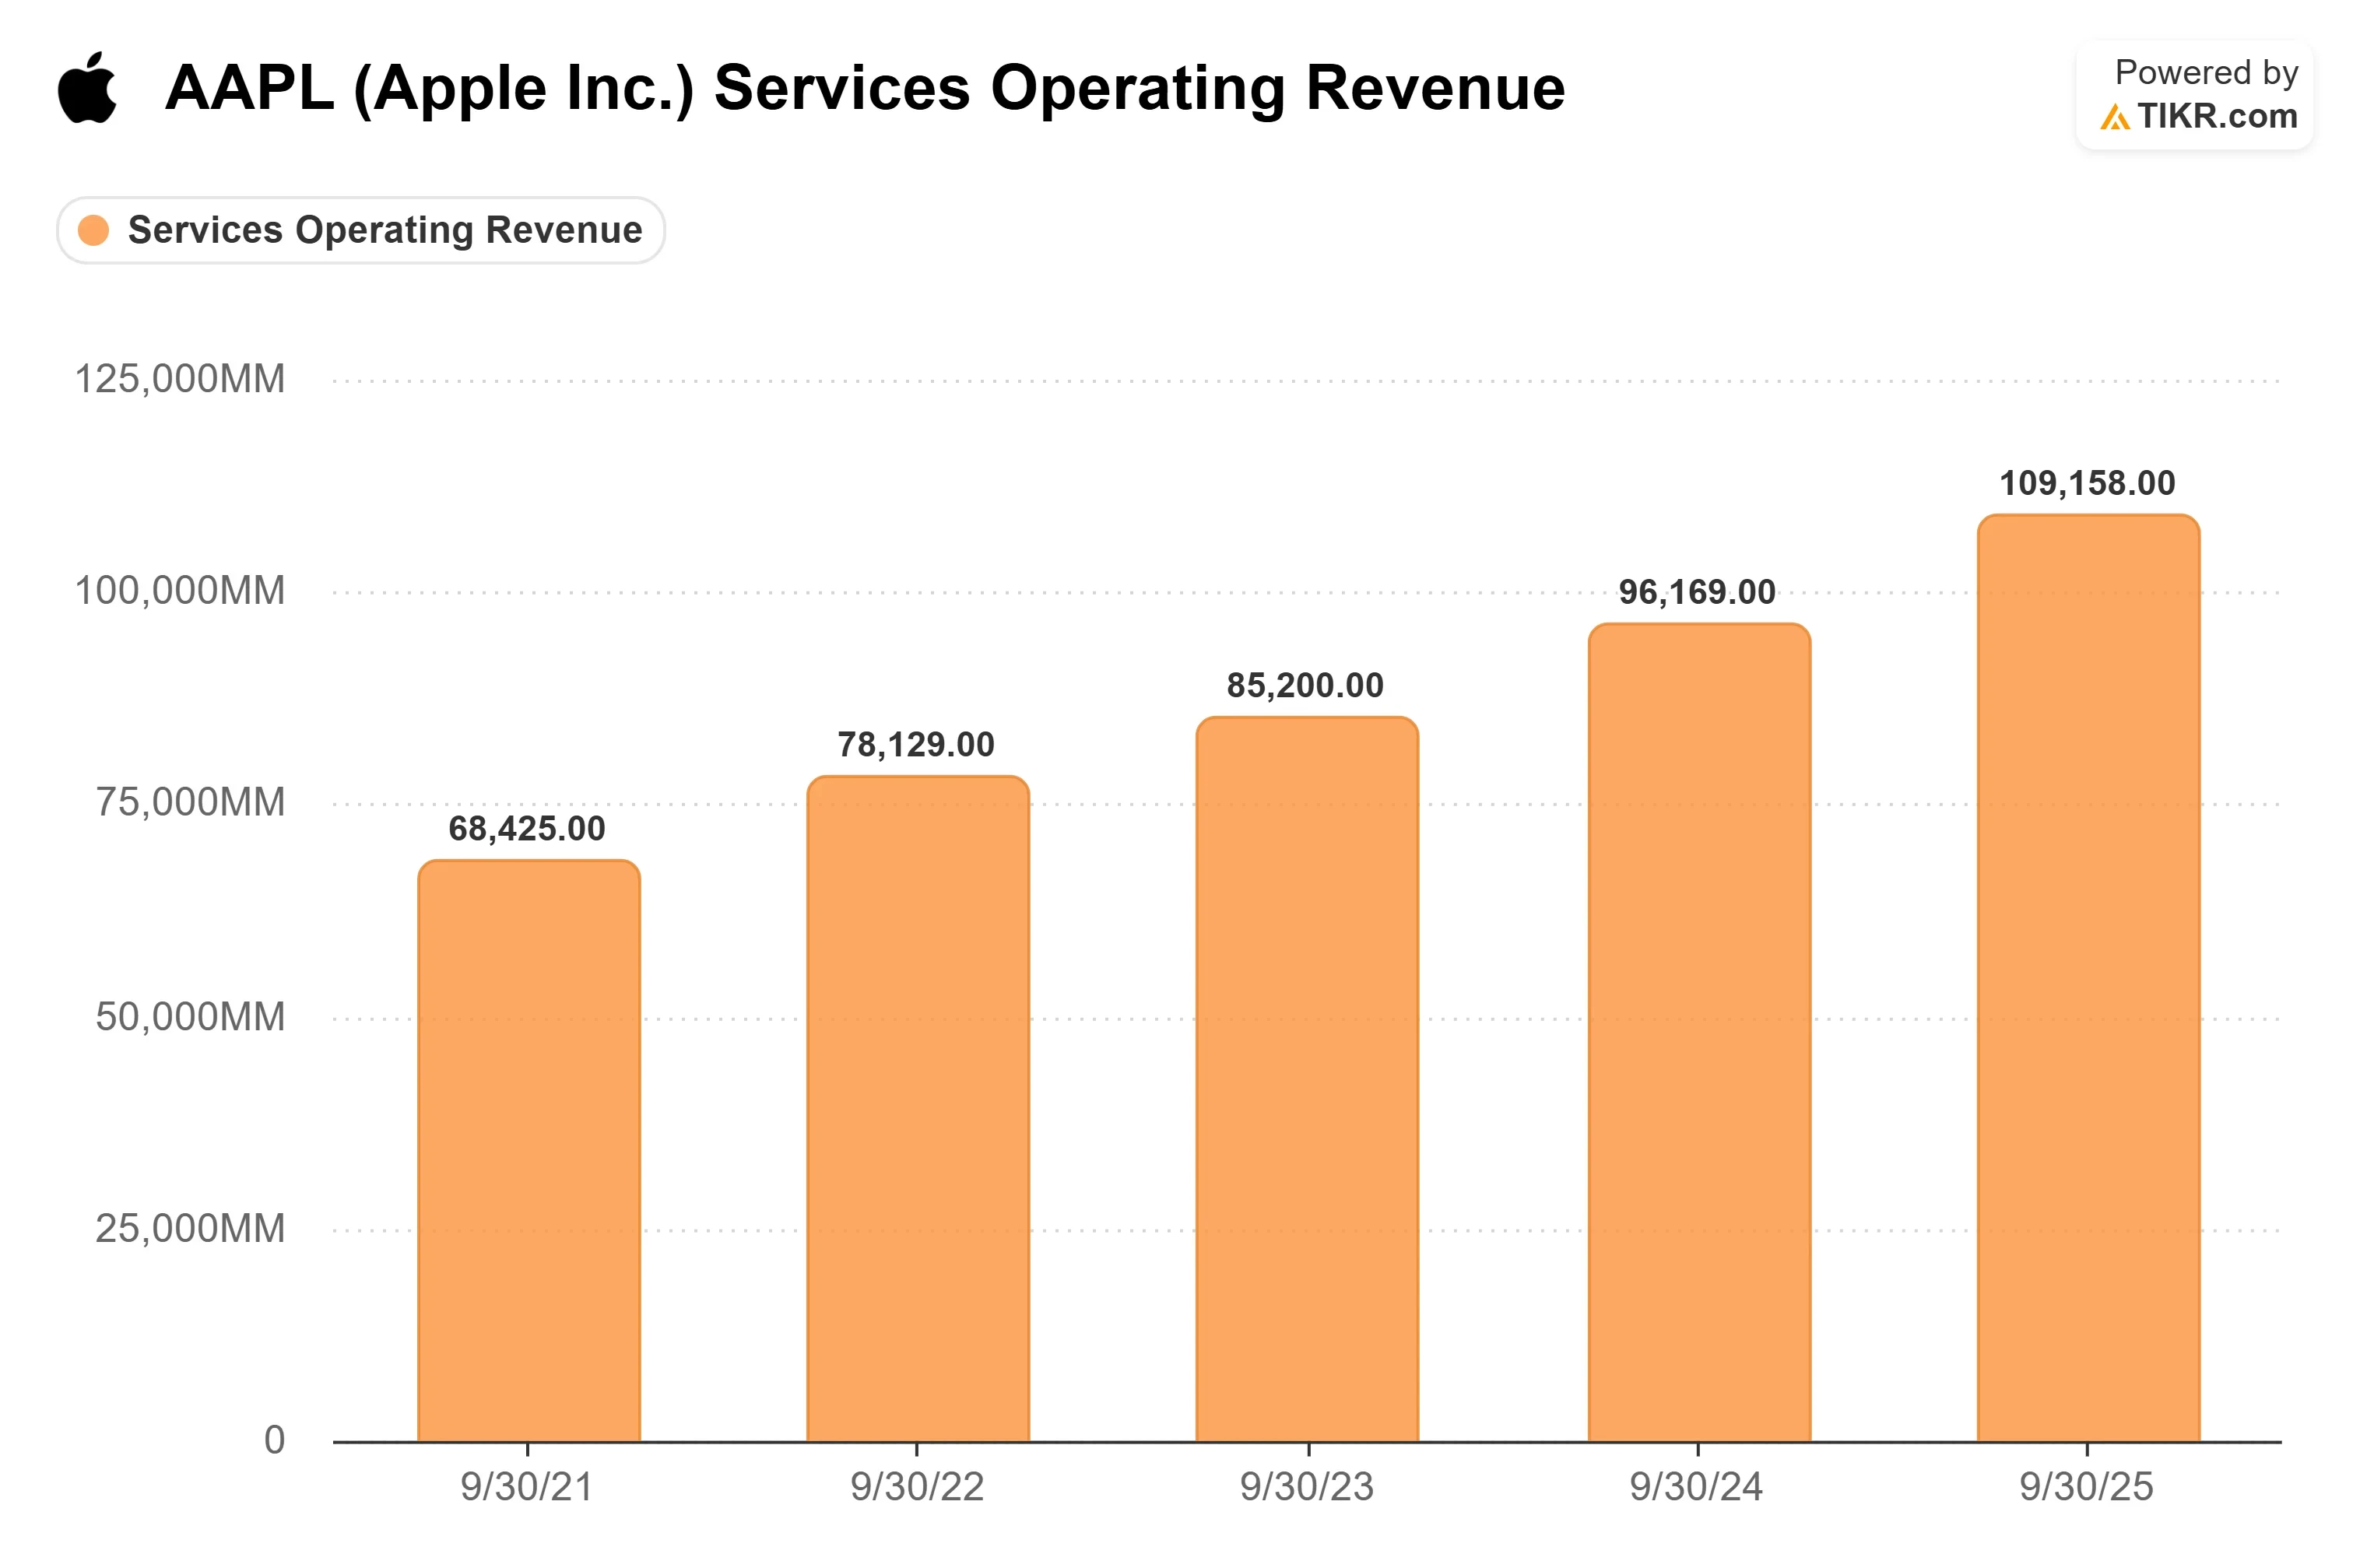
Services brought in $109.2 billion in fiscal 2025, about 26% of revenue, and the September event added a quiet lever. Apple said some of its new AI features will have usage limits because they rely on server models, with more access on most iCloud+ plans. With Siri handling more than 2.5 billion requests a day, that could steer users toward paid tiers, though Siri AI is still in beta. CEO John Ternus put the iPhone at the center: “there’s no product in the world better designed to be your intelligent personal hub than iPhone.”
Regulators are pressing on the fees around it. On October 20, the UK’s Competition and Markets Authority proposed wider, cheaper access for rival wallets to the iPhone’s tap-to-pay chip; Apple says developers can already offer contactless payments, and the consultation runs to November 17. Separately, in a case brought by Epic Games, Australia’s Federal Court ordered Apple to allow rival app stores and outside payments for Australian users from March 1, 2027, with a possible extension to May 3, 2027. Apple told Reuters it plans to appeal.
TIKR Advanced Model Analysis
- Current Price: $343.99
- Target Price (Mid): ~$485
- Potential Total Return: ~41%
- Annualized IRR: ~9% / year
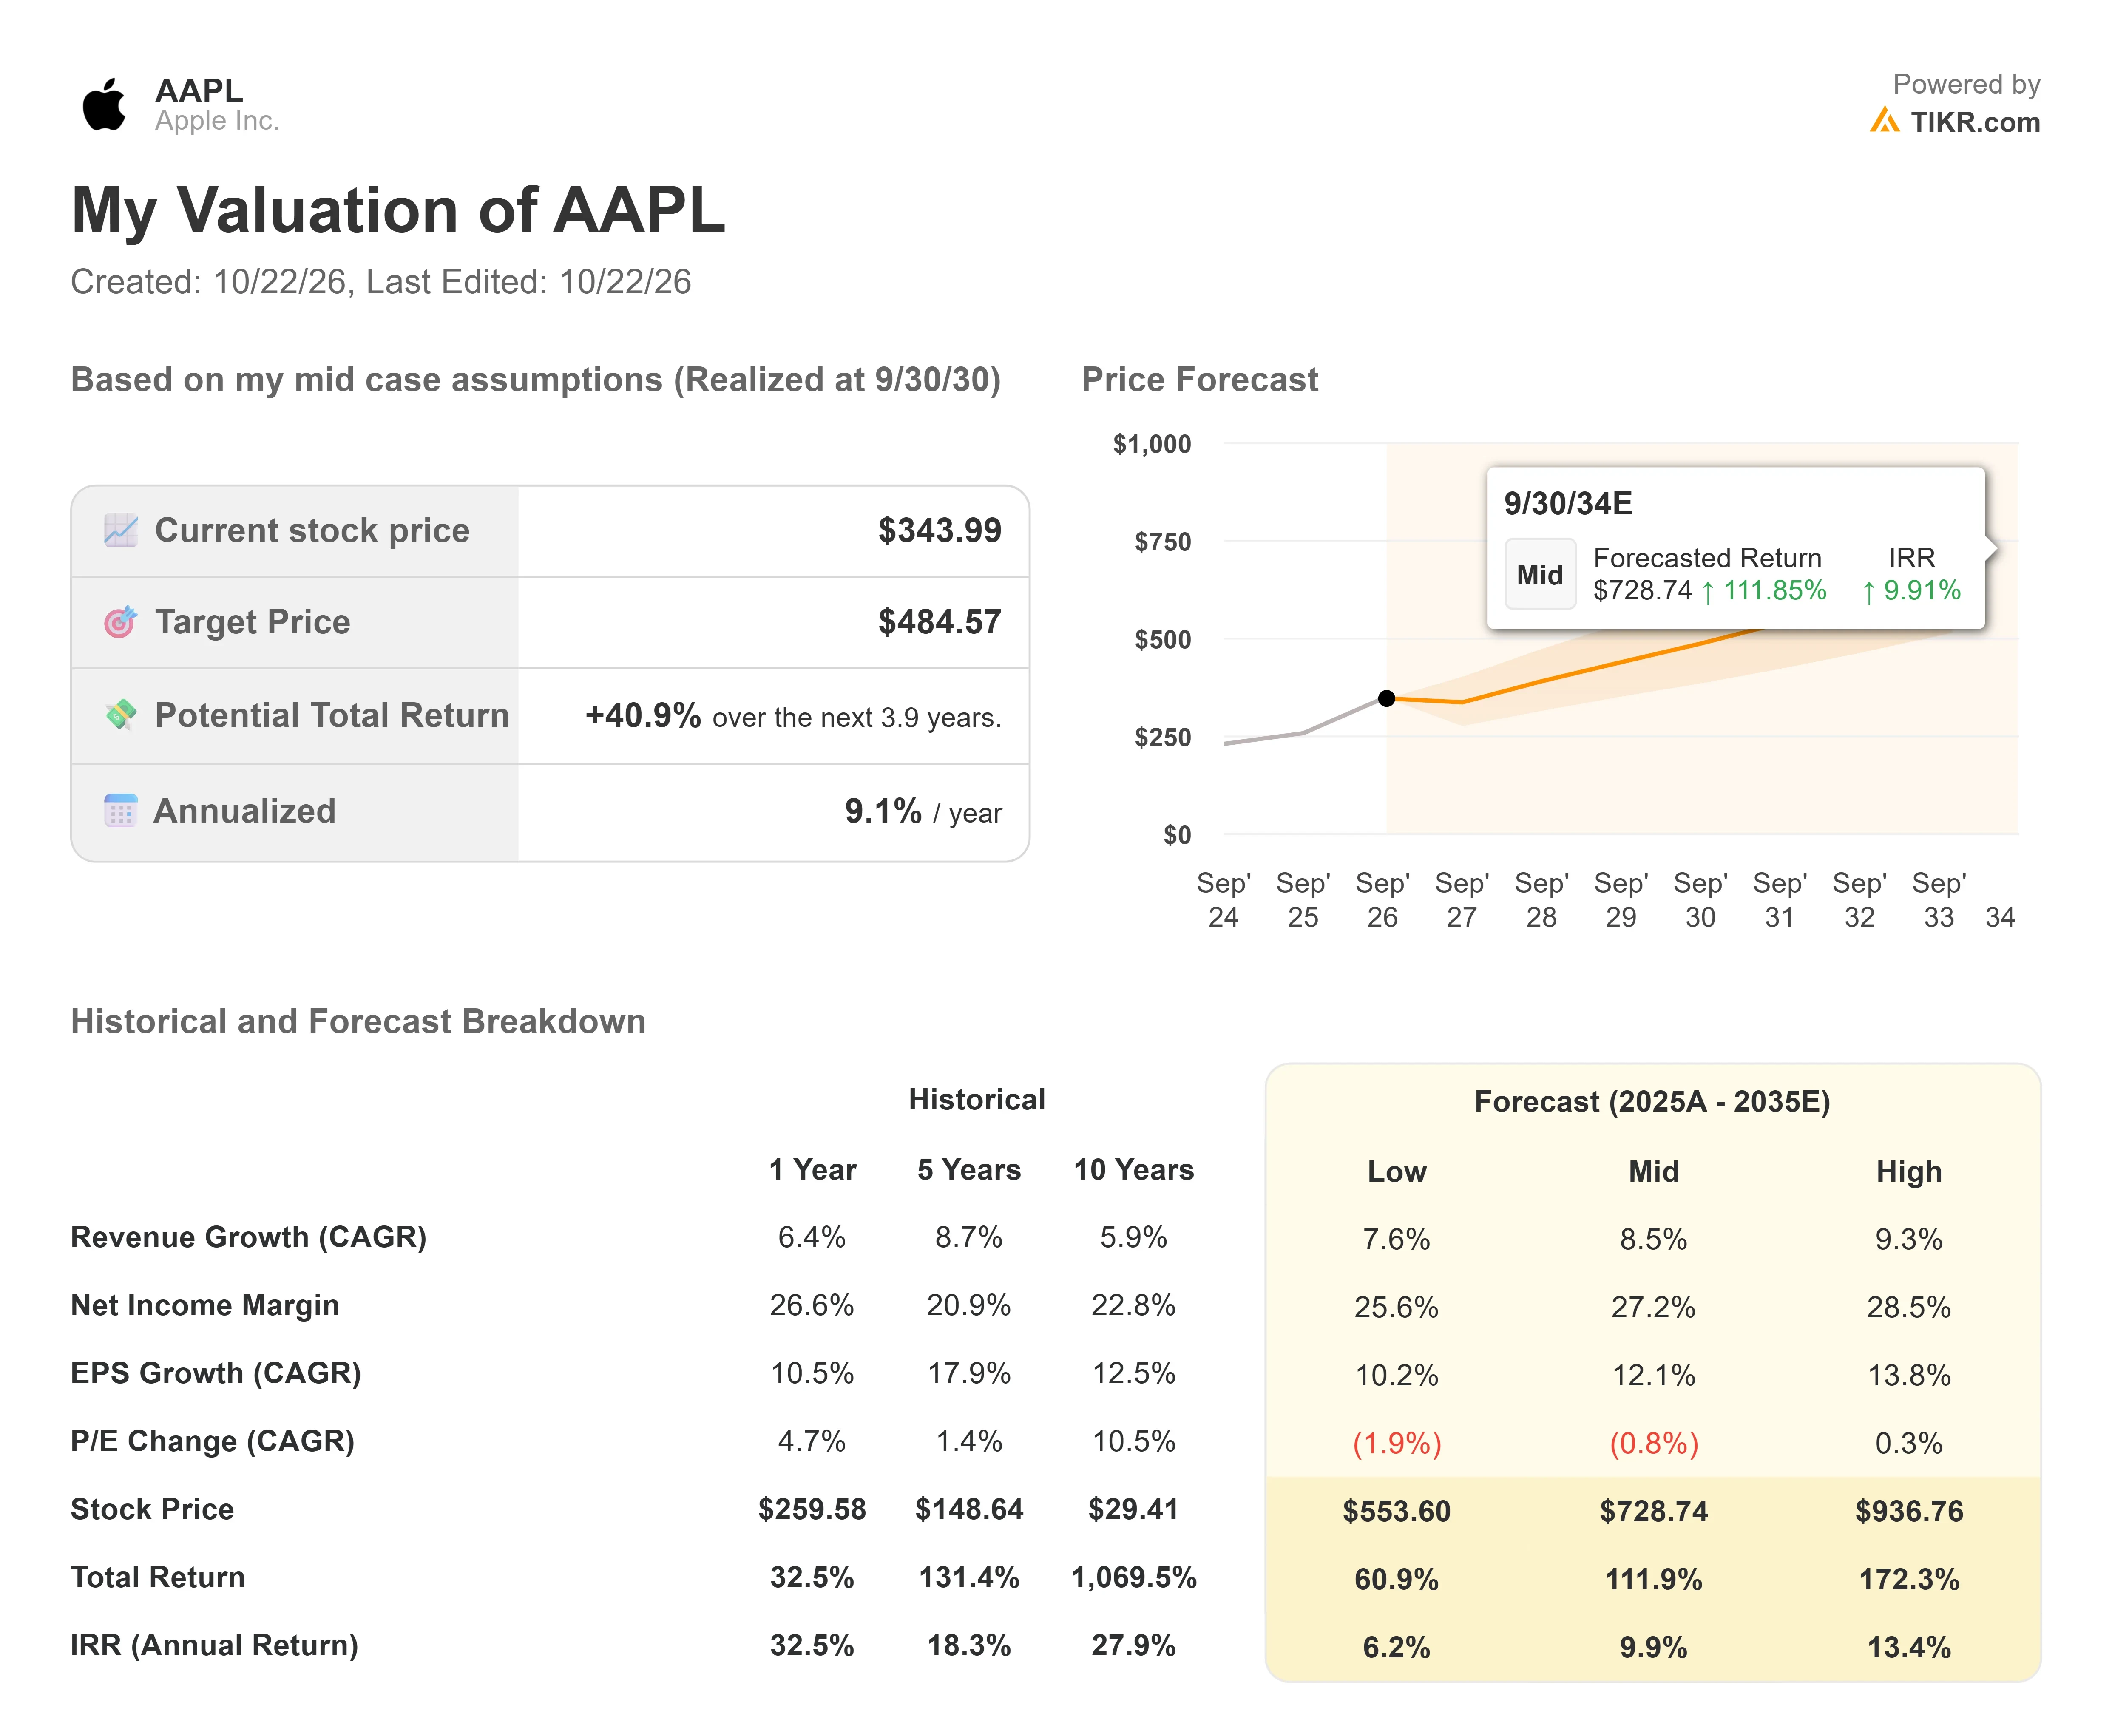
The TIKR model’s mid case puts Apple at around $485 by September 30, 2030, a total return of about 41%, or around 9% a year from $343.99. That return leans on a multiple the market granted only recently: since late March, shares rose about 38% while forward earnings estimates rose about 7%, lifting the forward P/E from about 29x to about 37x. The main risk is a reset if December guidance disappoints; shares fell 7.35% on July 31 after the last soft outlook. Sentiment has cooled, with Sell ratings up from one in late June to three and Buy ratings down from 22 to 18. Upside needs a Duo ramp plus paid AI tiers that justify the premium.
Conclusion
November 2 comes down to December-quarter revenue guidance. Growth well above the Street’s roughly 7% would show the bigger Duo build reflects real demand, not a launch squeeze. Guidance near 7% would leave a 37x stock leaning on AI subscriptions while its payment and App Store fees face pressure in the UK and Australia.
So what is Apple stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Apple could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!