Key Takeaways
- American Express (AXP) shares have gained 9% in the past month, which puts them right around Citi’s $335 and Evercore ISI’s $330 Hold targets.
- At 17x forward earnings, the stock trades right at its 10-year average, so further gains have to come from earnings growth.
- Today’s price assumes analysts are right that normalized EPS grows about 13% in fiscal 2027 and 15% in fiscal 2028, faster than revenue’s 9%.
- If the multiple holds and the estimates come in, the stock would be near the $380 targets in about a year, and the Q4 report in January is the next test.
American Express has gained 9% in the past month, and 4% in the past week.
At the last close, the stock sat less than 1% below Citi’s $335 target and about 1% above Evercore ISI’s $330. Both firms rate it Hold.
So investors need a new question. Earlier this month, the debate was what American Express’s latest quarter said about a rebound and whether the price reflected Bill Ackman’s warning. Now that the rebound has happened, the question is what today’s price already assumes.
TIKR tracks 32 analysts on American Express. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on American Express, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See American Express’ Analyst Ratings
Guidance went up, and so did the targets
American Express raised its outlook in its Q3 release in October. It now expects 2026 EPS of $18.30-$18.60, or $17.60-$17.90 adjusted, and says it’s on track for another year of 10% revenue growth.
Adjusted EPS for the quarter was $4.68, up 13% on 9% revenue growth.
Five firms updated their calls in the last week of October:
- J.P. Morgan: Buy, $365 target (Oct. 30)
- Citi: Hold, $335, down from $340 (Oct. 27)
- Evercore ISI: Hold, $330, up from $320 (Oct. 26)
- Morgan Stanley: Hold, $380 (Oct. 26)
- BMO Capital: Buy, $380 (Oct. 26)
At the last close, the stock had reached the two lowest. J.P. Morgan’s target sat about 10% above it, and the two $380 targets were about 14% above it.
The consensus for fiscal 2026 normalized EPS is $17.82, which lands inside management’s adjusted range. So this year is close to settled, and what matters for the price is the years after it.
Analysts see EPS climbing to $23.21 by fiscal 2028.
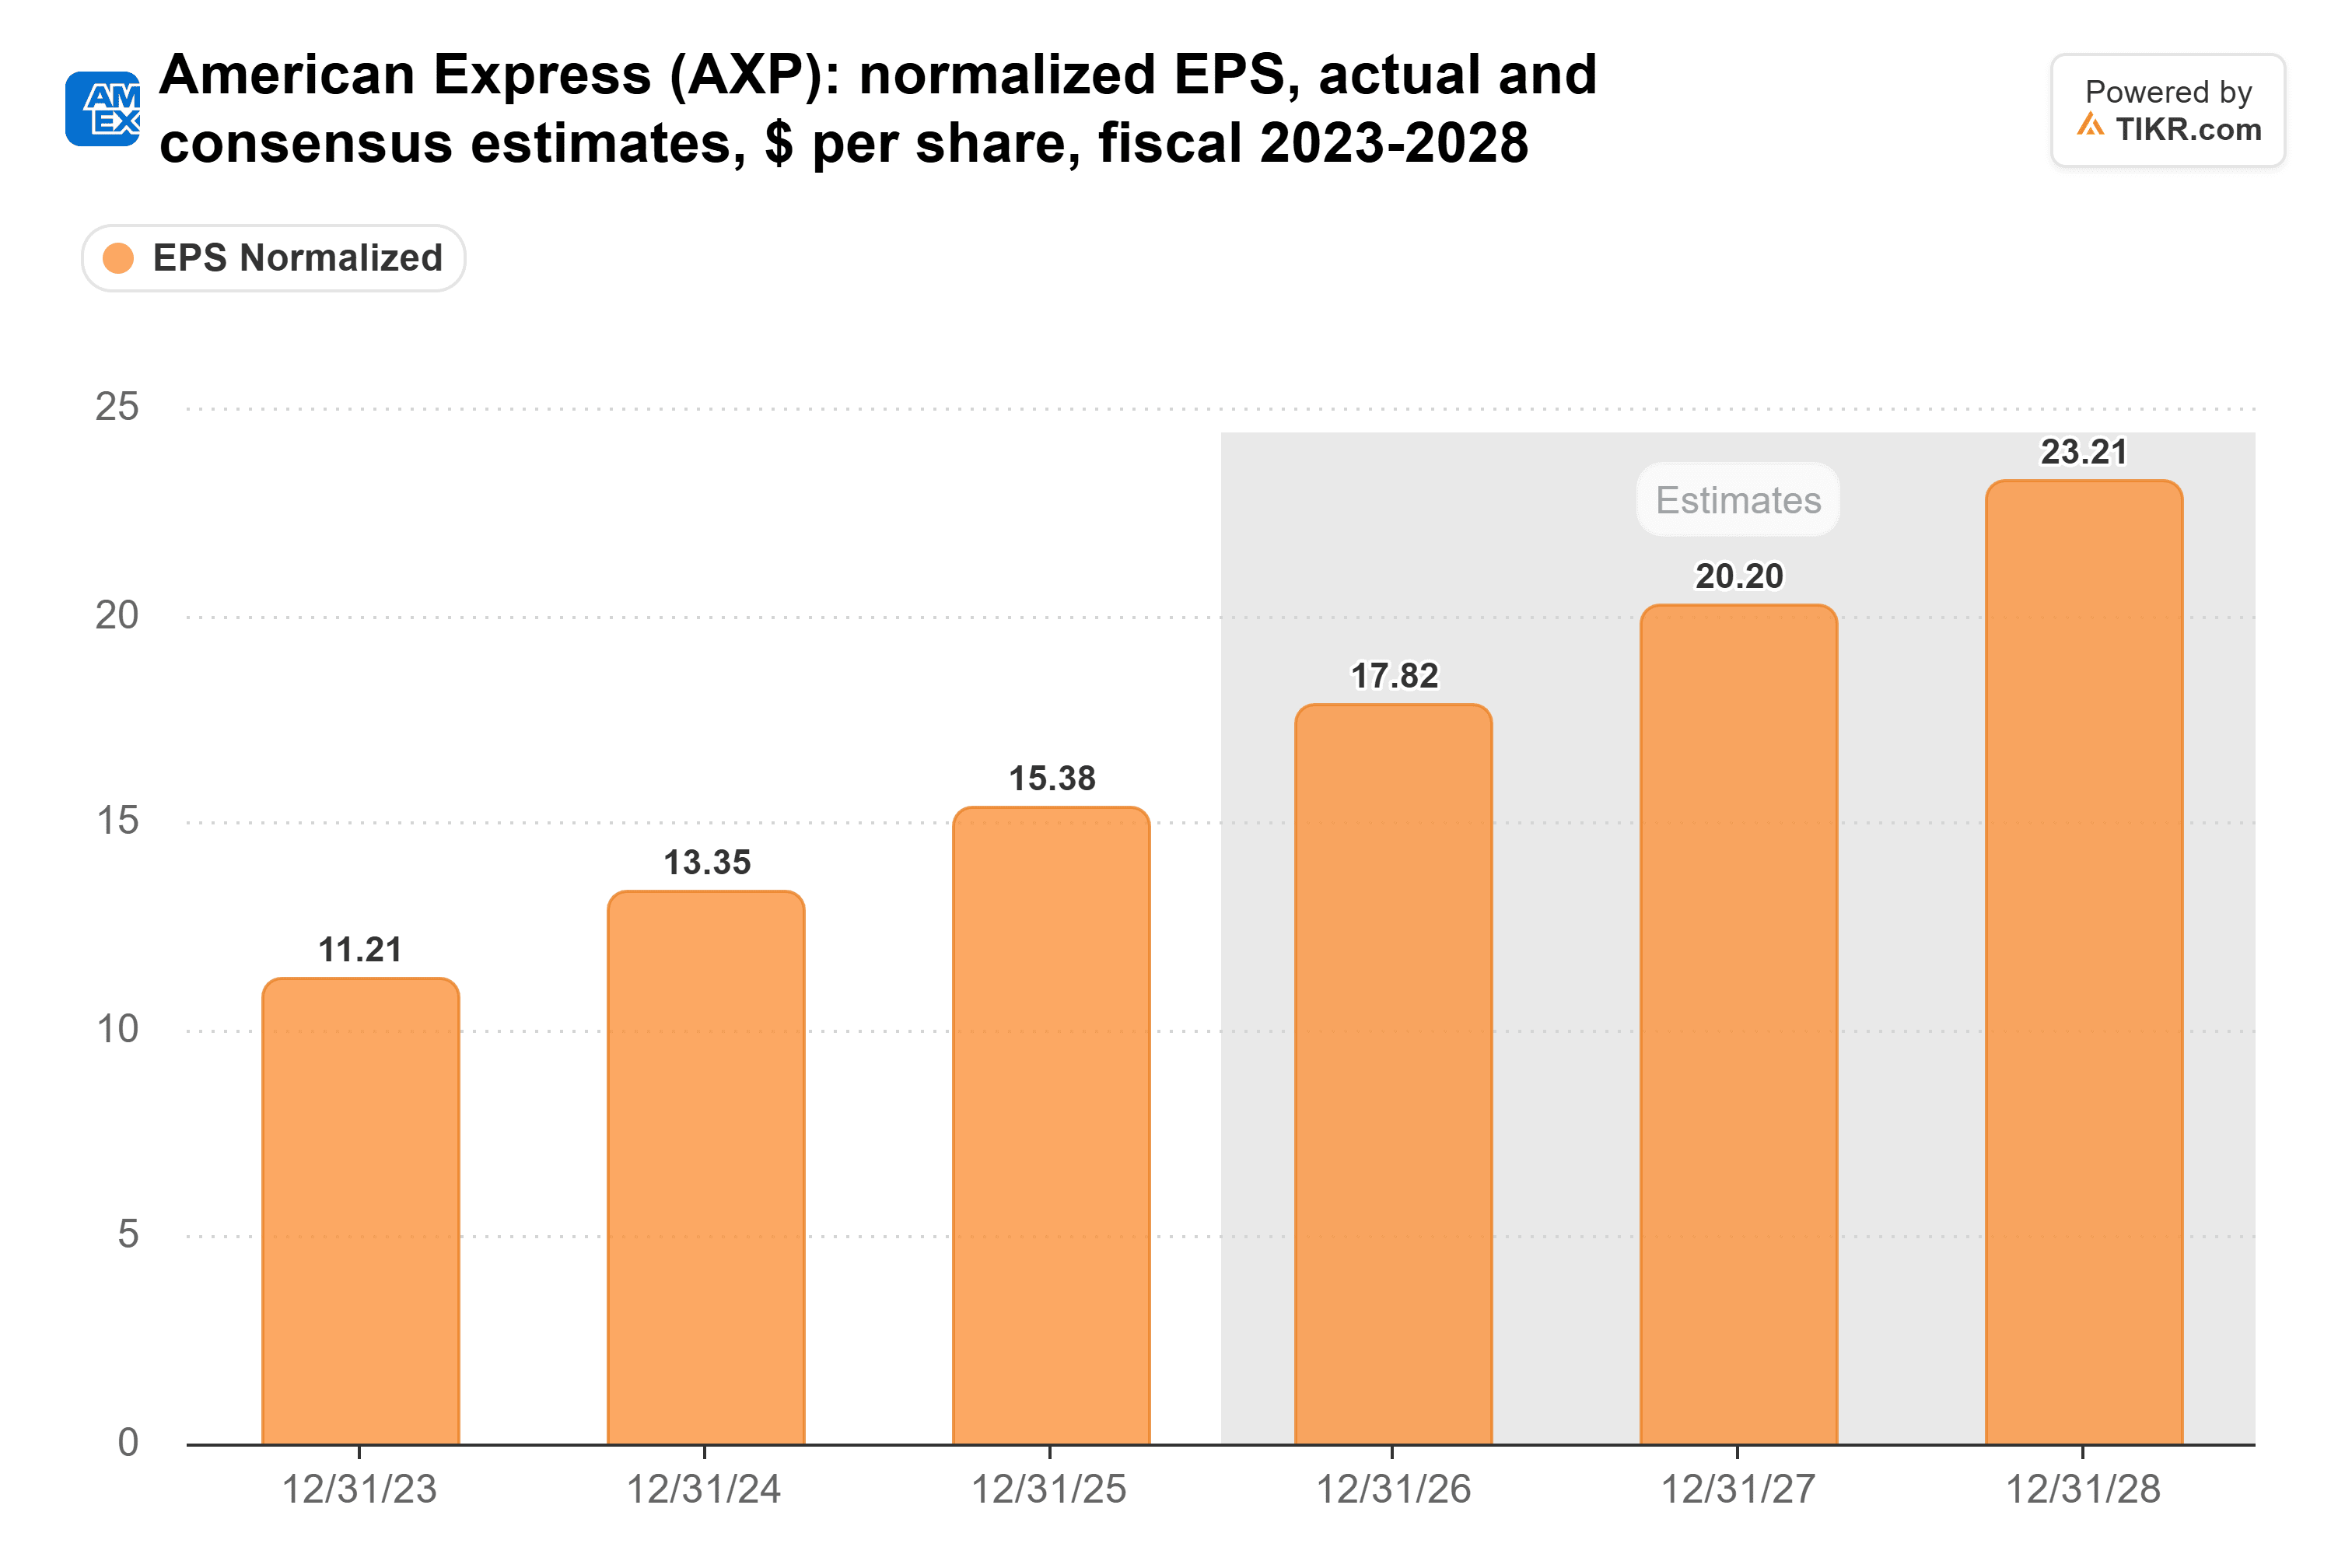
That works out to about 13% growth in fiscal 2027 and 15% in fiscal 2028, in line with the 15% American Express delivered in fiscal 2025.
A 17x multiple is right on average
After the month’s gain, the forward P/E is back at about 17x, right on its 10-year average of 17x:
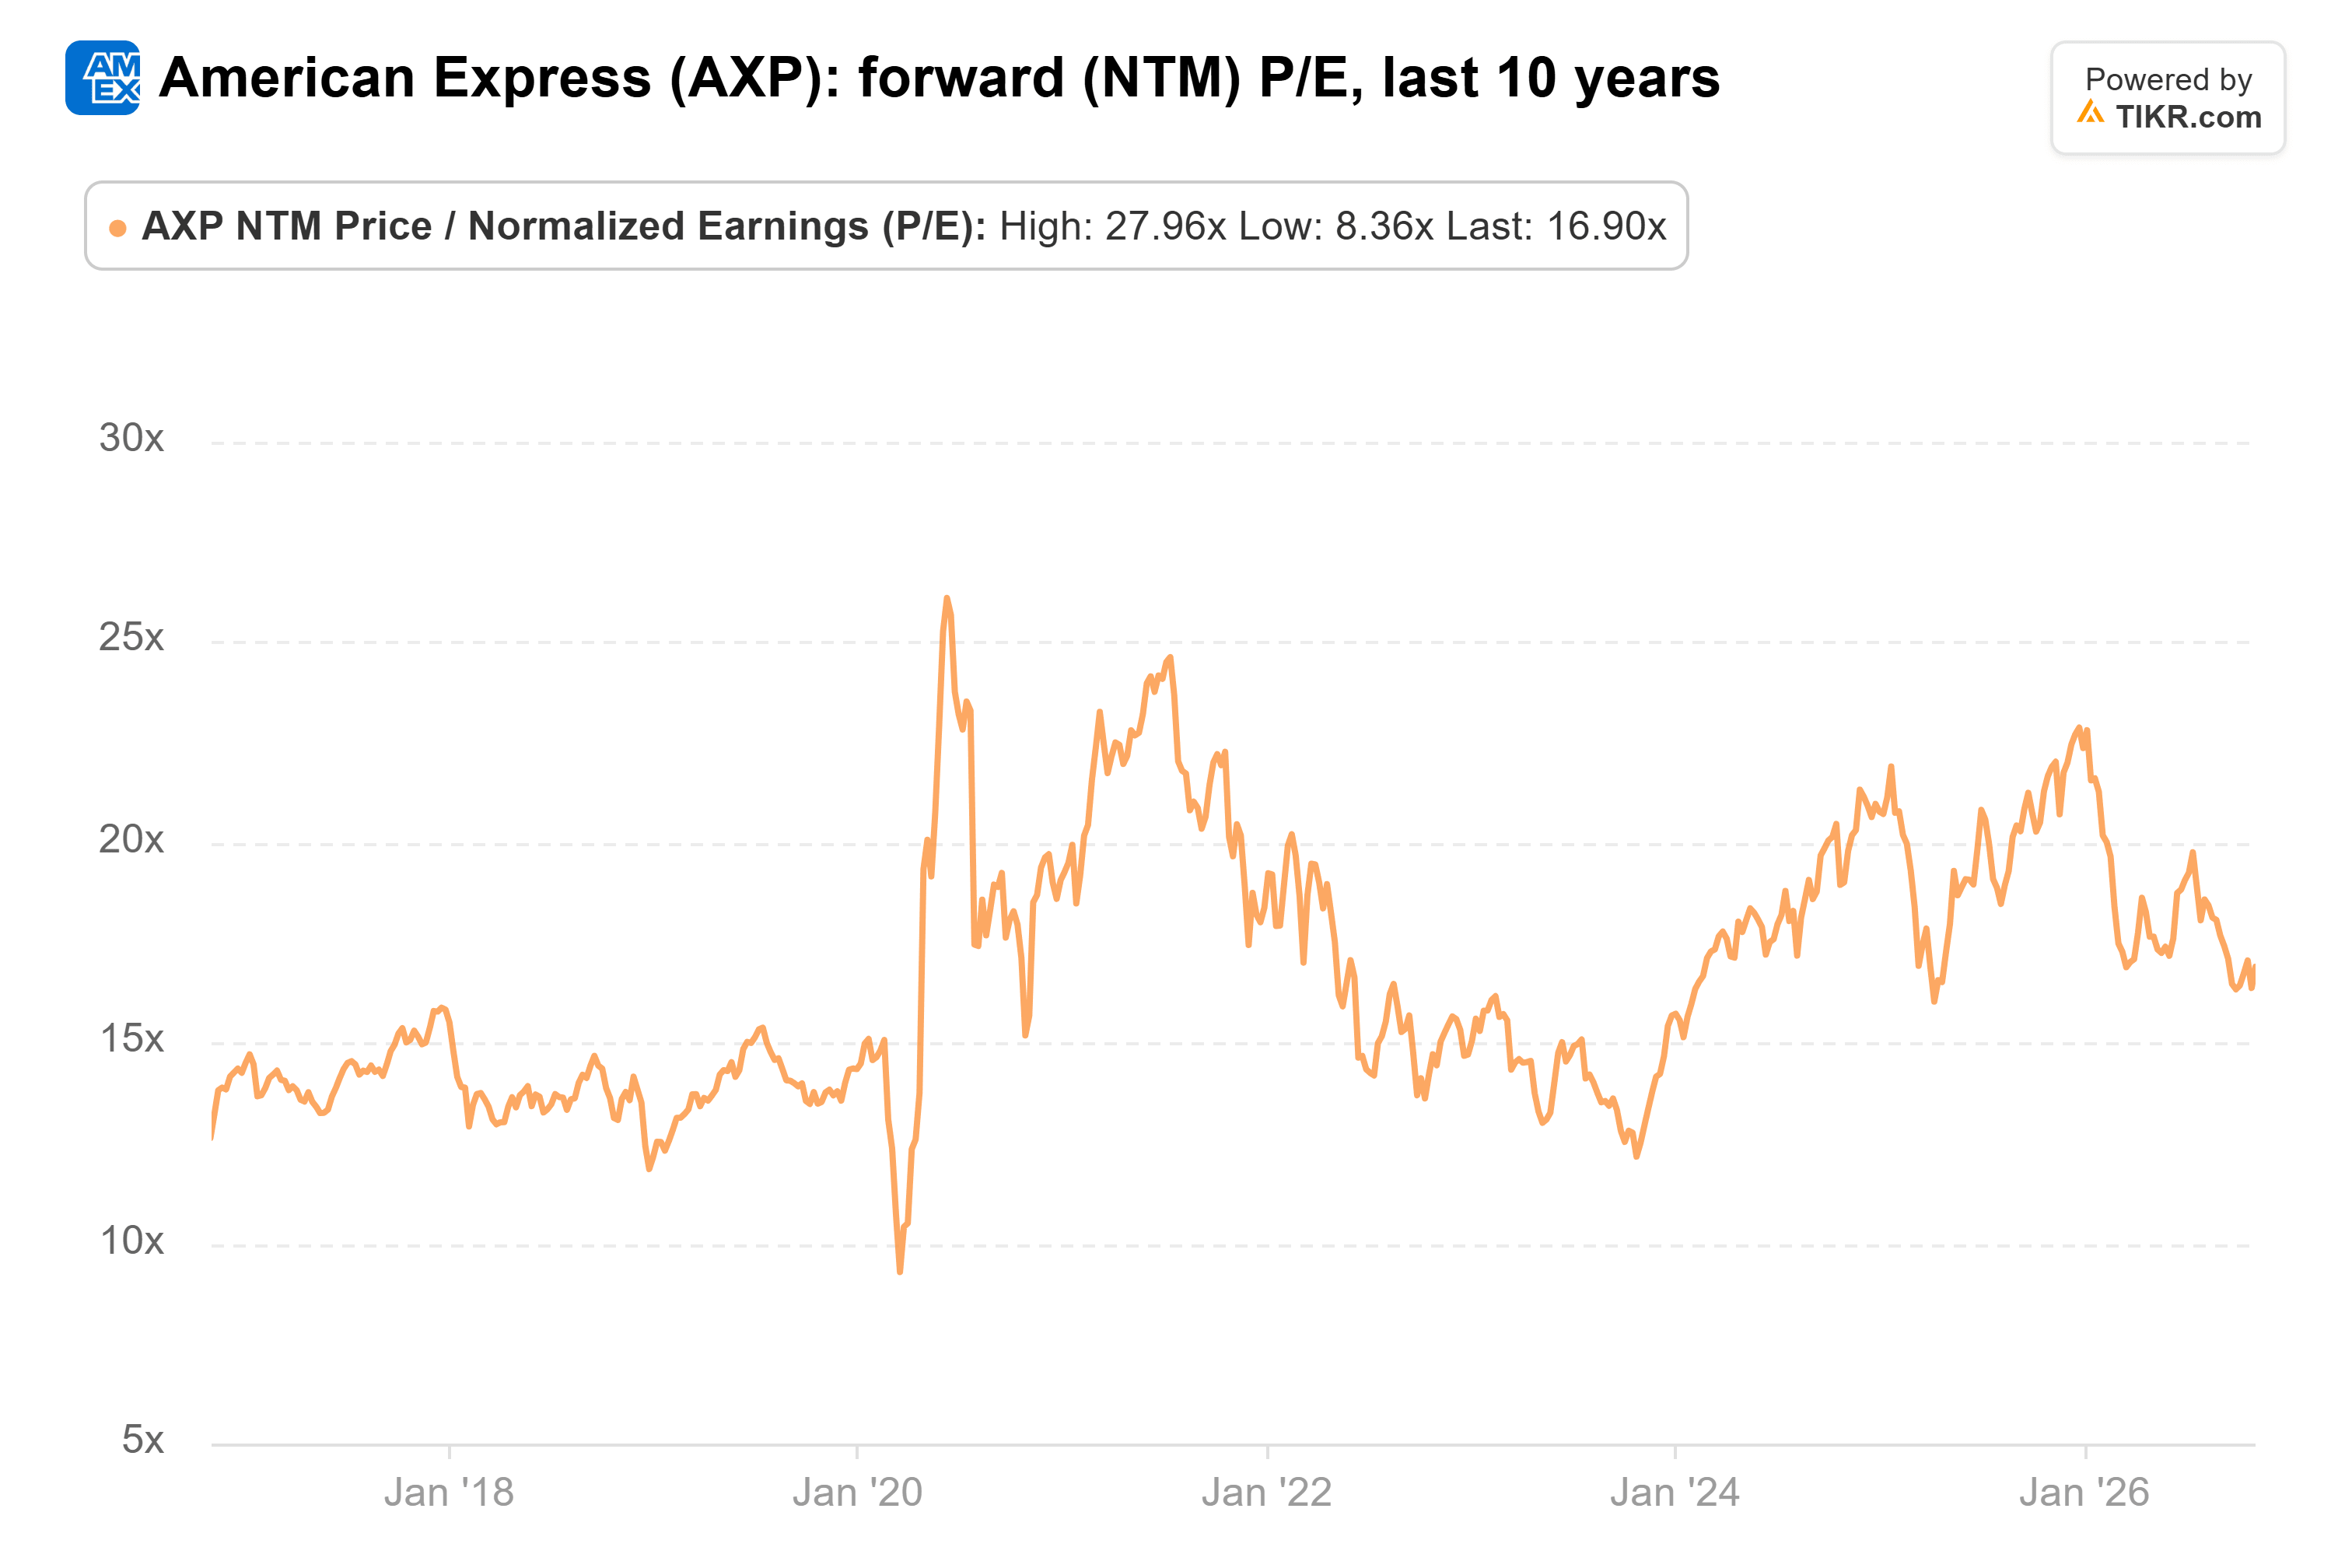
Over that decade, it ranged from 8.4x in March 2020 to 28x in June 2020.
There’s nothing stretched about today’s multiple, but there’s no discount left in it either. Investors who bought the drop have had their rerating. To keep climbing, the stock now needs earnings growth.
What today’s price assumes
At about 17x, the price assumes the consensus is right. That means roughly $20 of normalized EPS over the next twelve months, then growth in the low-to-mid teens after that.
That’s faster growth than the top line. Analysts see revenue rising 9% to 10% a year through fiscal 2028:

So EPS has to grow 4 to 6 points a year faster than revenue. American Express has done that lately.
In fiscal 2024, EPS rose 19% on 9% revenue growth, and in fiscal 2025 it rose 15% on 9%.
The $380 targets don’t need a richer multiple
The stock is still down 12% this year and 14% below its 52-week high. Even so, the higher targets don’t depend on investors paying more for each dollar of earnings.
Say the multiple stays around 17x and the estimates come in. By this time next year, the forward earnings will be mostly fiscal 2028’s, and that multiple works out to a price in the mid-$380s. That’s right around Morgan Stanley’s and BMO’s $380, and roughly back to the 52-week high.
At an average multiple, a slowdown in card spending or a turn in credit would cut straight into those estimates, and the price would fall with them.
The way I see it, American Express is fairly priced again. From here, I’d expect the stock to roughly track its earnings. Growth of 13% to 15% a year is a solid return, but buyers today are paying for that growth up front.
Next up is the Q4 report, due in late January, which should bring management’s first guidance for 2027.
If that lands near the $20.20 consensus, the $380 targets look reasonable. If it comes in light, a stock at its average multiple has little to fall back on.
So what is American Express stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what American Express could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value American Express for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!