Key Takeaways
- Citi cut Adobe (ADBE) to Sell with a $207 target on Wednesday and warned of a rising risk of a “hard reset,” with the stock already down 25% this year.
- At 9.4x forward earnings, against a 10-year average of 30x, Adobe’s price already assumes much slower growth than analysts forecast.
- Citi’s target needs one of two things: Adobe’s lowest multiple in a decade, or earnings estimates about 17% lower, which would put fiscal 2027 below fiscal 2026.
- Adobe’s fiscal 2027 guidance comes with its December report, under a new CEO, and will show whether the estimates really have to fall that far.
Adobe is down 25% this year, and analysts are still cutting the stock price target.
On Wednesday, Citi cut the stock to Sell from Neutral and lowered its price target to $207 from $250. It’s the third downgrade in about three weeks. Wells Fargo moved to Sell and HSBC to Hold in mid-October, and the latest targets now run from $200 to $267.
At 9.4x forward earnings, though, Adobe’s price already reflects plenty of bad news. Citi is betting the estimates still have further to fall.
TIKR tracks 41 analysts on Adobe. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Adobe, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Adobe’s Analyst Ratings
Citi thinks fiscal 2027 estimates are too high
Citi’s analysts wrote that they “see rising risk of a hard reset.” They gave four reasons:
- Leadership: Anil Chakravarthy takes over as CEO on Dec. 1, and the CFO and head of Digital Media jobs are both open.
- Strategy: Adobe is chasing user growth through AI products like Firefly instead of Creative Cloud price increases. Citi thinks that takes about 200 basis points off fiscal 2027 ARR growth, plus another 50 as Adobe laps its earlier price increases.
- Demand: weak small-business demand, and more competition from web-based and AI-native creative tools.
- Margins: Citi cut its fiscal 2027 non-GAAP gross margin estimate by 70 basis points, partly because of AI inference costs Adobe hasn’t fully monetized.
Put together, Citi expects ARR growth of about 5.3% in fiscal 2027 and 4.5% in fiscal 2028. That’s roughly 200 to 300 basis points below Wall Street’s forecasts, and Citi expects the weaker outlook to show up when Adobe reports its Q4 next month.
Even Citi sees a silver lining: “A ‘hard reset’ would pressure shares near term but provide time to rebuild leadership, refine strategy, and establish a more achievable base to accelerate.”
Wall Street still expects double-digit growth
The consensus hasn’t moved that far. Analysts expect normalized EPS to rise from $20.94 in fiscal 2025 to $31.20 by fiscal 2028:
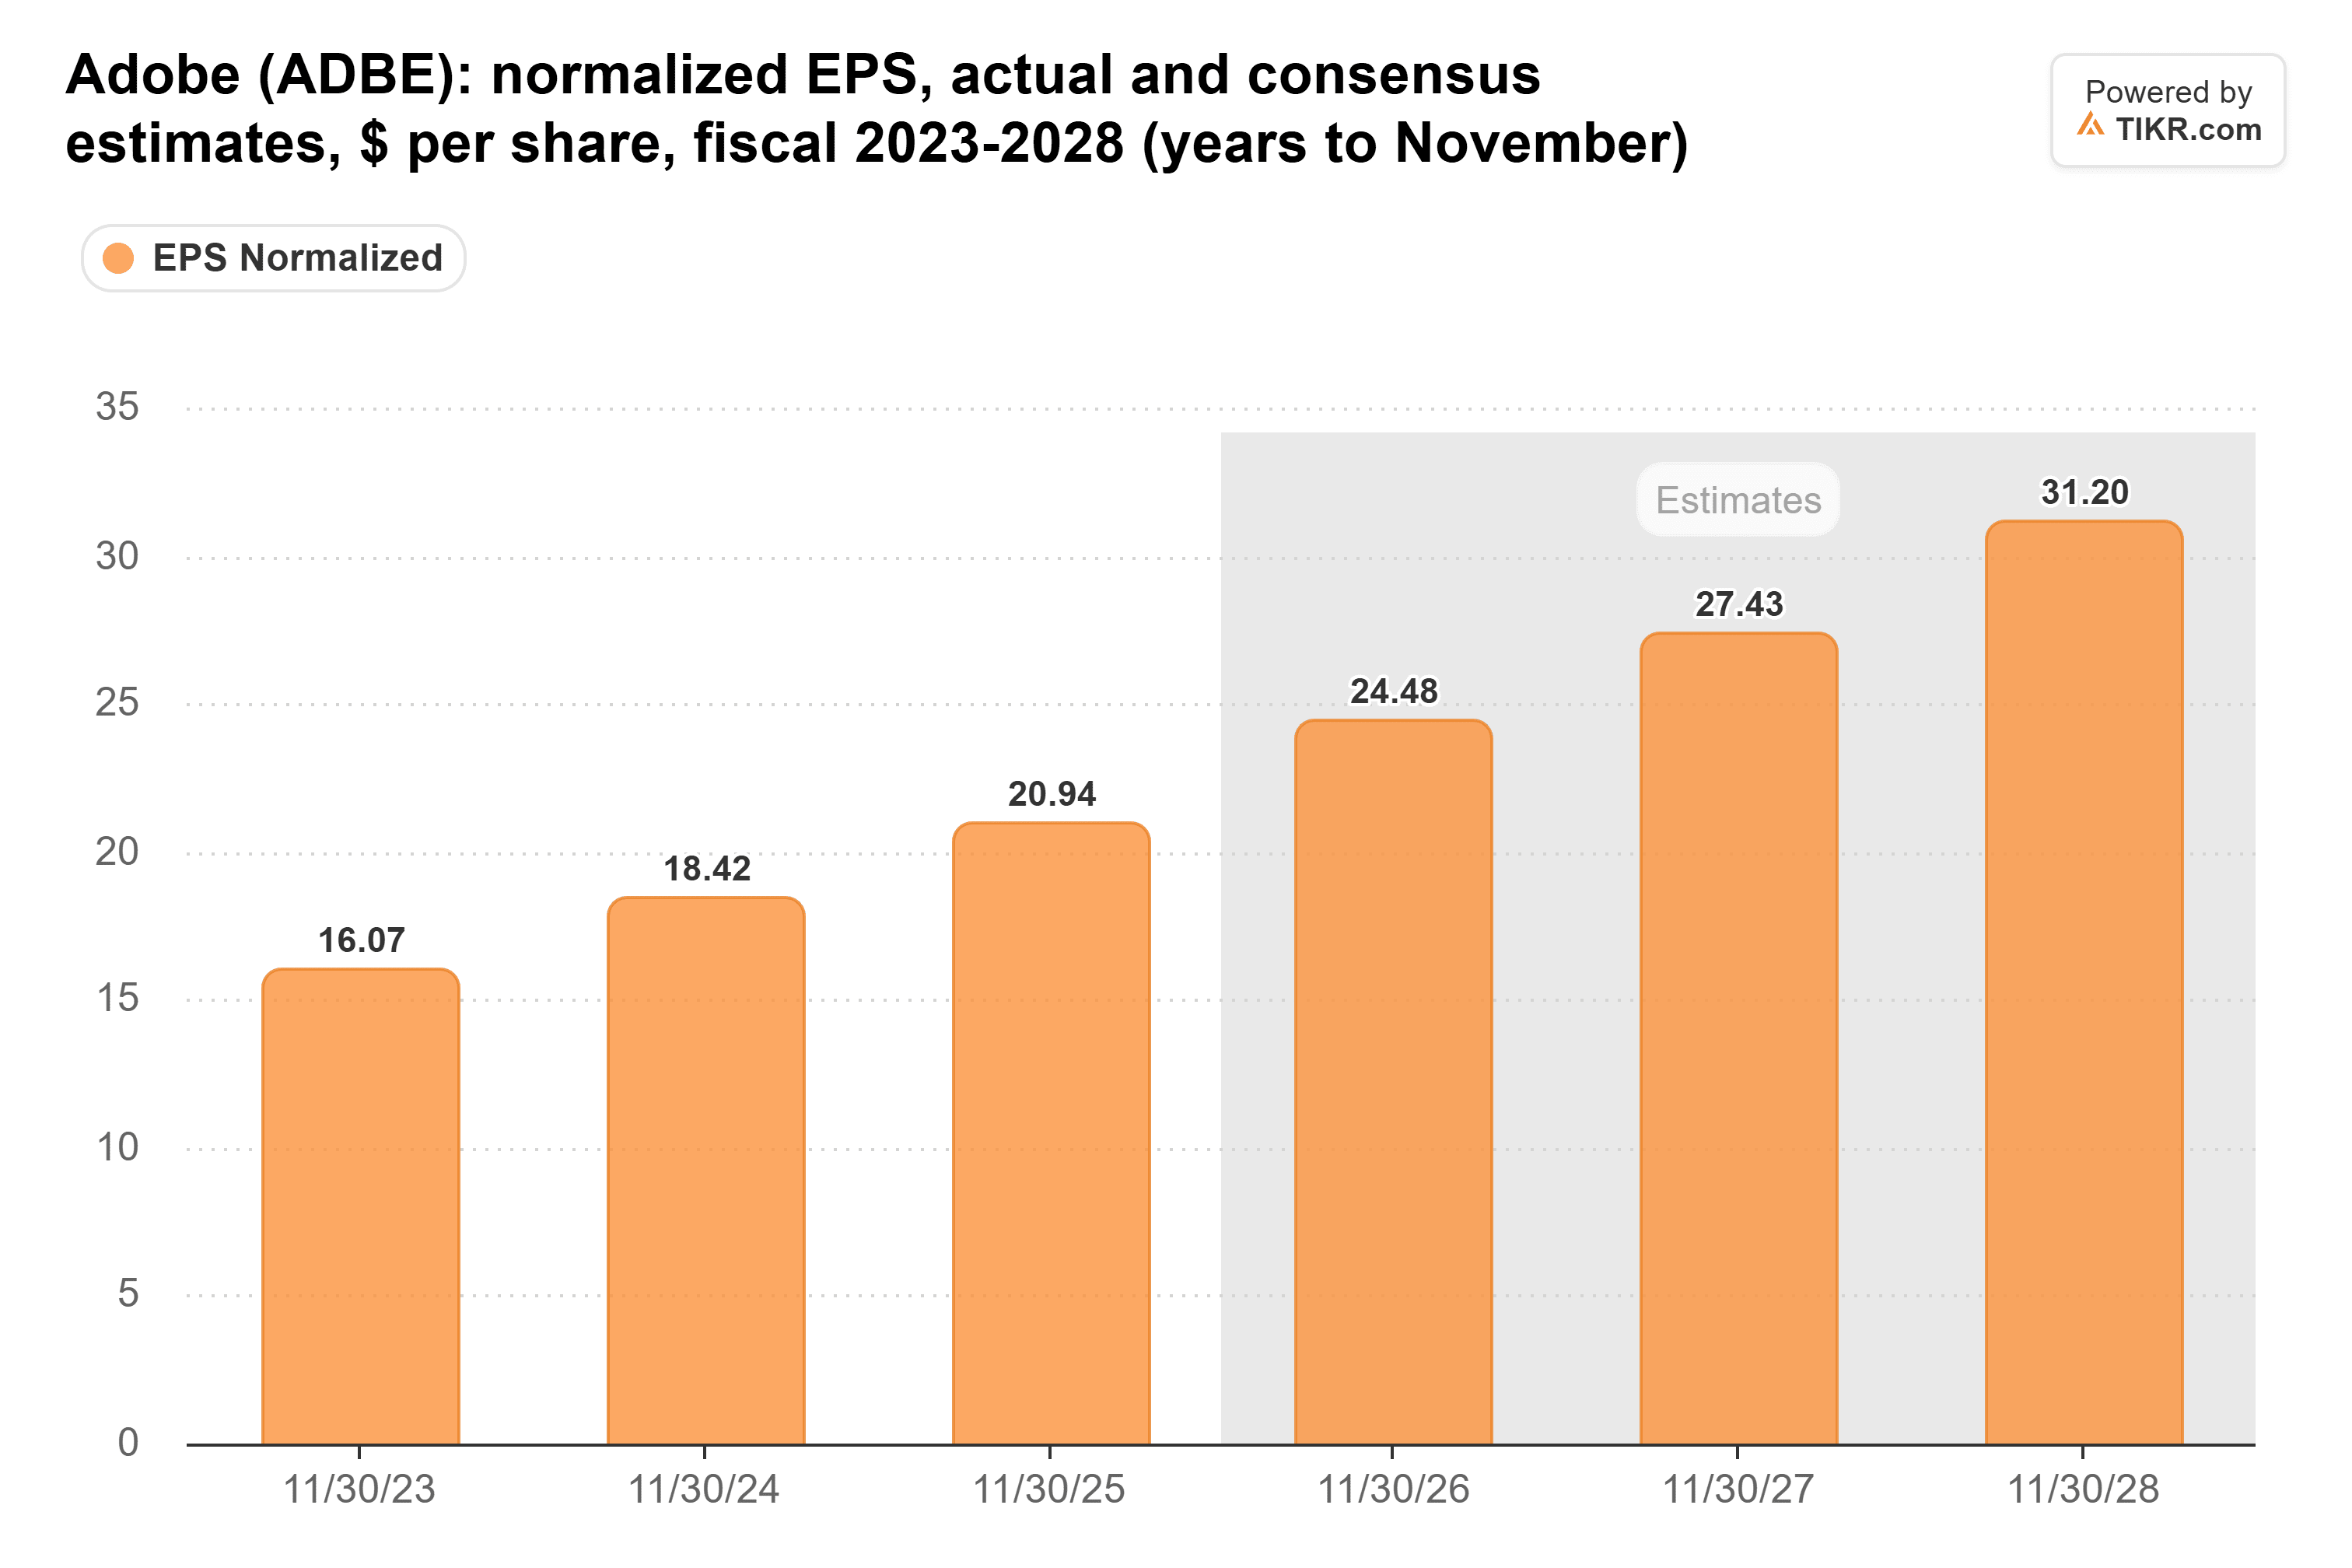
That’s about 12% growth in fiscal 2027 and 14% in fiscal 2028, on the estimates of 38 and 22 analysts.
Adobe trades like a company that’s done growing
The market isn’t paying for that growth. Adobe’s forward P/E is a fraction of what it has usually been over the past decade:
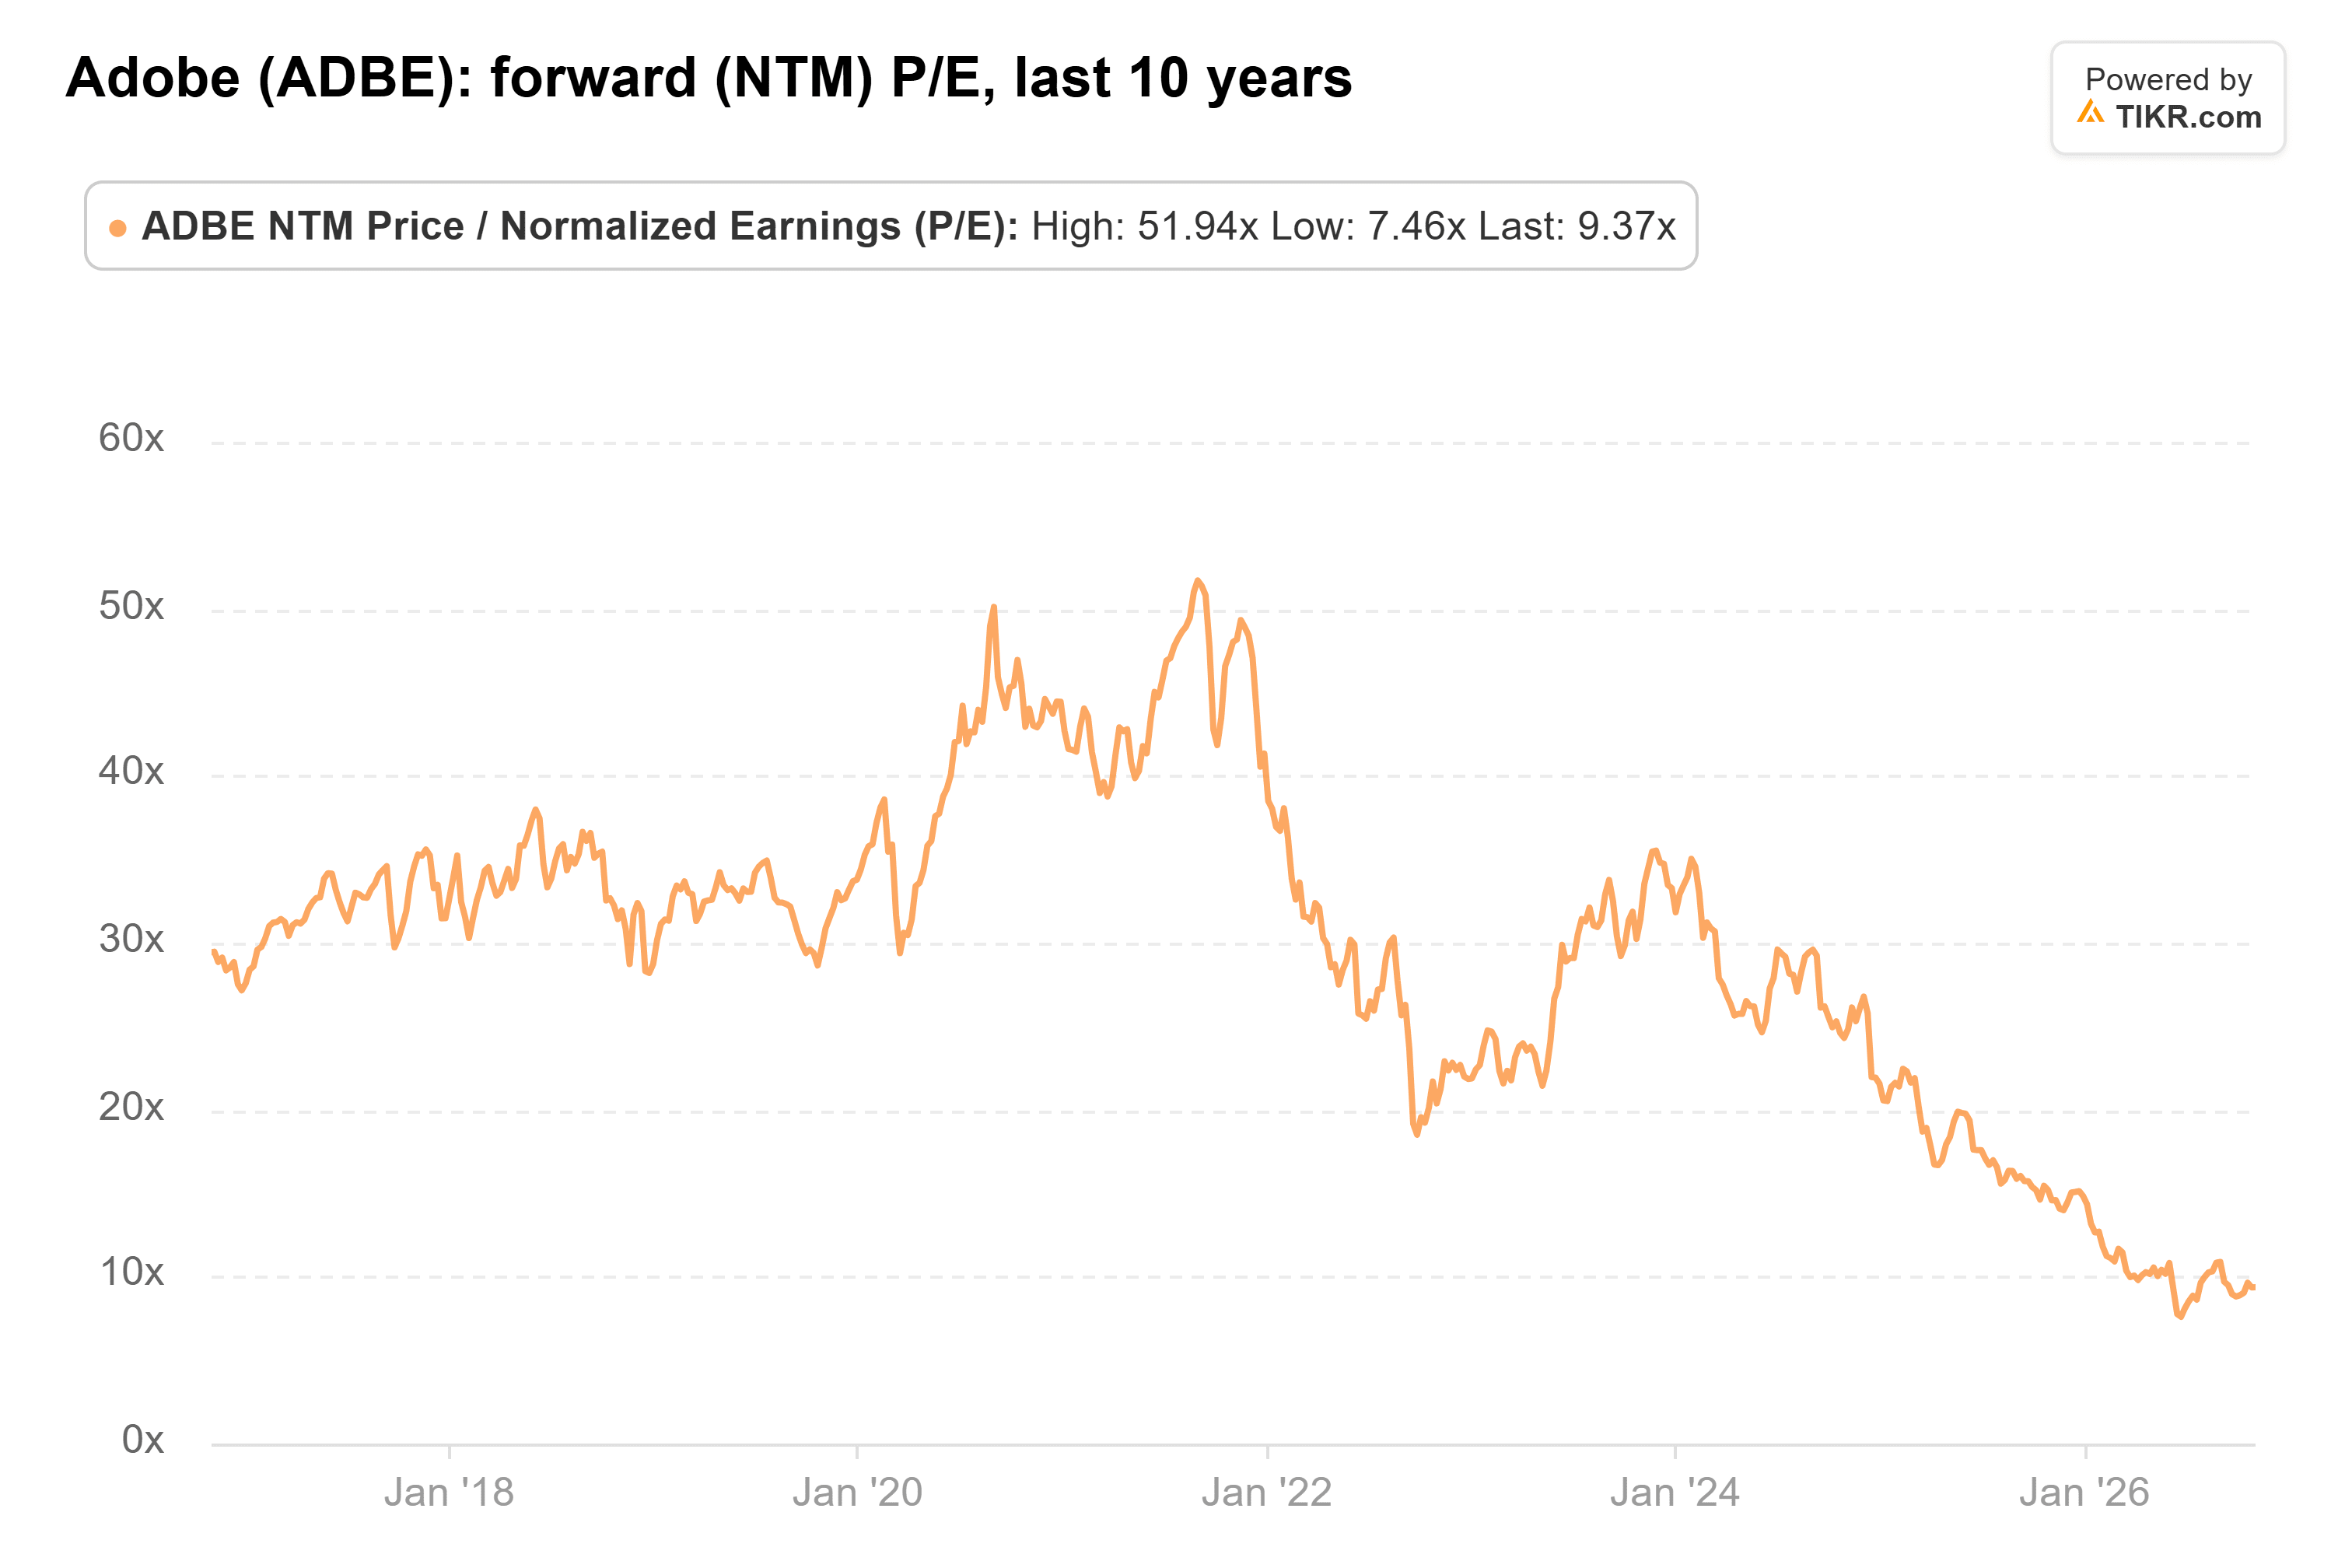
Its 10-year average is 30x, and it reached 52x in September 2020. The only time it’s been cheaper than that current multiple was this June, when it hit 7.5x.
At its 30x average, Adobe’s last close of $248.48 would only make sense with EPS of $8.37. That’s less than a third of the $27.43 analysts expect for fiscal 2027.
Even if Adobe hits consensus through fiscal 2028, today’s price is just 8.0x that year’s EPS.
That’s a grim forecast.
Citi’s $207 target is 17% below the last close. If the multiple stays where it is, the target needs earnings estimates about 17% lower.
That would put fiscal 2027 EPS near $22.85, below the $24.48 analysts expect for the fiscal year ending this month.
If the estimates hold instead, $207 works out to 7.5x fiscal 2027 EPS, the same as June’s 10-year low.
Free cash flow keeps climbing
Adobe’s free cash flow has grown nearly fivefold over the past decade, with one dip in fiscal 2023:

Fiscal 2025’s $9.85 billion was up 25% from the year before. It also equals about a tenth of Adobe’s $97.9 billion market value.
A lower multiple may be the new normal
I wouldn’t count on 30x again. Adobe earned that average in a decade when nobody questioned its pricing power.
Citi now describes a company giving up price increases to win users while it pays for AI inference. If AI tools are wearing down Adobe’s pricing power, the old average makes the stock look cheaper than it is.
Still, the stock doesn’t need to get anywhere near 30x to be cheap at 9.4x.
The bar is already low
The way I see it, Adobe’s price already reflects much of the hard reset Citi is warning about. Citi may be right that the fiscal 2027 guidance disappoints. But its $207 target needs the estimates to fall below this year’s earnings.
My read: a few points of slower ARR growth and a 70-basis-point gross margin cut don’t add up to a 17% cut in earnings, especially with free cash flow still rising.
Of course, a new CEO without a CFO has every reason to set a low bar in December. If the guidance is soft enough, the stock could get cheaper still.
So what is Adobe stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Adobe could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!