Key Takeaways
- Heard Capital, a $2.4 billion fund, opened new positions in Bloom Energy (BE), Marvell Technology (MRVL), and added 25% to its AeroVironment (AVAV) stake in the quarter ended June 30, according to its latest 13F.
- All three stocks have fallen 31% to 46% since June 30.
- Analysts’ average targets sit 43% to 113% above each stock’s last close, but AeroVironment’s target has nearly halved over the past year while Bloom’s and Marvell’s more than tripled.
- Bloom Energy looks like the best buy of the three, with its earnings estimates rising and its forward P/E well below its own average.
Heard Capital holds $2.34 billion of US stocks in just 21 positions, so a stake worth more than 5% of the fund is a real bet.
Its 13F for the quarter ended June 30, filed Aug. 11 and still its latest filing, shows three new or bigger ones: Bloom Energy, Marvell Technology and AeroVironment.
All three have fallen hard since June 30. (Those are price changes from the quarter’s end: a 13F doesn’t show what Heard paid.)
Bloom’s estimates are climbing as its stock falls
Bloom Energy was Heard’s biggest new position: 448,808 shares worth $136 million at June 30, or 5.8% of the fund.
The stock is down 35% since then, even after Bloom raised its 2026 revenue guidance for the third time on Oct. 22, to $4.4 billion to $4.6 billion, on Q3 revenue up 138%.
Analysts’ average target has more than tripled over the past year, to $287.

The stock fell after that report as free cash flow turned negative at $180.6 million in Q3, as contract assets climbed to $858.6 million on Sept. 30 from $241.2 million at the end of 2025.
TIKR tracks 32 analysts on Bloom Energy. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Bloom Energy, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Bloom Energy’s Analyst Ratings
Marvell’s outlook keeps going up
Heard also opened a stake in Marvell: 447,977 shares worth $133 million, or 5.7% of the fund.
Marvell is down 46% since June 30, even though management has raised its revenue outlook for fiscal 2028 (the year ending in January 2028) three times since March, to about $20 billion.
Chief Operating Officer Chris Koopmans says Marvell has the demand and the supply to get there.
Analysts’ average target has nearly quadrupled over the past year, to about $340:
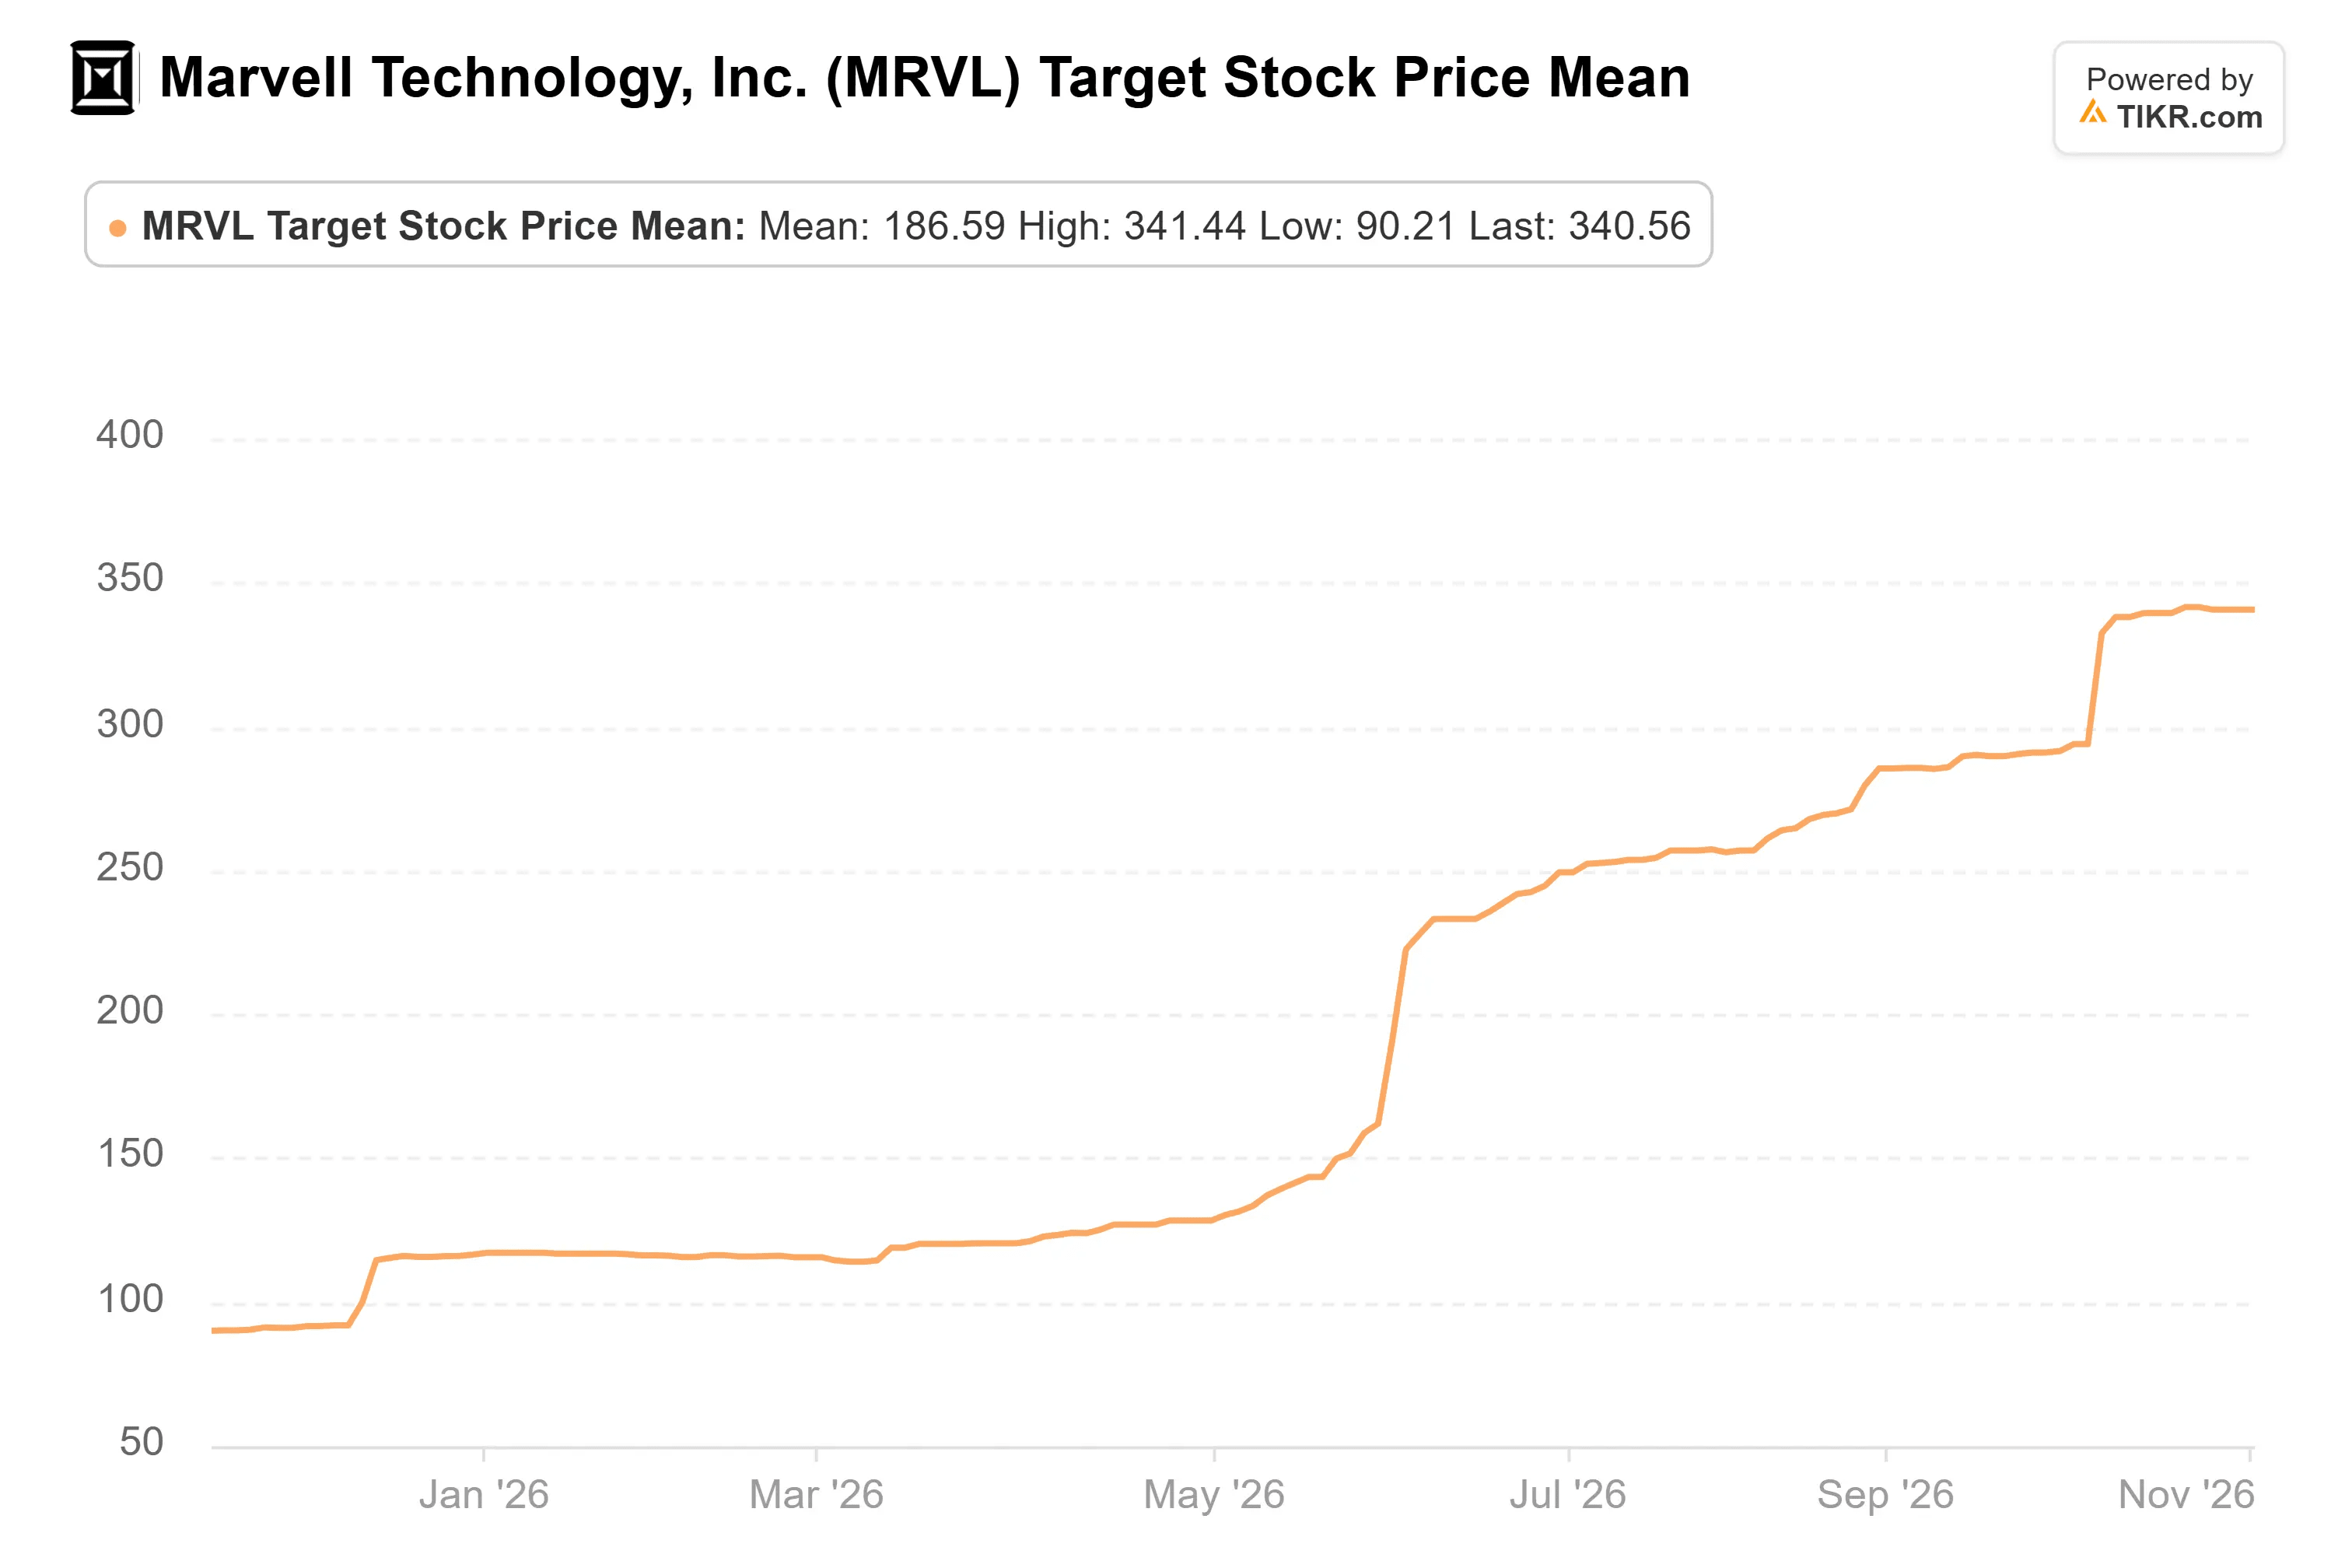
The latest impact came when Bloomberg reported on Oct. 28 that Marvell was in advanced talks to buy Lumentum, and the stock sank 12%.
Lumentum is worth about a third as much as Marvell, so a deal would likely mean a lot of new shares.
Marvell’s diluted share count already climbed from 856.2 million to 921.2 million in the two quarters to Aug. 1.
AeroVironment’s targets keep coming down
AeroVironment was the one stock of the three that Heard already owned.
It raised the stake 25% in the quarter, to 903,975 shares worth $149 million, its seventh-biggest holding at 6.4% of the fund. The stock is down 31% since June 30 and sits 72% below its 52-week high.
Analysts have cut their average target nearly in half over the past year, to $212:

The latest quarter was a good one.
On Sept. 9, AeroVironment reported record Q1 revenue of $480.5 million, up 6%, and a record $1.5 billion funded backlog.
It stood by its outlook for fiscal 2027, the year ending next April: revenue of $2.125 billion to $2.225 billion, about 10% growth at the midpoint, and adjusted EPS of $3.02 to $3.34.
CEO Wahid Nawabi named the timing of Congress’s fiscal 2027 defense budget as the main uncertainty.
Bloom has the numbers on its side
Bloom trades at about 40x forward earnings, well below the 75.5x it averaged at quarter-ends since September 2023. Since June 30, analysts have raised their 2026 EPS estimate 52%, to $3.25.
Marvell, at about 30x, sits a little below its five-year average of 32.6x, and analysts have raised their fiscal 2028 EPS estimate 19% since June 30.
AeroVironment trades at about 37x forward earnings while guiding to roughly 10% revenue growth, and its average target hit its low for the year on Oct. 22.
Bloom’s risk is concentration: two customers took 69% of its third-quarter revenue, and much of the money for those deliveries still sits in contract assets.
If I could buy only one of these three today, it’d be Bloom. Its estimates keep rising, and its multiple has come down to the lower part of its range since 2023.
Marvell’s case holds up too, but at about its usual multiple, with a possible stock-funded deal hanging over it. And I’d want AeroVironment’s targets to stop falling before paying 30x for it.
Bloom’s Q4 report, due early next year, will show whether those contract assets turn into cash. Marvell and AeroVironment both report in early December.
And Heard’s 13F for the September quarter, due by Nov. 16, will show whether it still held all three on Sept. 30.
So what is Bloom Energy stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Bloom Energy could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!