Key Takeaways
- Nike (NKE) stock is up 19% in the past month. On Wednesday, Morgan Stanley kept its Sell rating and trimmed its price target to $25.
- After the rally, Nike’s forward P/E is back near its 10-year average of 31x, so buyers are paying a normal multiple for earnings close to their low.
- Analysts expect EPS of $1.28 this fiscal year and $1.56 in fiscal 2028. That’s about where fiscal 2026 ended, and less than half of fiscal 2024.
- To reach Morgan Stanley’s target, Nike would need its lowest multiple in a decade or earnings below its own guidance. The Nov. 16-17 Investor Day is the next test.
Nike stock is up 19% in the past month, and not everyone on Wall Street is following it up.
On Wednesday, Morgan Stanley kept its Sell rating and trimmed its price target to $25, from $27. Stifel kept its Hold rating and $36 target the same day. Both are below where Nike trades now.
So anyone buying after the rally needs to know how much of Nike’s recovery they’re already paying for.
Analysts see a slow climb back
When Nike reported on Oct. 1, it guided for fiscal 2027 adjusted EPS of $1.15 to $1.35 (the year ends in May). That range excludes about $0.15 a share of restructuring charges.
Analysts sit in the middle of the range, then pencil in a modest rebound for fiscal 2028:
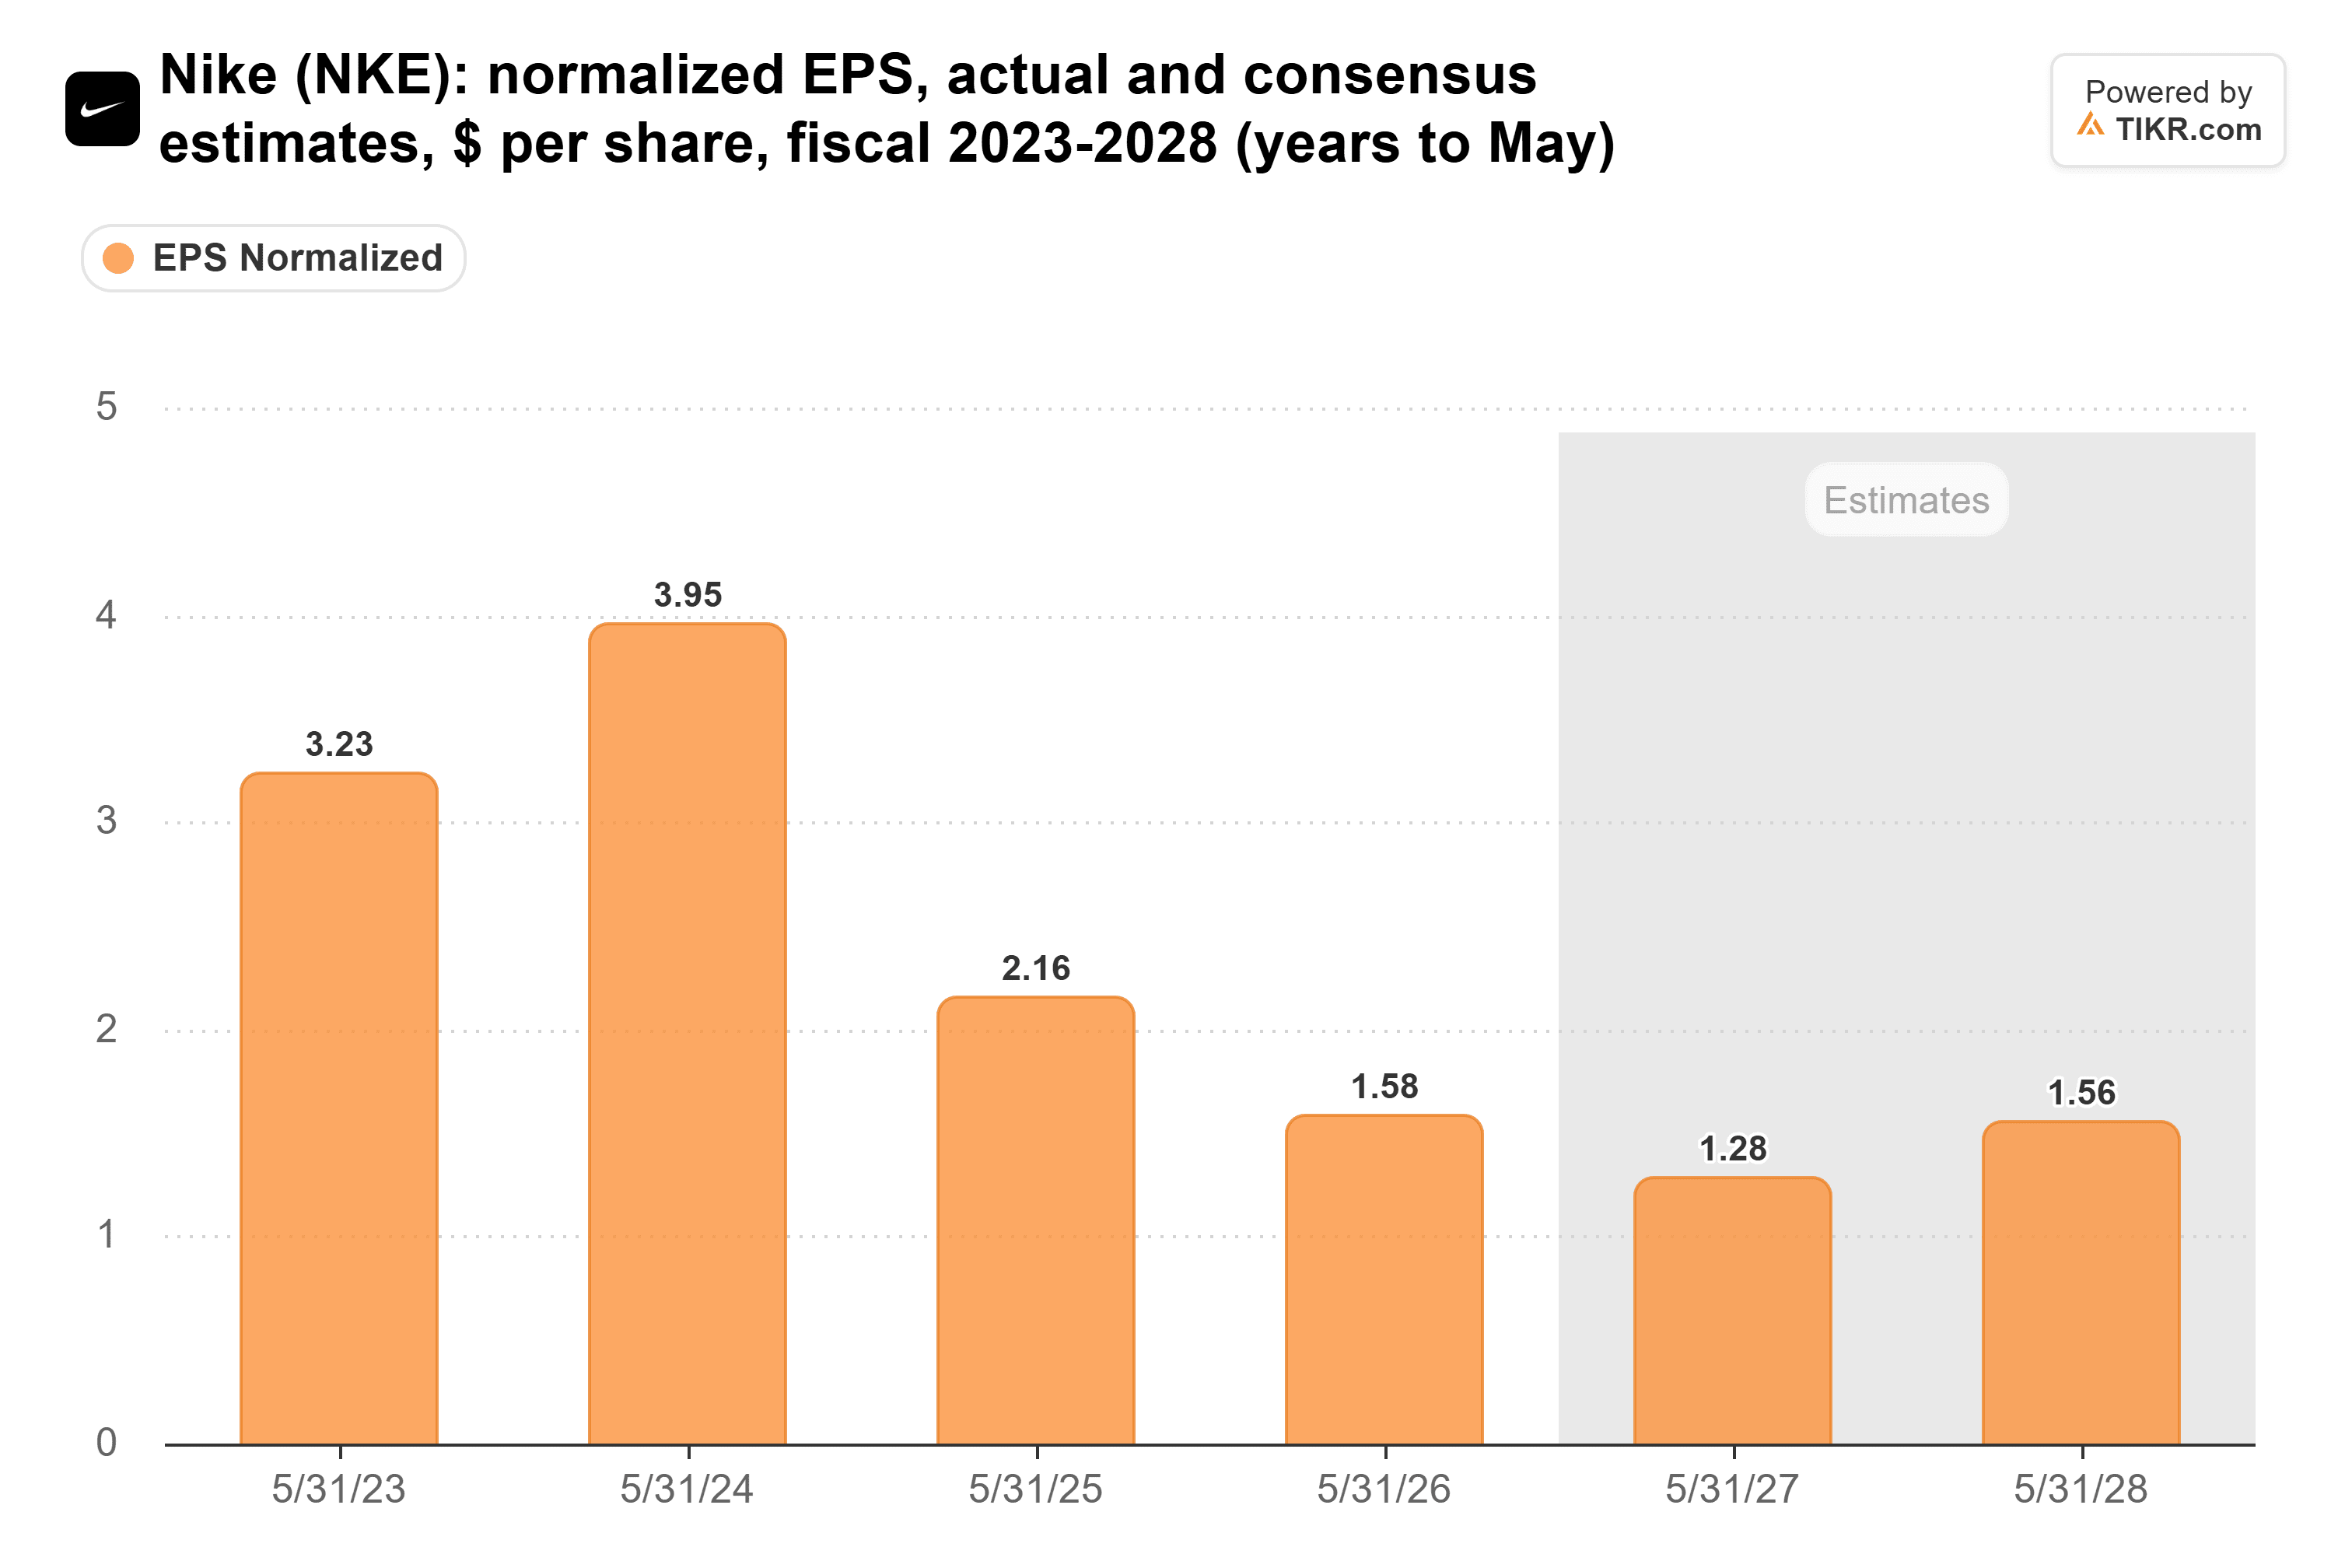
So two years out, analysts expect Nike to earn about what it did in fiscal 2026, and less than half of fiscal 2024’s $3.95.
This year’s consensus is still falling, too: it dropped 25% in the 90 days to Oct. 22. Barclays called the shares “near bottom” last month, but it also warned that fiscal 2028 estimates “may need an expected sales haircut.”
TIKR tracks 44 analysts on Nike. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Nike, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Nike’s Analyst Ratings
Back to an average multiple
The rally has pushed Nike’s forward P/E right back to its 10-year average:
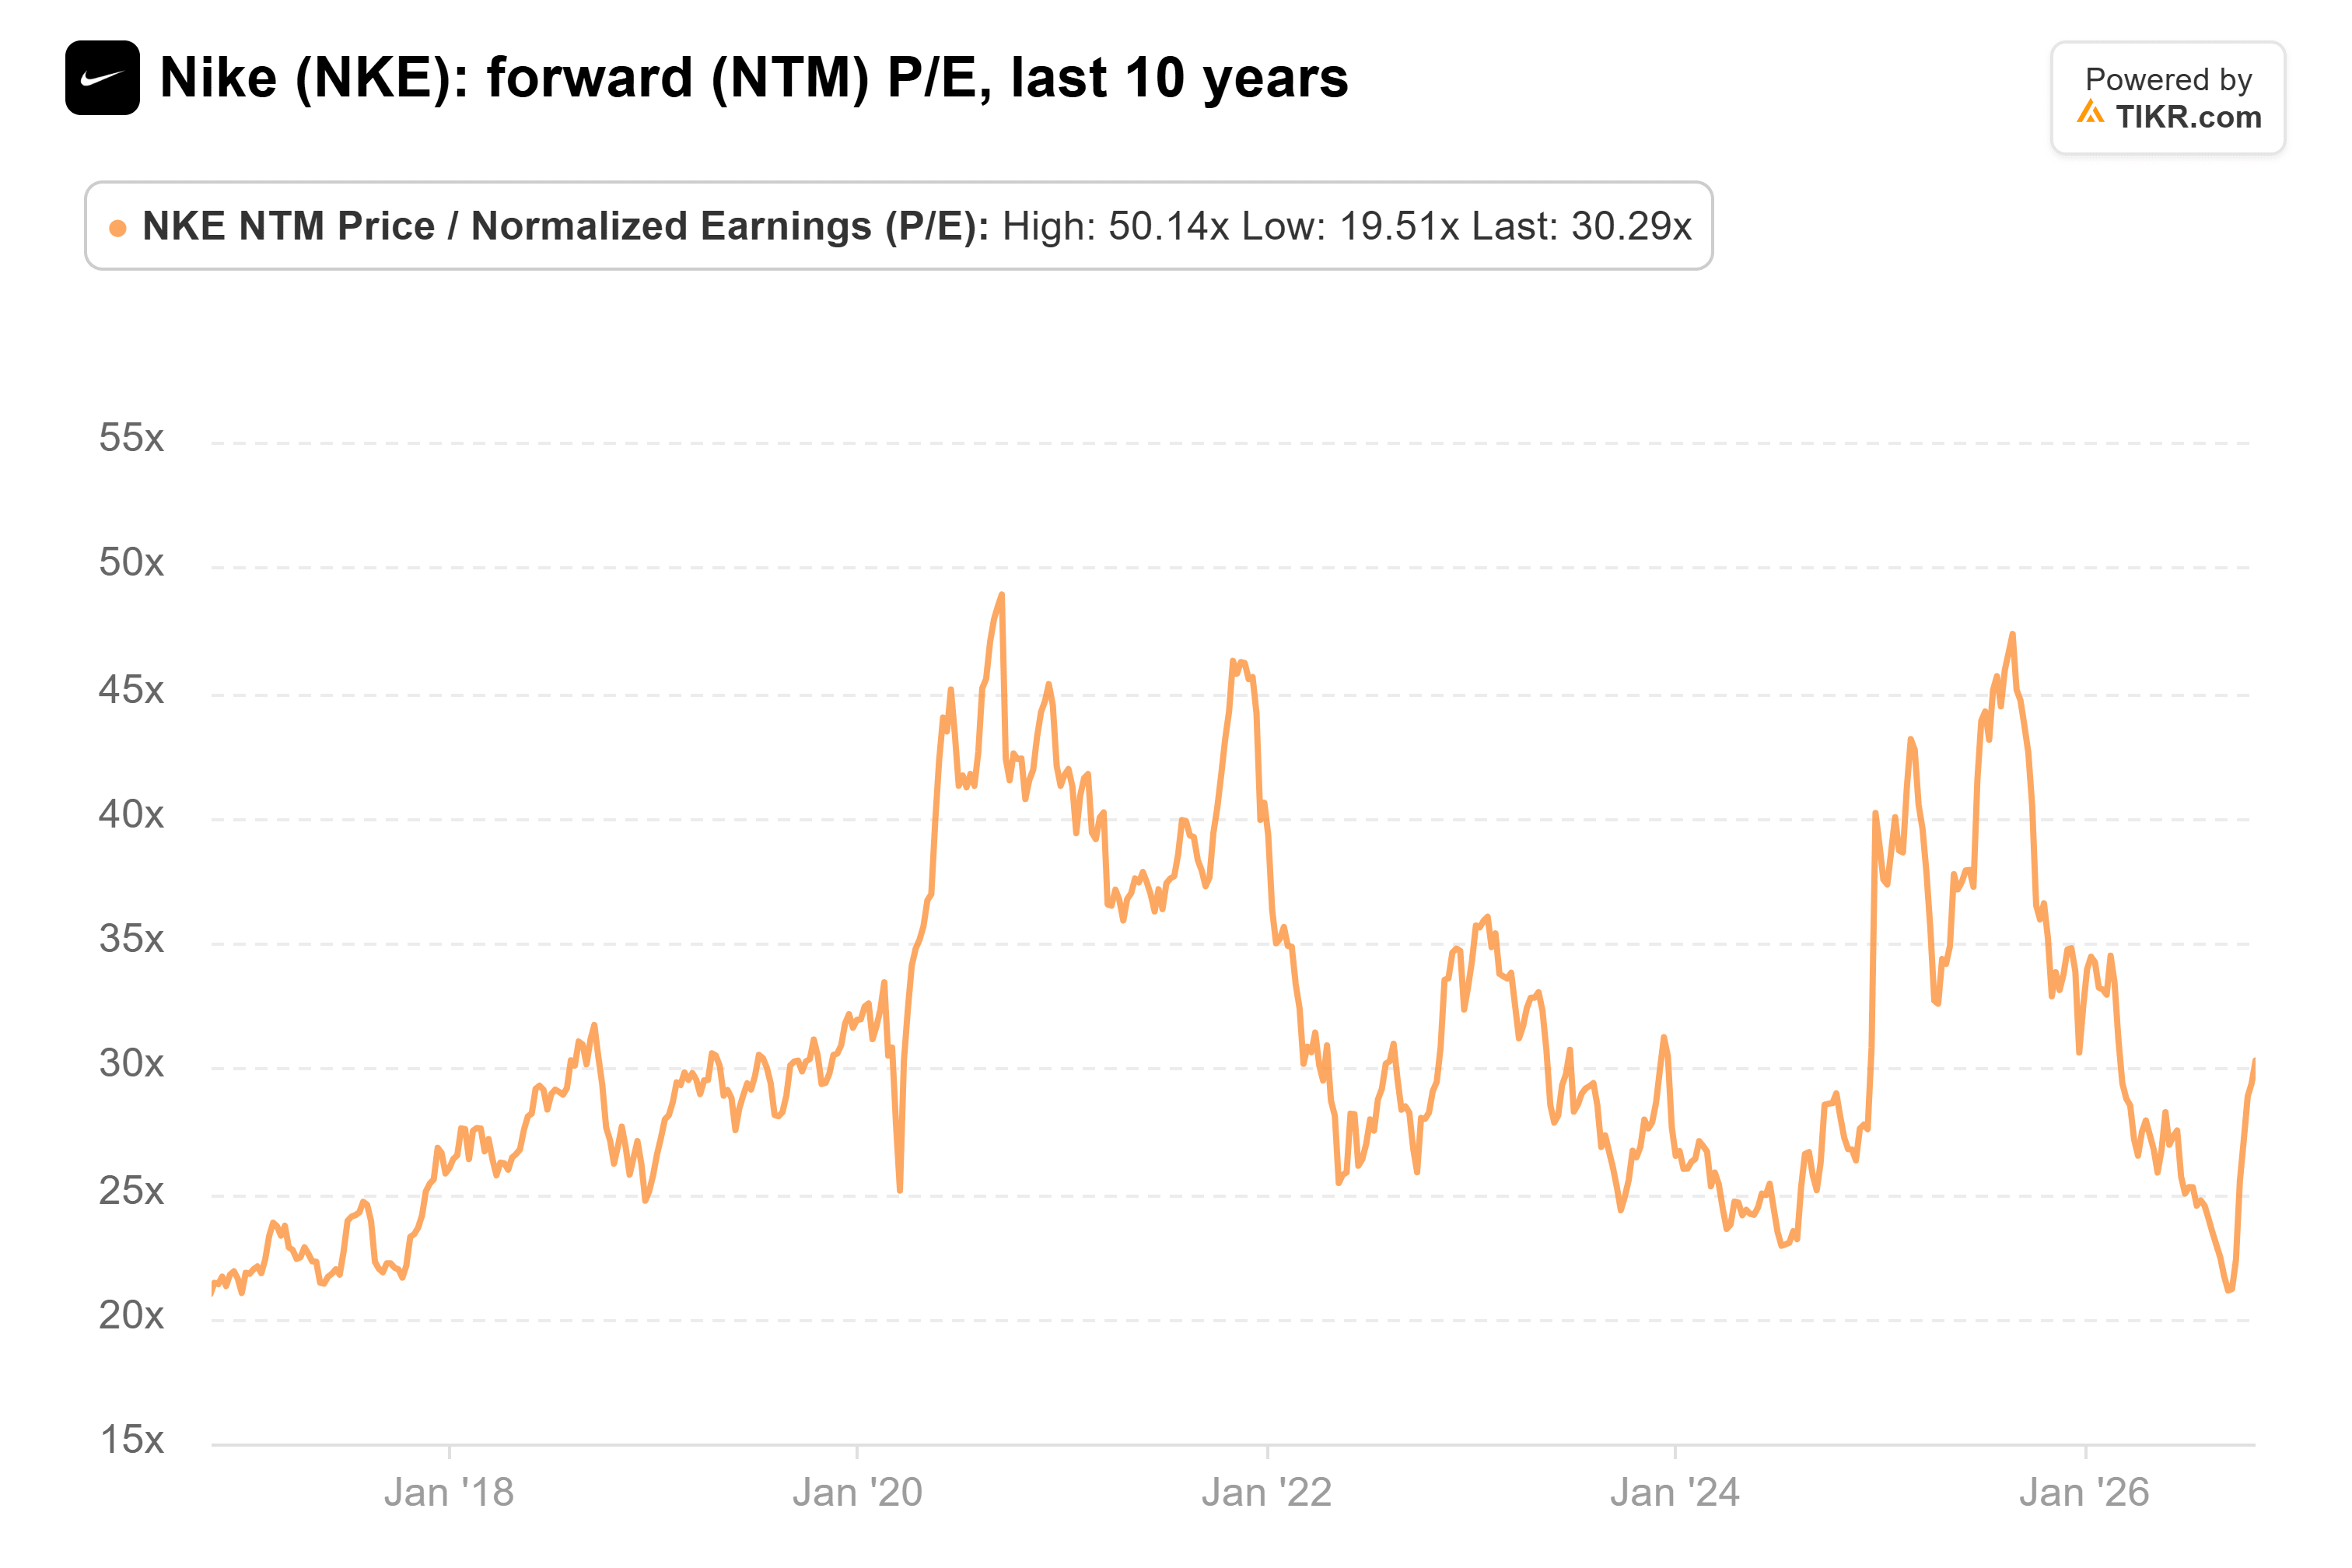
It was 30x on Monday, against a 31x average and a low of 20x in June 2024. At the end of August, it was 23x.
Part of that climb came from analysts cutting their estimates, and the rest came from the rally. At today’s price, it’s even higher.
At the last close, Nike traded at about 32x this year’s consensus and 26x fiscal 2028’s. That’s a full multiple for earnings near their low.
So buyers at this price are counting on the recovery in those estimates arriving on time.
Getting to $25 takes a decade-low multiple
Morgan Stanley is betting against that. Its $25 target is 20x this year’s consensus, right at Nike’s lowest forward P/E of the past decade. It’s just 16x fiscal 2028’s.
For Nike to be worth $25 at its 31x average, EPS would have to land around $0.80. That’s well under the $1.15 low end of Nike’s own guidance.
The bull case is in the margins
Bulls argue that these are trough earnings. Nike’s operating margin was in the low-to-mid teens in most years of the past decade, and it’s at 9% now:

If margins got back there, today’s estimates would look far too low, and the multiple would shrink without the stock falling. (At the last close, Nike traded at about 10x fiscal 2024’s $3.95.)
But analysts don’t expect that soon. They see a 5.7% operating margin this fiscal year and 7.0% in fiscal 2028.
Nike’s new cost program, Pace, targets $2.5 billion of savings through fiscal 2031, and most of that arrives in fiscal 2029 and 2030.
Priced for the recovery, on schedule
The way I see it, Nike is fairly valued at this price, on a recovery that analysts are still marking down.
Morgan Stanley’s $25 needs results worse than Nike’s own guidance, and that looks too harsh to me. But buyers here are paying in full for a rebound that hasn’t started, so I wouldn’t chase the rally.
Of course, Nike’s Investor Day on Nov. 16 and 17 could change that. Management has said it will lay out its long-term financial goals there.
A dated path back to double-digit operating margins would make today’s multiple look a lot more reasonable. Q2 results follow on Dec. 17.
So what is Nike stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Nike could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!