Key Takeaways
- Freedom Capital Markets downgraded Visa (V) to Hold with a $427 price target after the stock gained 18% in a month to a 52-week high.
- Visa’s forward P/E has climbed from 23x at the end of March to its 10-year average.
- Analysts’ fiscal 2027 EPS estimate implies 13% growth, the top of the range Visa guided to last week.
- At this multiple, the stock needs earnings estimates to keep rising, so Freedom’s Hold looks like the right call for now.
Visa shares have gained 18% in a month to a 52-week high, and today they got a Hold.
Freedom Capital Markets downgraded the stock from Buy and raised its price target to $427, from $410.
That target is below where Visa closed Tuesday. It’s also the only Hold among the calls analysts have made since Visa reported on Oct. 27.
The rest of the Street is still buying
DZ Bank kept its Buy rating today. On Monday, Cantor Fitzgerald raised its target to $500 from $445. On Oct. 29, Wells Fargo raised its target to $463 from $432, and Mizuho raised its target to $440 from $425. Visa closed Tuesday just below Mizuho’s target and about 15% below Cantor’s.
The quarter wasn’t the problem. Fiscal Q4 adjusted EPS rose 17% to $3.48, ahead of the $3.44 consensus, and net revenue rose 13% to $12.14 billion. For the year ended September, EPS rose 16% to $13.27, and the board raised the dividend 16%.
Freedom’s problem is the year ahead. Visa guided fiscal 2027 net revenue growth to the low double digits and EPS growth to the low double digits to low teens.
Freedom analyst Mikhail Paramonov’s team sees that as a slowdown from a high base. They point to rising client incentives and a record number of contract renewals.
Incentives jumped 21% to $5.1 billion in Q4, and about 25% of Visa’s payment volume comes up for renewal in fiscal 2027, up from 20% this year.
TIKR tracks 41 analysts on Visa. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Visa, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Visa’s Analyst Ratings
Analysts are already at the top of the guide
Analysts expect normalized EPS to keep growing at a double-digit pace through fiscal 2028:

The fiscal 2027 consensus of $15.02, from 39 analysts, is 13% above fiscal 2026’s $13.27. That’s the top of management’s range.
Fiscal 2028’s $17.13, from 32 analysts, needs 14% growth on top of that.
The multiple did most of the work
Visa’s forward P/E is back to where it has averaged over the past decade:

It was 28x on Nov. 2, in line with its 10-year average and well below its 40x peak in December 2020. Tuesday’s gain took it to about 29x. At the end of March, it was 23x.
Over that stretch, the fiscal 2028 EPS estimate has risen about 2%, from $16.83 at the end of June. Most of the stock’s run came from investors paying more for the same earnings.
Visa has earned its premium
To be fair to the bulls, a 28x average didn’t come from nowhere. Visa’s EPS grew about 15% a year over the decade to fiscal 2025.
A business that compounds like that deserves a premium, and its estimates have been edging higher rather than falling.
So the price is fair if Visa keeps doing what it has done. Price targets look about a year out, when next-twelve-months earnings will roughly match fiscal 2028’s.
Freedom’s $427 is about 25x fiscal 2028 consensus EPS, right at Visa’s one-year average forward P/E. Cantor’s $500 is about 29x, which assumes today’s multiple holds for another year.
The Street’s average target has climbed along with the stock over the past year:
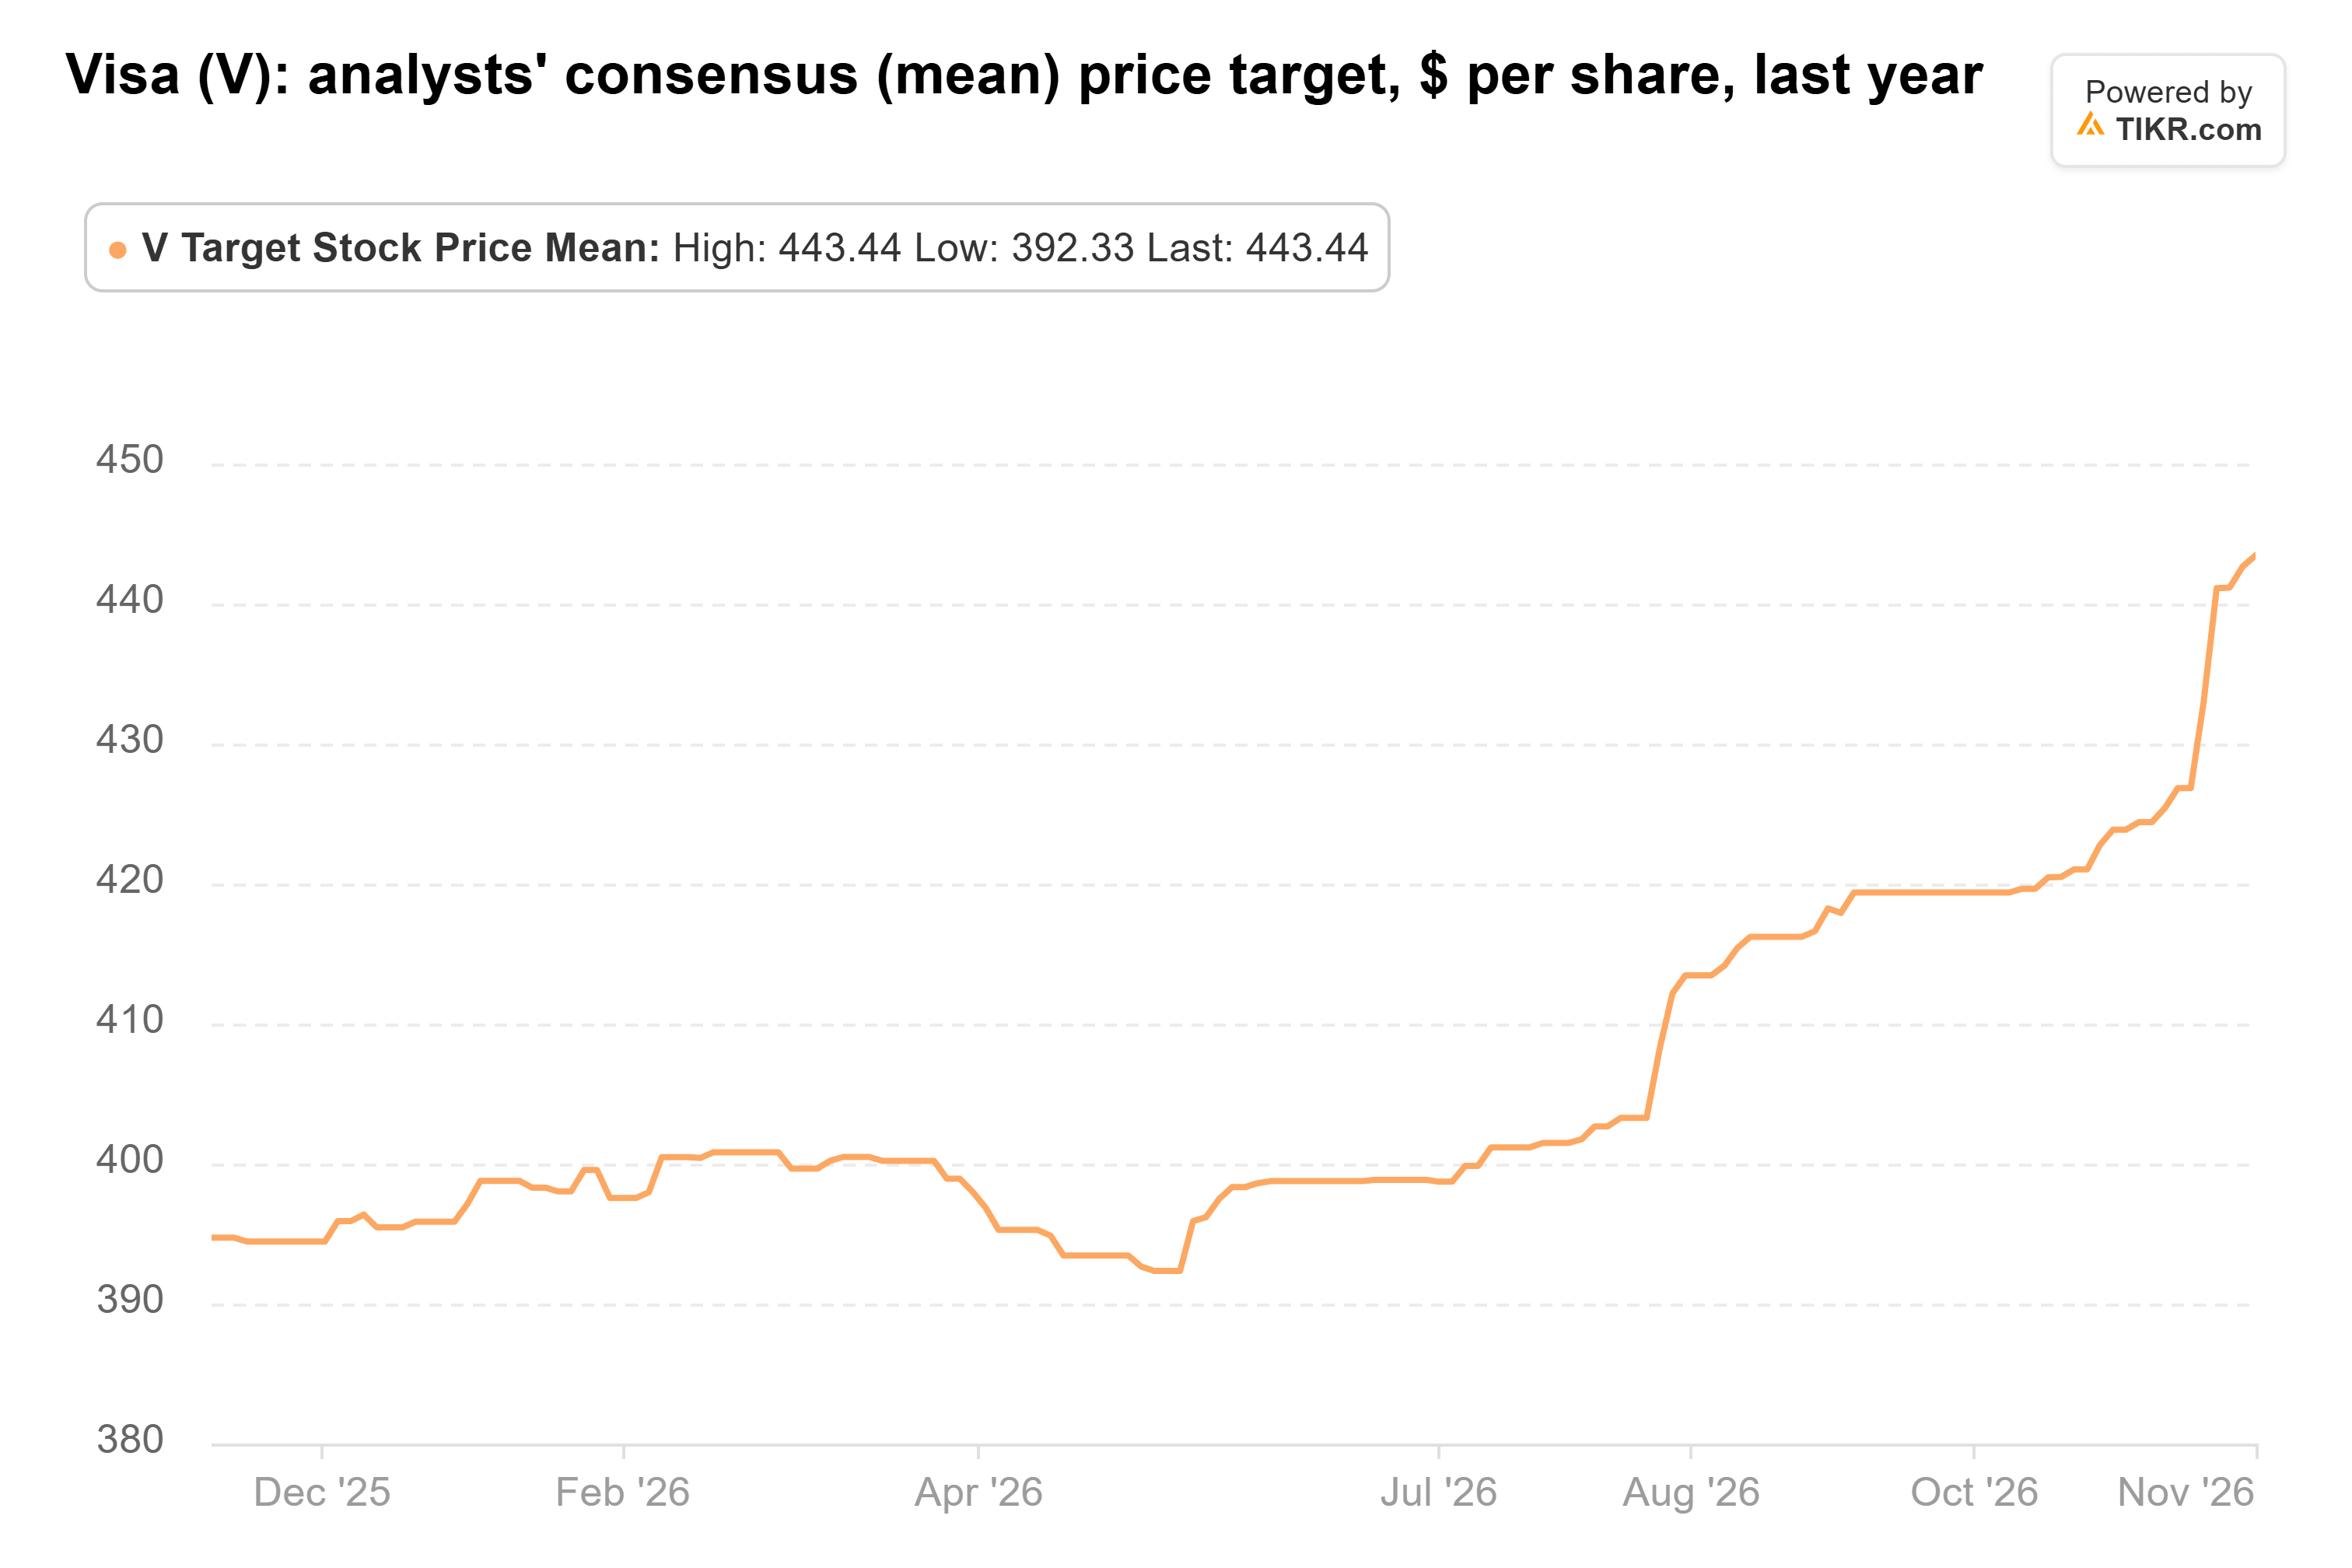
The average target rose from $395 to $443, and Visa closed Wednesday within about 2% of it. Individual targets run from $330 to $500.
The renewals Freedom points to are the biggest risk. If issuers win bigger incentives, EPS growth could slip toward the low end of the guide, and a 29x multiple would be hard to hold.
Frankly, I think Freedom has it right. Visa is a terrific business, but at about 29x, the stock is priced for the top of its guidance and has nearly caught up to the Street’s average target. I’d want a pullback, or a fiscal 2027 that runs ahead of the guide, before buying more.
Of course, renewals could come in cheaper than feared. We’ll get a first read when Visa’s CFO speaks at the Citi FinTech conference on Nov. 9, and a clearer one when Visa reports its fiscal Q1 early next year.
So what is Visa stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Visa could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!