Key Takeaways
- Accenture shares jumped about 17% after fiscal fourth-quarter revenue of $18.7 billion topped both its own guidance range and the $18.04 billion consensus.
- The rally reflects how far expectations had fallen on AI-disruption worries, since the company’s outlook came in slightly below consensus at the midpoints.
- Clients signed a record 141 bookings of $100 million or more in the quarter, and book-to-bill came in at 1.2.
- Fiscal 2027 guidance calls for 3% to 6% local-currency revenue growth, so bookings need to hold up to keep the rally going.
Accenture (ACN) is up about 23% after reporting fiscal fourth-quarter results before Thursday’s open.
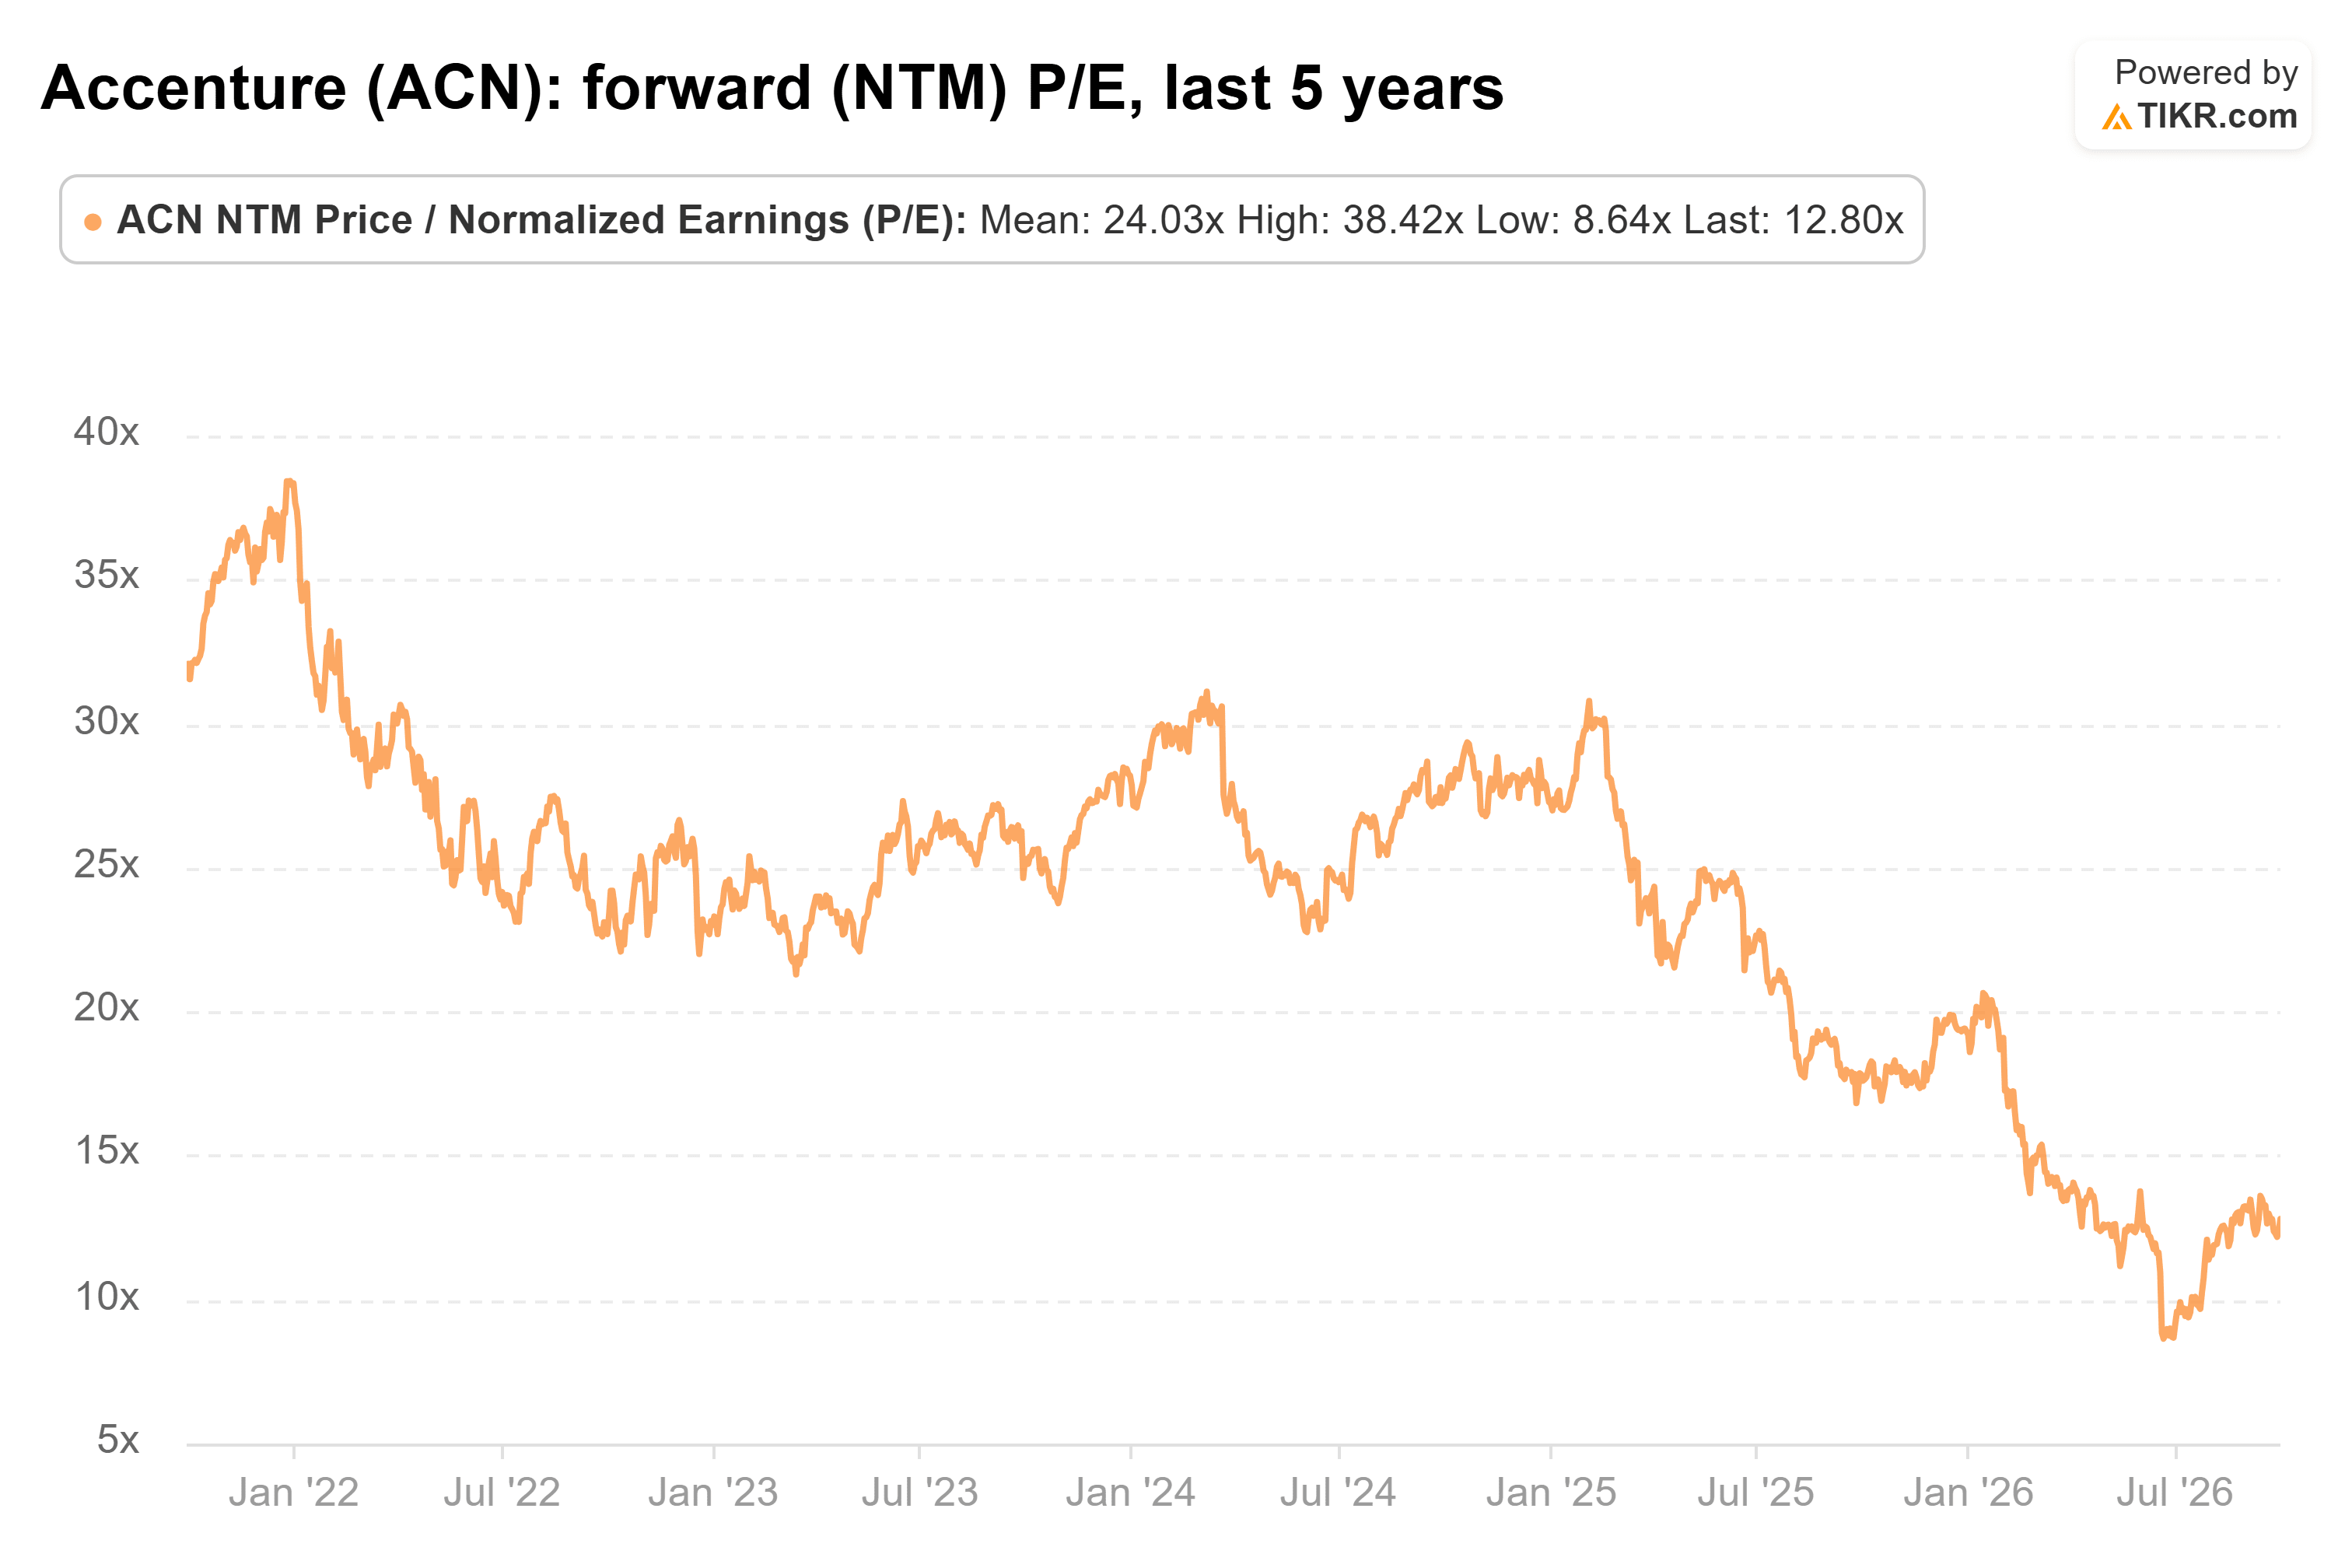
That’s a huge move for a business with $74 billion in annual revenue. The stock had been sliding on fears that AI would shrink demand for consultants. TIKR noted last month that it was down 37% from its peak. This quarter was a firm rebuttal to that fear. Jevons paradox at work, yet again.
What exactly happened
- Revenue of $18.7 billion, up 7% in local currency, about $640 million above the $18.04 billion consensus
- That cleared the top of Accenture’s own $17.75 billion to $18.40 billion range
- EPS of $3.29, against a $3.18 consensus
- New bookings of $22.2 billion, a book-to-bill of 1.2 (about $1.20 of new work signed for every dollar billed)
CEO Julie Sweet said the company “capped off another year of broad-based growth across our business” and “reached a new high of 141 quarterly client bookings of $100 million or more.”
Why this matters
The bear case is that clients will need fewer consultants once AI can do the work. If that were happening, you’d expect the big contracts to dry up first. Instead, Accenture had more nine-figure deals than ever.
Communications, Media & Technology was also its fastest-growing industry group, up 11% in local currency. That group serves the tech companies building AI.
That supports the pitch behind Accenture’s recent partnership with Anthropic: companies adopting AI still need someone to put it to work.
The guidance didn’t have to be great
Here’s the thing: the outlook came in a bit light. The fiscal 2027 EPS range of $14.39 to $14.81 has a midpoint of $14.60, against a $14.67 consensus. First-quarter revenue of $18.95 billion to $19.60 billion has a midpoint of about $19.3 billion, a hair below the $19.4 billion consensus.
A 23% jump on guidance like that shows how low the bar had fallen.
What’s next
I think this rally is earned. Accenture produced $11.6 billion of free cash flow last year and plans to return at least $9.5 billion to shareholders this year, and the market had been pricing it like a business in decline.
Meanwhile, Wall Street is predicting (modest) growth ahead. And nothing in this quarter’s release makes me expect downward revisions.
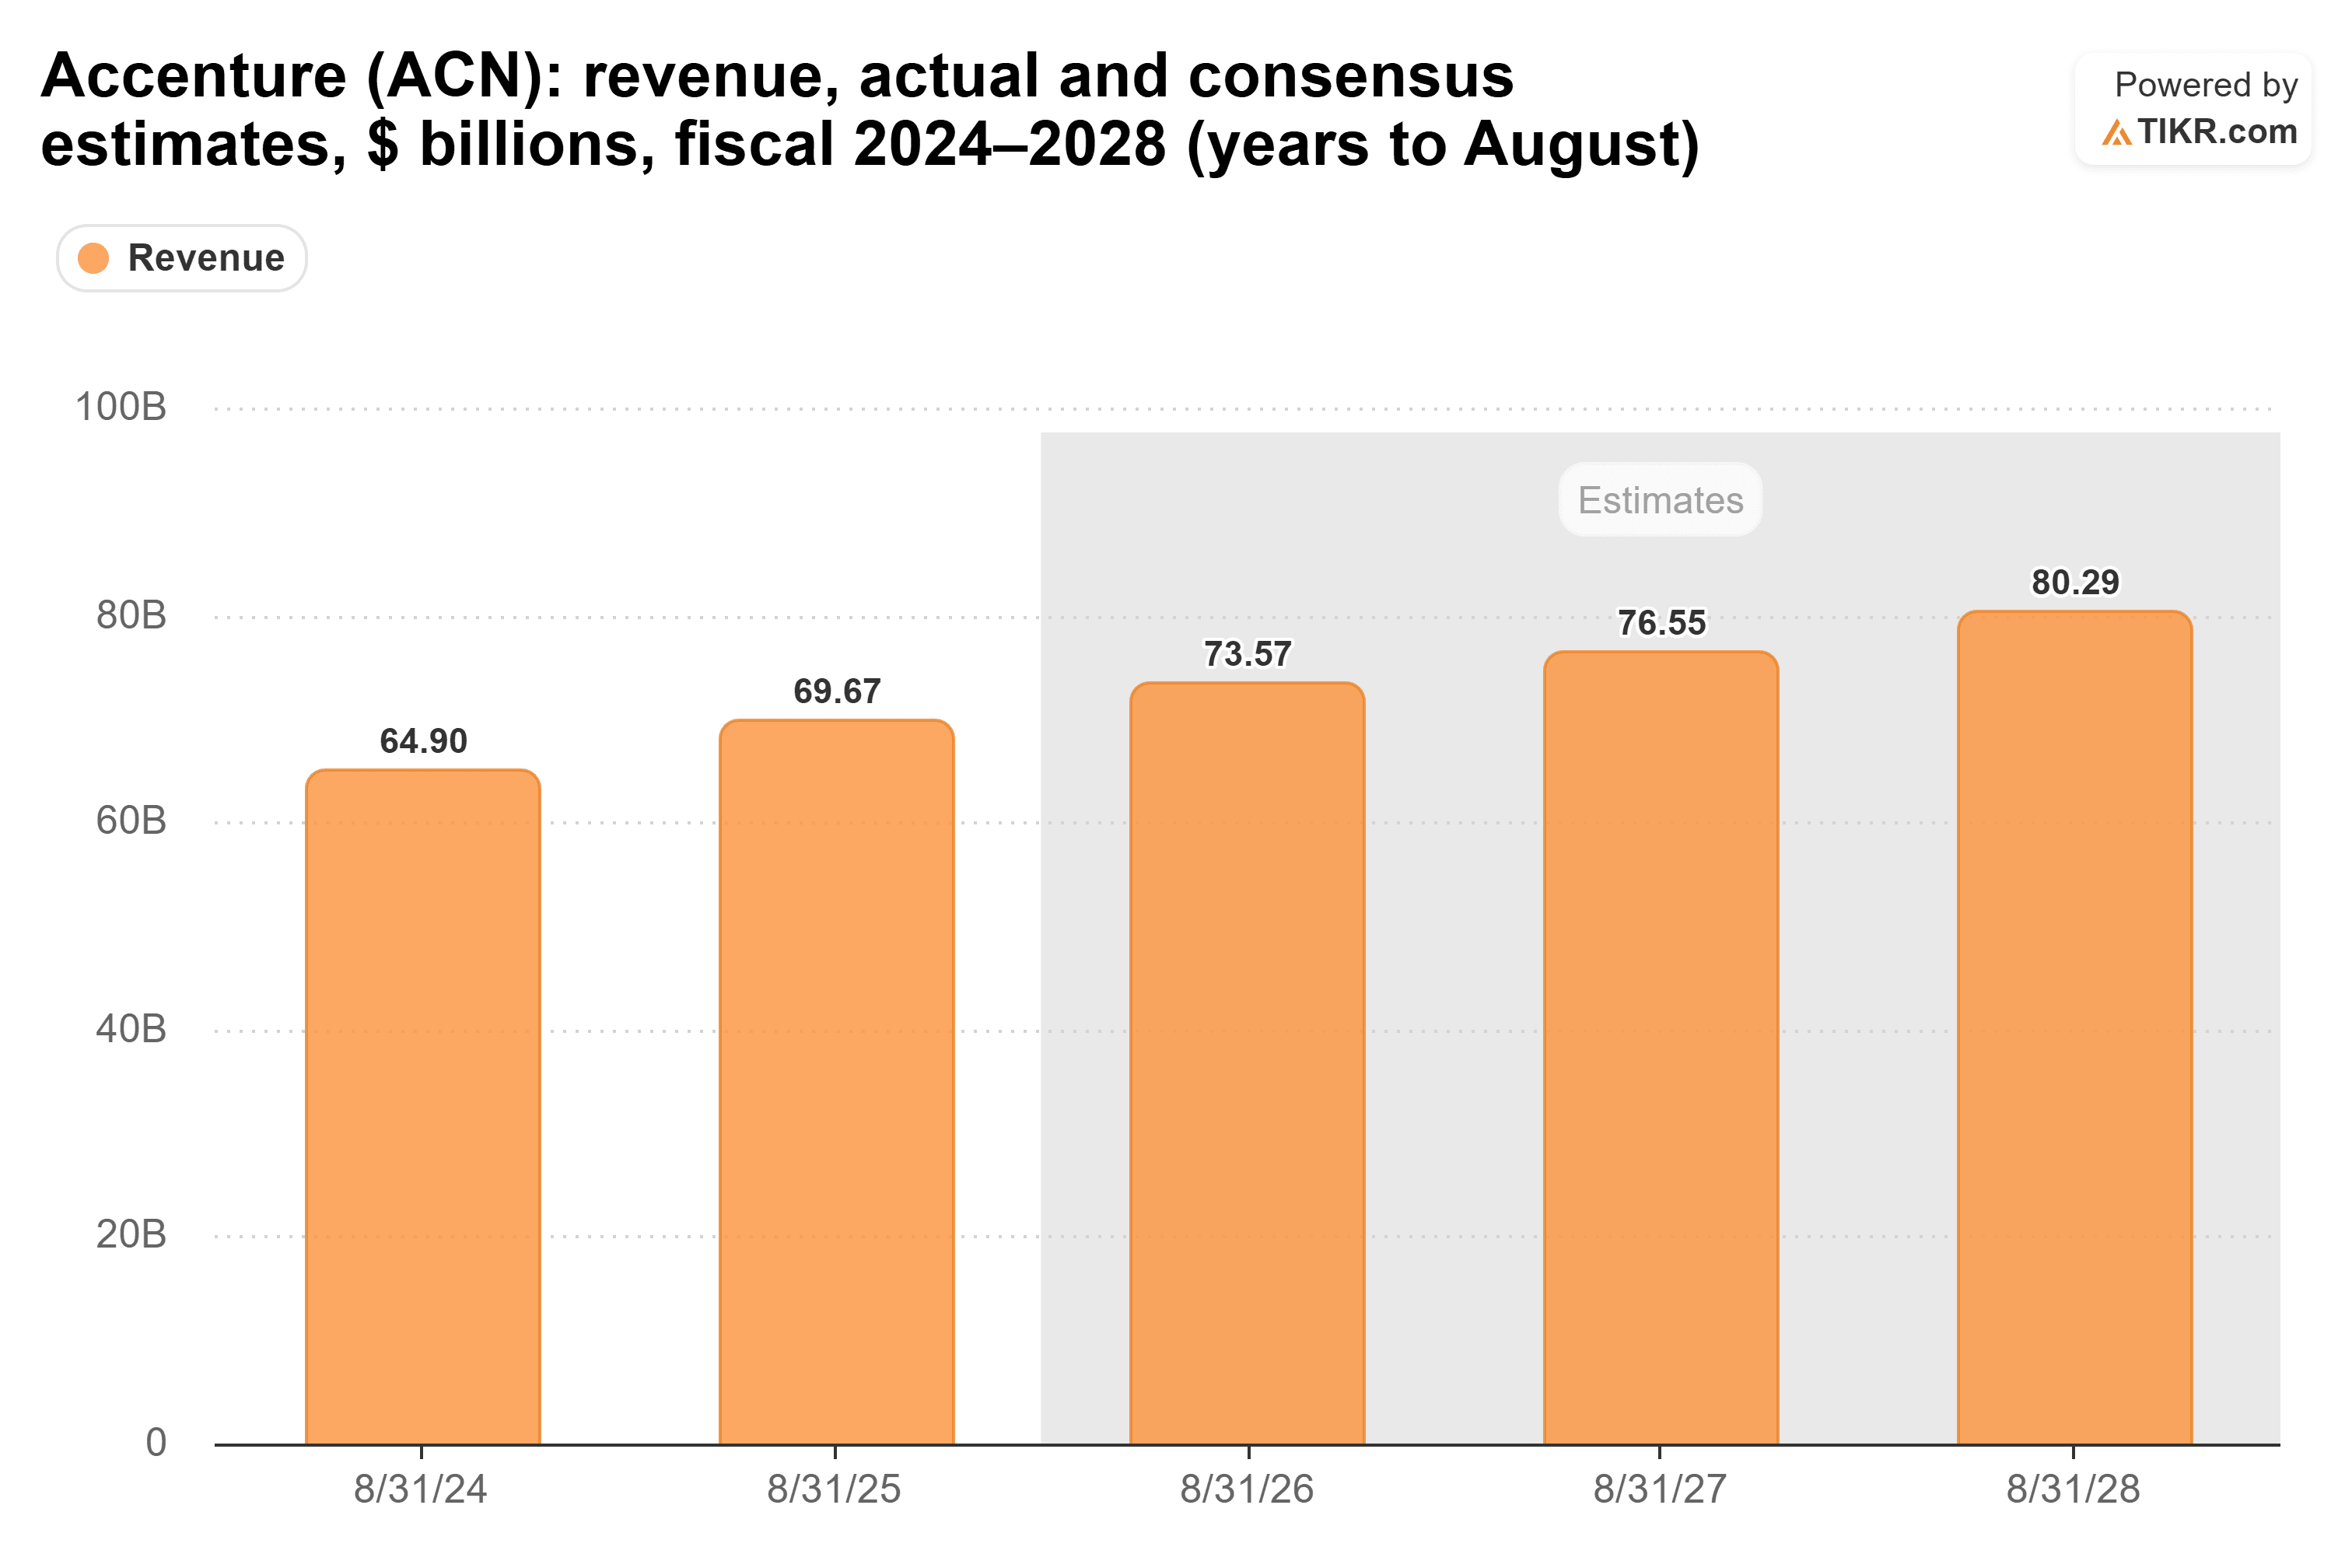
So did the quarter ease the AI fears? For now, yes. Of course, one quarter of bookings doesn’t settle the question, and with guidance calling for 3% to 6% growth, the coming quarters will show whether the big deals keep coming.
So what is Accenture stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Accenture could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!