


Key Takeaways
- A $3.2 billion fund, Blue Whale Capital, added to Applied Materials and Lumentum and opened a stake in SK hynix in the third quarter. On Sept. 30, the three were among its four biggest positions.
- All three stocks have fallen 41% to 53% since Sept. 30.
- Lumentum now trades on Marvell’s stock because of a pending all-stock deal, and SK hynix is priced for the end of a memory boom.
- Applied Materials is the one the numbers back best: analysts’ earnings estimates kept rising as the stock fell, and its forward P/E sits below its five-year average.
AI chip stocks have had a brutal couple of months. By Sept. 30, one $3.2 billion fund had made three of them among its four biggest positions.
Blue Whale Capital’s 13F for the quarter ended Sept. 30, filed Nov. 13, shows it added to Applied Materials (AMAT) and Lumentum (LITE) and opened a new stake in SK hynix (SKHY). That $3.2 billion is what its 13F holds in US stocks, across 24 positions. A 13F shows only what a fund held on the last day of the quarter, so we don’t know what Blue Whale paid or whether it still owns the shares.
Applied Materials’ estimates kept climbing
Blue Whale held 776,812 Applied Materials shares on Sept. 30, 30% more than in June. They were worth $397 million, which was 12.4% of its 13F and its second-biggest position. The stock is down 41% since then, even though Applied reported a record quarter on Nov. 12. Thirteen firms cut their price targets after the report, and analysts’ average target has come down from its September high:
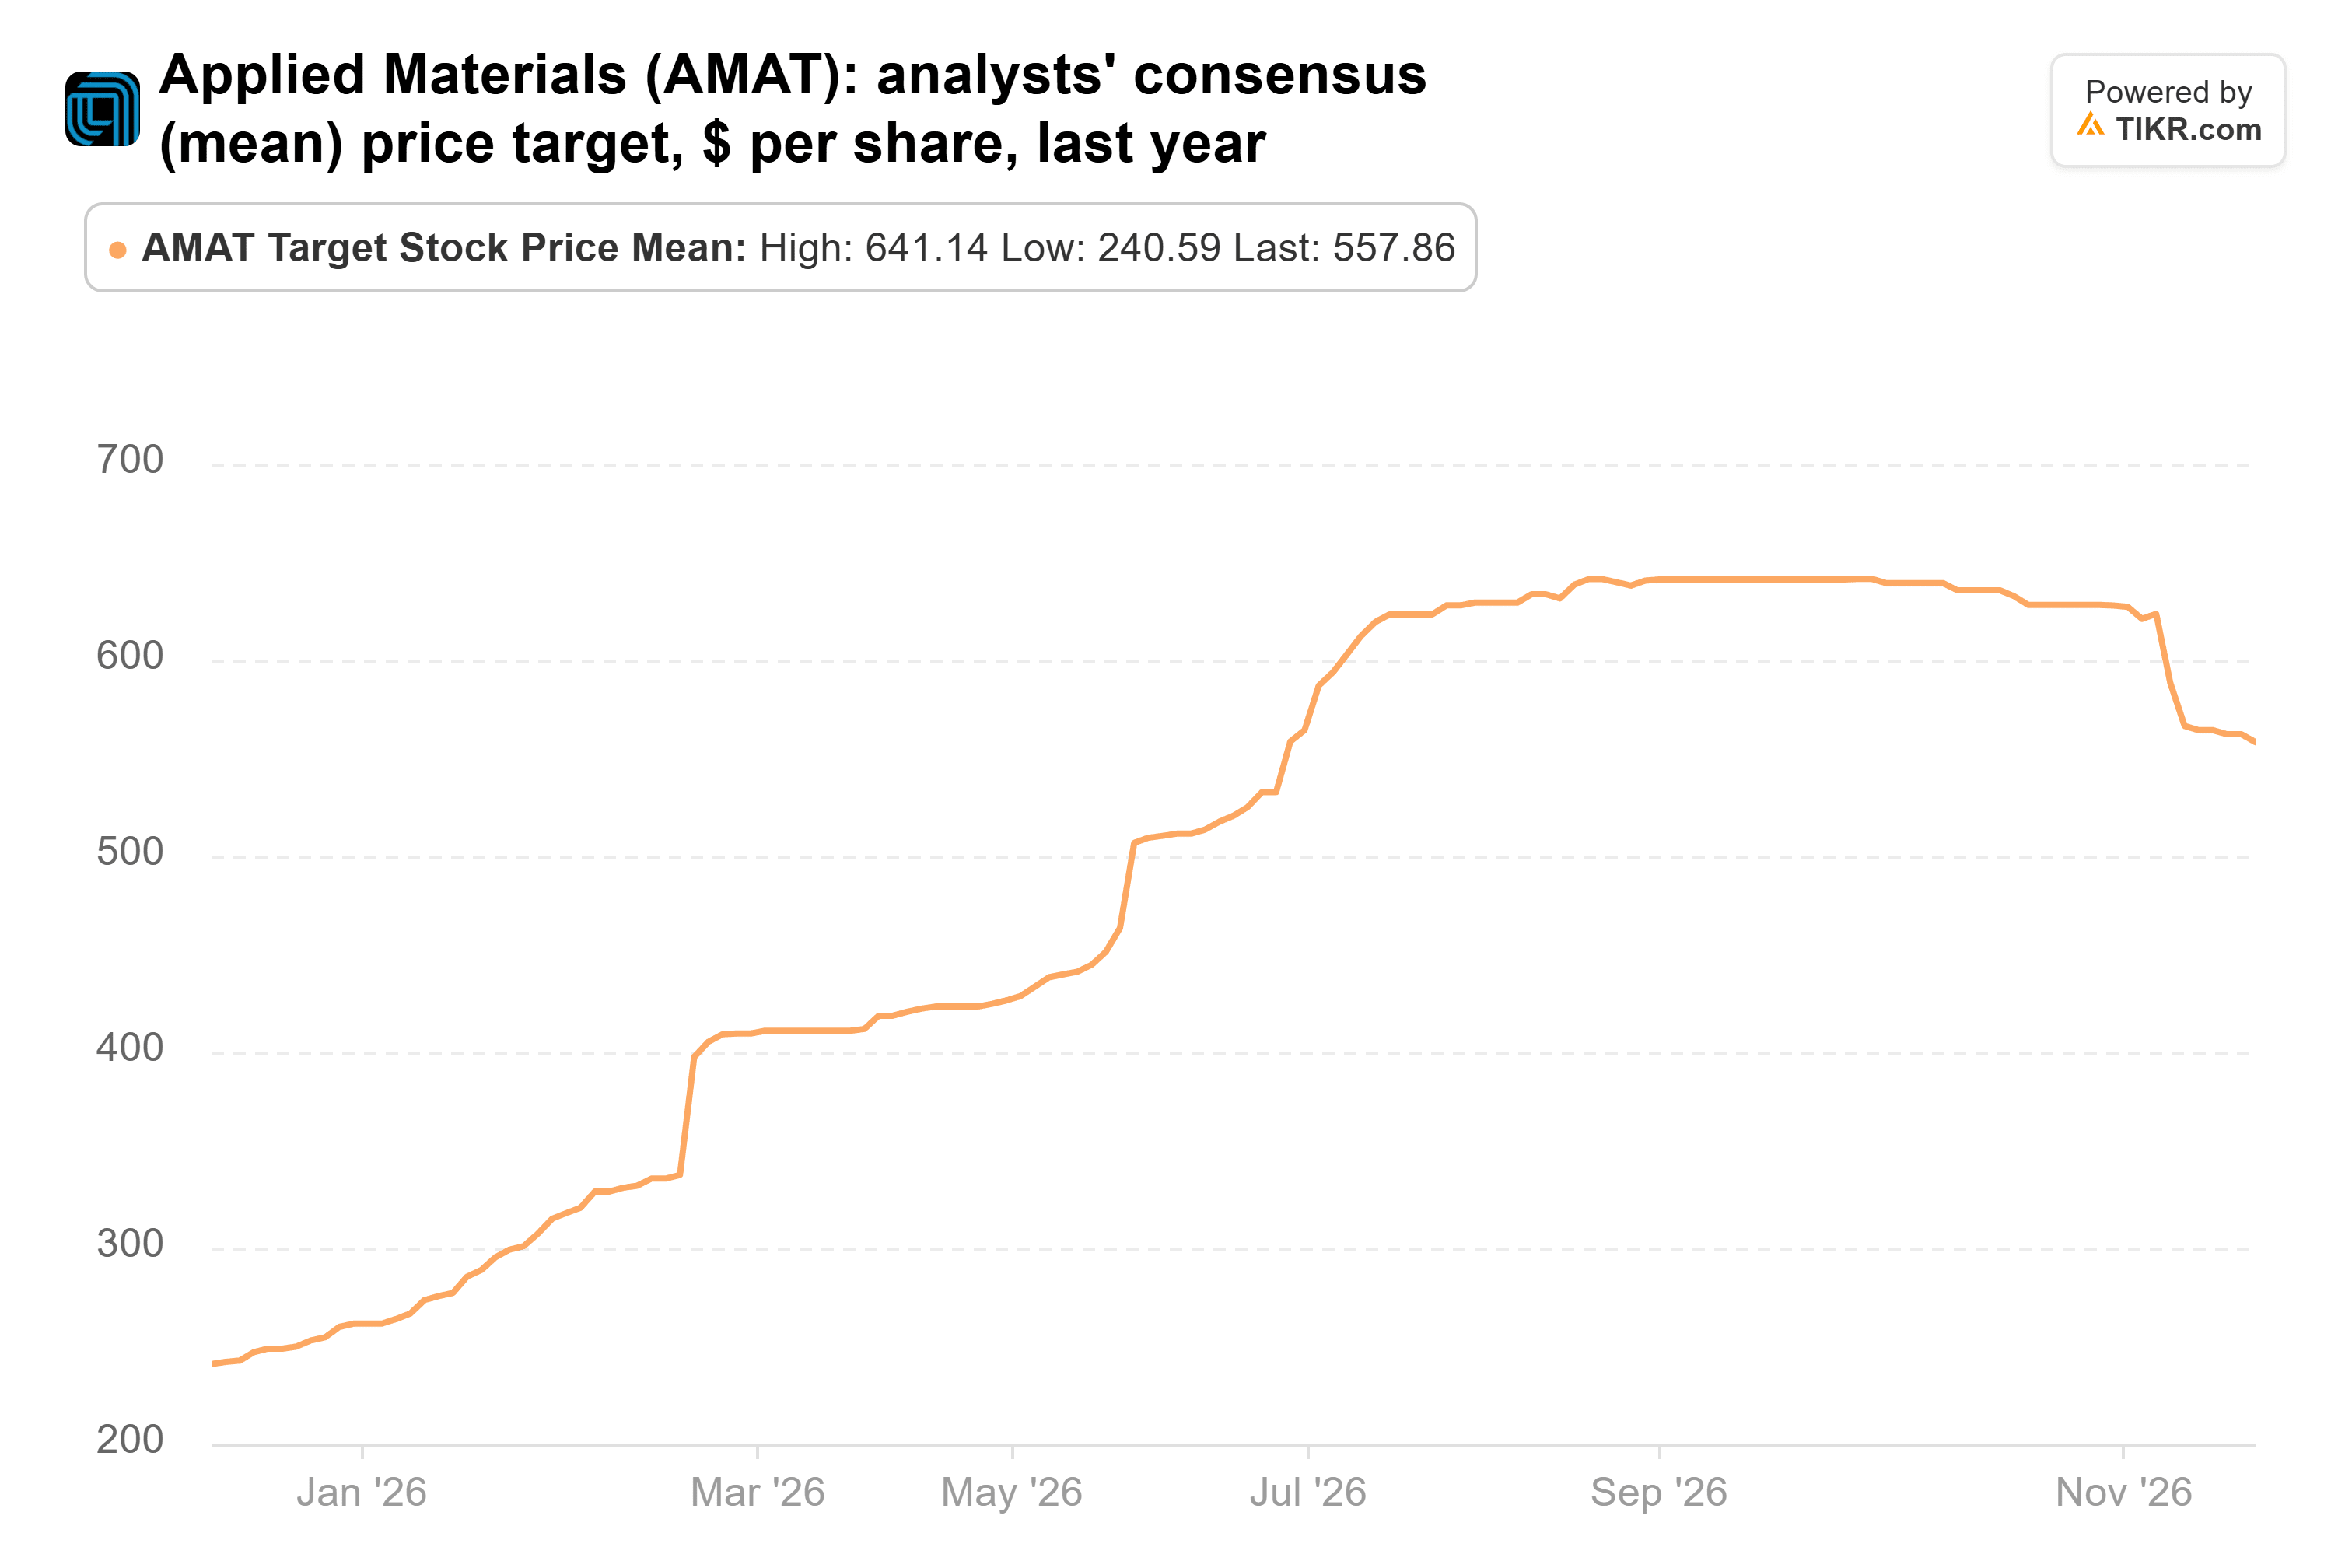
At $557.86, that average is still 84% above today’s price. The estimates moved the other way: consensus has Applied earning $19.29 a share, normalized, in fiscal 2027, up from $16.40 at the end of June. That leaves the stock at about 16x forward earnings, against a five-year average of 21x.
TIKR tracks 40 analysts on Applied Materials. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Applied Materials, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Applied Materials’ Analyst Ratings
Lumentum now trades on Marvell’s price
The fund added even more to Lumentum. Its stake rose 68% to 310,081 shares, worth $301 million, which was 9.4% of the 13F and its third-biggest position. The stock is down 53% since Sept. 30, and since Nov. 2 its price has mostly followed Marvell’s. That day, Marvell agreed to buy Lumentum for 4.5 of its own shares per Lumentum share, a deal worth about $1,132 a share when it was announced. With Marvell at $122.28, the deal is worth about $550 a share, and Lumentum trades about 16% below that.
Analysts’ average target peaked in mid-October and is down about 10% since:
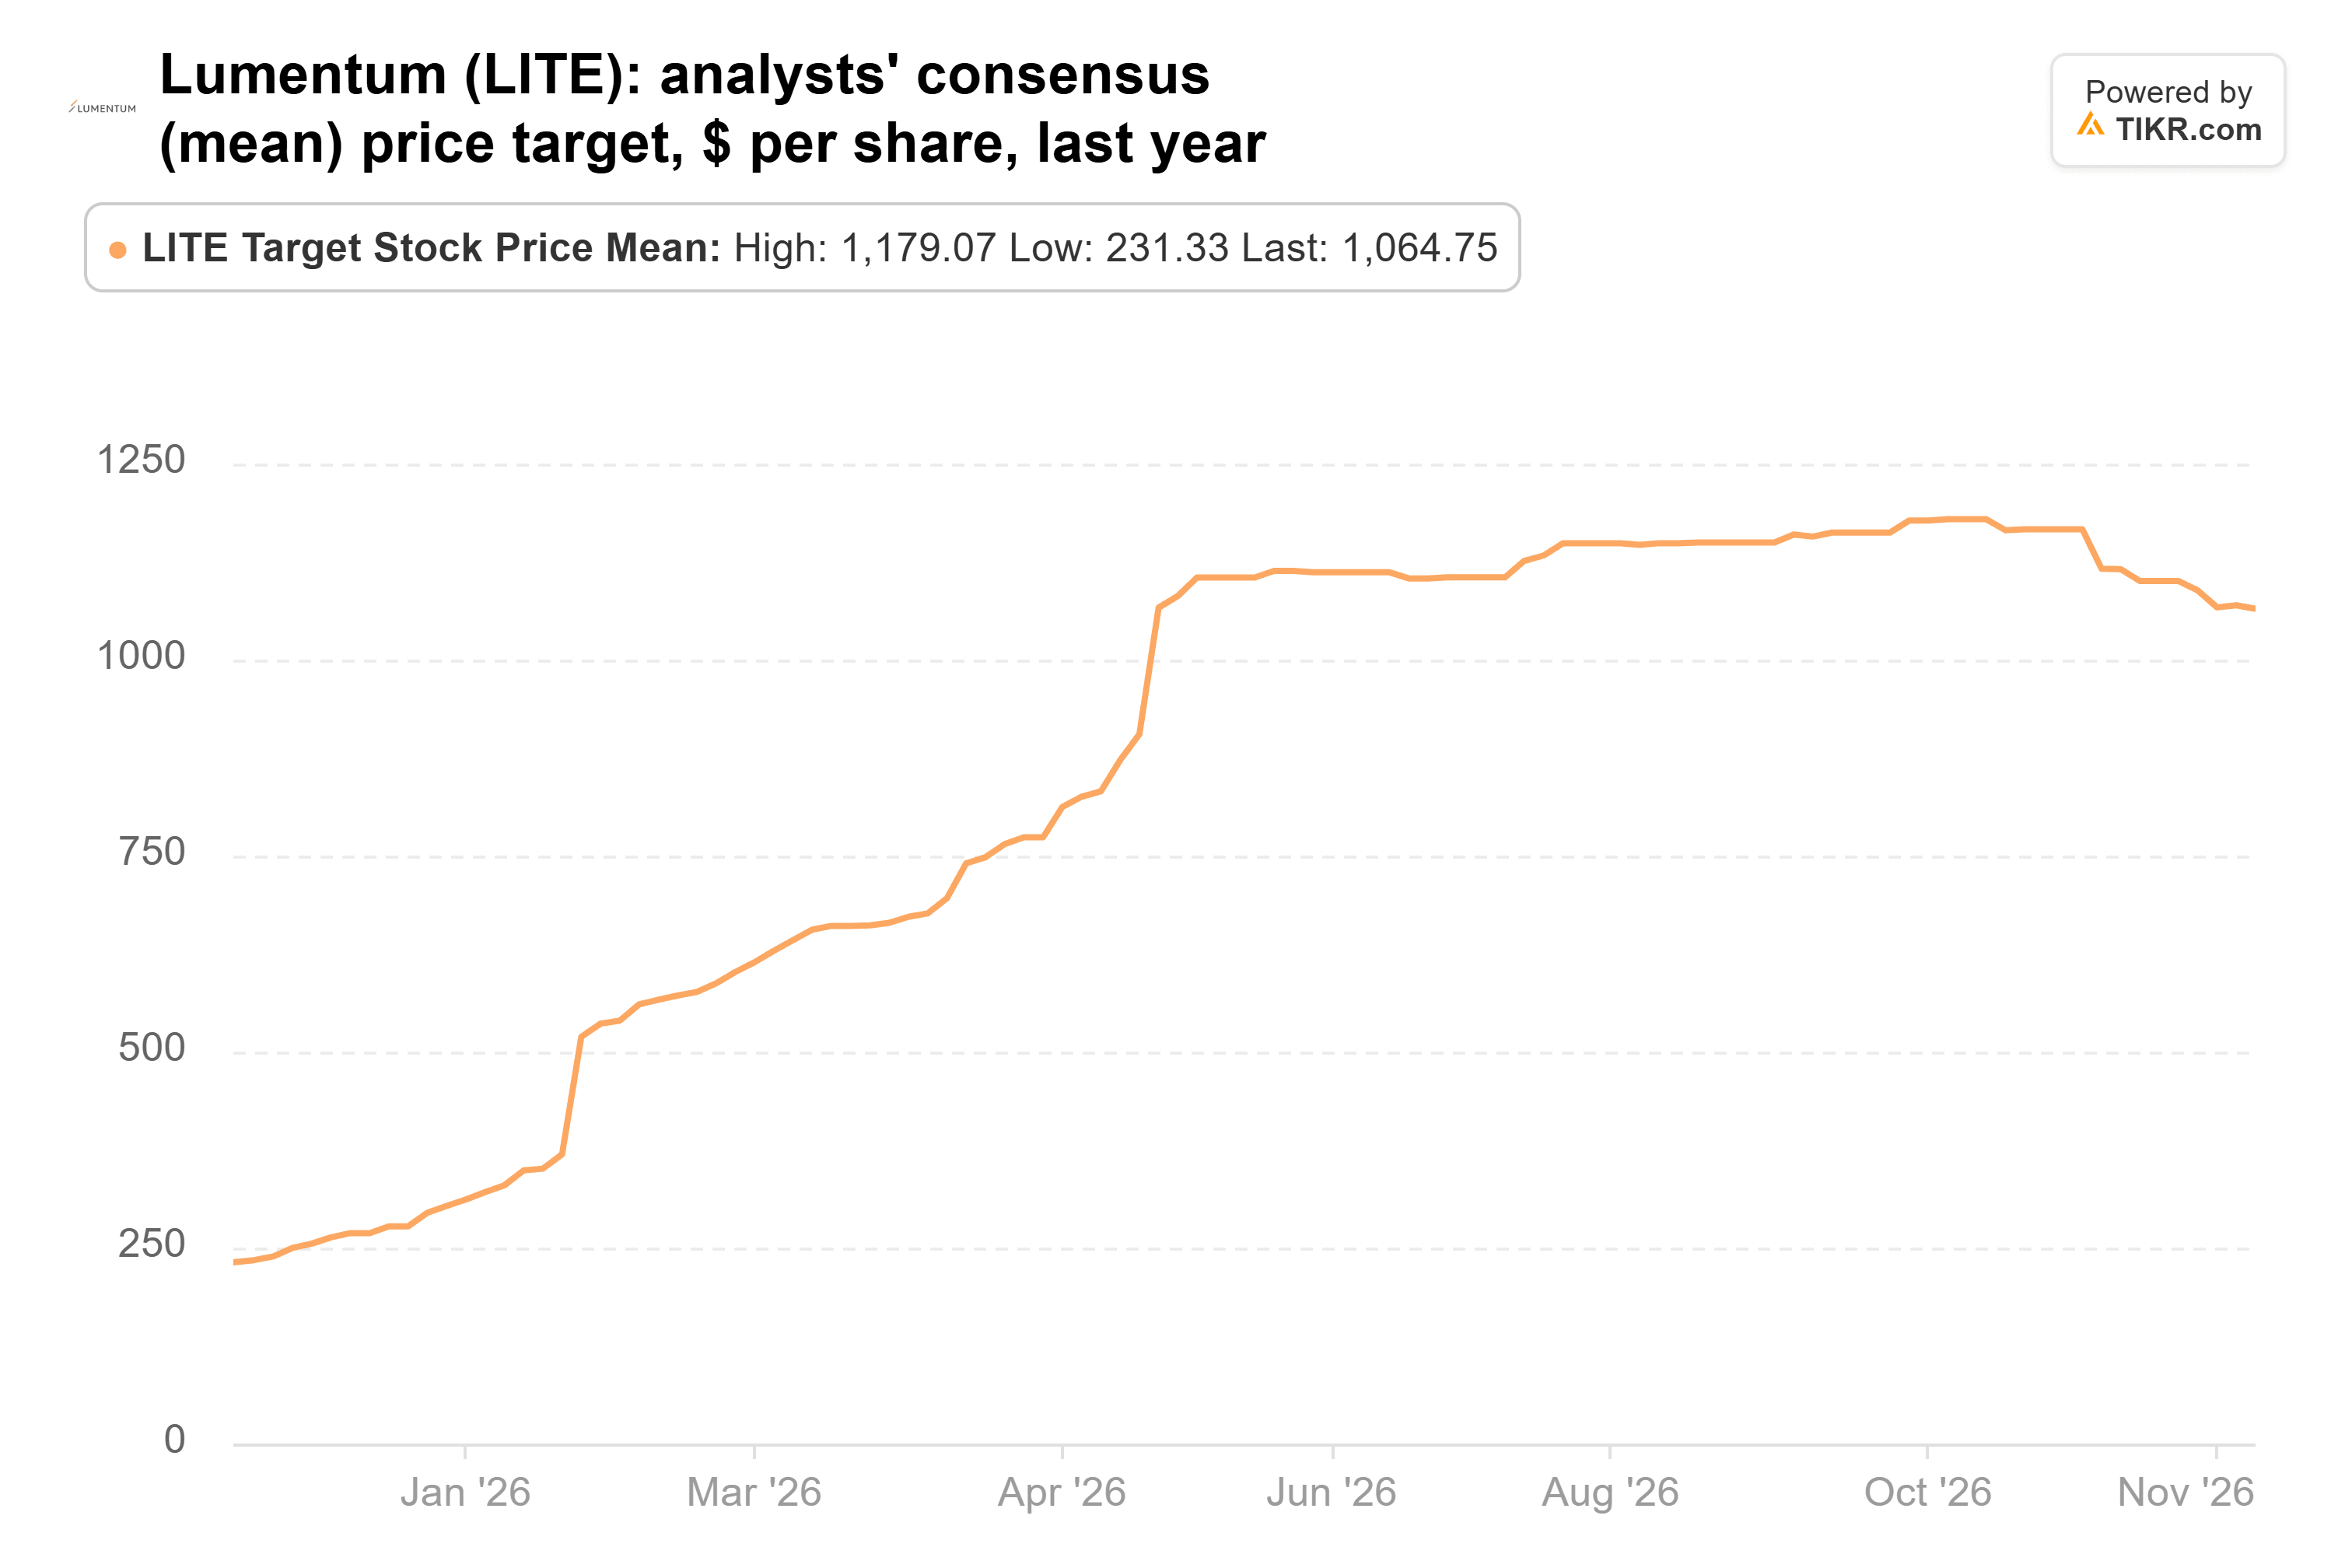
Most of those targets were set before the deal, which ties Lumentum’s value to Marvell’s stock until it closes. Bernstein, for one, now sets its target off Marvell’s price. Closing could take a while: analysts expect a Chinese antitrust review of 12 to 18 months, and Marvell owes Lumentum a $3.2 billion fee if regulators block the deal. So buying Lumentum today is mostly buying Marvell at a discount.
SK hynix is priced for the bust
SK hynix is the fund’s one new name: 1.18 million US-listed shares worth $218 million, 6.8% of the 13F and its fourth-biggest position. The stock is down 44% since Sept. 30, though the business hasn’t obviously cracked. Half of SK hynix’s 2027 and 2028 capacity is already contracted. And Nvidia just guided to $130 billion of revenue for a fourth quarter with an extra week. In January, TrendForce reported that Nvidia was expected to give SK hynix about two-thirds of its HBM4 orders. But Nvidia also lost Jensen Huang, who resigned as CEO on Nov. 12. And Dan Niles of Niles Investment Management says fourth-quarter memory price increases are coming in below what was expected a quarter ago.
Analysts haven’t followed the stock down. Their average target is below where it started when the shares listed in July, but it’s still far above the price:
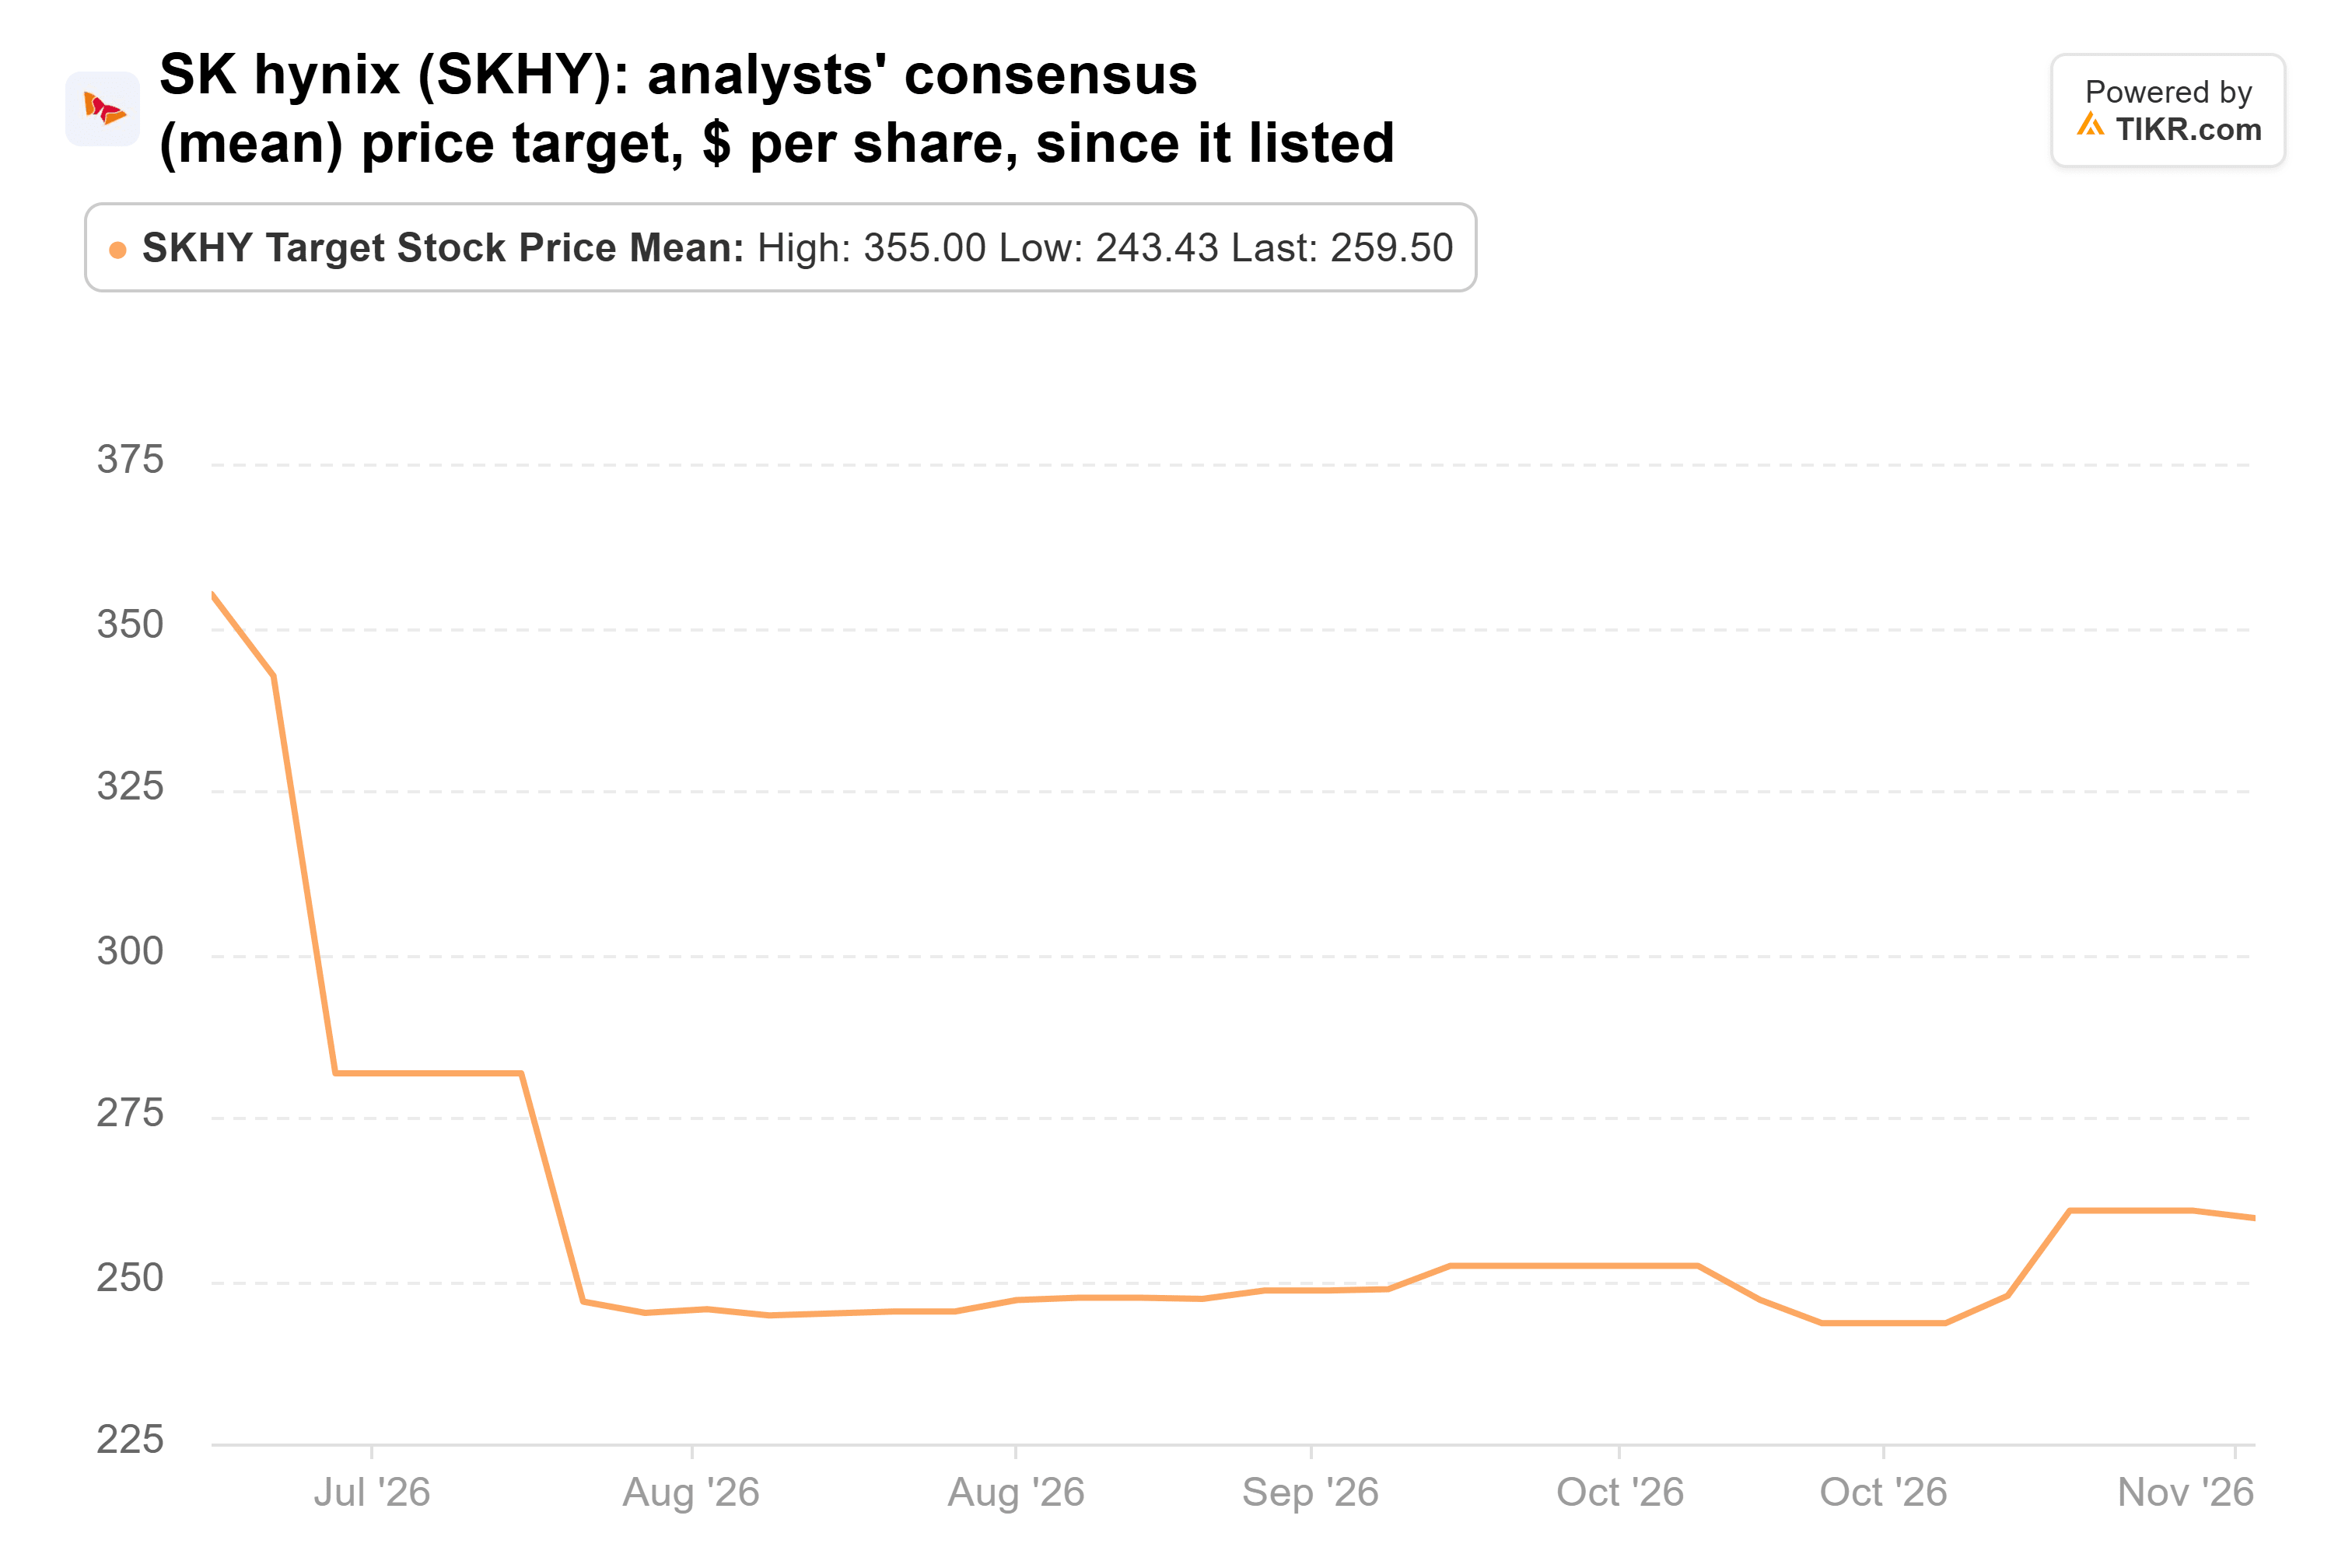
At $259.50, that average is 151% above today’s price. Investors are betting on a bust instead. SK hynix’s forward P/E sits near the bottom of its range since 2014, close to its 2018 readings. Its operating profit fell 87% the year after that.
Applied Materials is the one I’d buy
If I could only buy one of the three right now, it’d be Applied Materials. Its estimates rose through the selloff, so the stock got cheaper while its numbers got better, and it has no pending deal or swing in memory prices hanging over it. The risk is a repeat of 2018, when Applied’s forward P/E fell to 8.2x as a chip-equipment boom peaked. Two customers also supplied 34% of its revenue in the first nine months of fiscal 2026. Lumentum and SK hynix could bounce harder, but each depends on something outside its own business: Marvell’s stock for one, memory prices for the other.
The next tests come fast. Marvell reports on Dec. 1, and Applied’s fiscal first-quarter report in February will show whether that $19.29 holds up. Blue Whale’s next 13F, due in mid-February, will show whether the fund held on too.
So what is Applied Materials stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Applied Materials could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Applied Materials for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


