

Key Takeaways
- Eversource yields 4.6% and Mondelez 3.2%, but Mondelez raised its dividend 10% a year from fiscal 2020 to fiscal 2025, against 6% for Eversource.
- Mondelez’s dividend took 77% of its free cash flow in fiscal 2025, up from 58% in fiscal 2021, and analysts expect 74% for fiscal 2026.
- Eversource’s dividend took between 60% and 63% of its normalized EPS every year from fiscal 2016 to fiscal 2025, though it carries far more debt.
- At their 5-year growth rates, $10,000 in either stock would pay about $760 a year by year 10.
Mondelez International (MDLZ) and Eversource Energy (ES) both stood by their 2026 outlooks in their latest reports. Mondelez reaffirmed its targets on Oct. 29, and Eversource narrowed its earnings guidance on Nov. 4 and raised the midpoint.
Retirees living off dividends want a check they can count on, and these two pay very different ones. Eversource yields 4.6%, against 3.2% for Mondelez. Mondelez, on the other hand, raised its dividend 10.1% a year from fiscal 2020 to fiscal 2025, almost twice Eversource’s 5.8%.
So which one belongs in a retiree’s portfolio?
| Metric | Mondelez (MDLZ) | Eversource (ES) |
|---|---|---|
| Dividend yield | 3.2% | 4.6% |
| Dividend growth, fiscal 2020-2025 | 10.1% a year | 5.8% a year |
| Coverage measure | Cash dividend payout ratio | Payout ratio of normalized EPS |
| Coverage, last reported | 70% (TTM to Sept. 30, 2026) | 63% (fiscal 2025) |
| Coverage, forward (fiscal 2026 consensus) | 74% | 68% |
| Net debt/EBITDA | 2.6x | 5.8x |
| Forward P/E | 20x | 15x |
Source: TIKR. Yields and P/Es at today’s prices.
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours as part of our new investment report. Learn more about how to get access right here.
Mondelez’s payout ratio keeps climbing
Mondelez is still growing. Organic net revenue rose 2.1% in the third quarter of 2026, and adjusted EPS of $0.78 was up 5.5% in constant currency. Much of the growth is coming from places like India, where Mondelez has added about 130,000 outlets this year, and Brazil, where it’s now in over 1 million stores. Europe went the other way, with revenue down 3.3% as Mondelez laps last year’s chocolate price increases.
Mondelez’s dividend took 70% of its free cash flow over the twelve months to Sept. 30, 2026. That’s still covered, but the margin has been shrinking. Free cash flow fell from $3.60 billion in fiscal 2023 to $3.24 billion in fiscal 2025, while dividends paid rose from $2.16 billion to $2.49 billion. That pushed the ratio from 58% in fiscal 2021 to a tighter 77%:
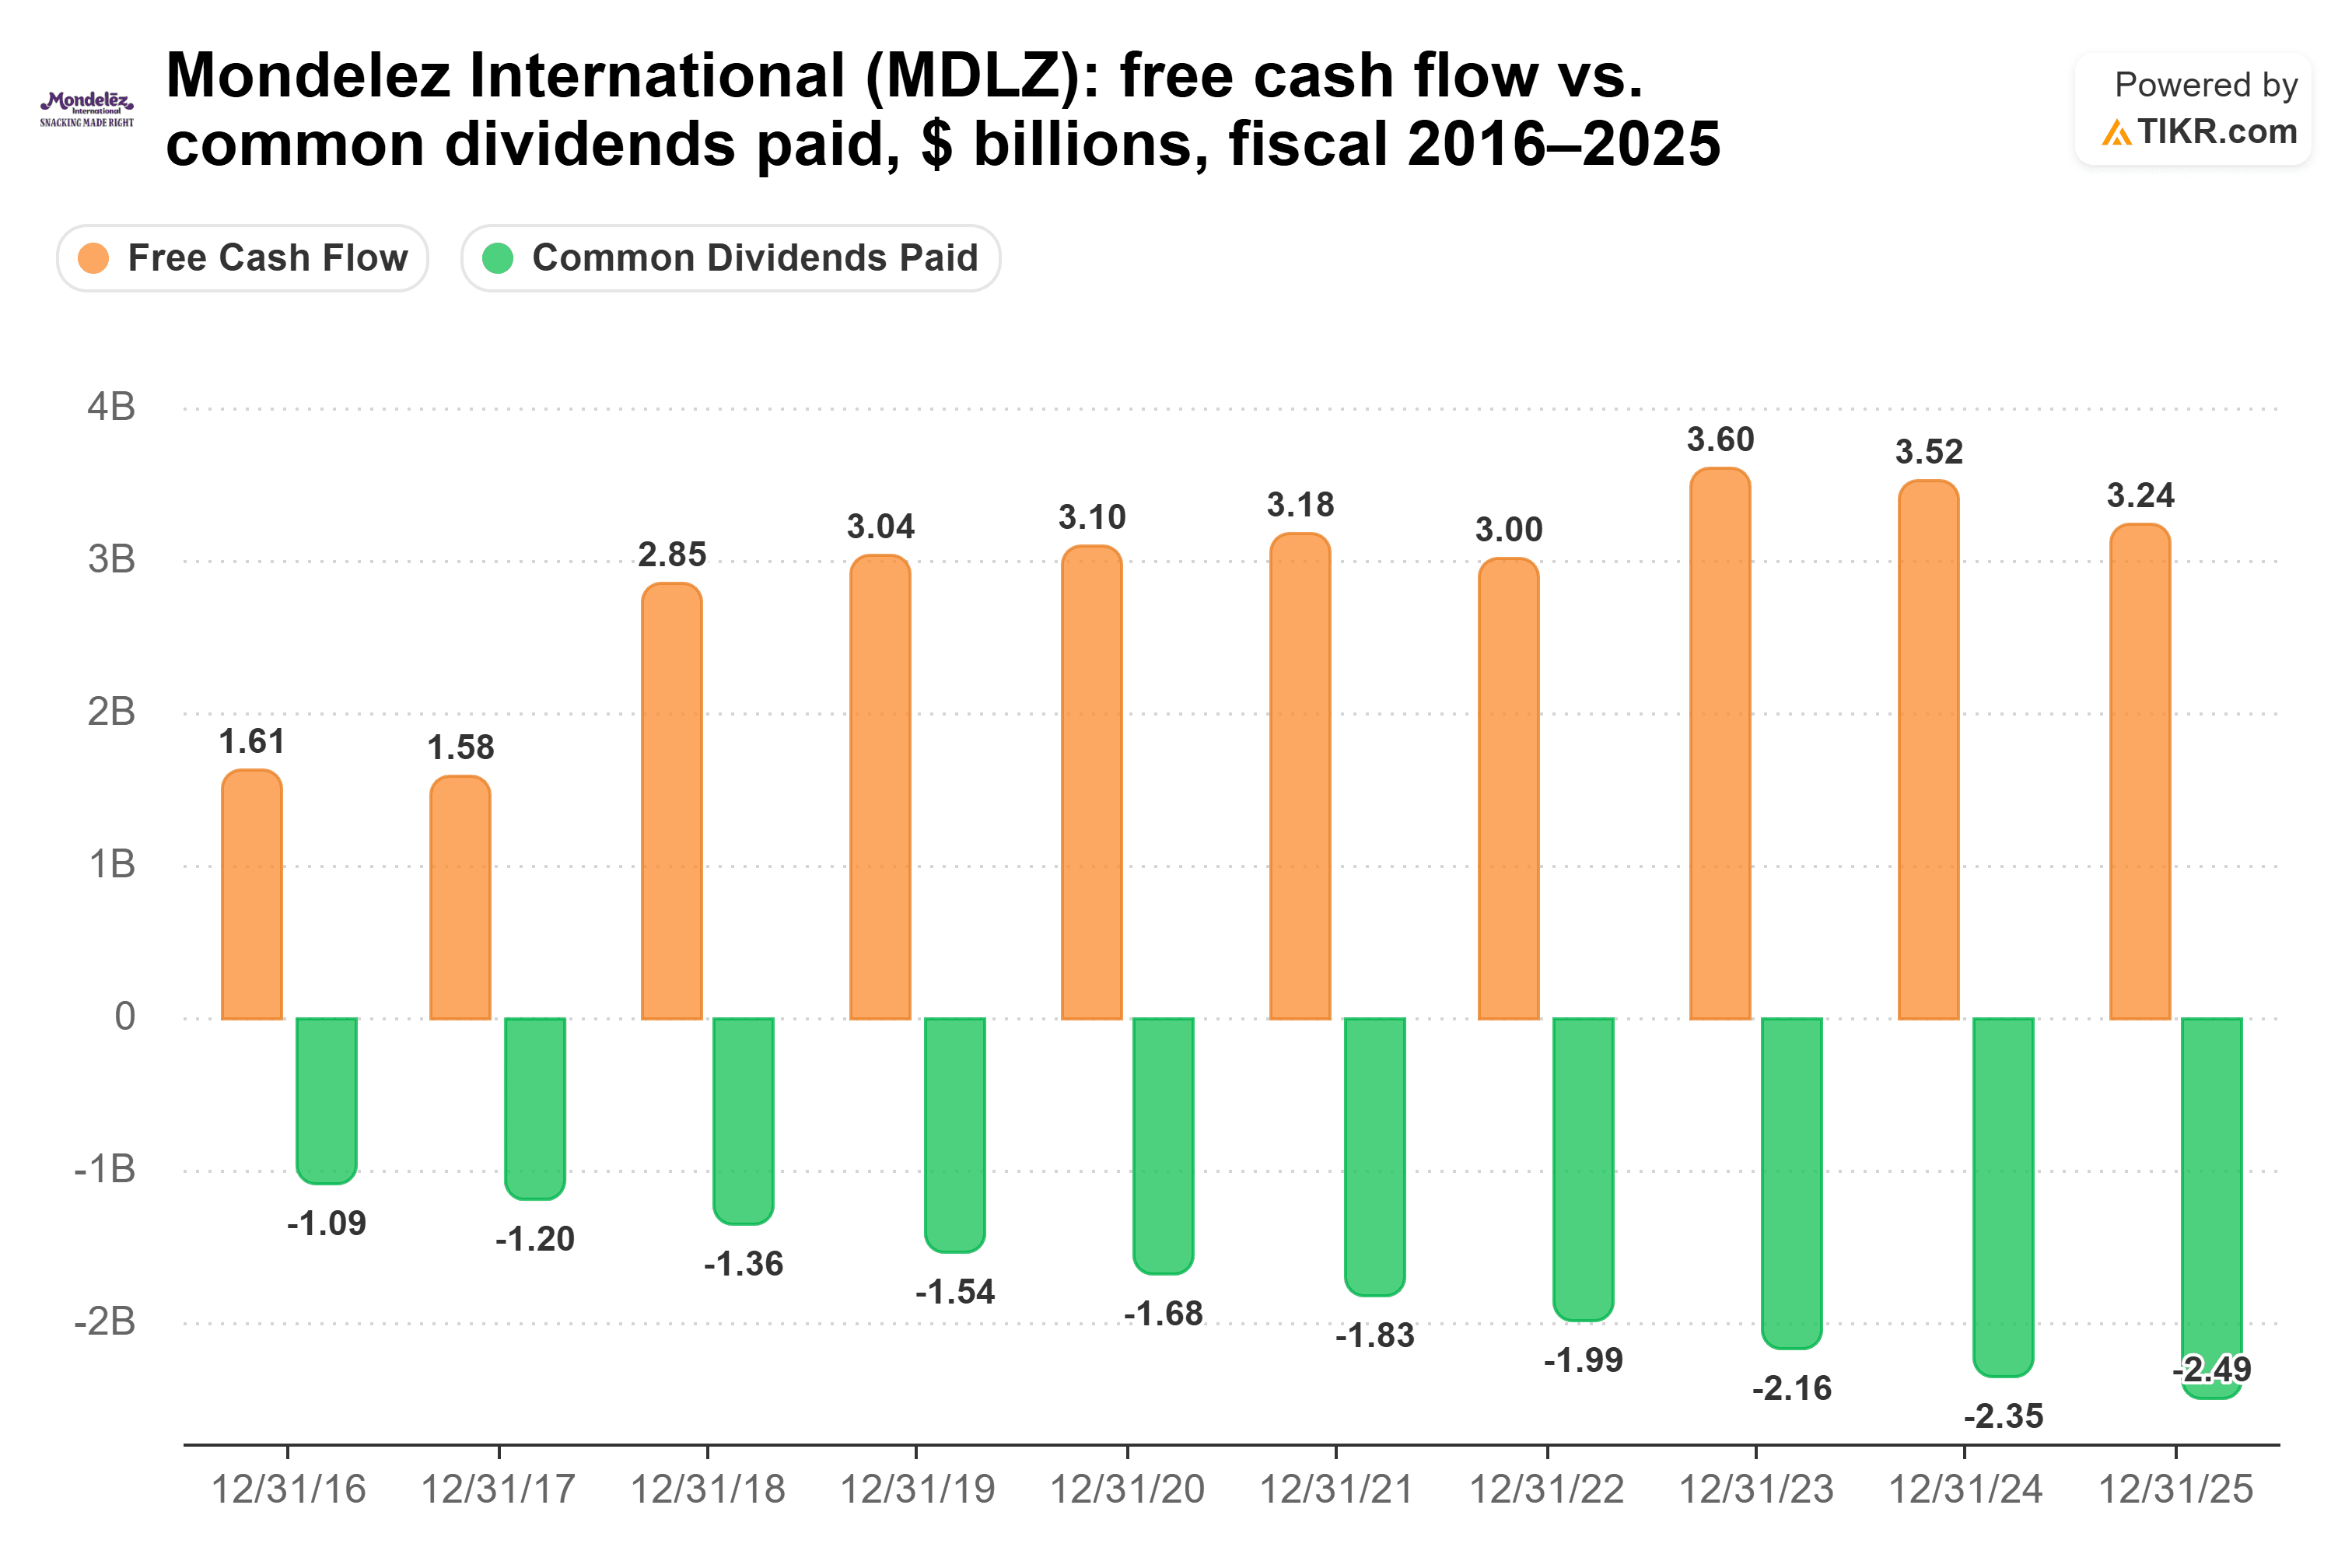
Analysts expect 74% for fiscal 2026, on $3.52 billion of free cash flow. Management’s own forecast is about $3 billion, which would leave less room. Cocoa is the other risk. CFO Amit Banati said on the third-quarter call that “the fundamentals are in a much stronger position than in the previous crisis.” But New York cocoa futures jumped 3% on Nov. 11 after Ivory Coast’s weather agency warned that a strong El Niño could cut its crop.
Eversource’s payout ratio has barely moved in a decade
Eversource’s dividend is far steadier. As a regulated utility, it borrows to build, so it’s judged on the share of normalized EPS its dividend takes. That share was 63% in fiscal 2025, against 60% in fiscal 2016. Over the same stretch, normalized EPS rose every year from $2.96 a share to $4.76, and the dividend rose from $1.78 to $3.01:
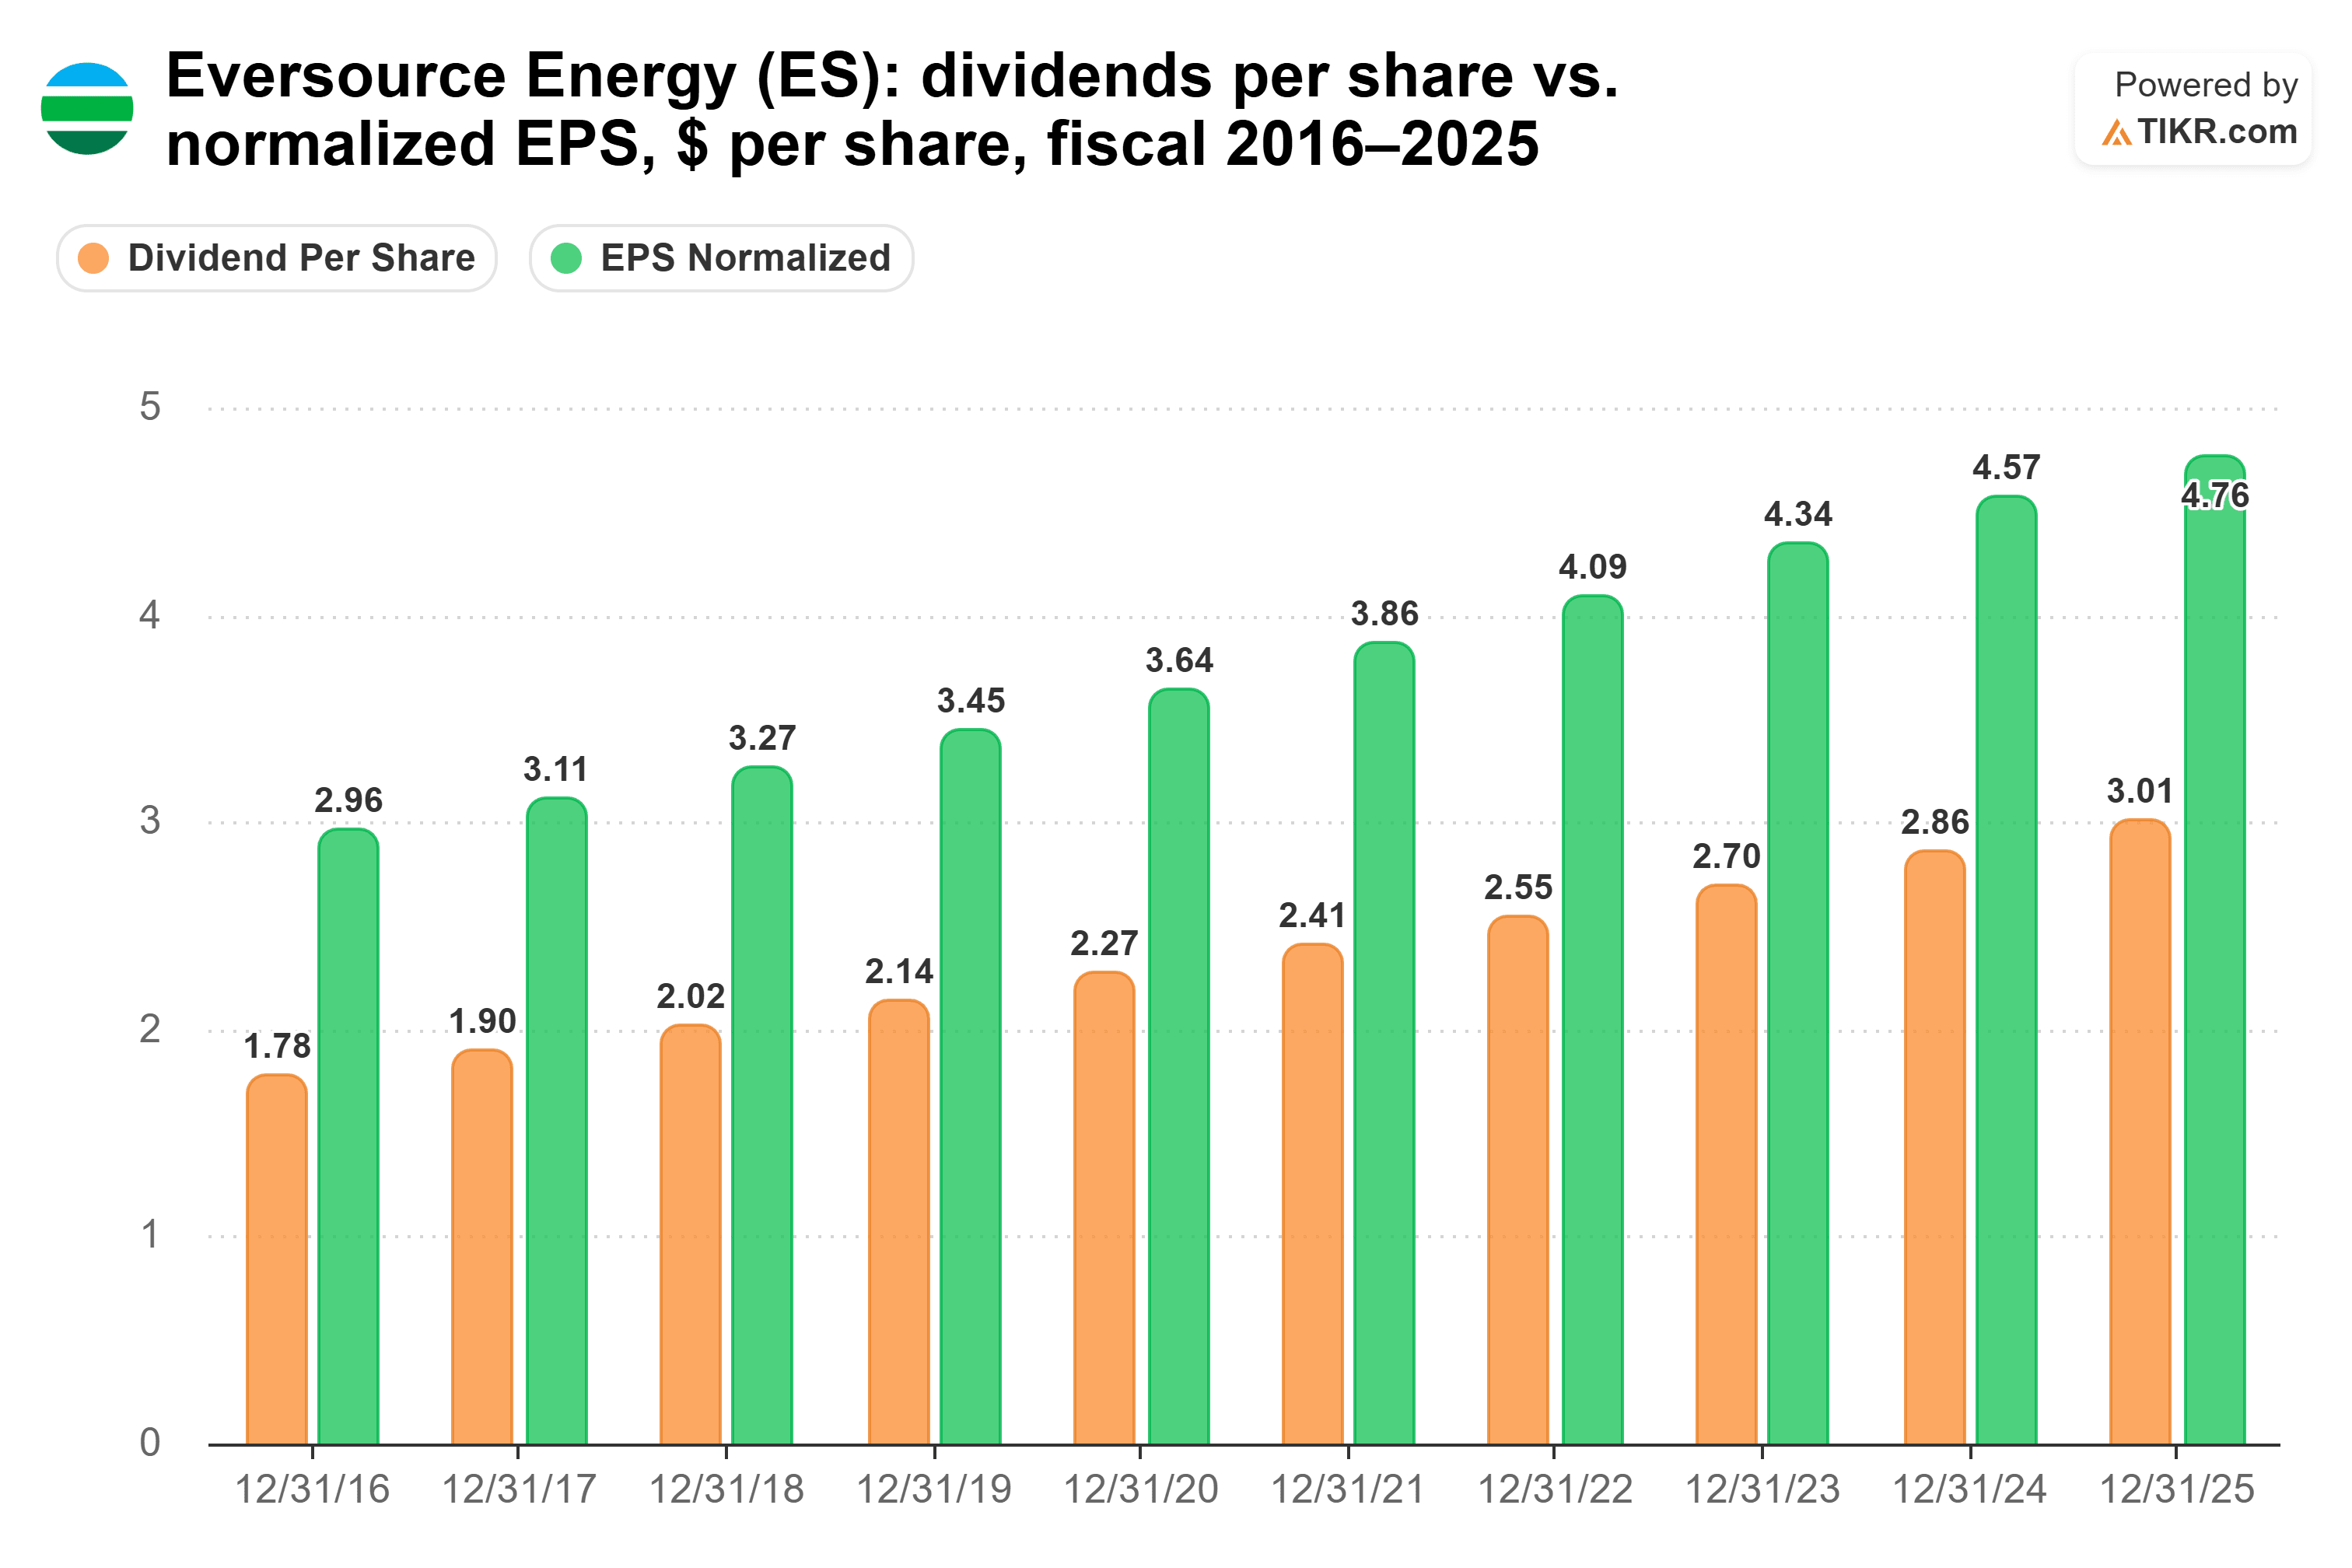
The third quarter of 2026 was a rough one. Non-GAAP earnings fell to $0.92 a share, from $1.19 a year earlier. The drop came from a lower allowed return on transmission, disallowed Connecticut storm costs and the June 30 sale of the Aquarion water business, among other items. Still, management narrowed 2026 guidance to $4.62-$4.70 a share, raising the midpoint to $4.66, and reaffirmed 5% to 7% yearly EPS growth through 2030. At the $4.66 consensus, the dividend takes 68% of fiscal 2026’s normalized EPS.
Offshore wind is less of a worry, too. CEO Joe Nolan said on the Nov. 5 call that, with Revolution Wind now fully operating, Eversource’s risk of further obligations is significantly reduced. It still has payments to settle with the buyer in 2027, and it believes its reserve is adequate. The catch is debt: Eversource carries net debt of 5.8x EBITDA and covers its interest 2.3x, against 2.6x and 10.6x at Mondelez.
So which dividend wins?
For retirees, Eversource is the better dividend stock.
It pays the bigger check today: $10,000 buys $460 a year of income, against $320 from Mondelez. At each stock’s 5-year growth rate, Mondelez’s income wouldn’t pass Eversource’s until about 2036. And that assumes Mondelez keeps raising 10.1% a year with its payout ratio already at 70%. Eversource’s 5.8% pace fits inside the 5% to 7% EPS growth management expects through 2030.
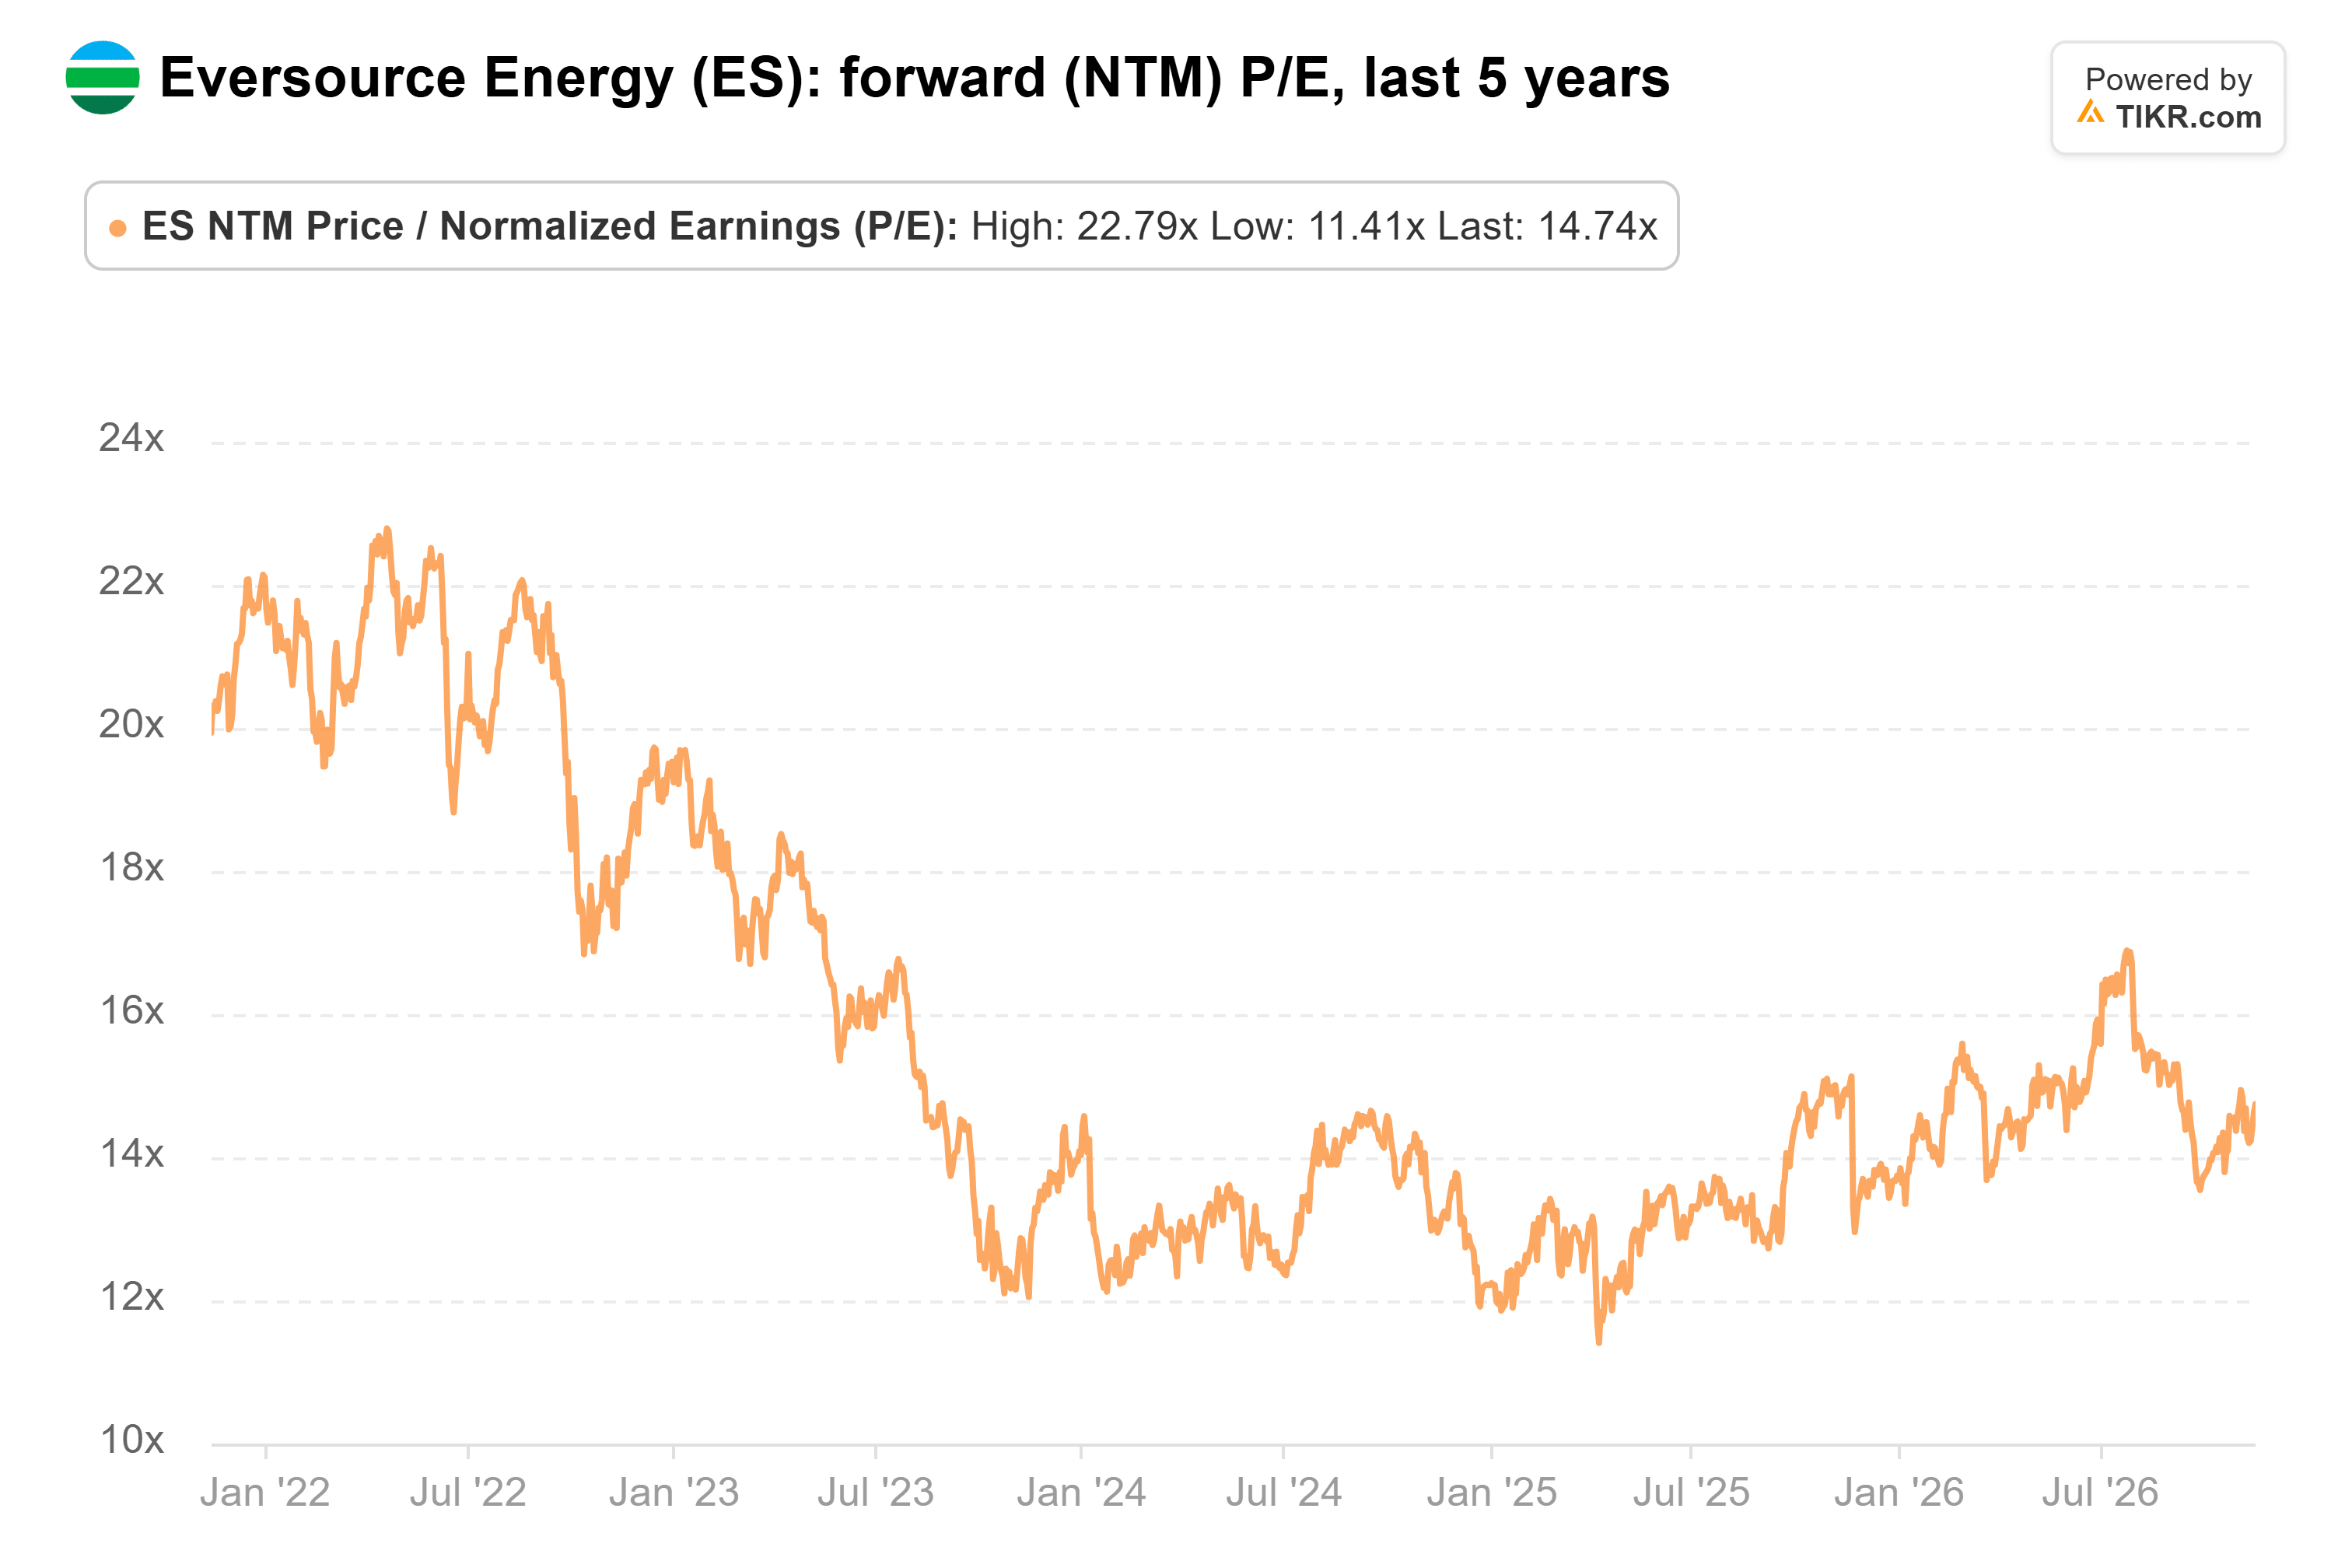
The extra income doesn’t come at a premium, either. Eversource trades at 15x forward earnings, below its 16x average over the last five years, while Mondelez trades at 20x:
Mondelez’s dividend is safe. Free cash flow still covers it, its balance sheet is far stronger, and its growth in emerging markets gives it room to keep raising. An investor with decades ahead could fairly prefer it. But a retiree is buying the check, and Eversource’s is bigger and rests on earnings that rose every year from fiscal 2016 to fiscal 2025.
The thing to watch is Connecticut. Regulators are expected to rule in June on Eversource’s first Connecticut Light & Power rate case since 2018.
Forget Eversource: 6 safe 6%+ dividend yields you can buy right now
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now. (And Eversource isn’t one of them.)
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


