Key Takeaways
- Lumentum fell 18.7% to $510 on Thursday, and Marvell’s own slide cut the all-stock deal’s value to about $601 a share from $1,132.
- Its fiscal first quarter still beat, with revenue up 136% to $1.26 billion and second-quarter guidance 8.3% above consensus.
- Lumentum trades about 15% below the deal’s current value, and analysts expect a Chinese antitrust review of 12 to 18 months.
- Lumentum’s February report and any word from Chinese regulators will show how much of the discount is deal risk.
Lumentum (LITE) shareholders were promised $1,132 a share. On Thursday the stock closed at $510.
Most of that gap traces to the buyer. On November 2, Marvell Technology (MRVL) agreed to buy Lumentum for 4.5 Marvell shares per Lumentum share, a 23.9% premium to the October 28 unaffected close. Marvell closed Thursday at $134 after a 16.4% drop, which puts the deal’s value at about $601 a share.
Lumentum trades about 15% below even that. It fell 18.7% on Thursday and 25.1% over two sessions as the Nasdaq slid into a correction.
The deal also reshapes the field for Coherent (COHR), which becomes the largest laser maker without a chip designer attached. Coherent just reported 85% datacenter growth, yet its shares fell 13% on Thursday too.
The business kept accelerating
Lumentum reported the same day the deal landed, and the quarter was strong:
- Revenue rose 136% to $1.26 billion, slightly ahead of consensus.
- Adjusted EPS of $4.57 beat the $4.19 estimate.
- Systems revenue jumped 229% to $508 million, while Components grew 99% to $754 million.
Pump lasers and optical circuit switches led the way. Lumentum also signed a second NPO/CPO contract with purchase commitments above $5 billion, and management said AI-server optical products are effectively sold out through 2029.
Systems used to be the smaller, slower side. That is changing fast:

Optical circuit switches put Systems on a much steeper curve, and that capacity is a big part of what Marvell is paying for.
Guidance says the Street is behind
Second-quarter revenue is guided to $1.575 billion to $1.625 billion. The midpoint sits 8.3% above the $1.48 billion consensus and implies about $350 million of sequential growth. Adjusted EPS should land at $5.90 to $6.20, with operating margin of 45% to 46%.
Compare that with Coherent, which posted a 23.2% adjusted operating margin last quarter. Lumentum is the smaller company, yet it turns about twice as much of each sales dollar into operating profit.
Does the gap hold on a reported basis?

Lumentum’s trailing EBIT margin of 23.4% is close to double Coherent’s 12.7%, and its guide suggests the gap is widening.
TIKR tracks 26 analysts on Lumentum. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Lumentum, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Lumentum’s Analyst Ratings
Closing is the hard part
Marvell CEO Matt Murphy framed the merger as a bet on AI shifting from copper to optical links, and the companies target more than $1 billion in annual cost synergies. Reuters Breakingviews was blunter, calling the deal “dangerously myopic.”
The timeline is long. Closing is expected in the first half of 2028, and China could take 12 to 18 months to review it. If regulators block the deal, Marvell owes Lumentum $3.2 billion. If Lumentum walks for a rival bid, it owes Marvell $2.9 billion.
On forward earnings, the past two days did real damage to the multiple:
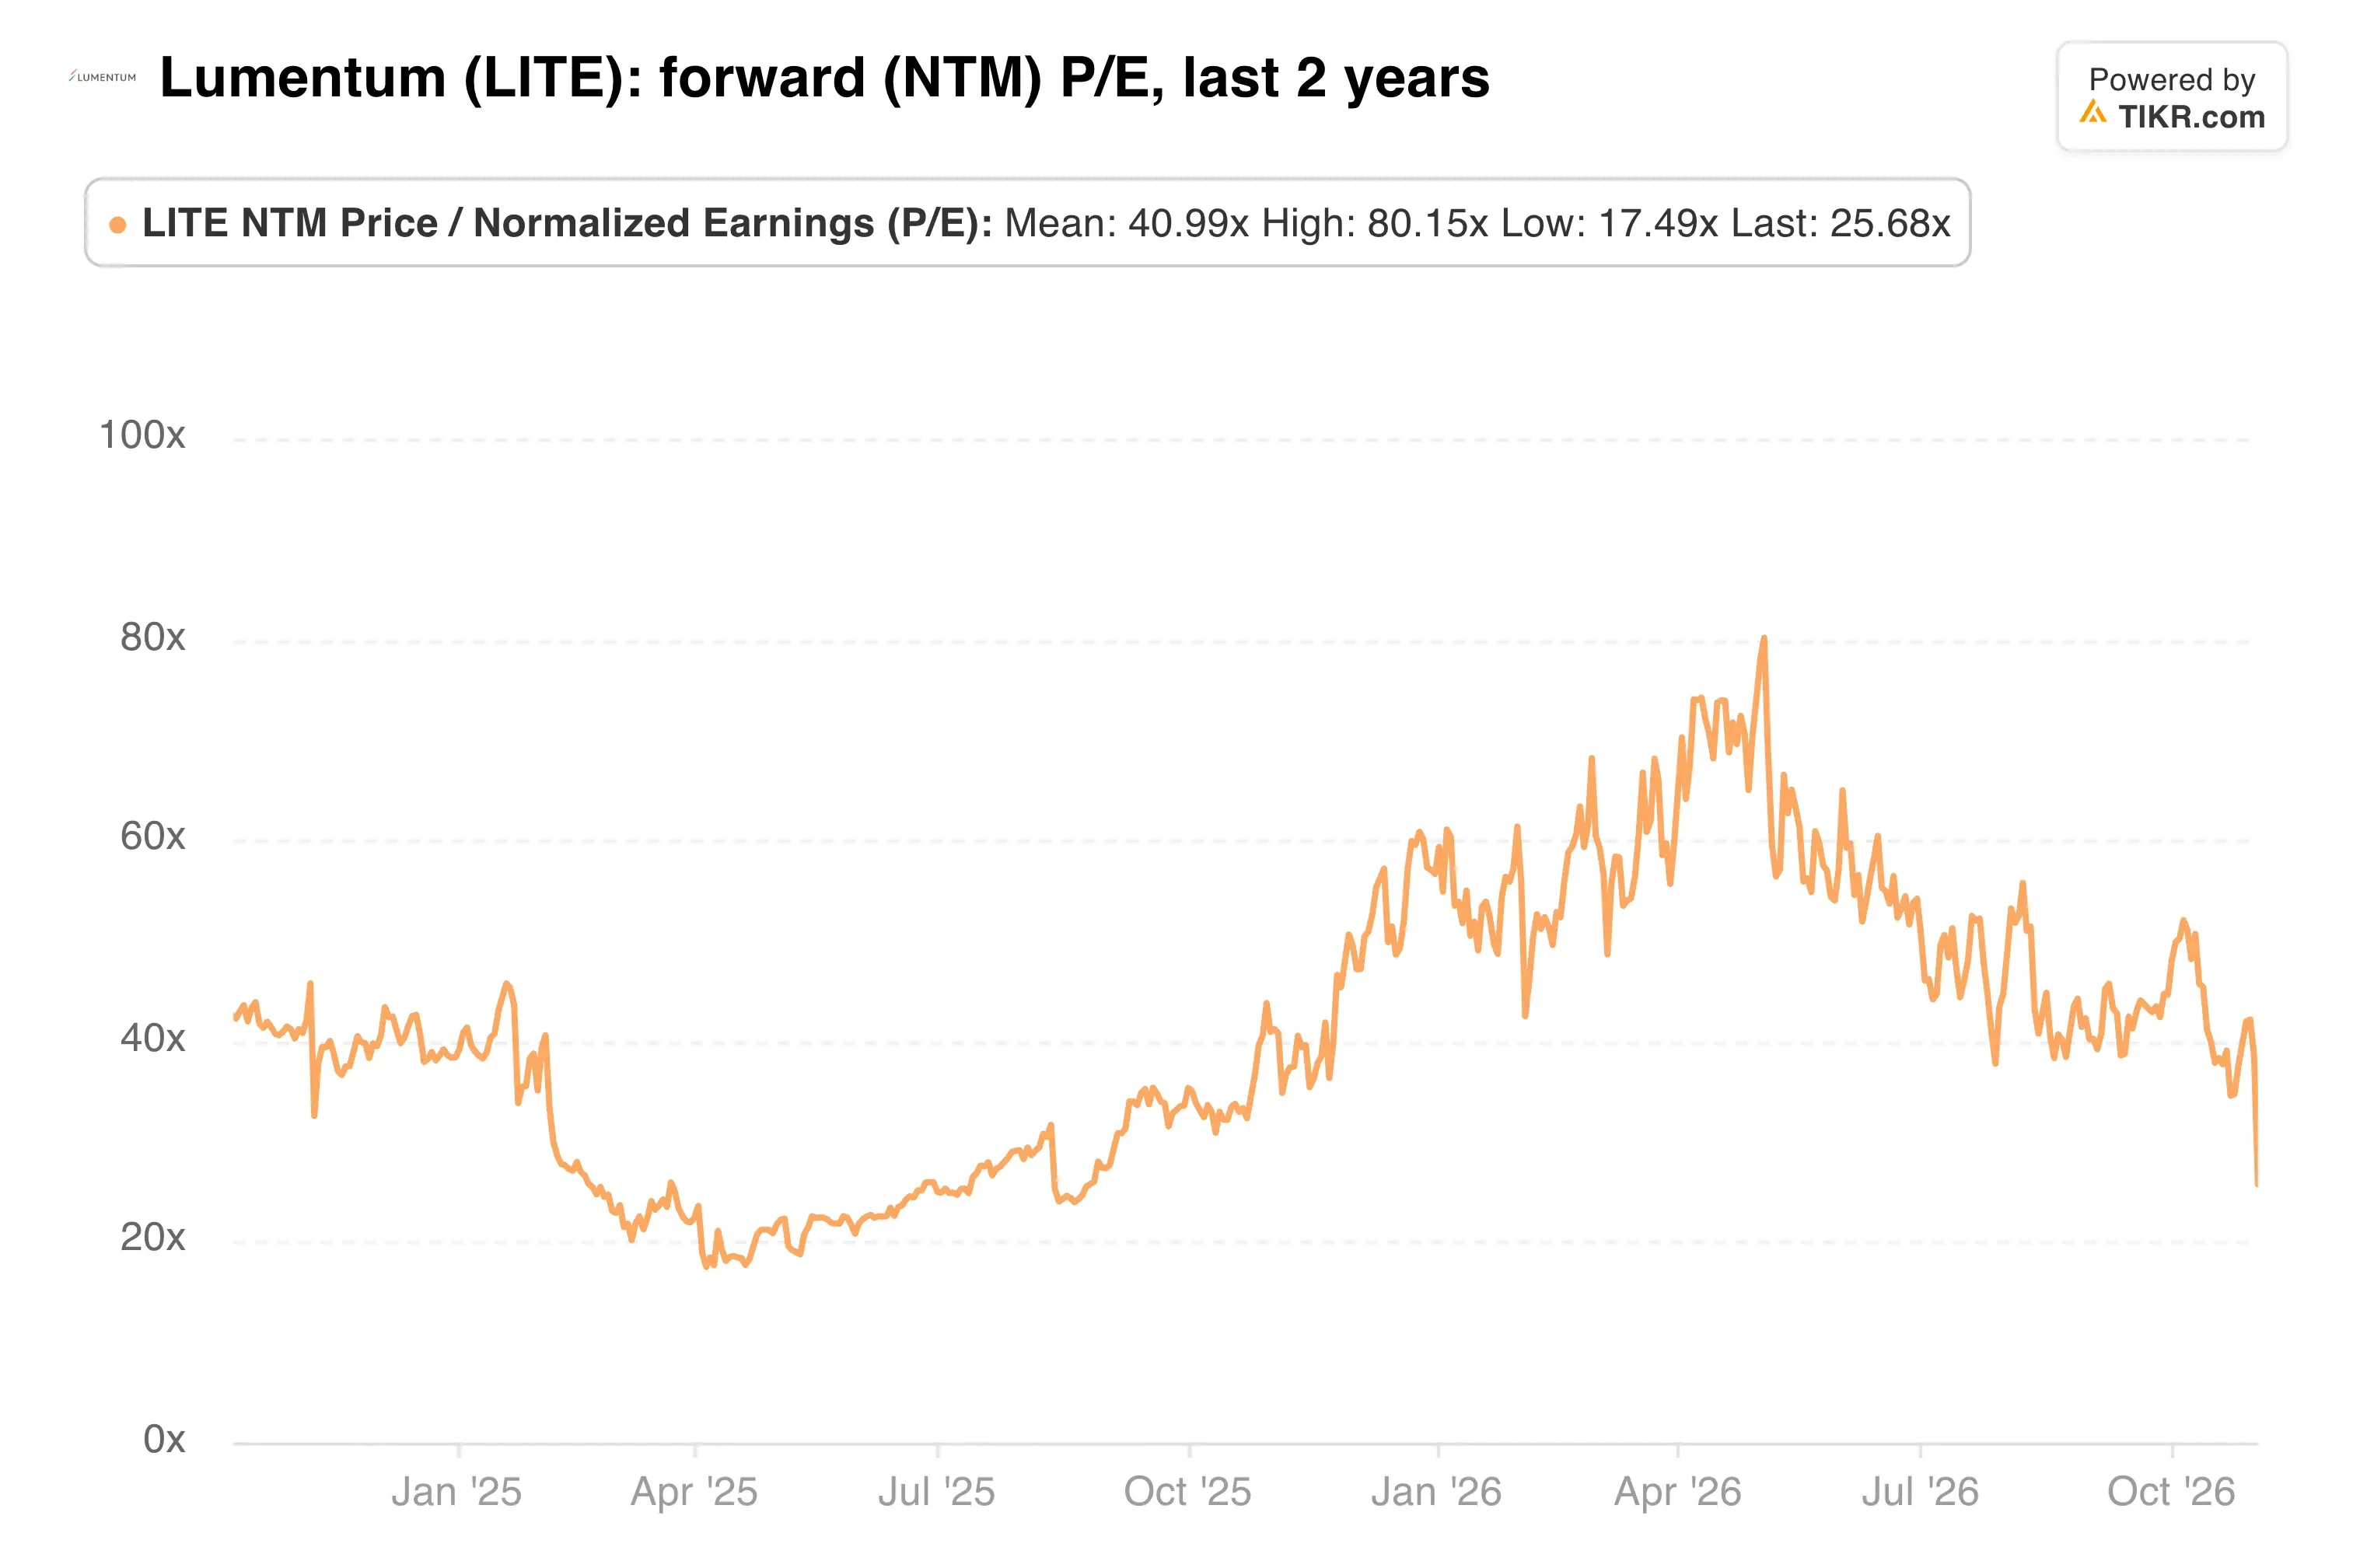
At roughly 20.9x, Lumentum now trades only slightly above Coherent’s 18.5x despite much higher margins and a signed takeover.
My take: The deal math looks far worse for Lumentum holders than it did on Sunday, and Thursday showed how fast a fixed ratio can cut. A 15% discount to Marvell’s own offer is wide for a signed deal, so plenty of regulatory doubt is already priced in. On its own guidance, about 21x for a company guiding 8% above the Street and sold out into 2029 looks cheap to me.
The risk is time. Eighteen months of Chinese review is a long stretch for a stock tied to someone else’s share price. The February report is the next test, and it will show whether the $1.6 billion guide holds while integration planning begins.
So what is Lumentum stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Lumentum could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!