Key Takeaways
- The Trade Desk fell 3.2% on Thursday to $12.81, down about a third in three months and 73% below its 52-week high.
- It guided third-quarter revenue to at least $650 million, about a 12% decline, after second-quarter growth slowed to 3%.
- Amazon grew ad revenue 26% to $19.8 billion that same quarter, more than three times Trade Desk’s $6.1 billion market value.
- The November 9 report will show whether a 15% workforce cut and CTV growth can put a floor under revenue.
The Trade Desk (TTD) can’t hold a bounce.
Shares fell 3.2% on Thursday to $12.81, giving back Wednesday’s gain as the Nasdaq dropped 5.5%. The stock is down about a third in three months. It sits 73% below its 52-week high of $48 and just 10% above its 52-week low of $11.62.
Meanwhile, Amazon (AMZN) keeps pulling ad dollars into its own ecosystem. Its advertising revenue grew 26% to $19.8 billion in the second quarter, the same quarter Trade Desk grew 3%. That single quarter of Amazon ad sales is more than three times Trade Desk’s $6.1 billion market value.
The index committee has already moved on. S&P dropped Trade Desk from the S&P 500 on September 21 and shifted it to the S&P 600.
So with the November 9 report coming Monday, is this the bottom?
Growth turned into decline
Second-quarter revenue rose 3% to $715 million, down from 19% growth a year earlier. It missed the roughly $752 million consensus, and adjusted EPS of $0.34 trailed the $0.40 estimate.
The outlook did more damage:
- Third-quarter revenue of at least $650 million, roughly 12% below last year
- Adjusted EBITDA of about $160 million, down from $241 million in the second quarter
- Analysts had expected about $804 million of third-quarter revenue
Management pointed to pressure from big consumer packaged goods and auto advertisers, plus its own execution. New CFO Nate Olmstead said the guide assumes no improvement in conditions.
Line the quarters up and the stall is plain.
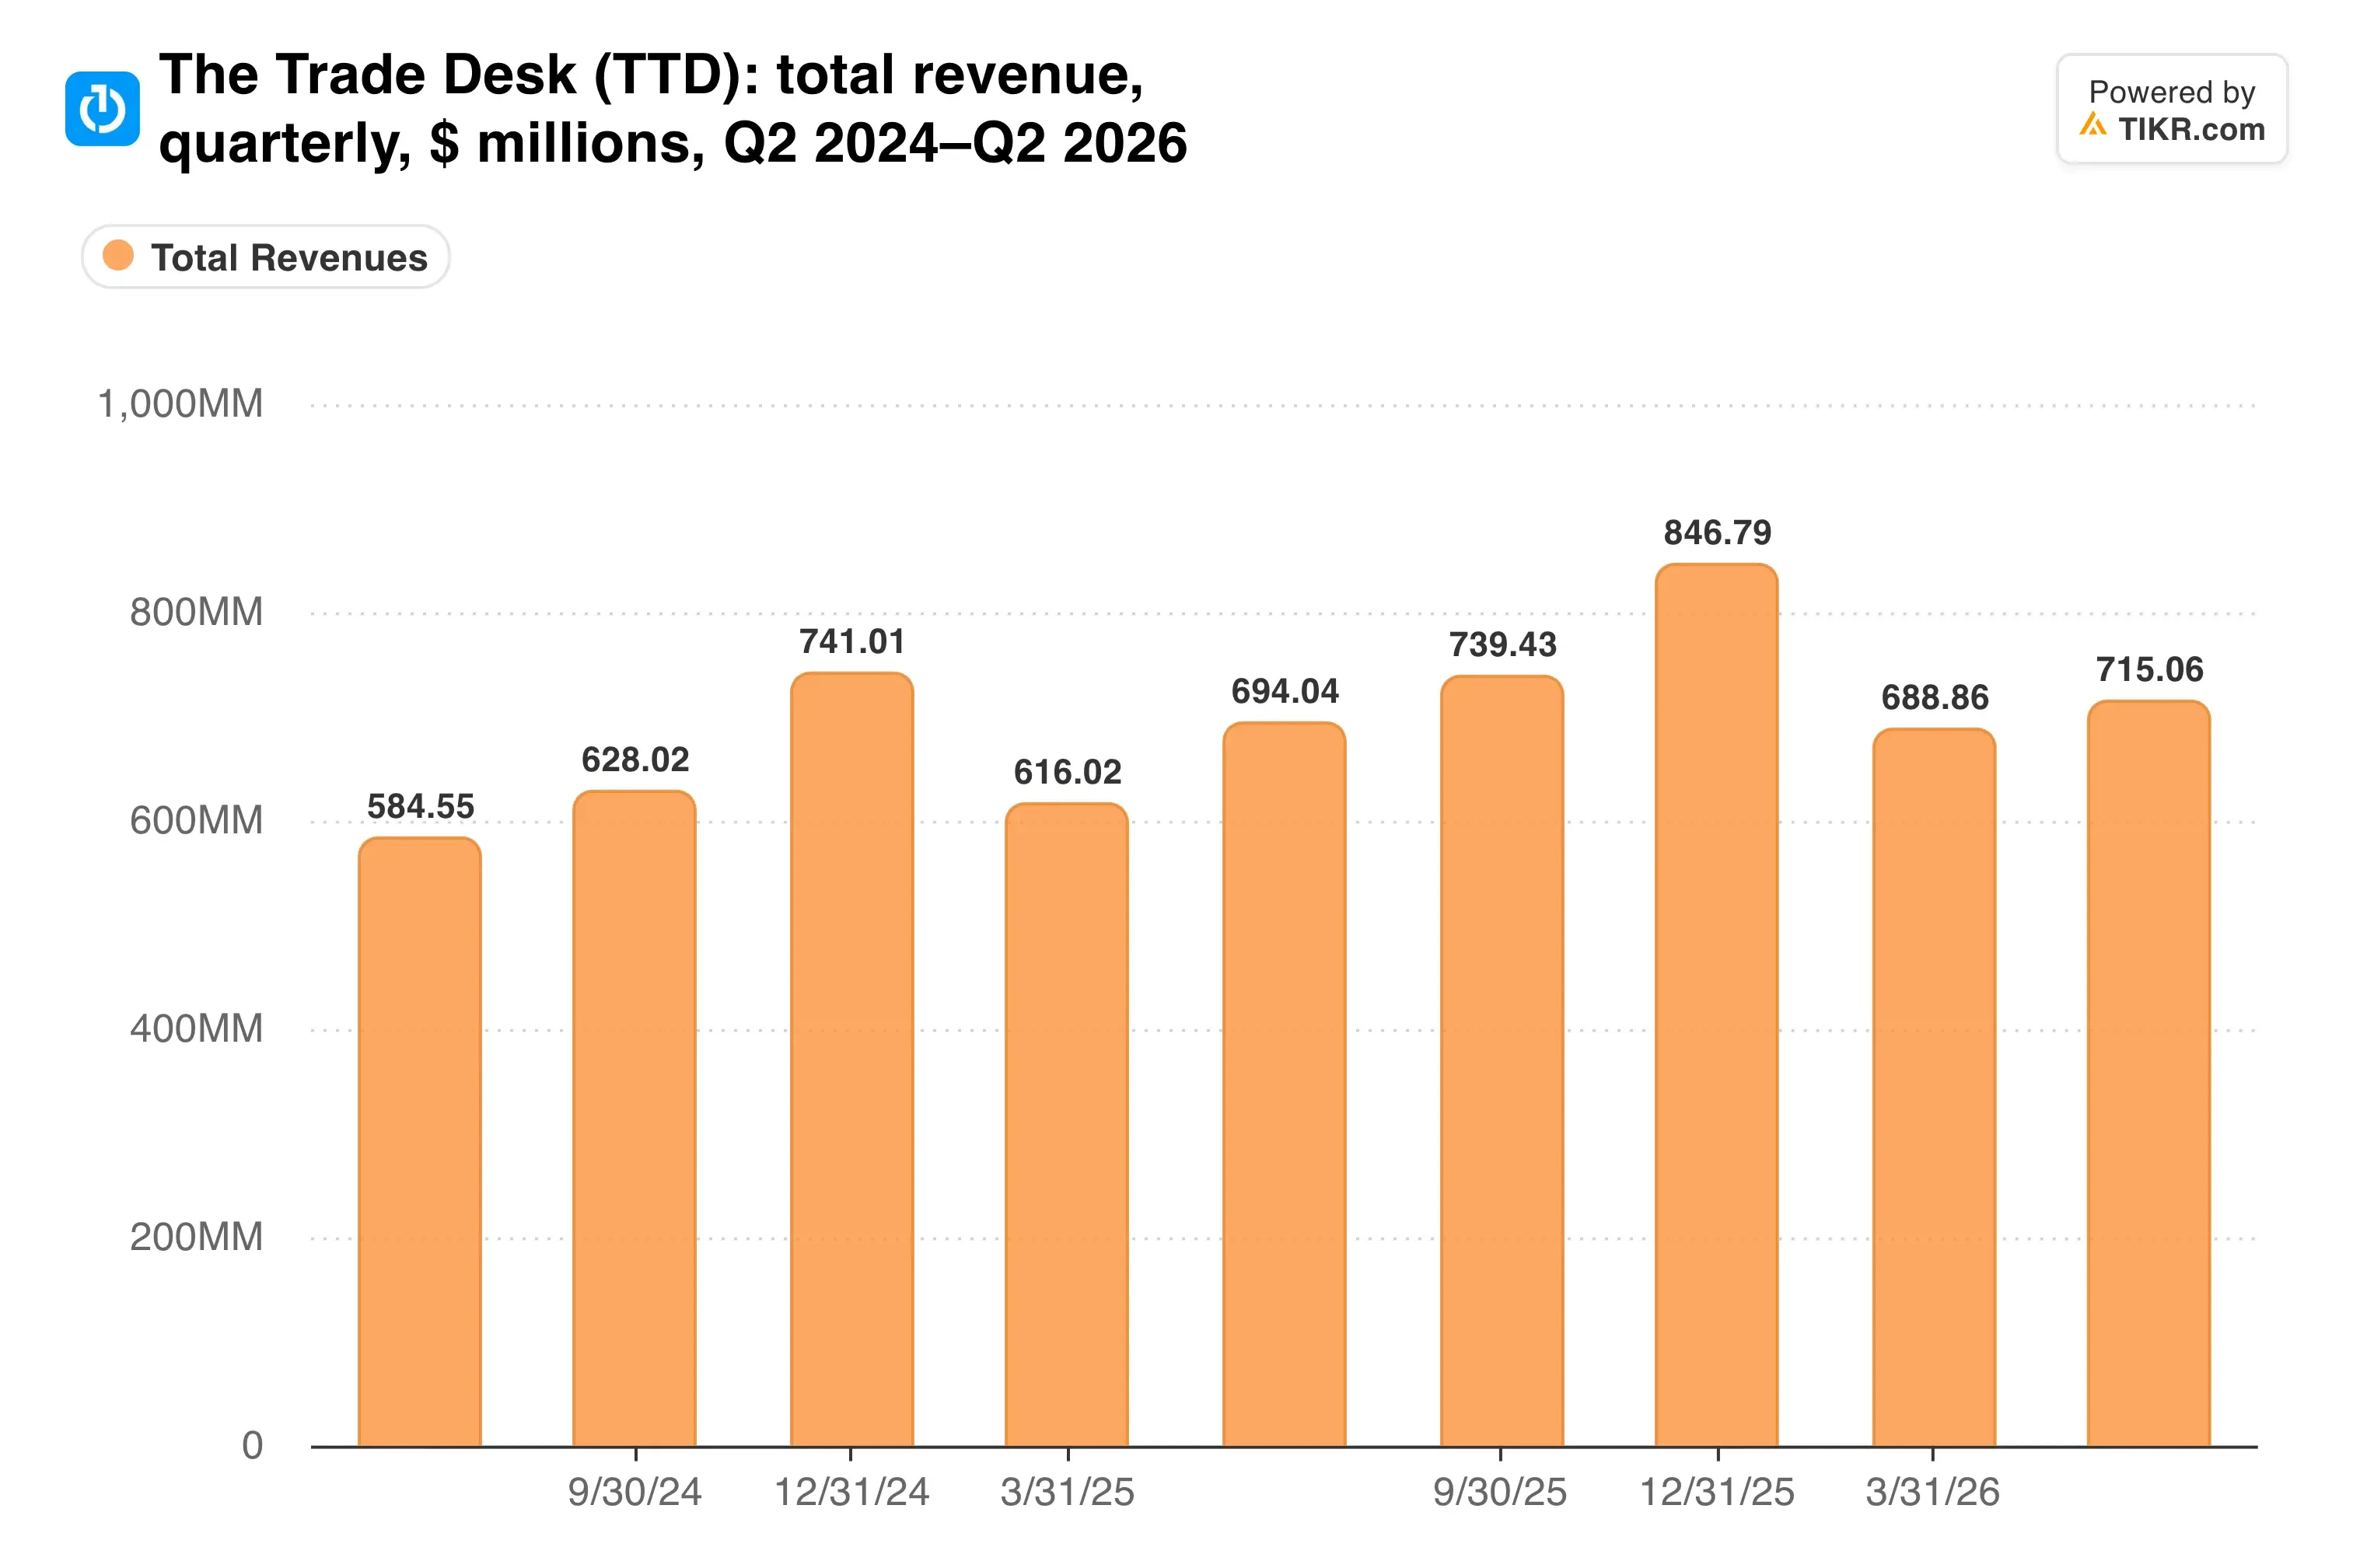
Revenue has gone sideways for a year, and the third quarter is set to break below it.
Smaller teams, same strategy
Jeff Green’s response was a 15% workforce cut, roughly 575 jobs, announced September 3. He told staff the company would run on “smaller pods and smaller scrums, but with greater focus.” Cash charges should land between $39 million and $51 million, mostly in the third quarter.
There’s still a business worth protecting. Video, including CTV, is a low-50% share of spend, and CTV grew more than 50% in both EMEA and APAC last quarter. Customer retention stayed above 95%.
The balance sheet buys time. Trade Desk held about $1.5 billion of cash and short-term investments at June 30 and spent $78 million on buybacks in the quarter.
Here’s what analysts now expect from the profit line:
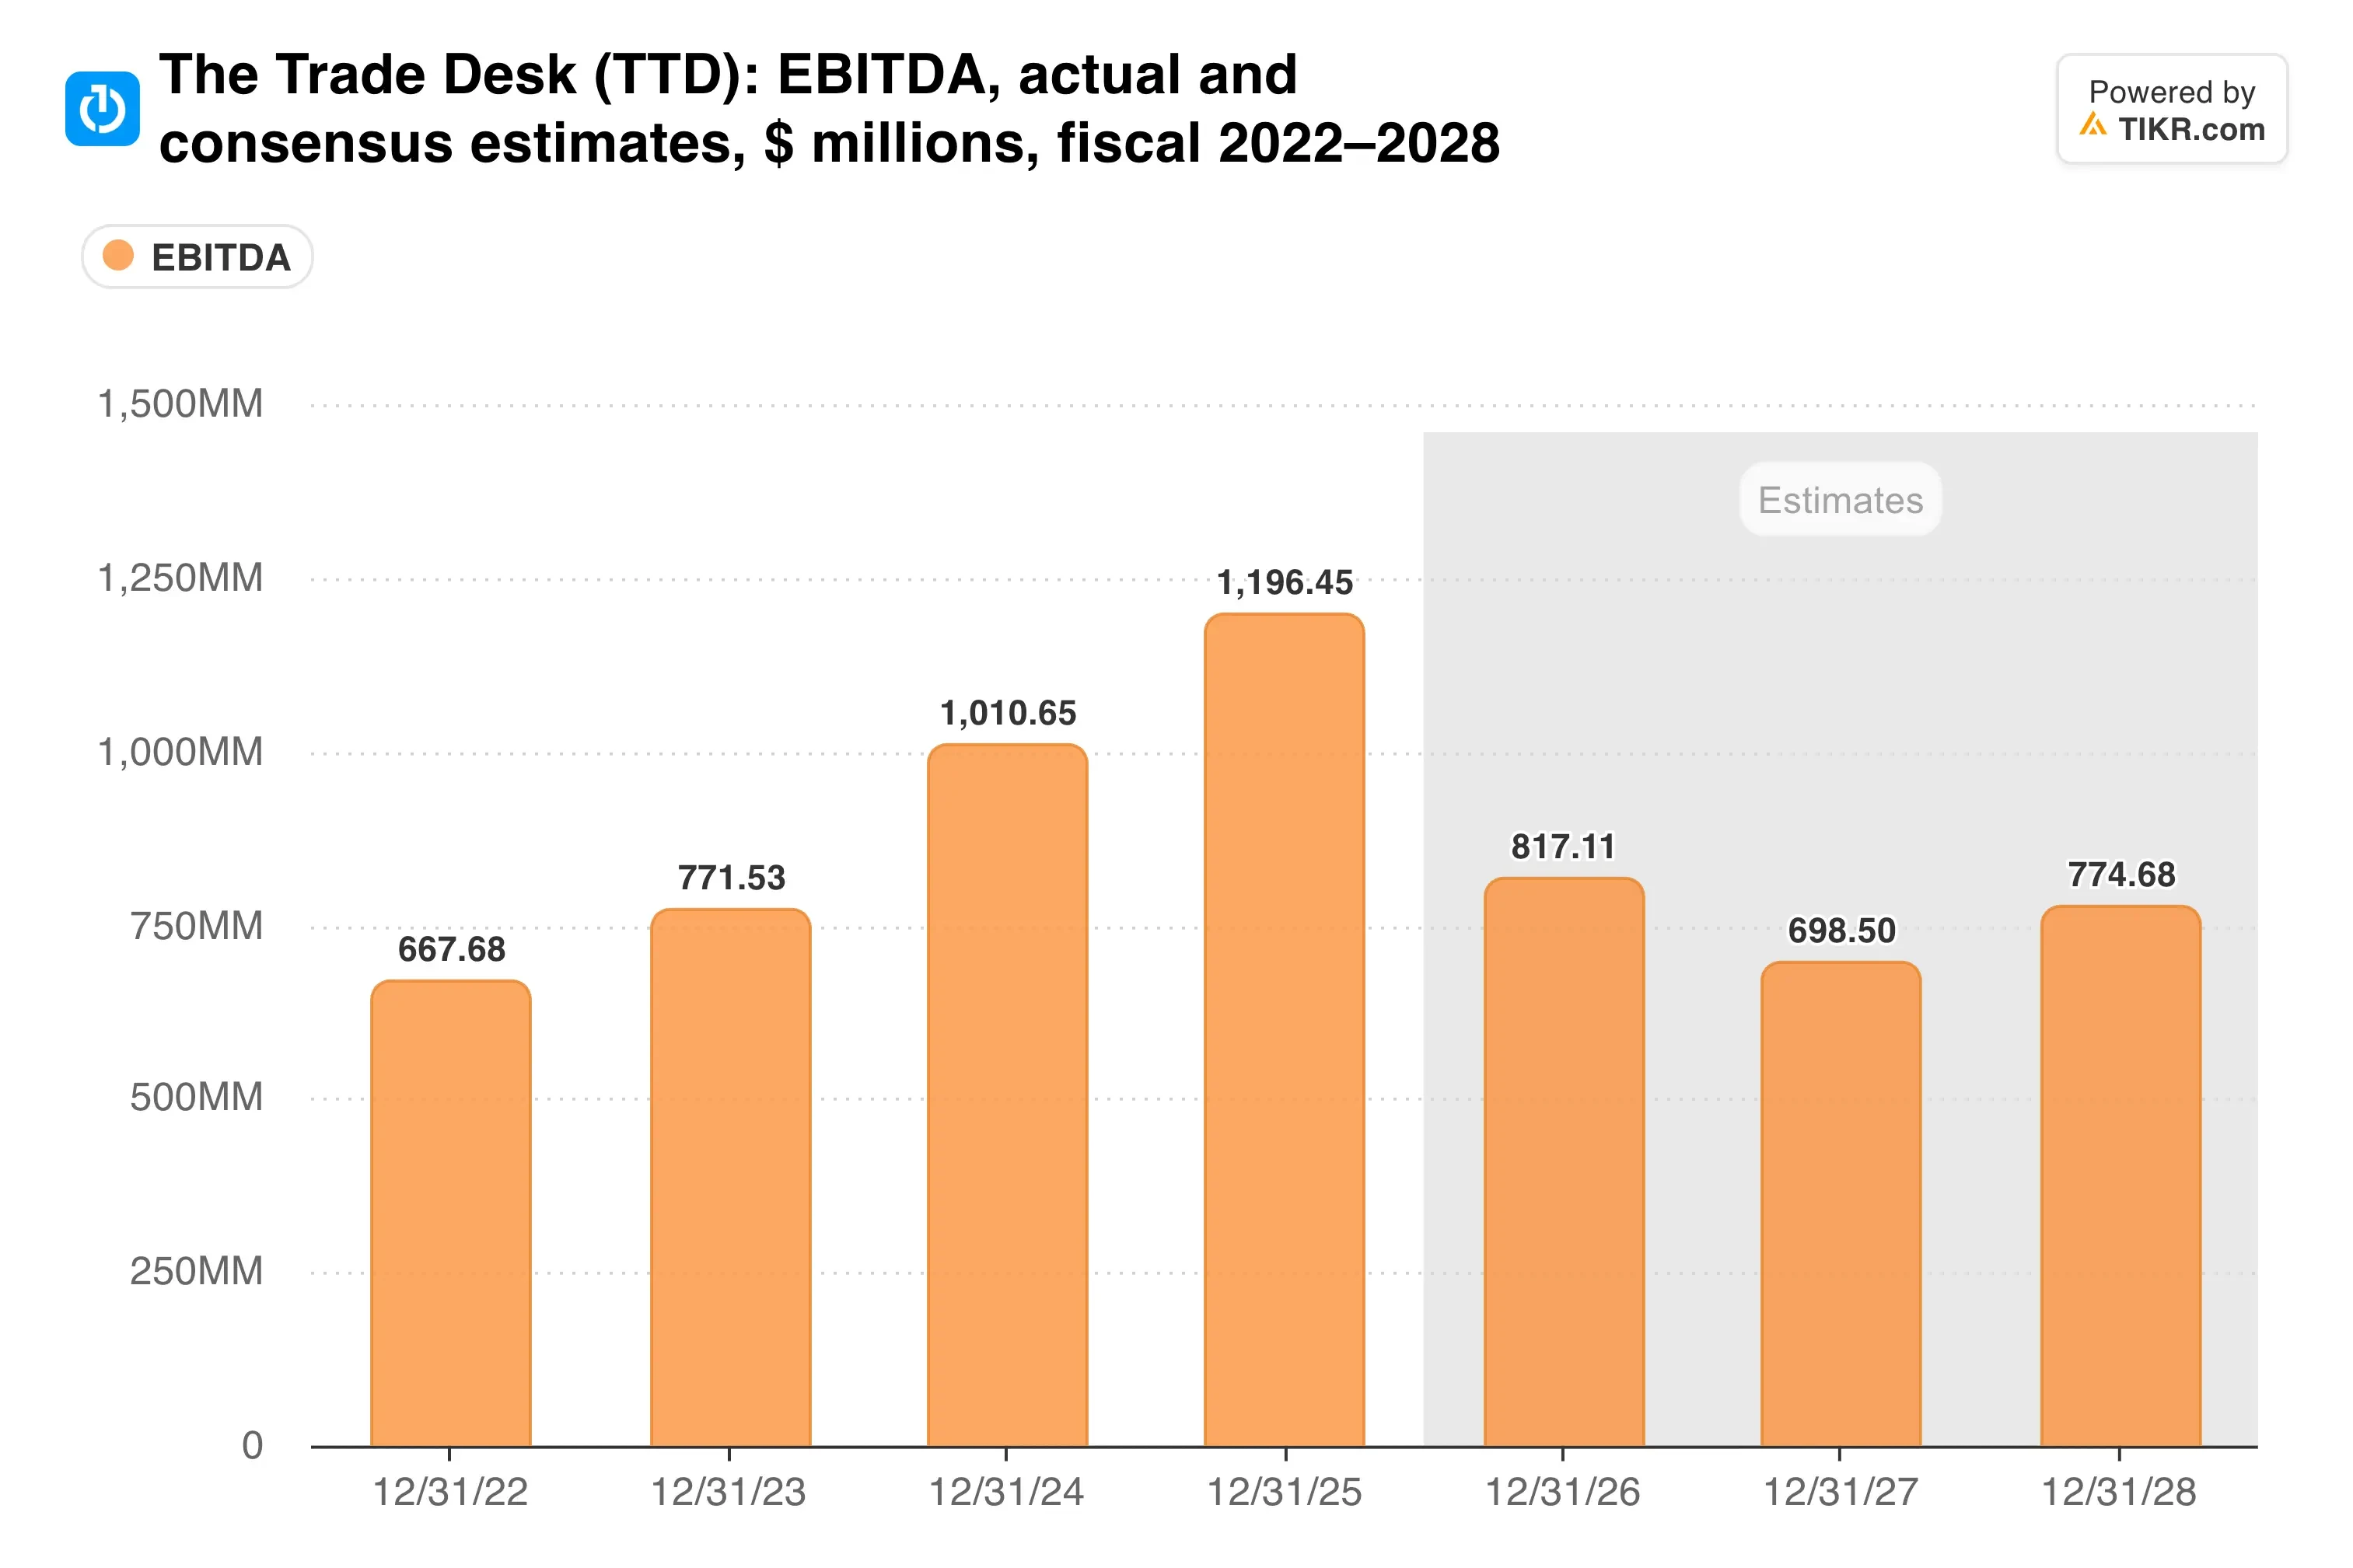
Consensus calls for EBITDA to fall about 24% a year over the next two years, with revenue down about 5% a year. The Street has finally marked its numbers down toward the guide.
TIKR tracks 36 analysts on The Trade Desk. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on The Trade Desk, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See The Trade Desk’s Analyst Ratings
Cheap, and estimates have reset
Trade Desk trades at 13.0x forward earnings and 7.5x forward EBITDA. The average analyst target of $13.53 sits just 6% above Thursday’s close.
For a former growth darling, the reset has been brutal…

The multiple has compressed, and now the estimates under it have too.
Amazon remains the bigger problem. Its DSP sits next to its own retail and Prime Video inventory, and its ad business is growing 26%. Every quarter Trade Desk shrinks, that comparison gets louder.
My take: I still wouldn’t load up before November 9. The good news is that falling estimates lower the bar, so a clean print could move the stock. But the third quarter is guided to shrink, and the stock couldn’t hold even a one-day bounce. If revenue clears $650 million and the fourth-quarter outlook stabilizes, 7.5x EBITDA starts to look interesting. Until then, I’d wait for the print.
The November 9 report should show three things: revenue against the $650 million floor, how much the job cuts save, and whether CTV growth can offset weaker brand budgets.
So what is The Trade Desk stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what The Trade Desk could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!