Key Takeaways
- Accenture (ACN) stock is up 37% in the past month but still up 2% in 2026.
- Even after the rally, Accenture still looks cheap against its own history, at 18x forward earnings against a 10-year average of 24x.
- At that average multiple, today’s price would need forward earnings about 22% below what Accenture earned in fiscal 2026, while analysts expect growth in each of the next two years.
- AI pricing pressure is the main risk to watch, though free cash flow reached $11.6 billion in fiscal 2026, its highest in a decade.
Accenture is up 37% in the past month, and it still hasn’t made it back to where it started the year. The stock is up only 2% in 2026.
That says a lot about how bad the first half was. The shares lost about half their value between January and July, as investors worried that AI tools would eat into the consulting and outsourcing work Accenture sells.
Investors have been warming up to the stock since Oct. 1. That day, Accenture reported fiscal Q4 revenue of $18.7 billion, up 7% in local currency and above the top of its own guidance. It also guided to 3% to 6% revenue growth in fiscal 2027, with about $5 billion set aside for acquisitions.
The run has since carried the stock past most of the Street’s recent targets. Wells Fargo and Robert W. Baird both rate it Hold with $252 targets, set in late October. Of the latest calls, only UBS, at Buy with a $300 target, sits above the last close.
The earnings keep climbing
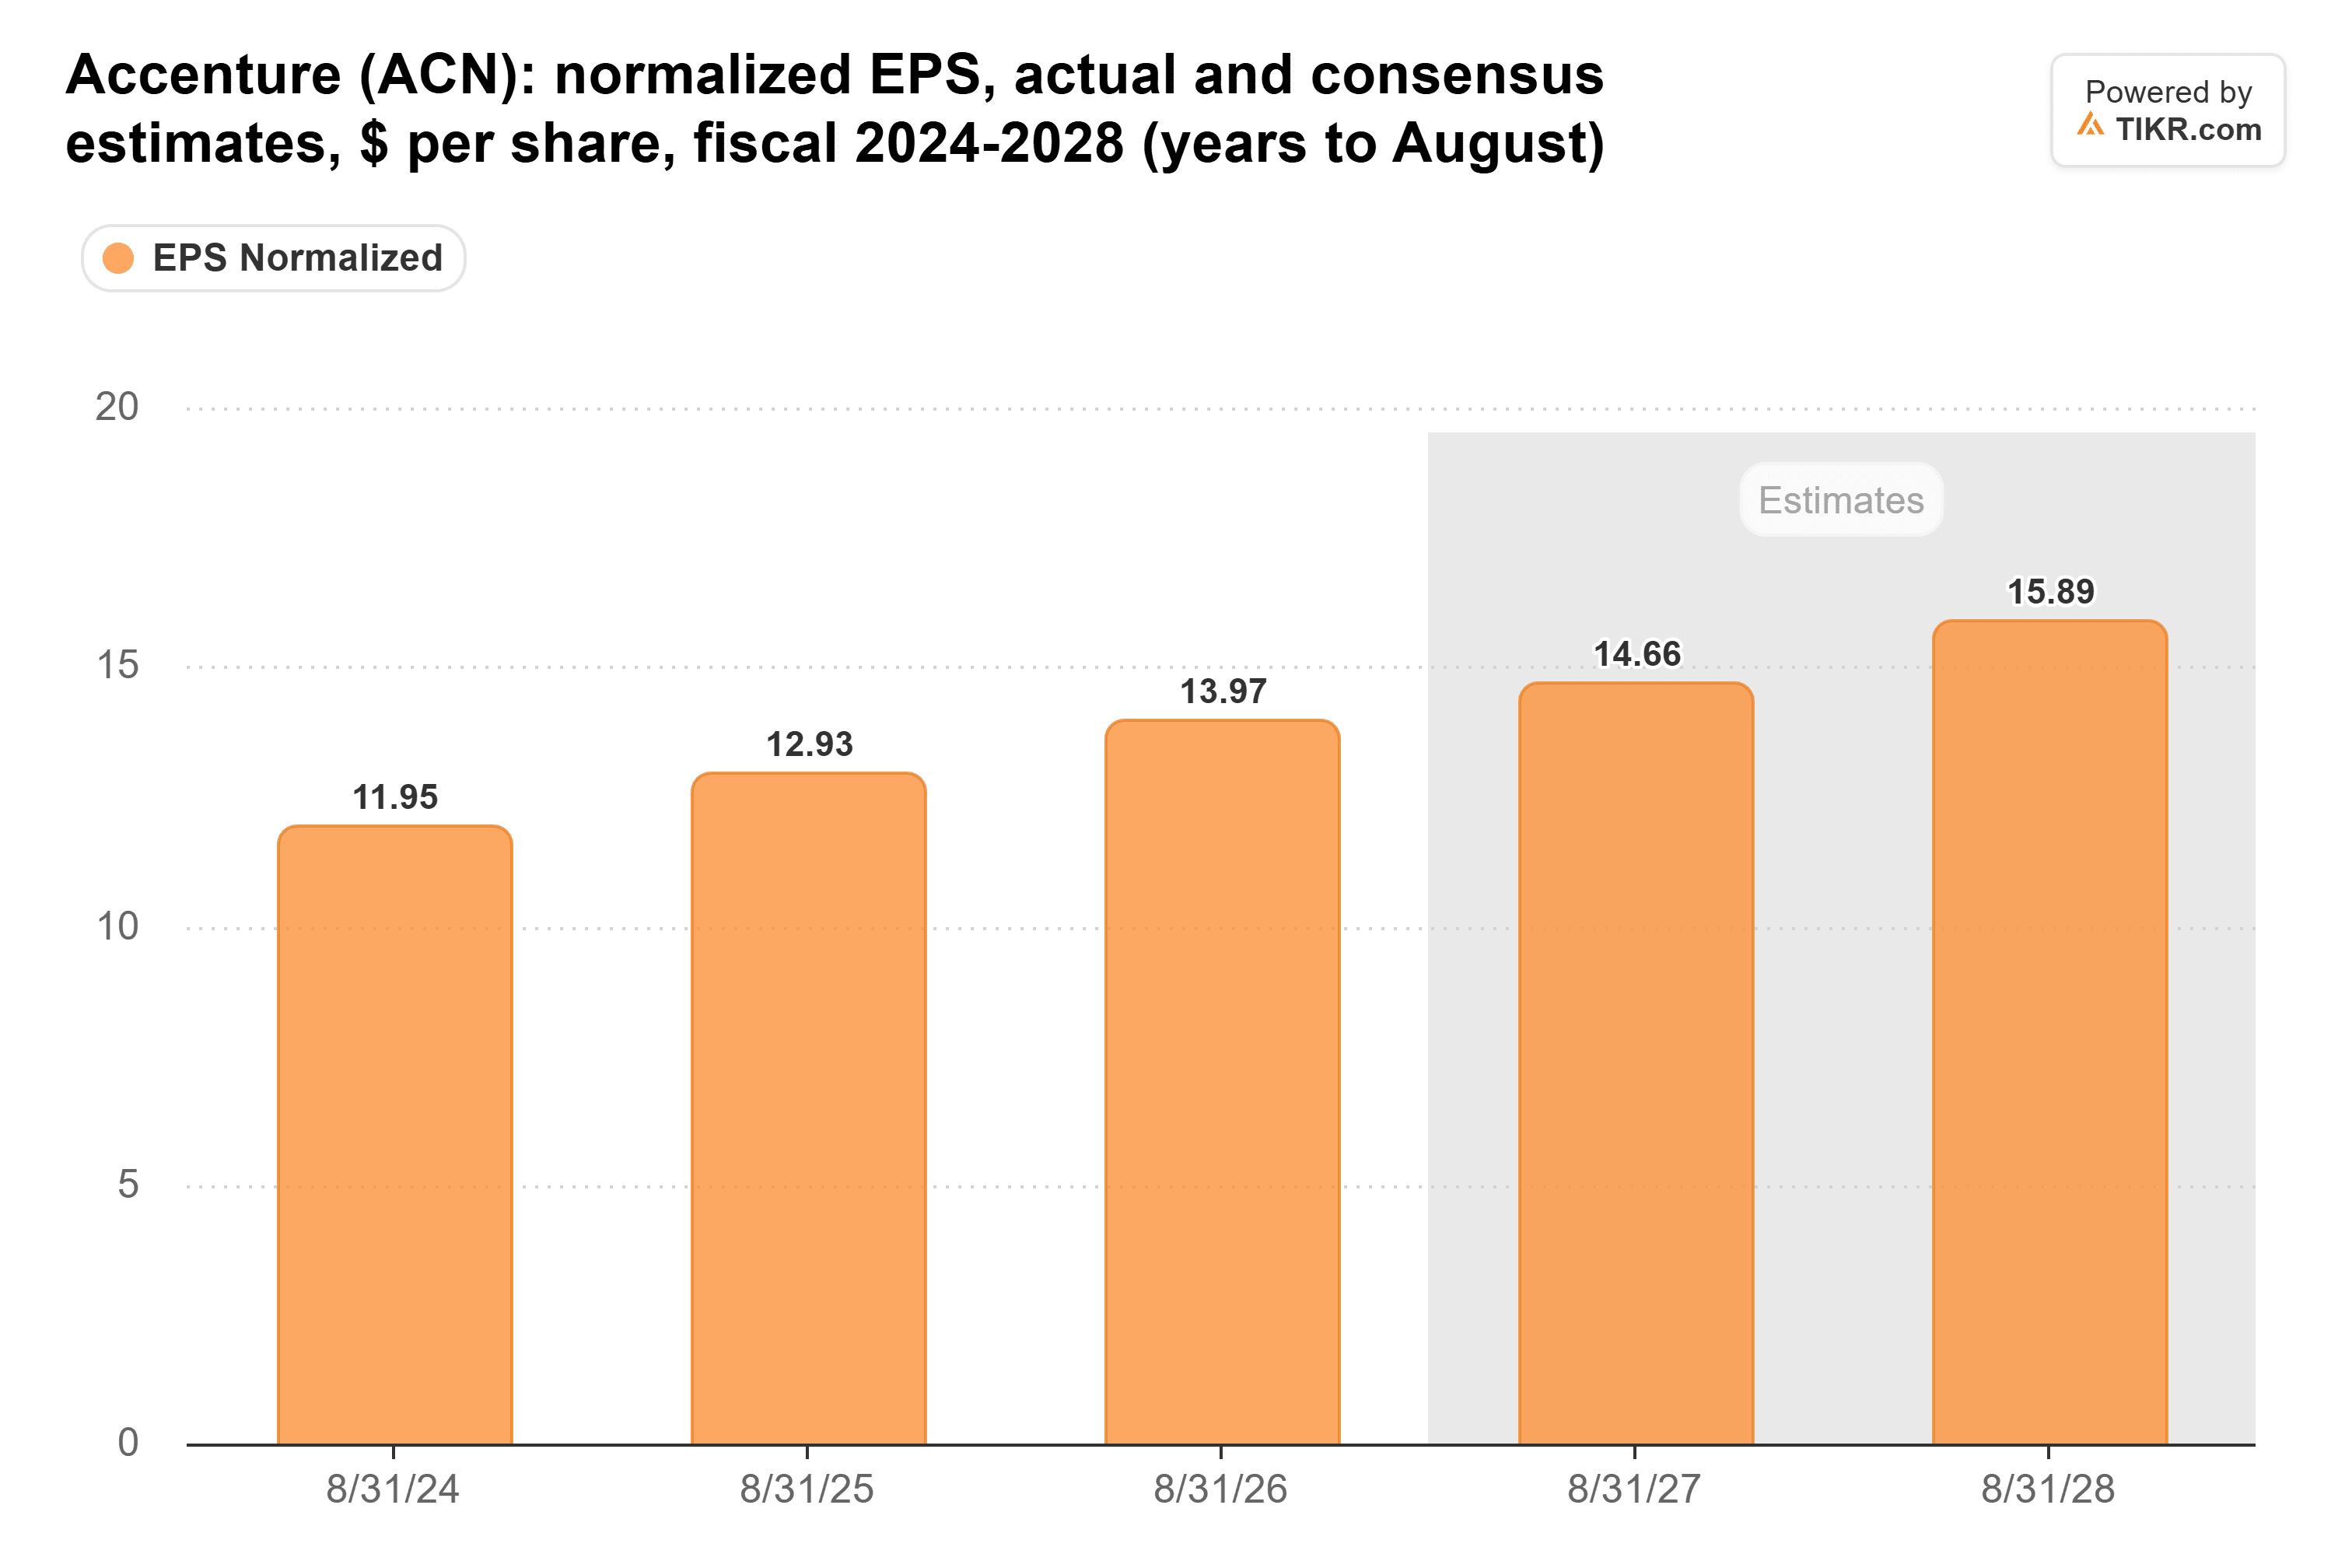
Accenture’s normalized EPS grew 8% in each of fiscal 2025 and fiscal 2026 (its year ends in August), reaching $13.97. Analysts expect 5% growth in fiscal 2027 and 8% in fiscal 2028:
The multiple hasn’t caught up
Despite the rally, Accenture trades at about 18x forward earnings. That’s well below its 10-year average of 24x and nowhere near its 38x peak in late 2021:

At that 24x average, today’s price would need only about $10.80 a share of earnings over the next year. That’s 22% less than the $13.97 Accenture earned in fiscal 2026.
Analysts expect $14.66 for fiscal 2027.
TIKR tracks 30 analysts on Accenture. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Accenture, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Accenture’s Analyst Ratings
AI hasn’t dented the cash yet
Some of the discount is fair. On its fiscal Q4 call, Accenture said pricing was lower in many areas of the business as AI lets it pass more productivity gains on to clients.
If AI keeps cutting the hours clients pay for, 24x may not be the right benchmark anymore.
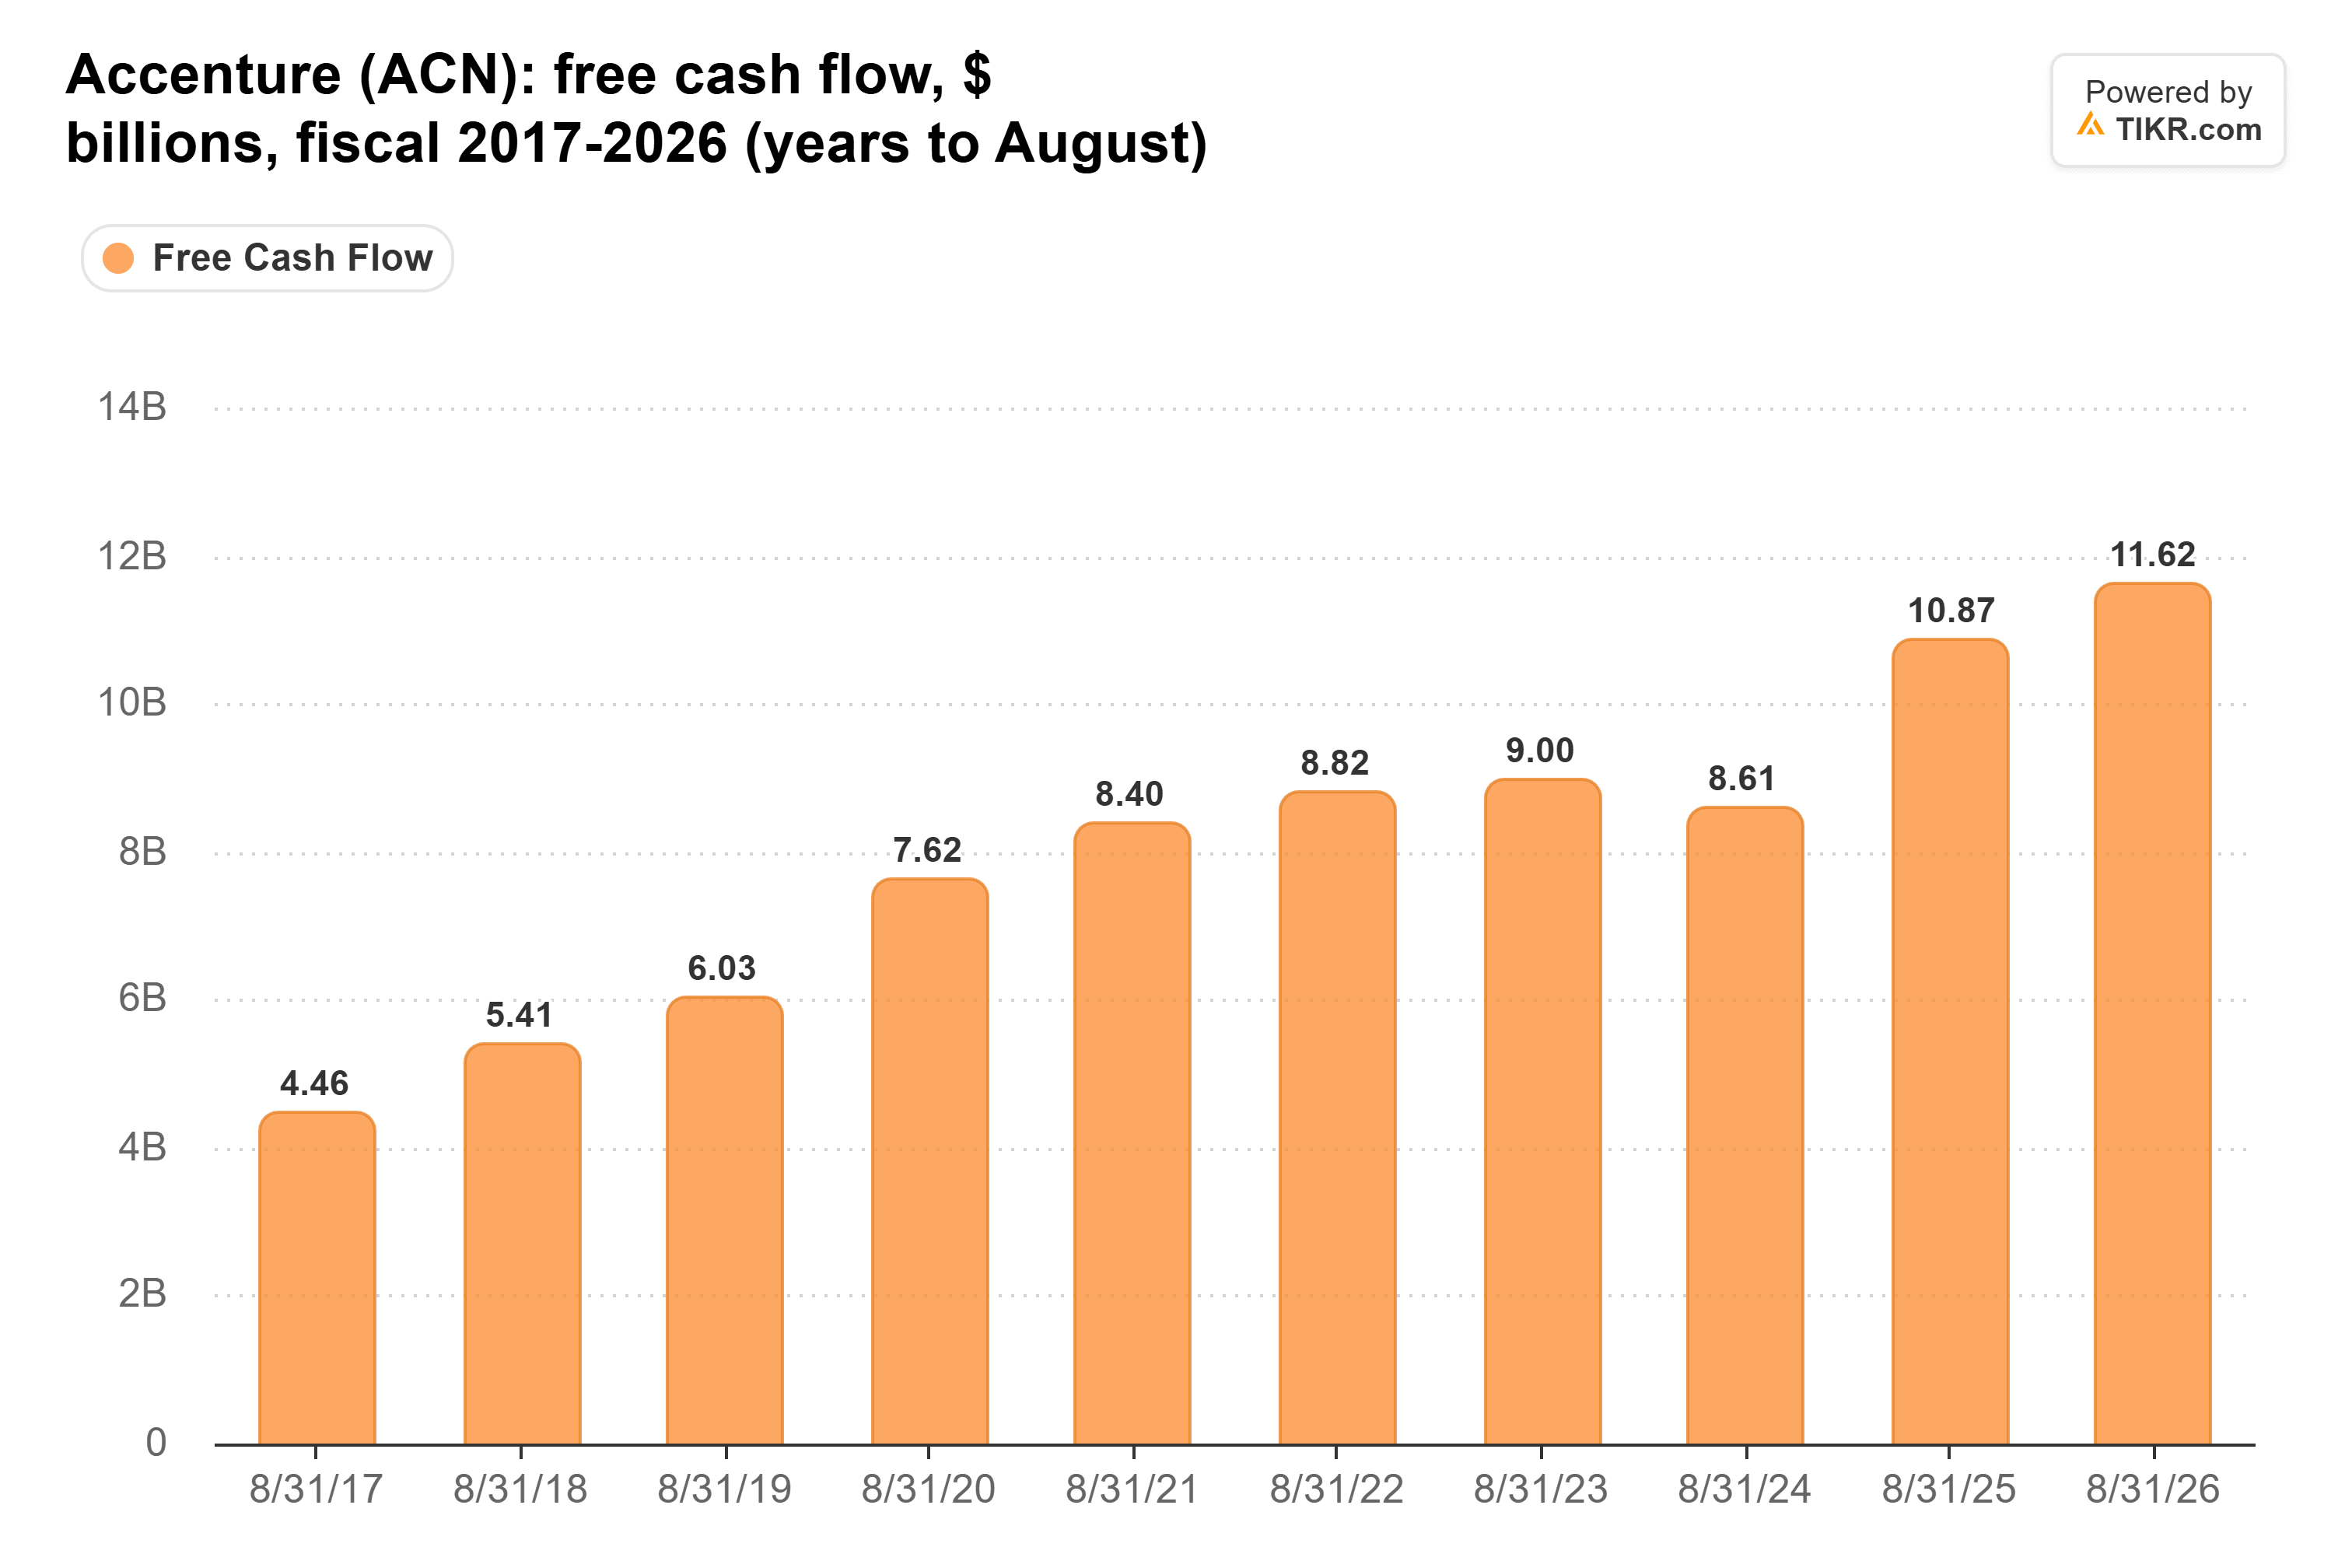
So far, though, the cash keeps coming in. Free cash flow more than doubled from $4.46 billion in fiscal 2017 to $11.6 billion in fiscal 2026, with one dip in fiscal 2024:
Still cheap, with a catch
Accenture still looks cheap to me. At 18x, the market is pricing it as if its earnings were headed lower. Analysts expect growth, and fiscal 2026’s free cash flow was the best of the decade.
The catch is that its fiscal 2027 outlook relies partly on acquisitions, while AI pushes its prices down.
Its fiscal Q1 report, expected in December, is the next test, and I’ll be listening for what management says about pricing.
So what is Accenture stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Accenture could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!