Key Takeaways
- Nvidia shares fell 4% as Jensen Huang resigned as CEO, after reports that its board would oust him. The board then announced that he is resigning, and CFO Colette Kress becomes interim CEO.
- Nvidia’s purchases from SK hynix are still growing, so the bigger risk from the shake-up is what Nvidia pays for memory in 2027.
- Nvidia bought 17.61 trillion won of SK hynix’s chips in the first half of 2026. With SK hynix’s gross margin at 85.7%, a lower price would hurt its profits far more than its sales.
- SK hynix trades at just 2.5x forward earnings, which already prices in much of that risk, and Nvidia’s guidance next week is the next test.
Nvidia (NVDA) shares fell 4% this morning as CEO Jensen Huang resigned, after reports that its board would oust him, and the drop pulled memory stocks down with it.
That’s a particular problem for SK hynix (SKHY), because Nvidia is its biggest customer.
Dan Niles saw the interim pick coming
After Wednesday’s close, The Wall Street Journal reported that Nvidia’s board was getting ready to oust Huang after reports of a second extramarital affair, this one with someone who reported directly to him. On Thursday, the board announced that Huang is resigning, effective immediately, and that CFO Colette Kress will serve as interim CEO.
Dan Niles of Niles Investment Management guessed on X Wednesday night that the CFO would get the interim job. He also said what he expects from her when Nvidia reports next week: “The new interim CEO will probably want to set a low bar.”
That’s an uncomfortable setup for any company that sells to Nvidia. For SK hynix, the question is how much is riding on it.
TIKR tracks 62 analysts on Nvidia. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Nvidia, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Nvidia’s Analyst Ratings
Nvidia is still buying more
SK hynix’s semi-annual report shows that its largest customer bought 17.61 trillion won of chips in the first half of 2026, or 13.35% of sales. The Seoul Economic Daily reported that the customer is Nvidia. In 2025, Nvidia’s 23.3 trillion won made up 23.9% of SK hynix’s sales.
Nvidia’s share fell because SK hynix’s other sales grew faster. First-half revenue of 131.9 trillion won was already more than the 97.1 trillion won SK hynix booked in all of 2025. Nvidia kept buying more as well: in six months, its purchases reached three-quarters of its total for 2025.
A second customer bought 17.19 trillion won in the half, so SK hynix depends on any one buyer less than it did a year ago. Still, Nvidia matters more than its 13.35% suggests. TrendForce estimated in January that Nvidia accounts for about two-thirds of demand for HBM4. The Seoul Economic Daily also expects Nvidia’s share of SK hynix’s sales to rise in the second half, as SK hynix times its HBM4 supply to Nvidia’s new Vera Rubin chip.
Analysts expect that demand to keep SK hynix’s earnings per US-listed share climbing through 2028:

A new CEO at Nvidia doesn’t change the HBM4 already planned for Vera Rubin, so I don’t see much reason for the 2026 estimate to move. The 2027 estimate depends far more on what Nvidia agrees to pay.
Already priced for a fall
Investors aren’t paying much for those estimates. SK hynix’s forward P/E has ranged from 2.3x to 4.6x since its US listing in July, and it’s now close to the bottom of that range:

At 2.5x as of yesterday’s close, against a 3.8x average, investors are already paying for a steep fall in earnings once the boom ends. Margins show why they’re nervous. SK hynix’s gross margin has risen every quarter since the June 2025 quarter, from 53.9% to 85.7%:
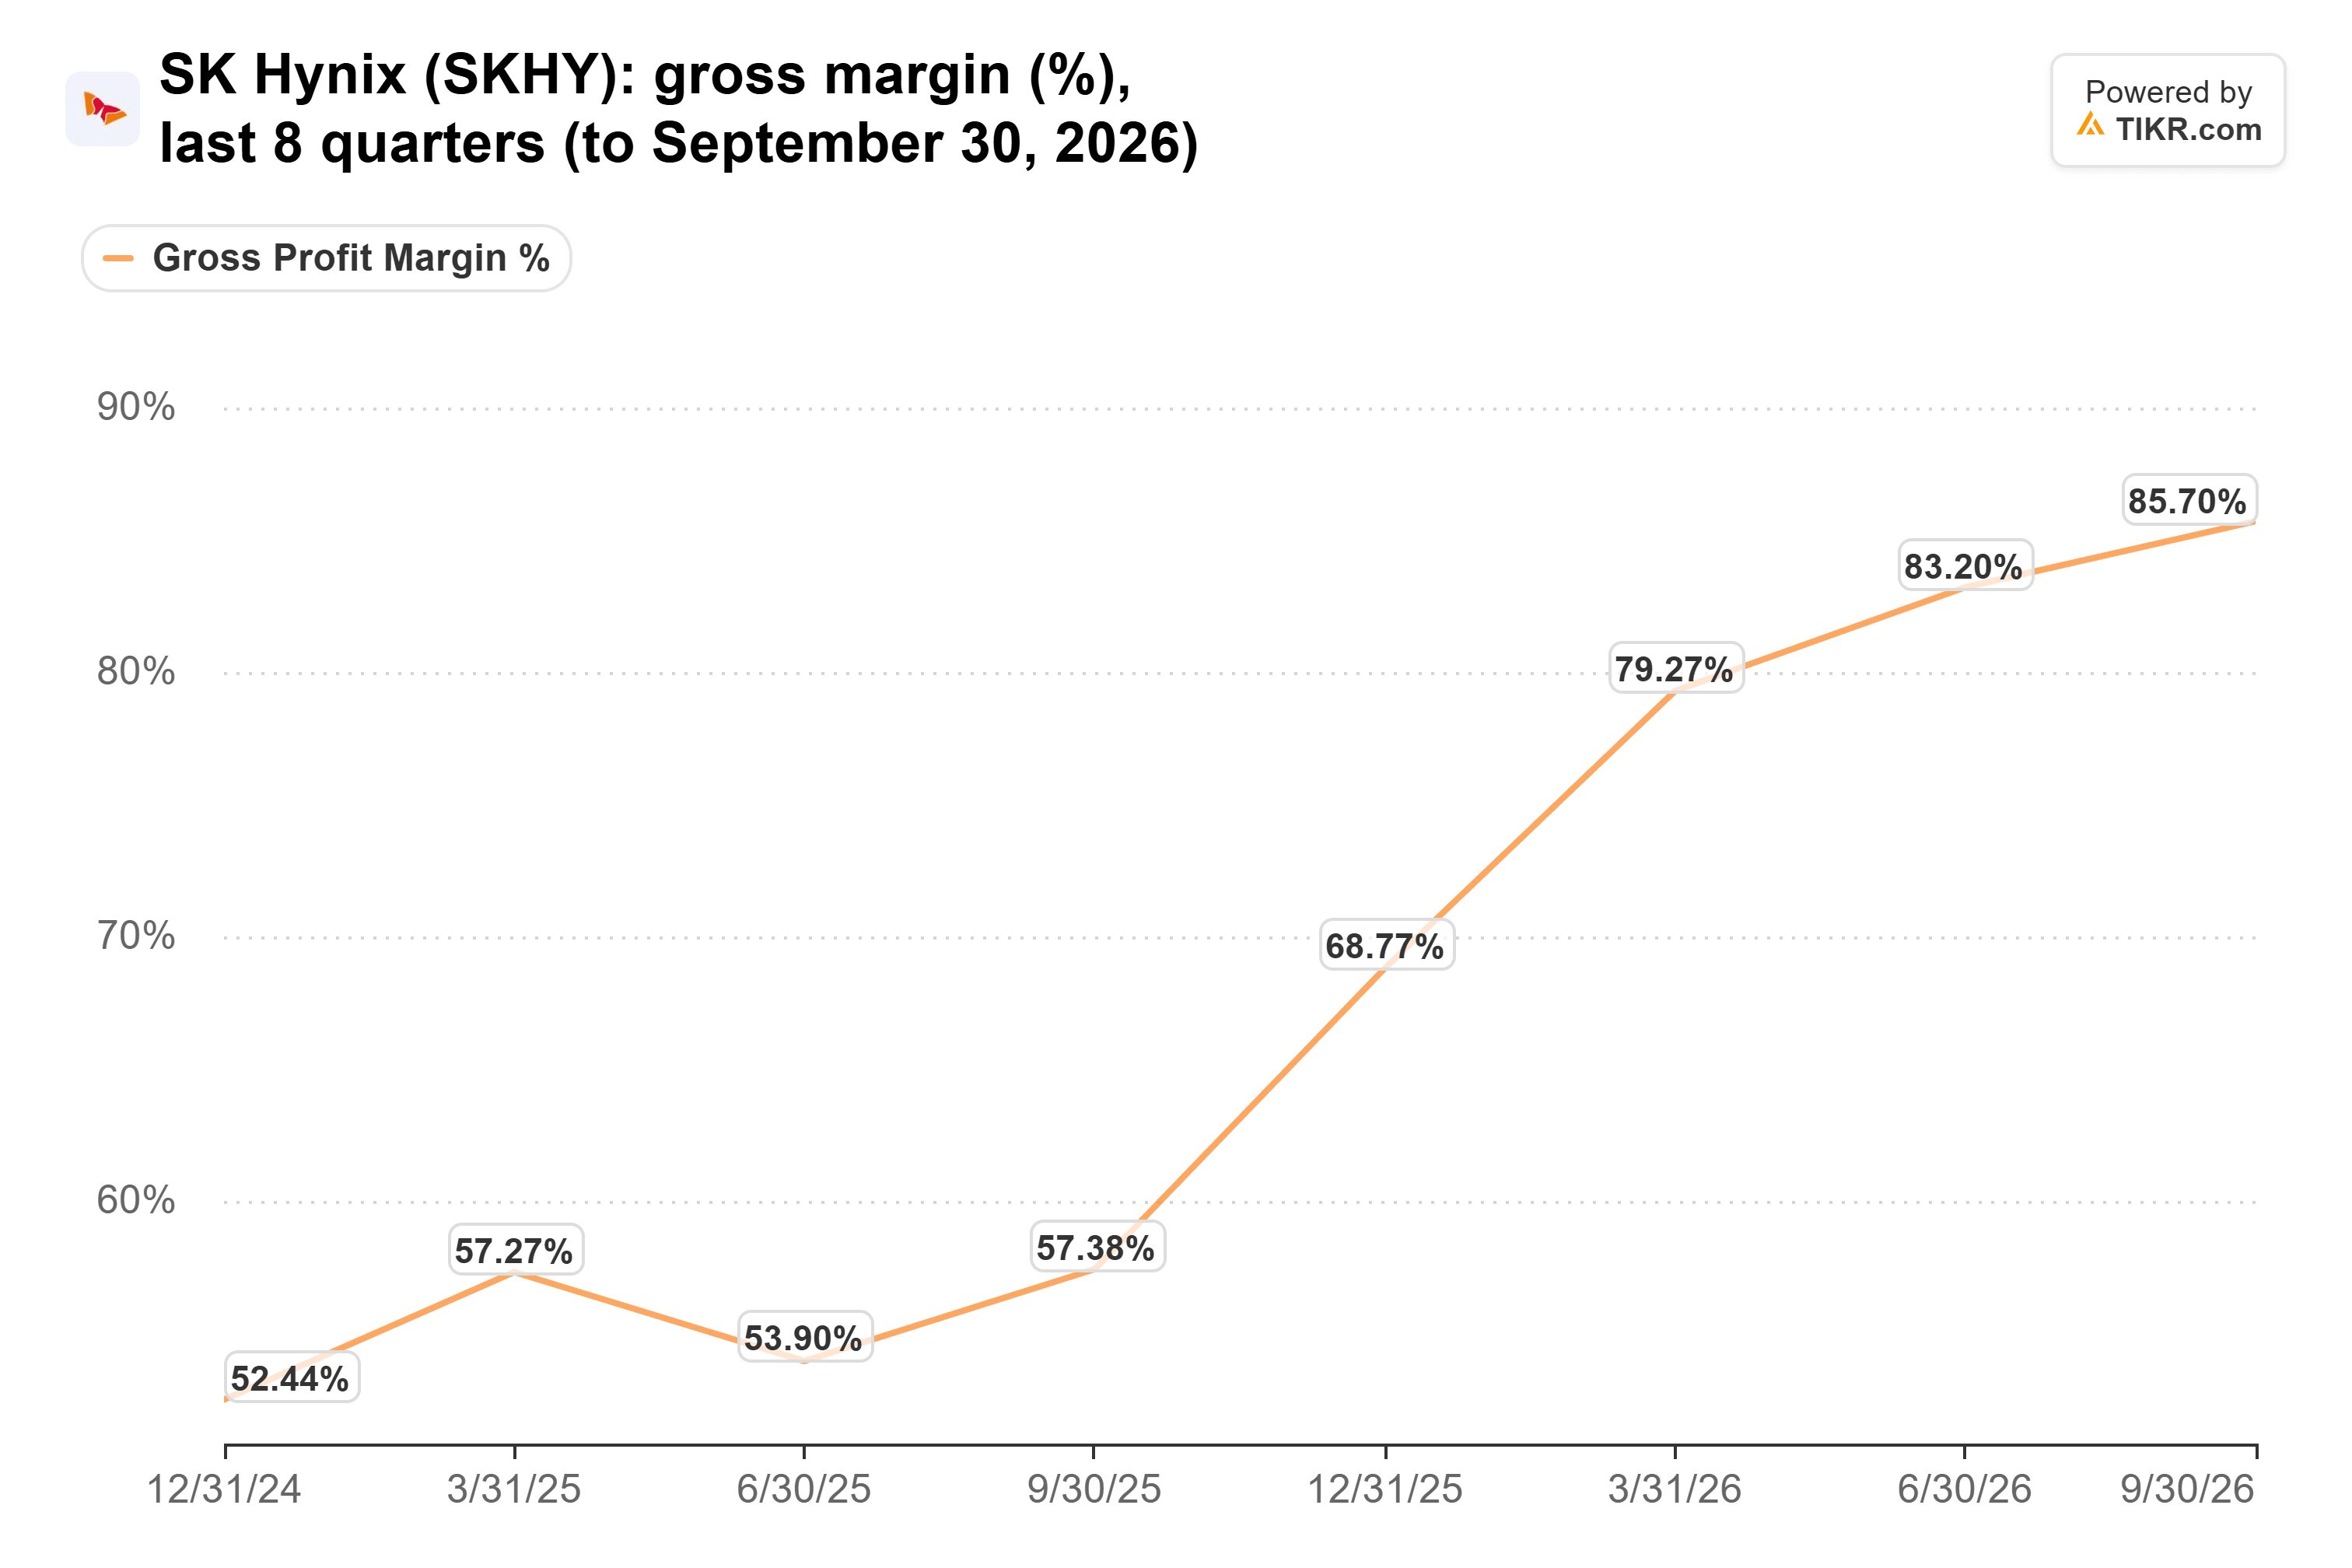
In the second quarter, nearly 90% of SK hynix’s revenue gain over the year before went straight to operating profit. If prices fell, profits would drop just as quickly.
Watch what Nvidia pays in 2027
So the bigger risk from Nvidia’s shake-up is the price it pays for HBM next year. SK hynix hasn’t said what its 2027 HBM prices will be. My read: a new CEO who wants to set a low bar has every reason to push suppliers hard on cost.
But Nvidia can’t ship its chips without the memory. SK hynix’s management said in April that customers’ HBM demand over the next three years is far greater than its capacity. On its third-quarter call, it said it plans 2027 results “at a significantly higher level, both in terms of absolute revenue and profit.”
So yes, Nvidia’s crisis is SK hynix’s problem too. But at 2.5x forward earnings, I think investors have already marked SK hynix down for it, and I’d treat a drop on Nvidia’s news as a chance to buy a supplier whose demand is still running ahead of its capacity. Of course, if Nvidia’s guidance next week points to slower data-center spending, or SK hynix’s 2027 HBM prices come in lower with its fourth-quarter results in late January, I’d have to rethink that.
So what is SK hynix stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what SK hynix could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!