Key Takeaways
- Scale Venture Partners’ Rory O’Driscoll said on 20VC that Palantir’s multimillion-dollar contracts let revenue grow faster than the company can hire, so its margins keep rising.
- Palantir’s operating margin went from -26.7% in 2021 to 31.6% in 2025 and about 47% in the third quarter of 2026, and revenue per employee has roughly doubled.
- The main risk is new business: total contract value grew just 6% in the third quarter, and analysts expect revenue growth to slow to about 53% in 2027.
- Palantir trades at 75x forward earnings, well under its three-year average of 130x, and its first 2027 guidance in early February is the next test.
Palantir Technologies (PLTR) has had a rough few weeks. AI stocks sold off, and the stock fell about 18% from its Oct. 9 closing high, even though third-quarter revenue grew 96% to $2.31 billion.
The selloff didn’t change the basic math of how Palantir makes money, though. On this week’s episode of 20VC, Scale Venture Partners’ Rory O’Driscoll pointed to how much revenue Palantir brings in for each person it employs:
“Palantir at 2 million, 2 million per employee. It’s very enterprise, but it’s 2 million per employee, growing 100%, growing 98%.”
Then he explained why that matters: “if you have $2 and $5 million contracts like Palantir, and if revenue doubles, you probably can’t hire headcount fast enough to catch up. You literally can’t stop your margins going up, which is a wonderful place to be.”
That’s about as bullish as a margin argument gets.
TIKR tracks 33 analysts on Palantir. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Palantir, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Palantir’s Analyst Ratings
The numbers back him up
Palantir’s revenue doubled in two years, from $2.23 billion in 2023 to $4.48 billion in 2025. Analysts expect $8.55 billion this year and $19.2 billion by 2028:

Headcount hasn’t kept up. Palantir’s annual report says it ended 2025 with 4,429 full-time employees. Multiply the third quarter’s $2.31 billion by four and you get about $9.2 billion, or roughly $2 million per employee. (That assumes headcount is still close to where it ended 2025, since Palantir gives the count only once a year.) Over all of 2025, it brought in about $1 million per employee.
As that gap has opened up, the operating margin has climbed every year, from -26.7% in 2021 to 31.6% in 2025:
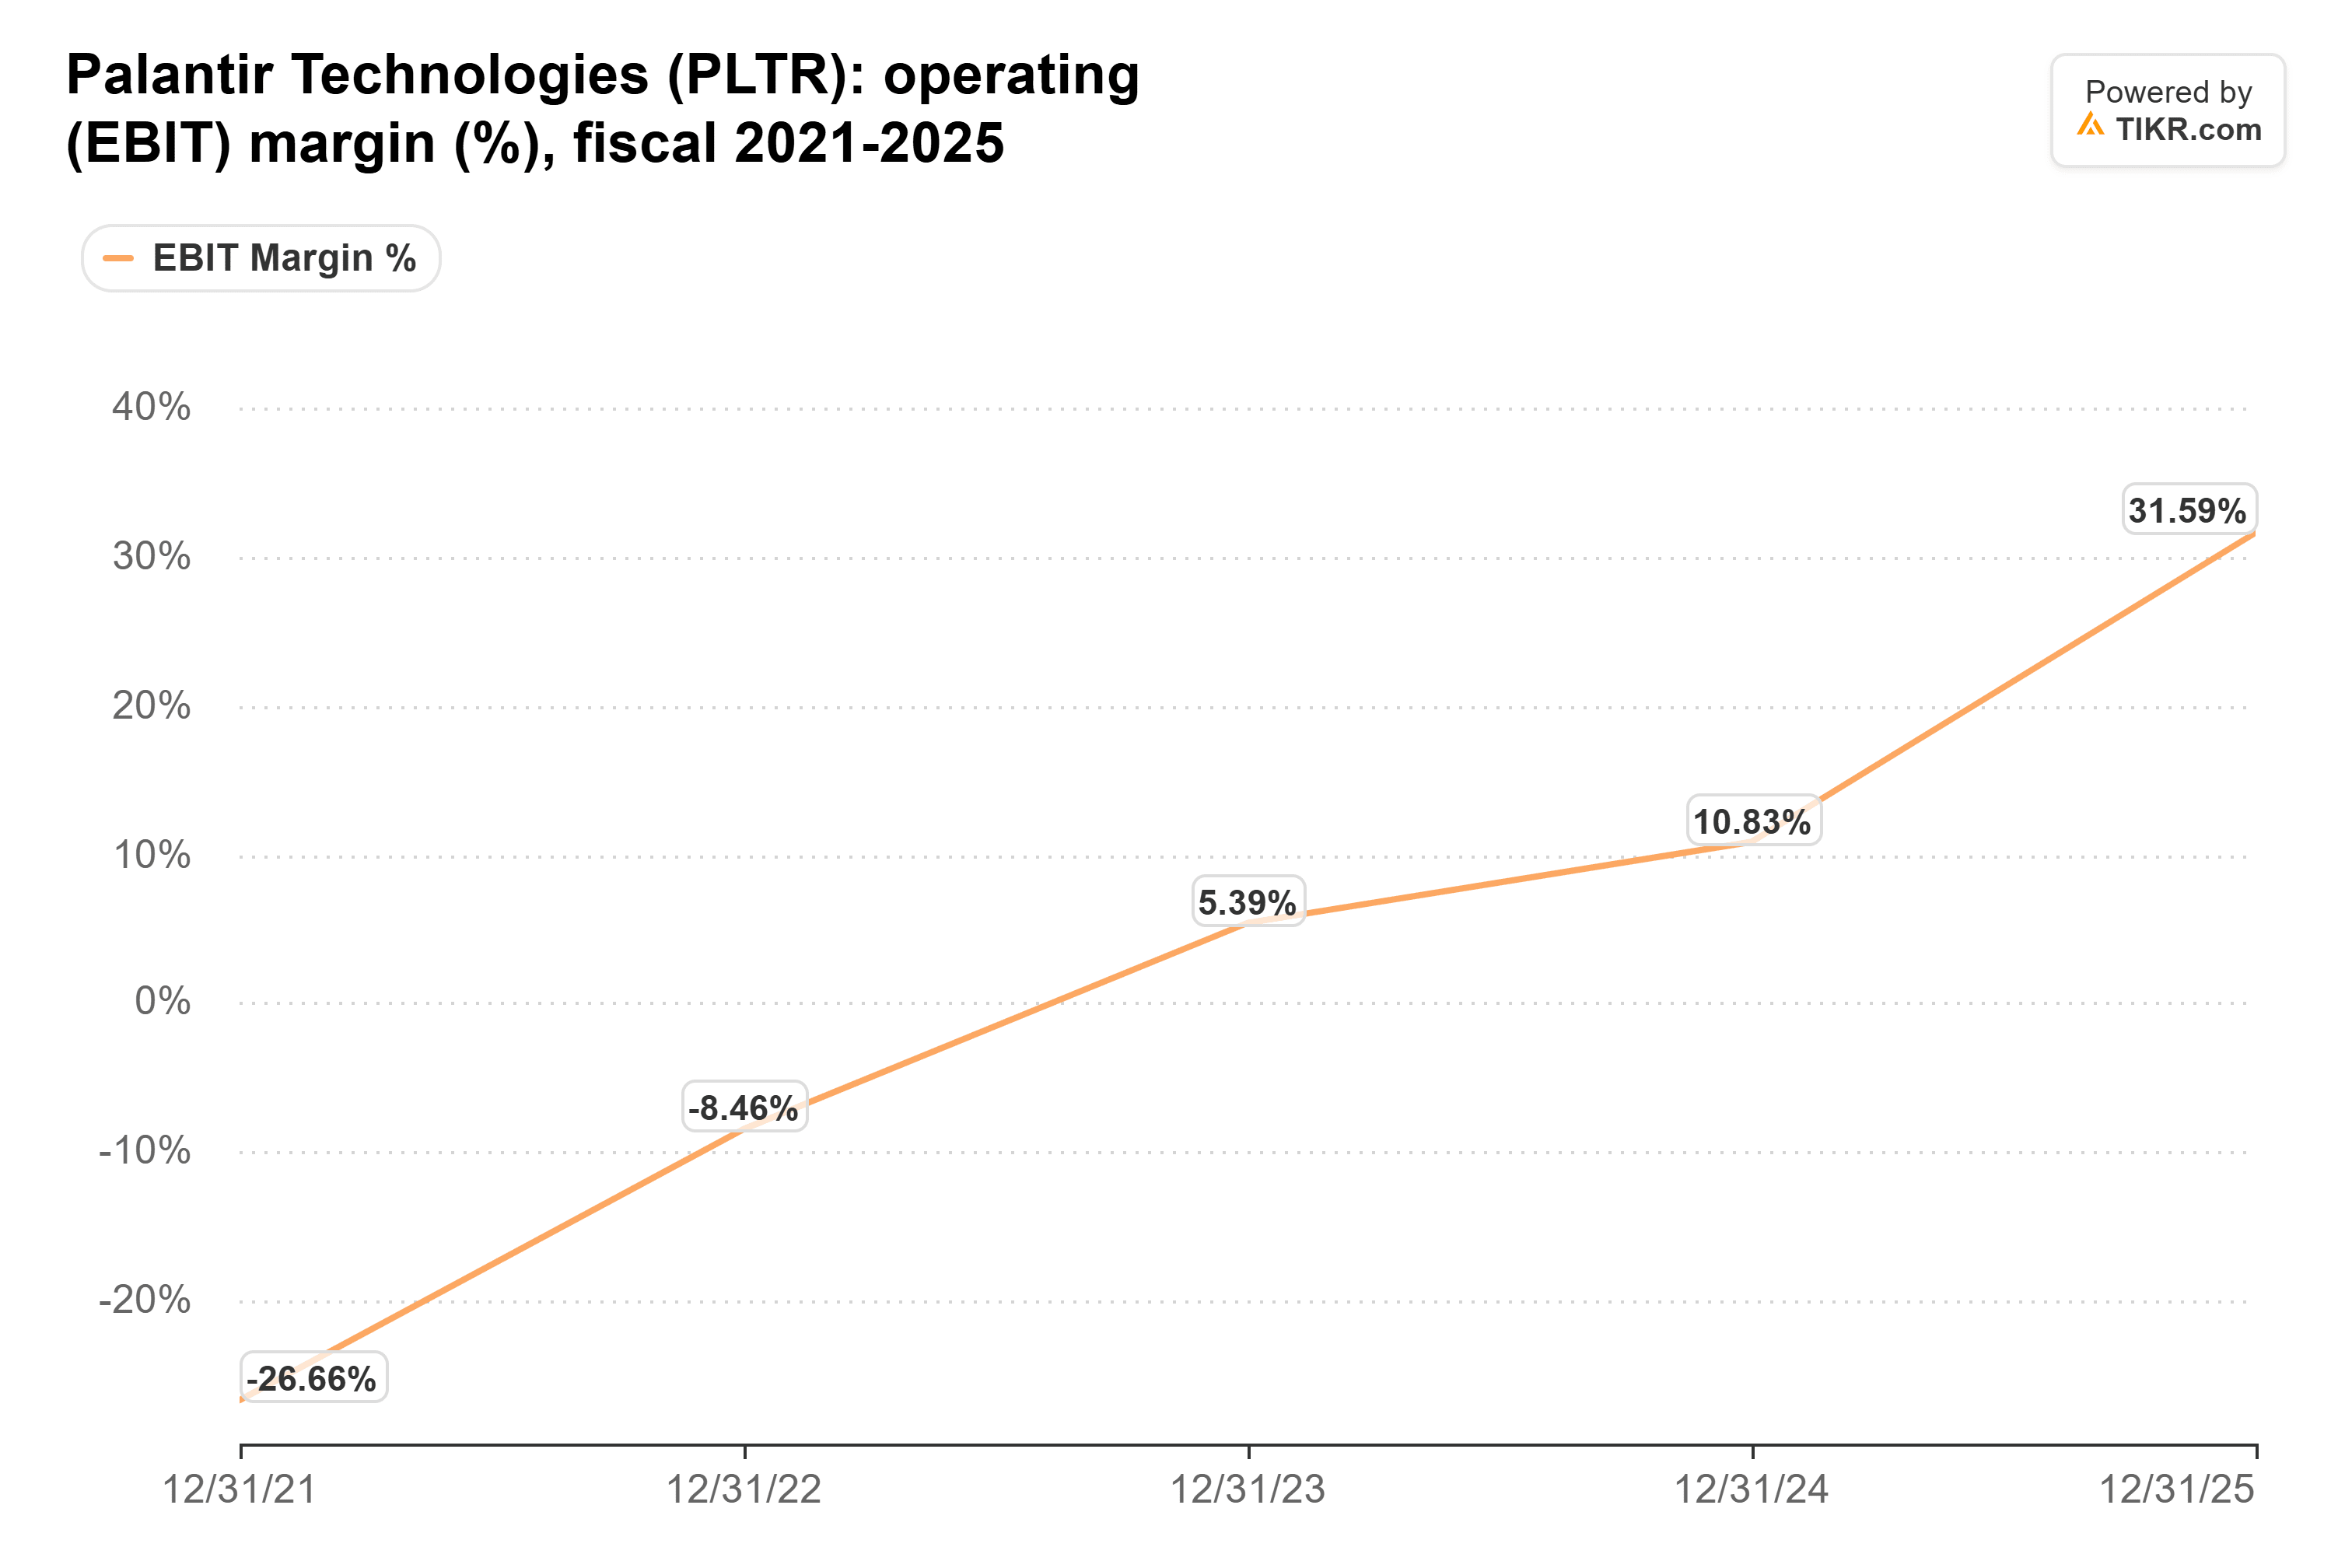
The margin is higher still now: $1.08 billion of operating income in the third quarter, about 47% of revenue.
The second quarter’s segment figures show the same thing. Commercial revenue rose 110%, while the costs Palantir assigns to that segment rose just 29%. Sales and marketing fell to 18% of revenue, from 24% a year earlier.
The catch is new contracts
O’Driscoll’s math works as long as revenue keeps running far ahead of hiring. In the third quarter, new deals slowed sharply: total contract value grew just 6%, and U.S. commercial remaining deal value rose only 4% from June. Management and Piper Sandler blamed shorter contract lengths. That may be true, but it’s the number I’d watch most closely.
Analysts expect revenue growth to slow as well. Consensus has 2027 revenue at $13.1 billion, about 53% growth, roughly half the pace O’Driscoll describes. Margins can still rise at that pace, as long as Palantir adds people more slowly than it adds revenue. They’ll just rise more slowly.
The selloff made the leverage cheaper
Palantir trades at 75x forward earnings, well under its three-year average of 130x and far below its 270x peak in October 2025:
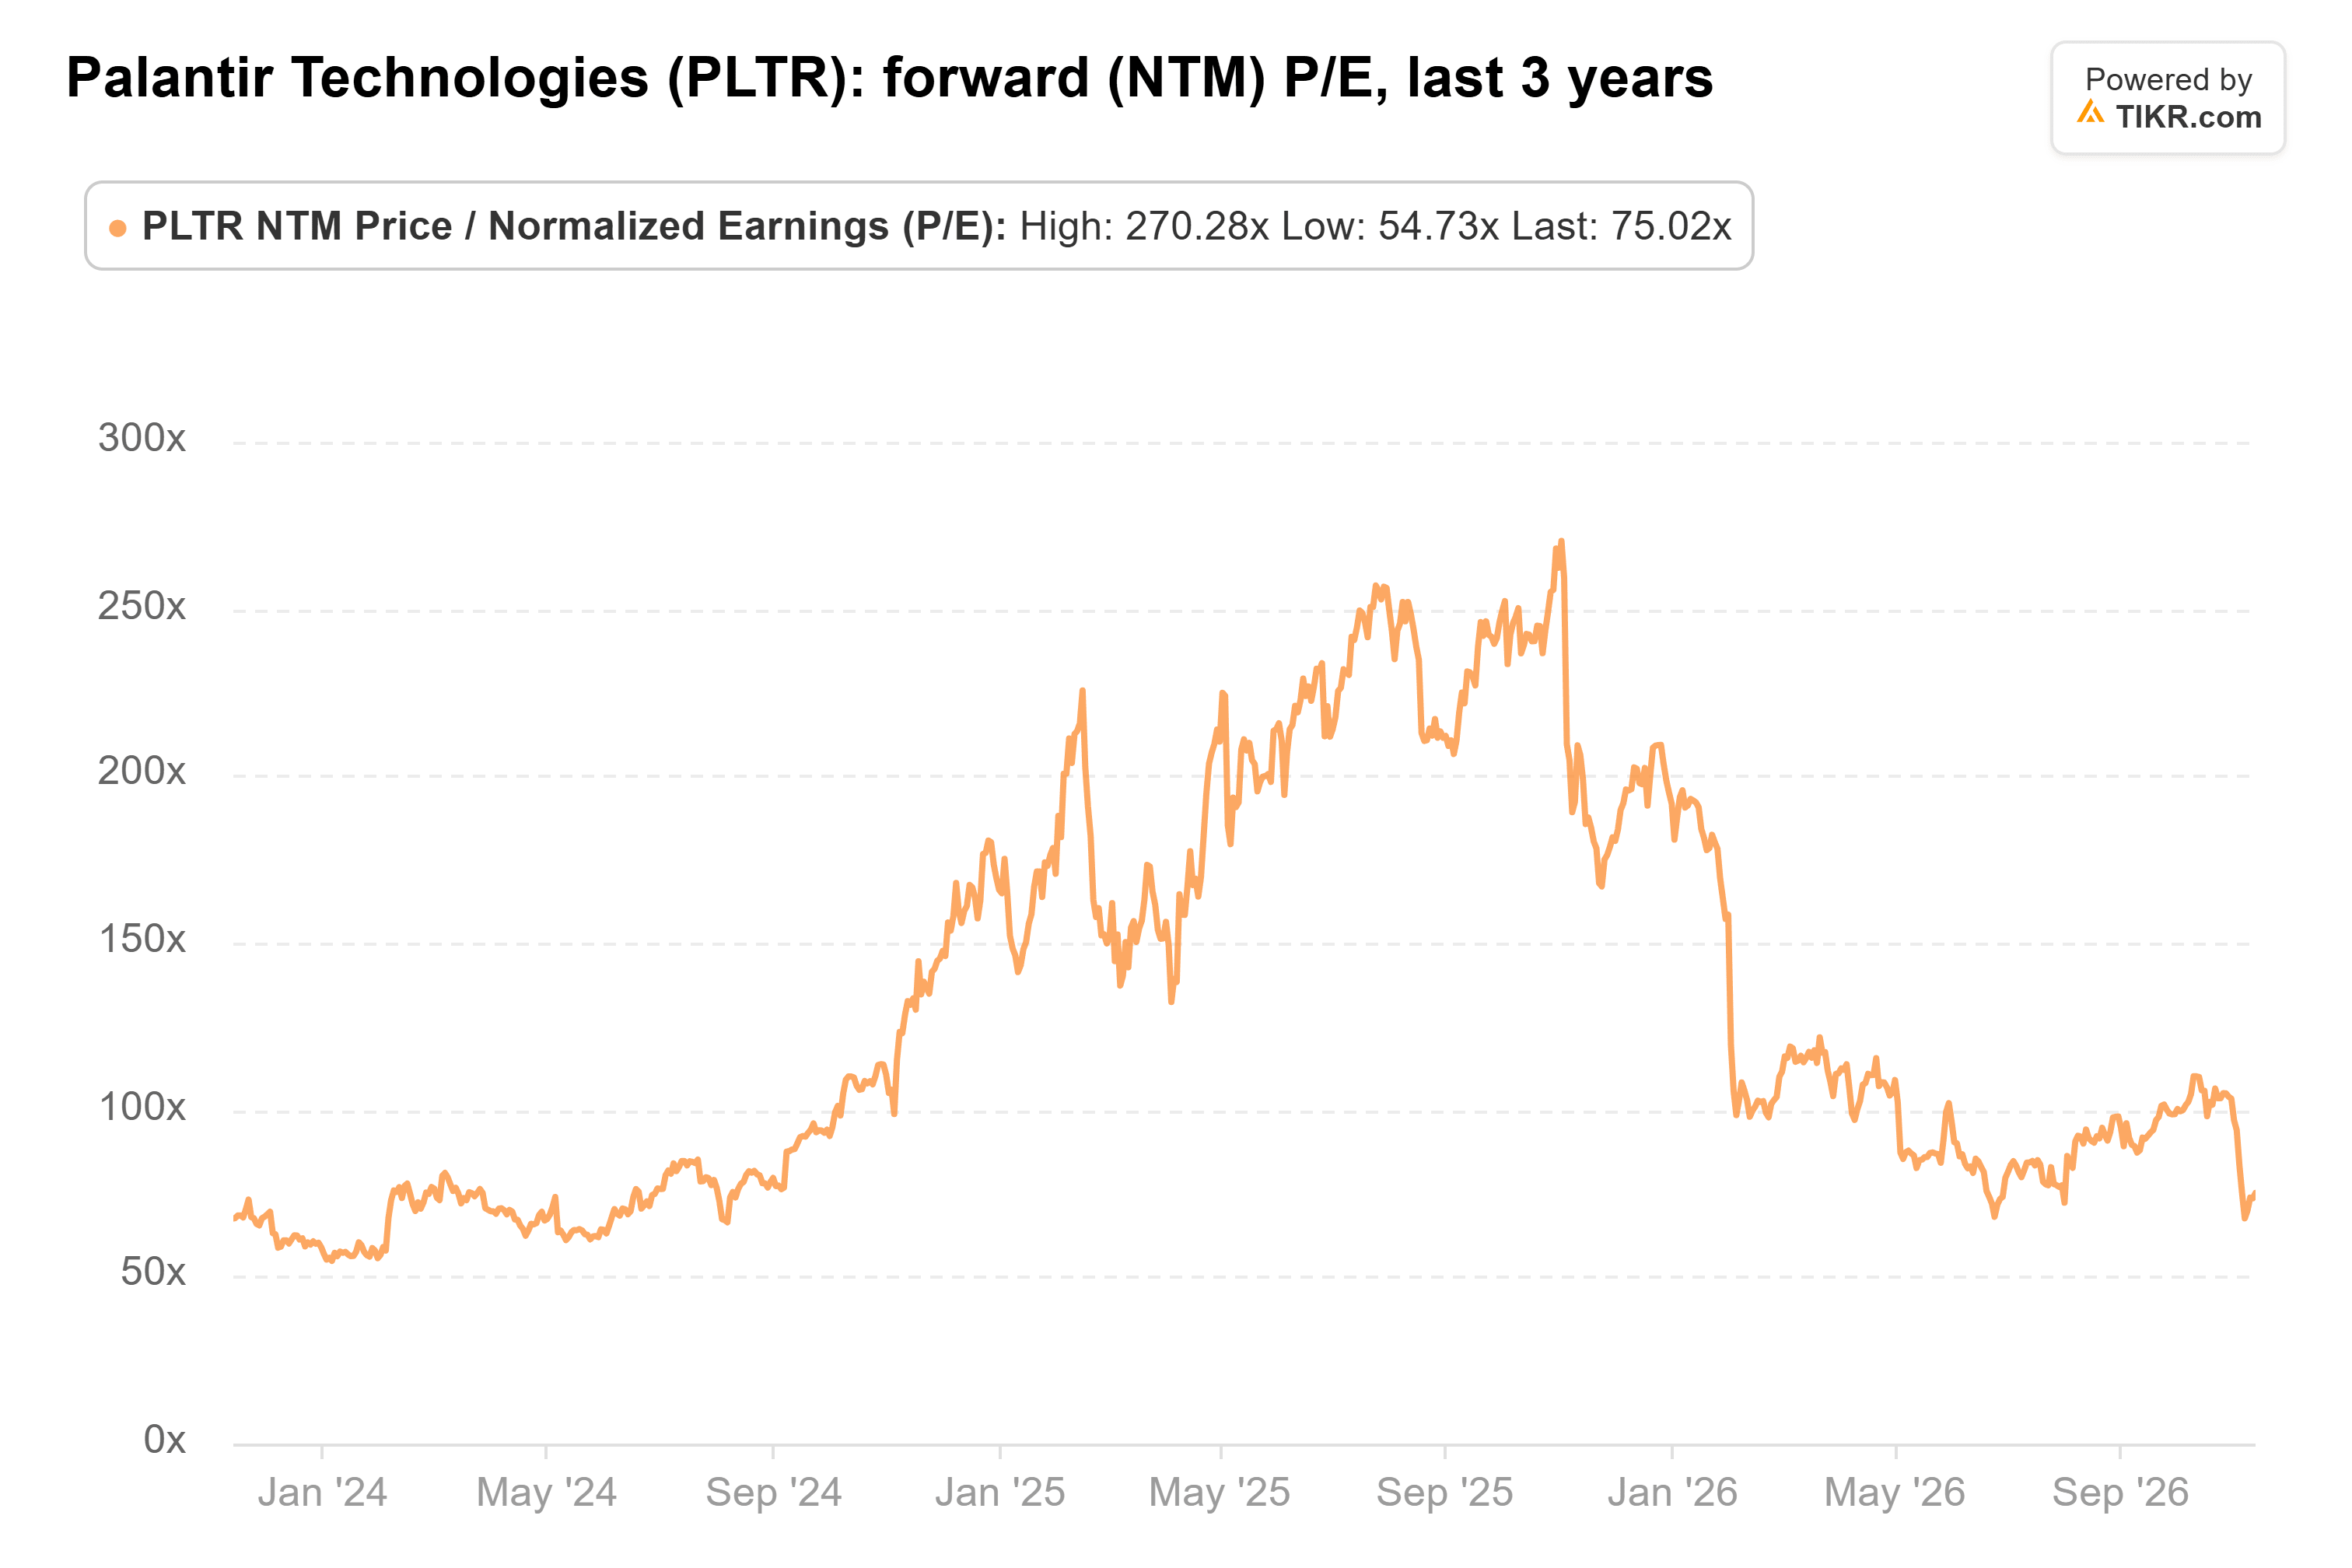
That’s still expensive by any normal standard. But investors are paying much less per dollar of expected earnings than they were a year ago, and the estimates keep rising: consensus normalized EPS for 2026 now stands at $1.70.
I think O’Driscoll is right about the margins. Contracts this big make Palantir’s operating leverage close to automatic, and the selloff has made that leverage much cheaper to buy than it was a year ago.
Of course, the real test comes in early February, when Palantir gives its first 2027 guidance against that $13.1 billion consensus. If slower bookings pull that guide below consensus, 75x won’t look so cheap.
So what is Palantir stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Palantir could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!