Key Takeaways
- Lumentum stock is up 56% in 2026, well ahead of rival Coherent, but it’s nearly half off its October high after Marvell’s all-stock deal and an AI chip selloff.
- Lumentum’s business drove the run: September-quarter revenue rose 136.5% to $1.26 billion, and the December-quarter guide calls for $1.575 billion to $1.625 billion.
- Each Lumentum share becomes 4.5 Marvell shares, so Marvell’s stock sets Lumentum’s price until the deal closes, expected in the first half of 2028.
- Holders shouldn’t sell below the offer’s value, and new money makes sense only for investors who want to own Marvell.
Lumentum (LITE) stock is up 56% in 2026, and the business earned that run. But since Marvell Technology (MRVL) agreed on Nov. 2 to pay 4.5 of its shares for each Lumentum share, Lumentum’s stock has moved with Marvell’s.
Nvidia invested $2 billion in Lumentum in March, and $2 billion in rival Coherent (COHR) this year too. Only Coherent still trades on its own optics business, so Lumentum holders should know what they actually own now.
TIKR tracks 25 analysts on Lumentum. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Lumentum, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Lumentum’s Analyst Ratings
The run was all business
June-quarter revenue rose 109% to $1.01 billion. CEO Michael Hurlston said the September-quarter guide, at a $1.25 billion midpoint, reached the company’s target model “more than a quarter ahead of schedule.” In October, he said Lumentum’s parts were sold out through early 2029.
The September quarter, reported Nov. 2, was its best yet. Revenue rose 136.5% to $1.26 billion, and non-GAAP gross margin climbed to 53.2% from 39.4% a year earlier. Lumentum also won its second major near- and co-packaged optics deal, backed by more than $5 billion of purchase commitments. And Hurlston expects more:
“Looking ahead, we anticipate adding approximately $350 million in sequential growth in our second quarter, a figure greater than the quarterly revenue of the whole company just two years ago.”
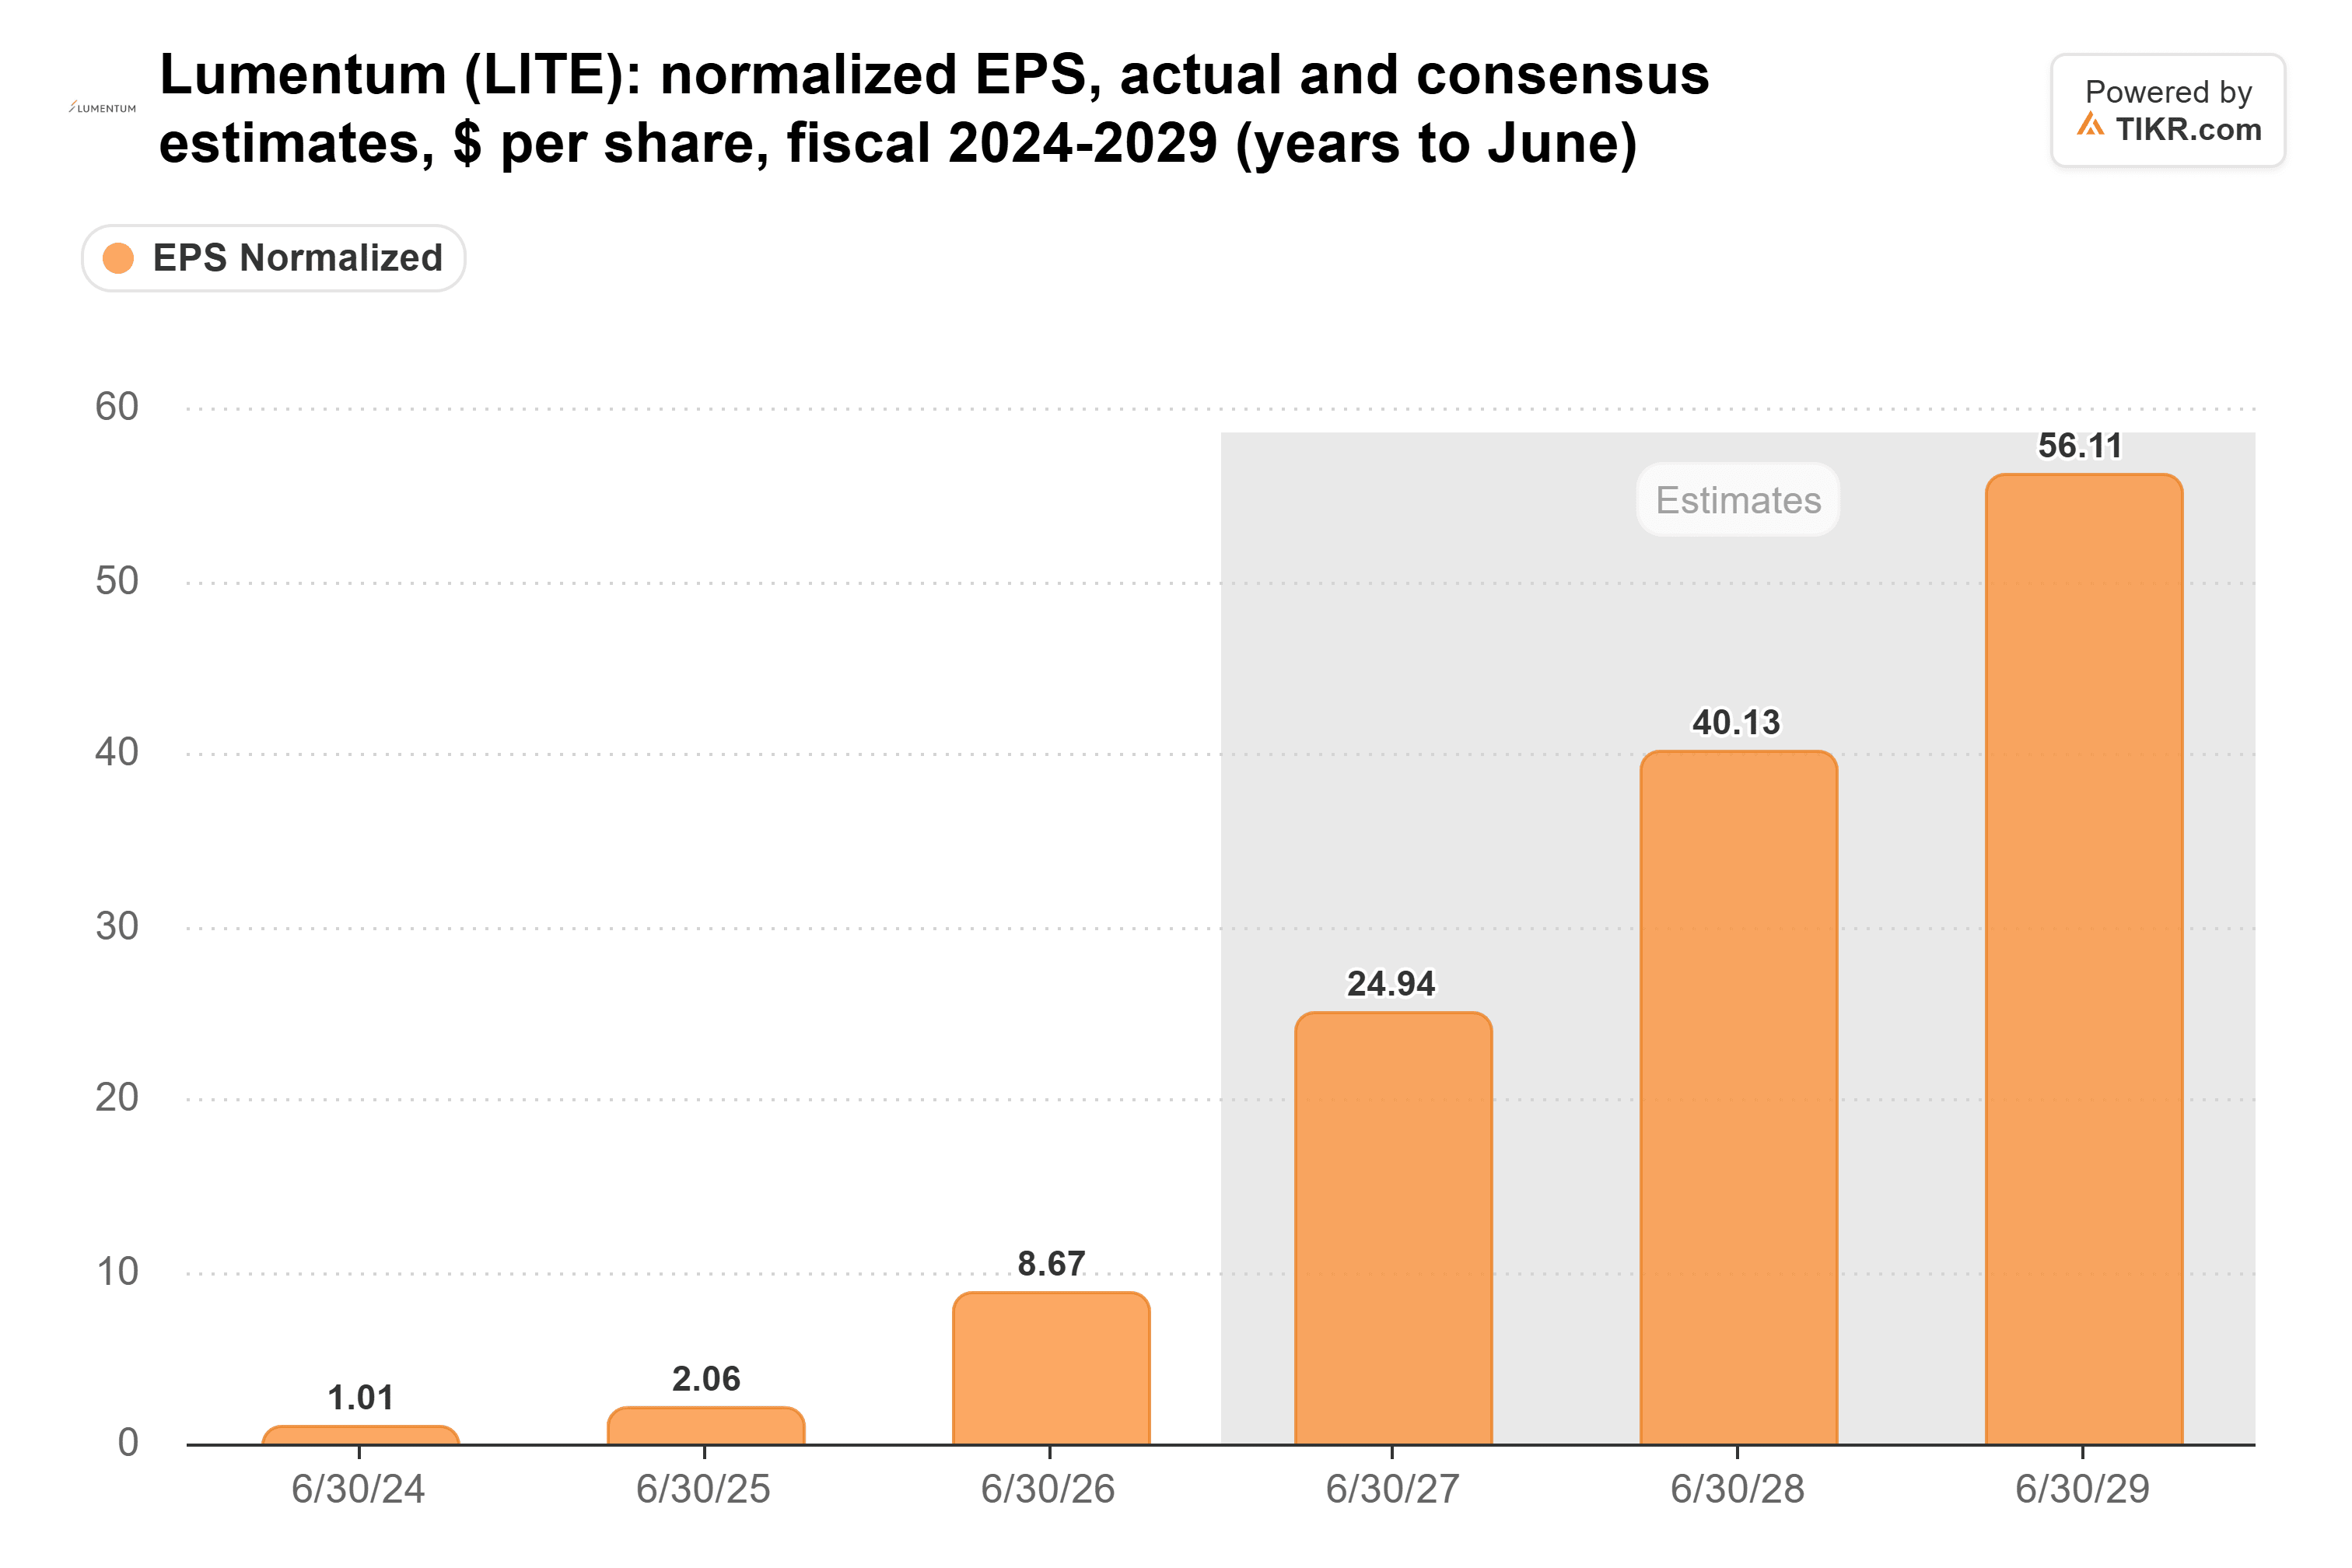
The Street sees far more ahead, with normalized EPS rising more than fourfold between fiscal 2026 and fiscal 2028 (years to June):
Then Marvell set the price
Using Oct. 28 closes, the companies valued the offer at about $1,132 a share, a 23.9% premium. Investors sold both stocks on the news. Then Democrats’ midterm sweep hit AI data-center stocks on Nov. 4, and a broad AI chip selloff followed a day later.
With a fixed ratio, each $1 move in Marvell’s stock moves the offer’s value $4.50. Marvell is still up 78% in 2026, and Lumentum is up 13% in the past week as AI stocks recovered, helped by CoreWeave raising its 2026 outlook. Analysts’ targets now follow Marvell too: Bernstein cut its Lumentum target to $635 from $900 on Nov. 9, then raised it to $700 a day later to reflect Marvell’s latest share price.
Coherent has no deal tying it down, and it’s up 8% in 2026. Lumentum runs the more profitable business, with a 53.2% non-GAAP gross margin against Coherent’s 40.6%. But Lumentum holders don’t keep that margin to themselves: they’ll own about a third of the combined company.
Hold on, and buy only if you’d own Marvell
On its own history, Lumentum looks cheap at 22x forward earnings, against a five-year average of 30x:
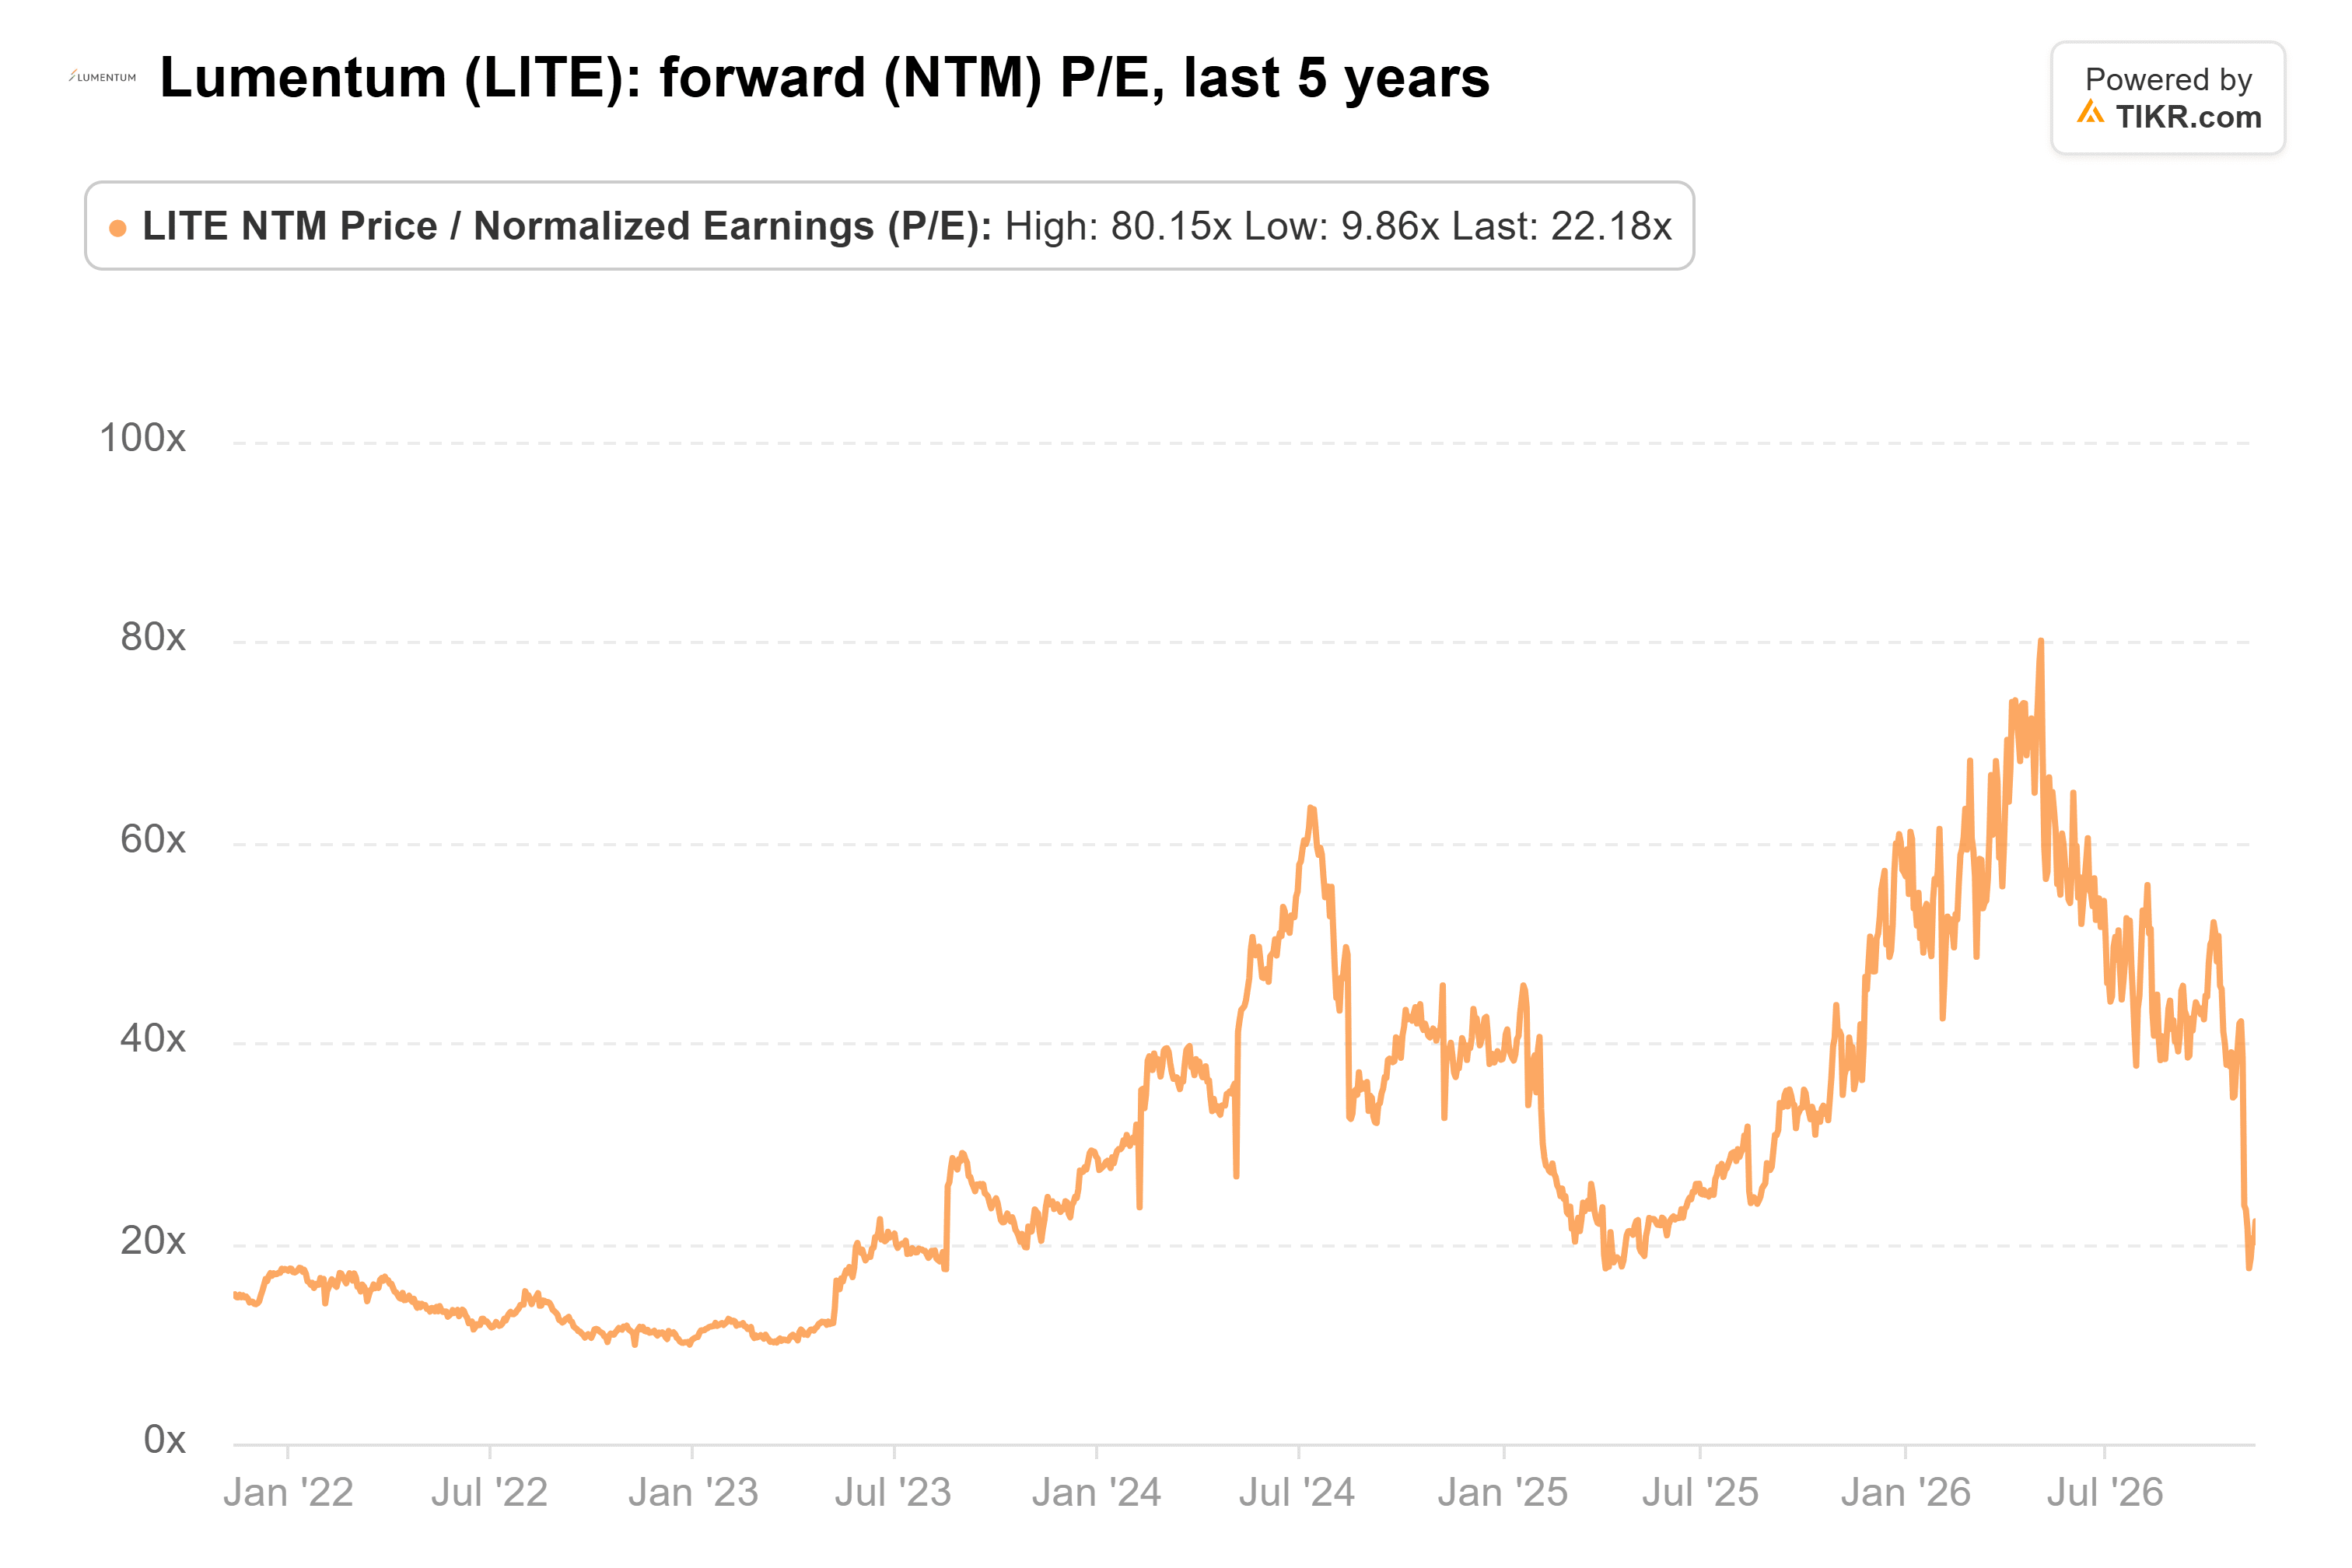
Holders end up with Marvell stock, though, so Marvell’s multiple matters more. On Nov. 2, Marvell was at about 30x forward earnings, under its five-year average of 33x, and the deal adds about 49% to its share count. Regulators still have to sign off, China’s among them, and Lumentum expects that to take 12 to 18 months. If they block it, Marvell owes Lumentum a $3.2 billion fee.
At the Nov. 12 close, Lumentum sat 15.6% below the value of 4.5 Marvell shares. Holders who wait collect that gap if the deal closes and Marvell’s stock holds up.
So I wouldn’t take profits here. Anyone who sells below the offer’s value gives up that discount on shares that would otherwise become Marvell stock. New money belongs here only if you’d happily own the combined company into 2028, since that’s what you’re buying.
Marvell reports on Dec. 1, and Lumentum’s December-quarter report is expected in February. Of course, if AI spending fears flare up again, the offer shrinks with Marvell’s stock before either.
So what is Lumentum stock actually worth if the deal doesn’t go through?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Lumentum could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!