Key Takeaways
- SK hynix shares fell 10.9% on Friday and 23.1% over the week, days after reporting KRW 104.6 trillion of revenue and an 80% operating margin.
- Long-term agreements with 14 customers cover more than half of 2027 and 2028 capacity, and Samsung also expects the AI chip shortage to worsen.
- The stock trades at 2.3x forward earnings, so the market is pricing a memory downturn the company’s own guidance doesn’t show.
- The January 28 fiscal-year report will show whether fourth-quarter DRAM bit shipments rose by the guided mid-20% range.
SK hynix (A000660) just posted the best quarter in its history. Then it lost almost a quarter of its value in five trading days.
The stock fell 10.9% on Friday alone and 23.1% for the week. It now sits 57% below its 52-week high.
The memory story didn’t break. Samsung Electronics (A005930), SK hynix’s biggest rival in HBM, said last week that it expects the AI chip shortage to get worse. Storage stocks slipped after Samsung’s report anyway.
What changed is the mood. Investors kept rotating out of AI trades after the US midterms, where Republicans took a beating and data center opponents showed real political muscle.
SK hynix also has a problem of its own. Its New York chip plans have hit a snag over US restrictions on China.
A quarter with no soft spots
Here’s what the third quarter delivered:
- Revenue of KRW 104.62 trillion, up 328% year over year
- Operating profit of KRW 83.33 trillion, up 632%, for an 80% margin
- Net income of KRW 39.78 trillion, down 58% from the second quarter on currency and investment valuation losses
Pricing did most of the work. DRAM average selling prices rose in the high 20% range from the prior quarter, and NAND prices climbed in the mid-20% range. HBM4 also went into mass production, and the company expects it to pass HBM3E in both volume and revenue share this quarter.
The top line has moved at a speed memory investors rarely see…
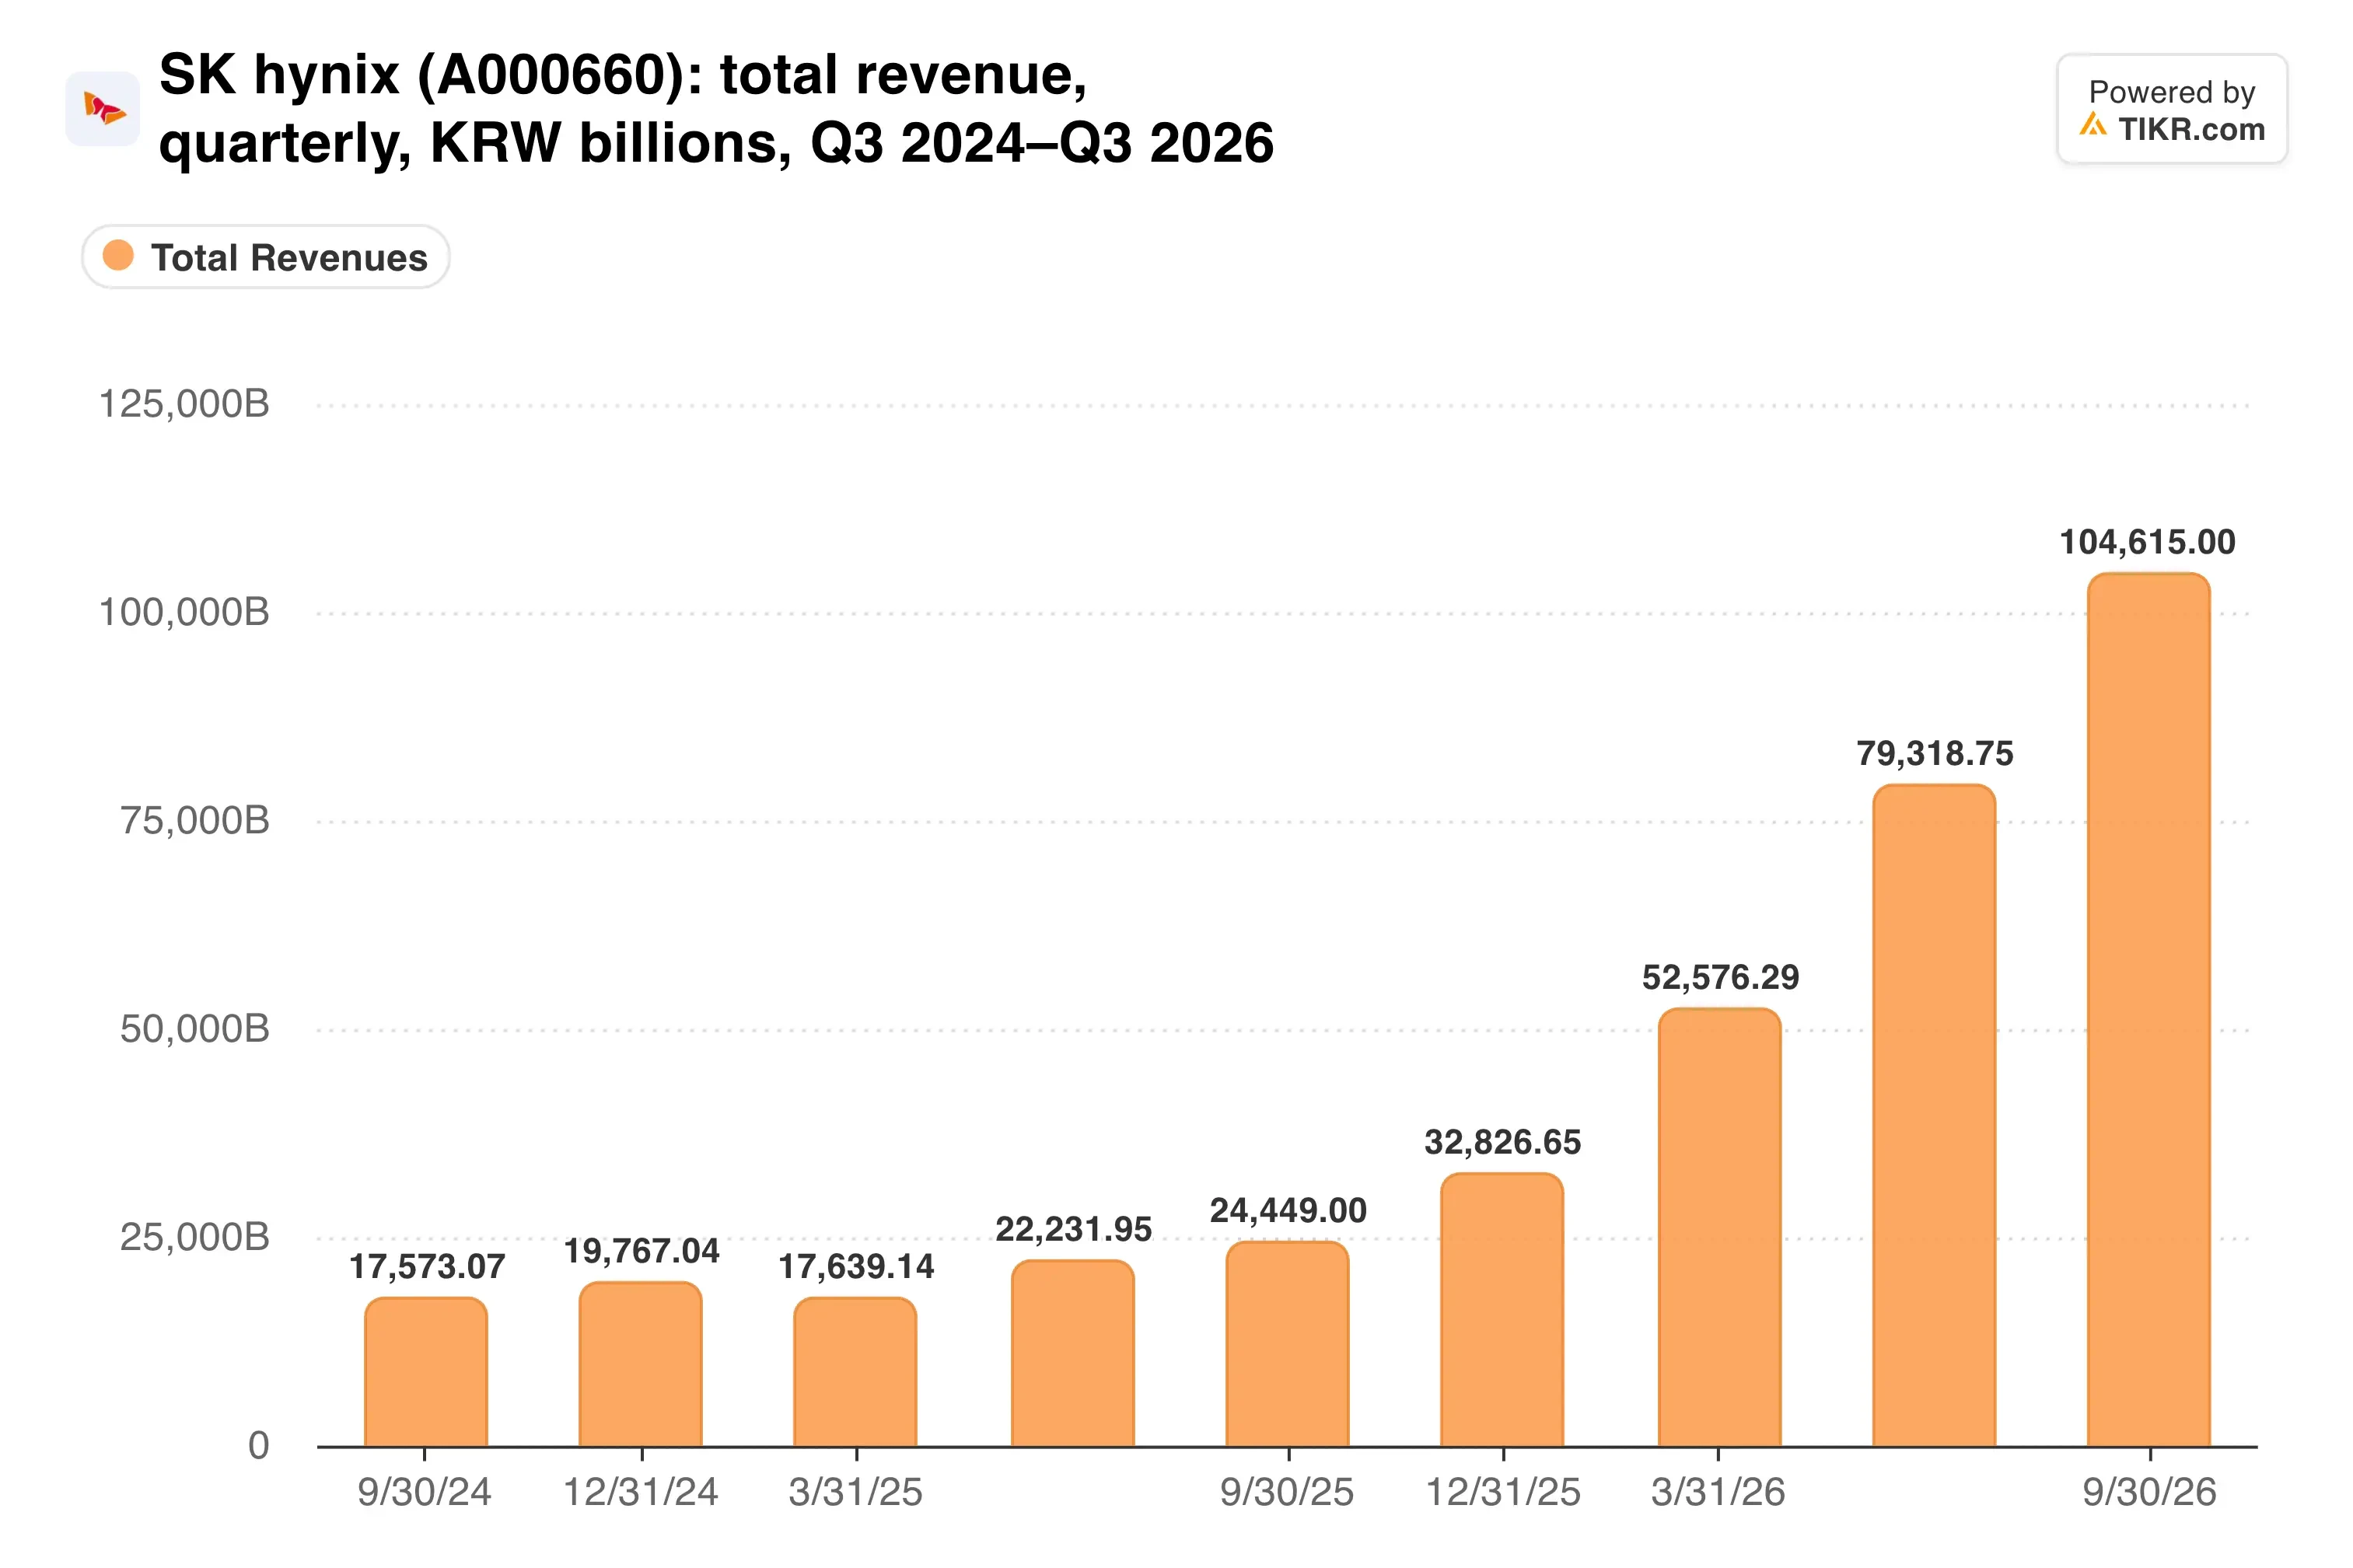
Quarterly revenue is now more than four times its level a year ago.
Customers signed up through 2028
The bigger number may be the contract book. SK hynix has long-term agreements with 14 major customers covering more than half of its 2027 and 2028 capacity. Once deals still in negotiation are added, it calls DRAM and HBM volumes effectively sold out through 2029.
Fourth-quarter guidance points the same way. DRAM bit shipments should rise in the mid-20% range from the third quarter, and NAND in the mid-single digits.
For 2027, the company expects DRAM demand to grow in the mid-20% range and NAND in the high teens. It also sees cloud providers lifting capex more than 60% next year.
How far ahead of its rival is it on profitability?
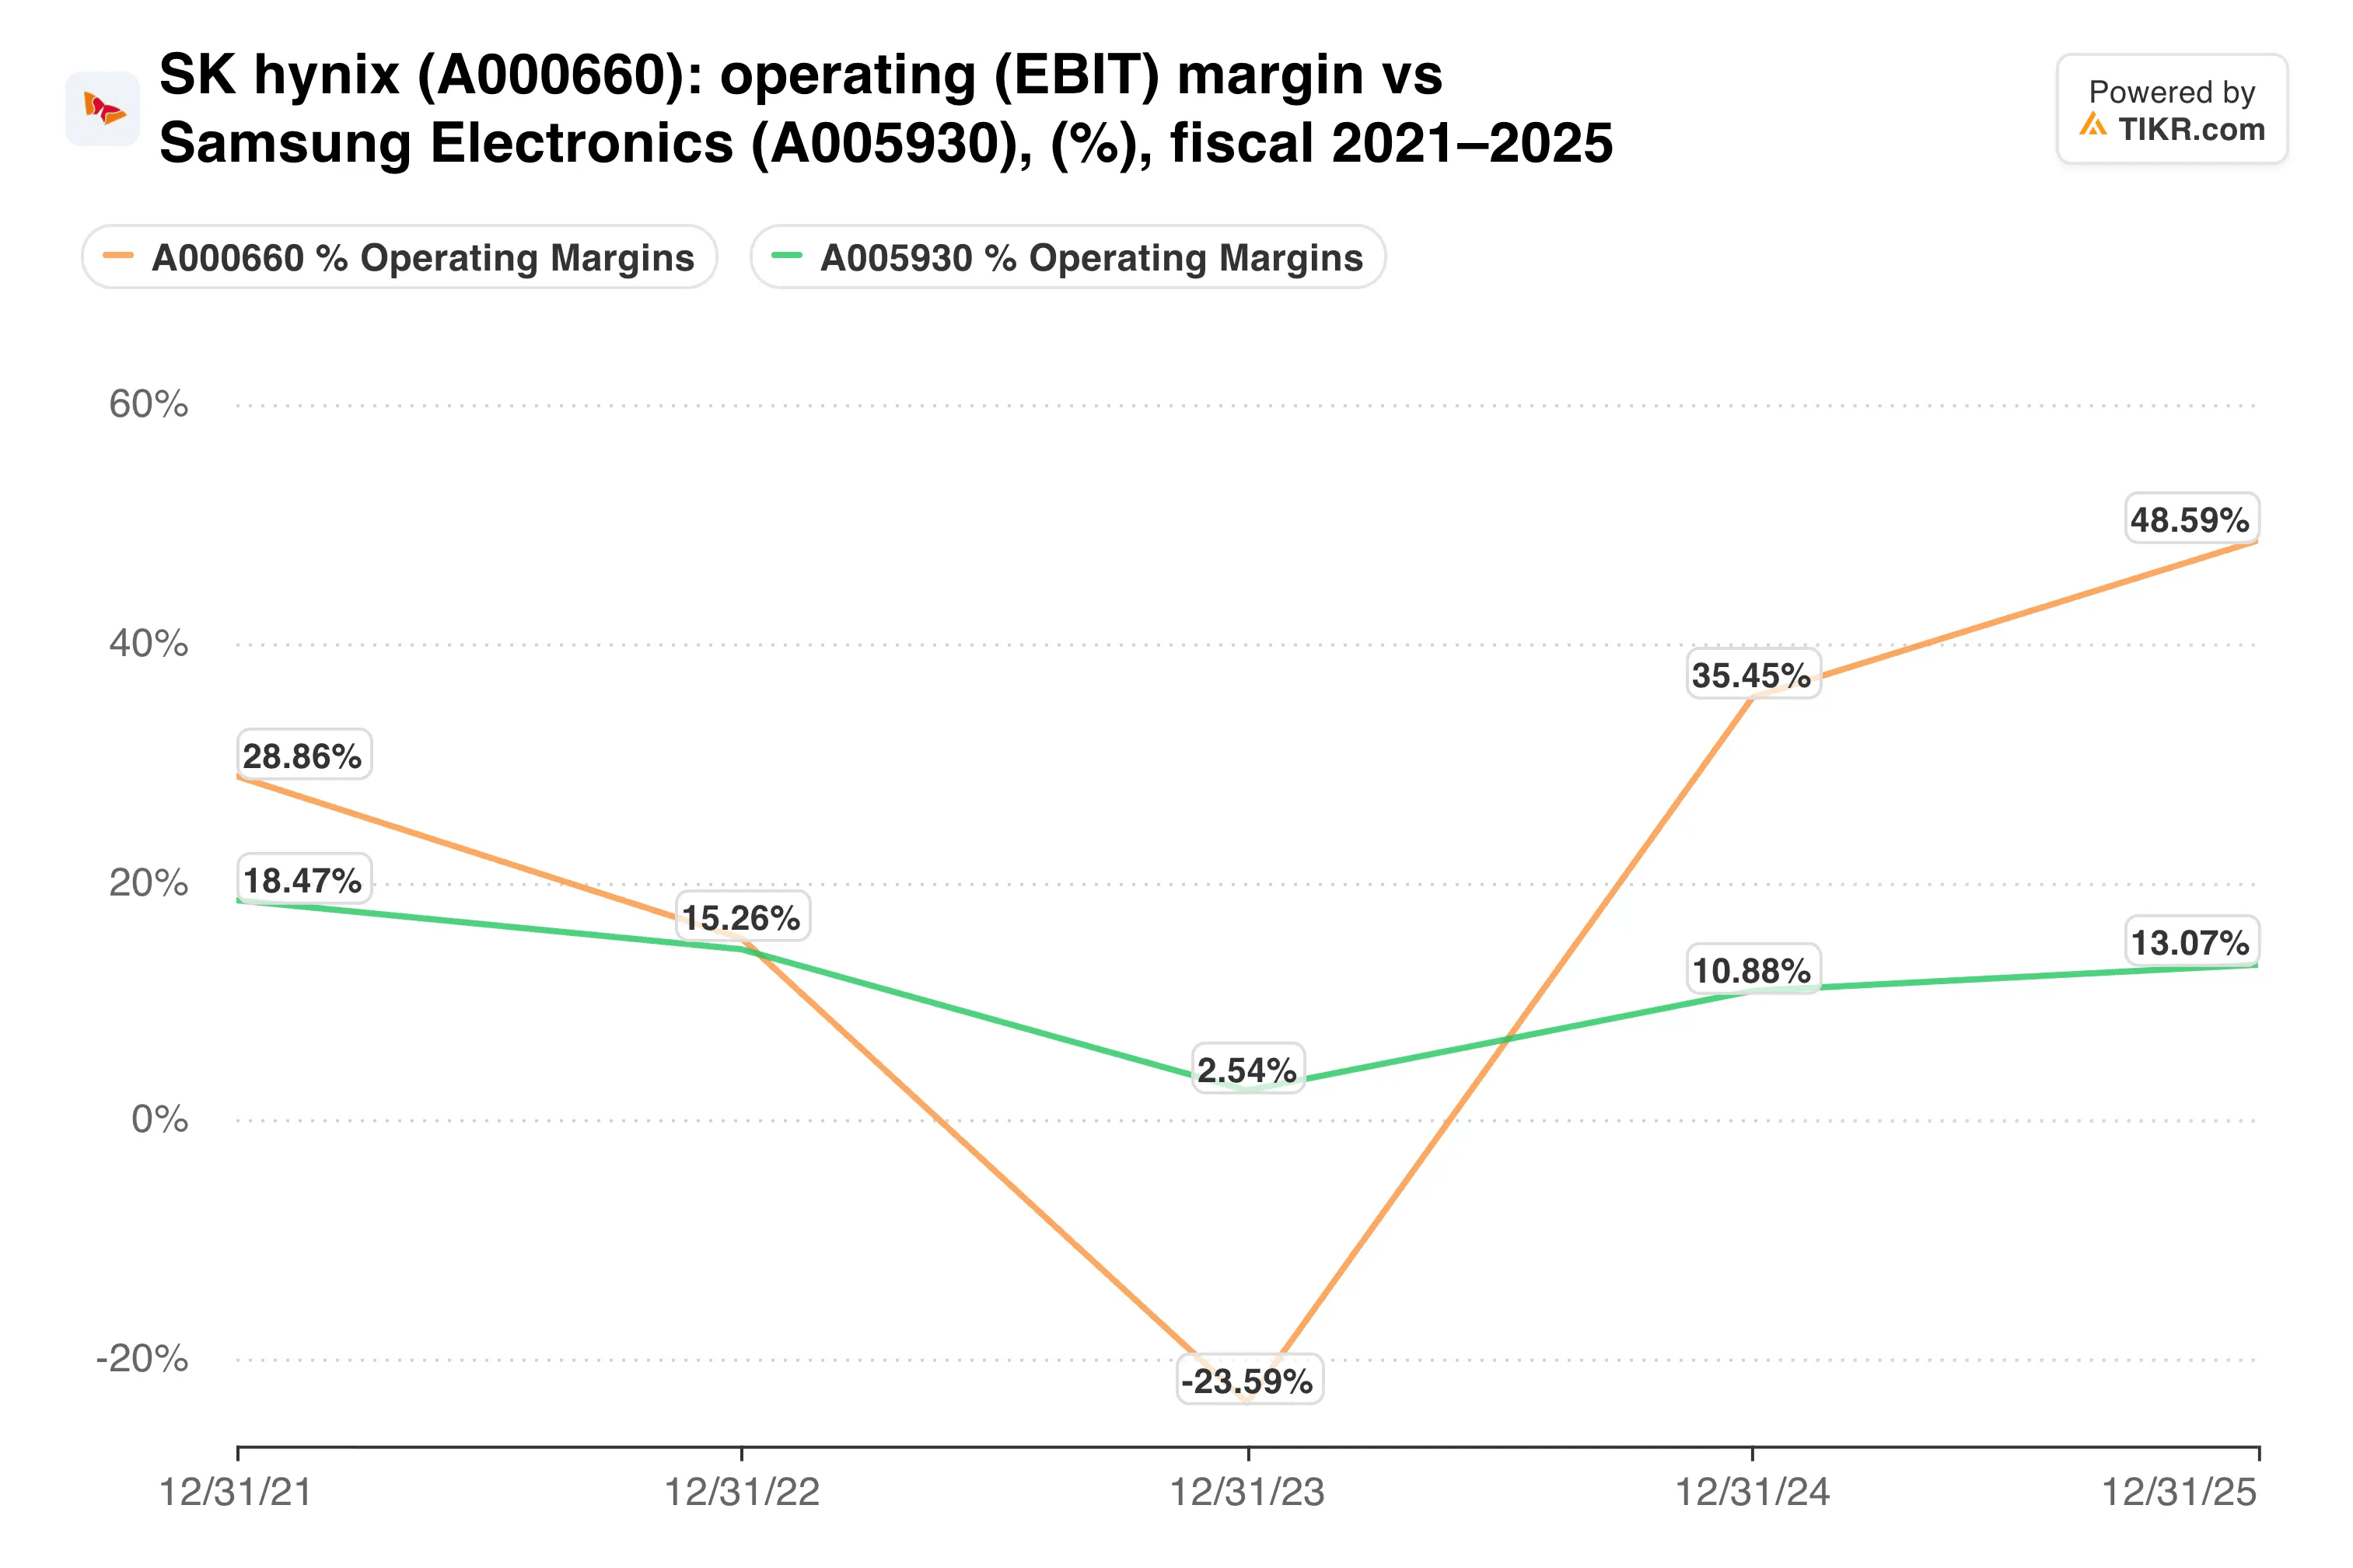
Samsung still carries phones, displays and foundry inside its margin. SK hynix is close to a pure bet on memory pricing, which cuts both ways in a cycle.
TIKR tracks 16 analysts on SK hynix. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on SK hynix, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See SK hynix’s Analyst Ratings
The market is pricing a cliff
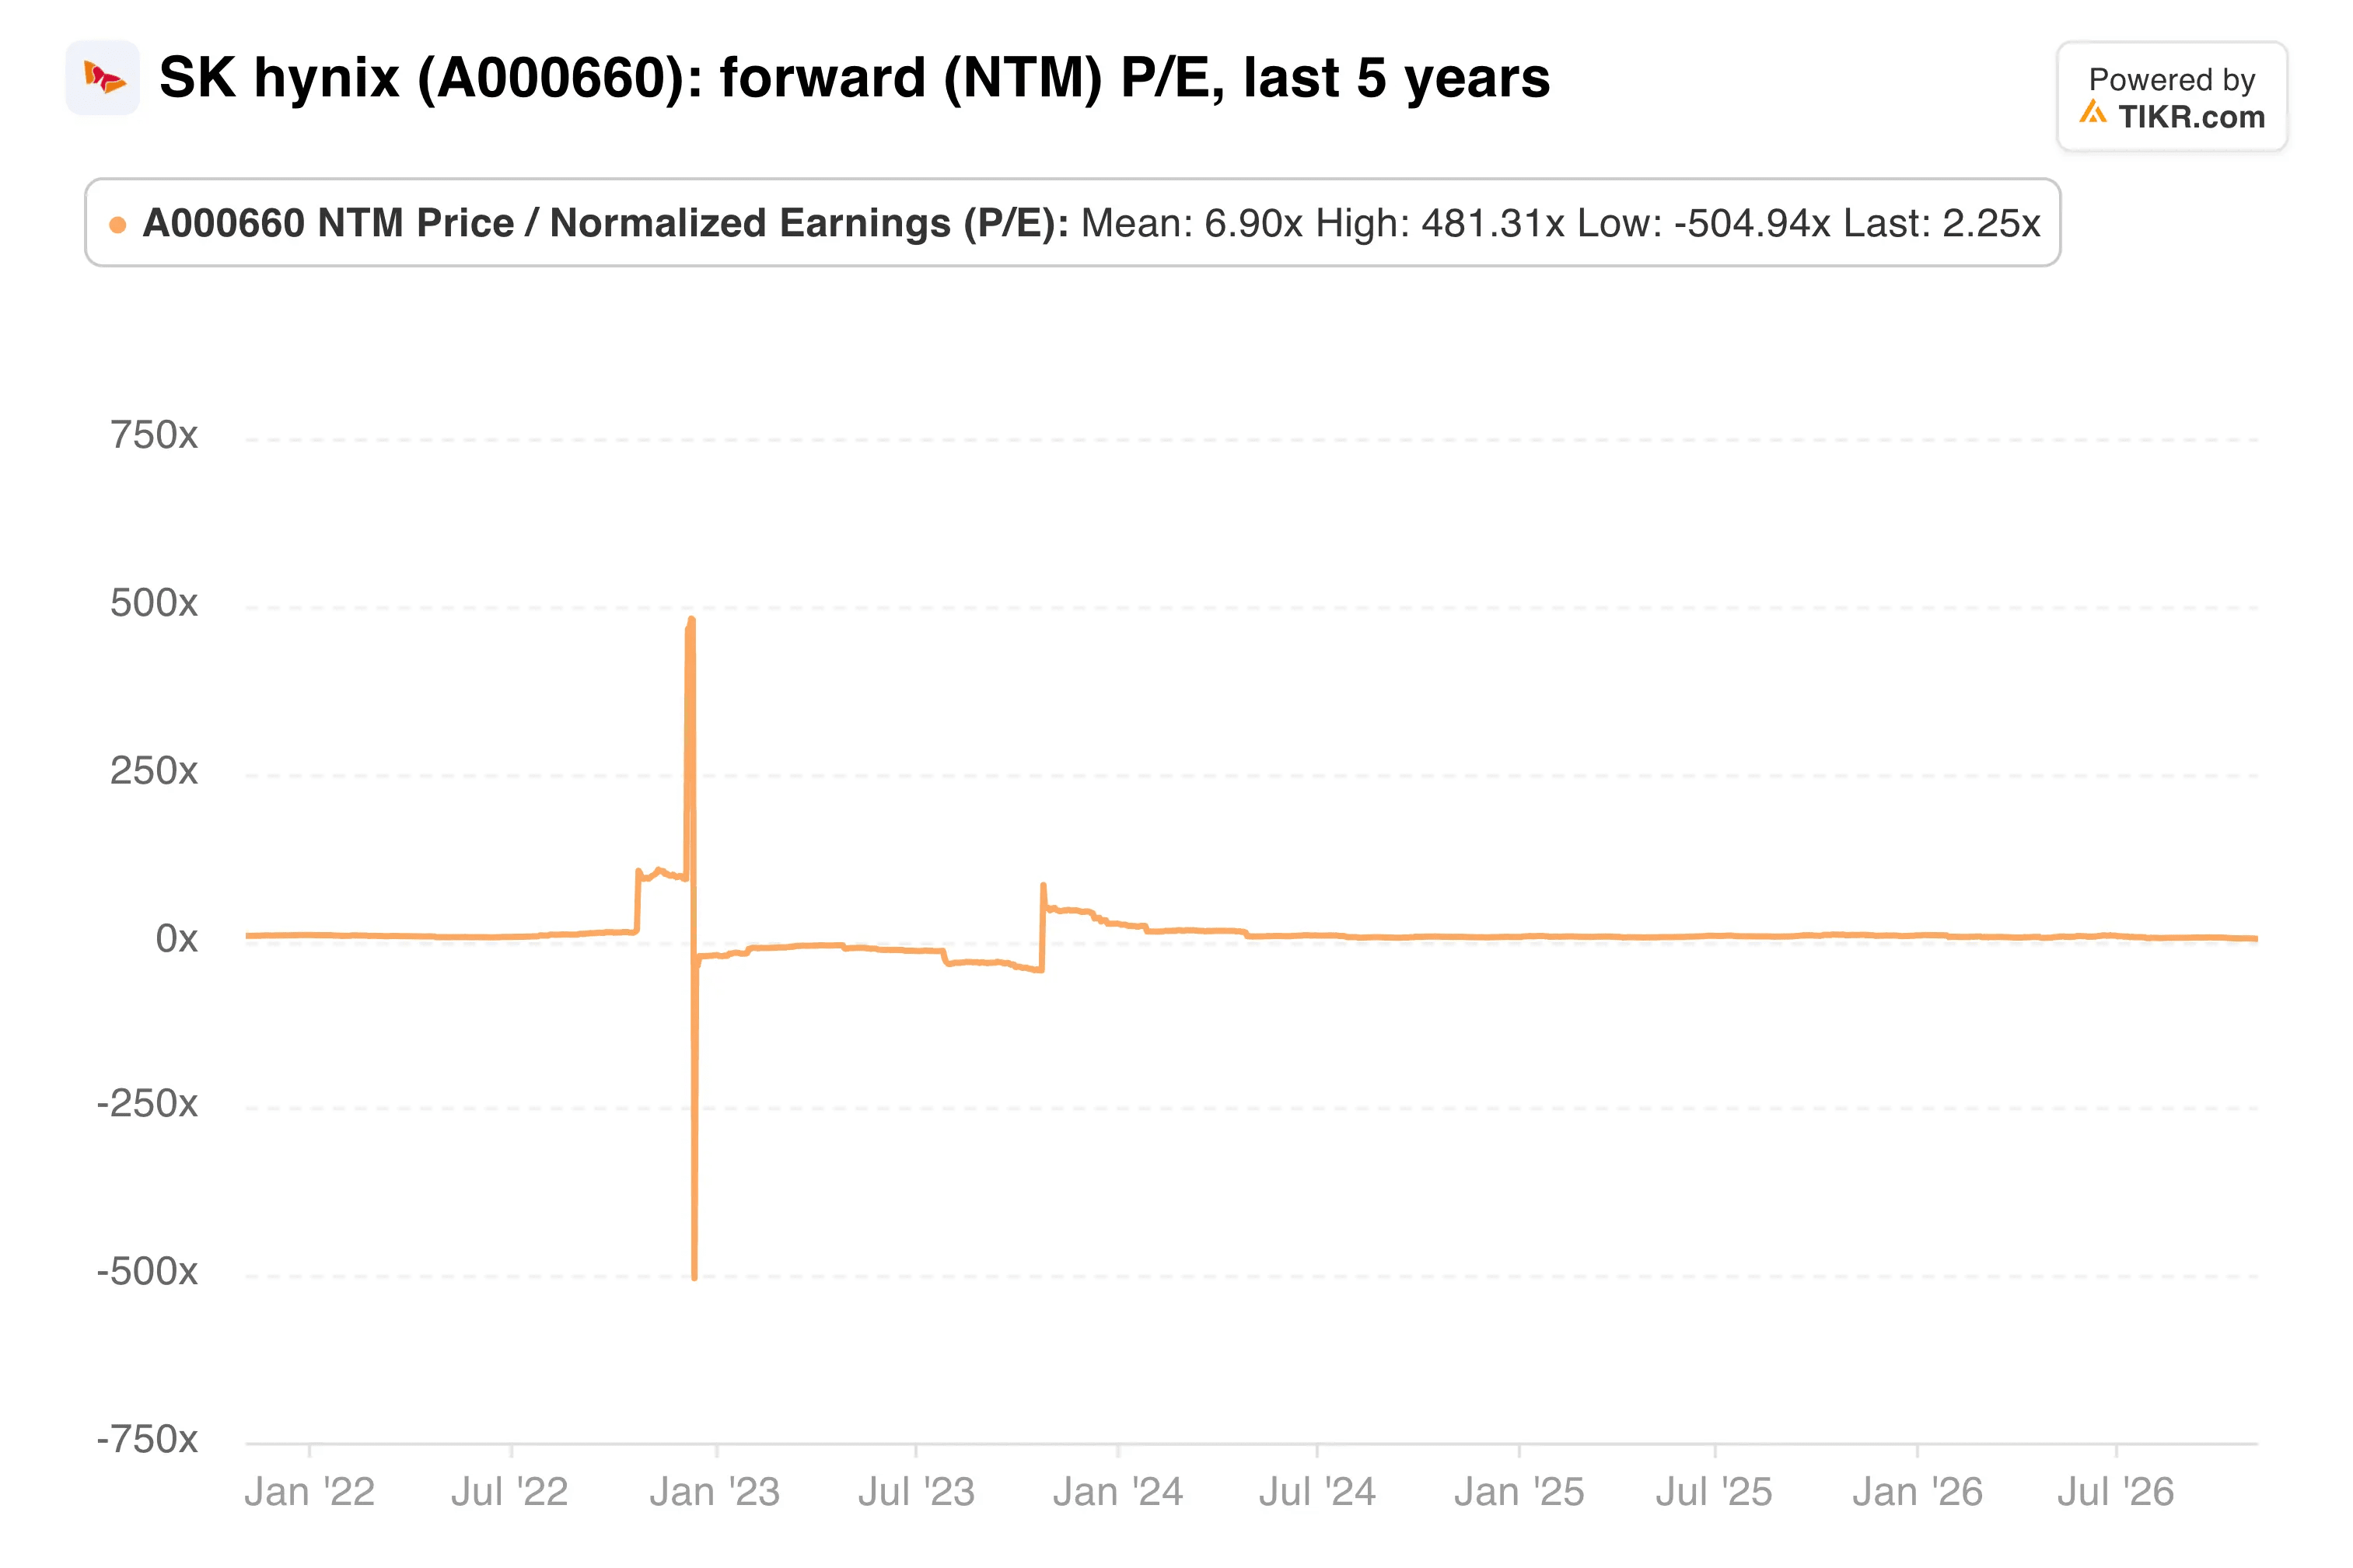
At 2.3x forward earnings and 4.3x trailing, the stock is priced as if these profits are about to vanish. The company also holds roughly $72.7 billion more cash than debt.
The average Street target of about $2,325 a share, in dollar terms, implies 180% upside from Friday’s close.
The multiple has rarely looked like this…
Even so, the risks are real. SK hynix’s China fabs need annual US approval for American equipment, and Washington has signaled it won’t approve gear that meaningfully expands capacity there. Capex is also set to rise significantly in 2027 from the high KRW 40 trillion range this year, and memory makers have overbuilt before.
My take: The selloff looks driven by sentiment more than by anything in the numbers. Contracts covering half of 2027 and 2028 make this cycle sturdier than past ones. Still, a 2.3x multiple tells you the market believes peak margins don’t last, and history mostly supports that view.
The January 28 report is the next hard check. Watch whether the DRAM shipment guidance held and how big the 2027 capex number gets.
So what is SK Hynix stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what SK Hynix could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!