Key Takeaways
- Social Security lets you withdraw a retirement claim once, in writing, within 12 months of first being entitled to benefits, as long as you repay what you received.
- A hypothetical worker with a $2,000 full-retirement-age benefit who claimed $1,400 a month at 62 could withdraw now, wait, and collect $2,480 a month at 70.
- Once the 12 months are up, the best fix left is to suspend benefits at 67, which reaches only $1,736 a month at 70, or $8,928 a year less.
- The do-over means repaying $14,000 after 10 checks. Anyone who claimed at 62 early this year has until this winter to file the request.
If you started Social Security at 62 this year and already regret it, I have some good news: you can still undo it. Social Security lets you take back a claim once and file again later for a bigger check.
The catch is the clock. You have 12 months from the first month you were entitled to benefits. For anyone who claimed early this year, that window closes this winter.
Two paths from the same $1,400 check
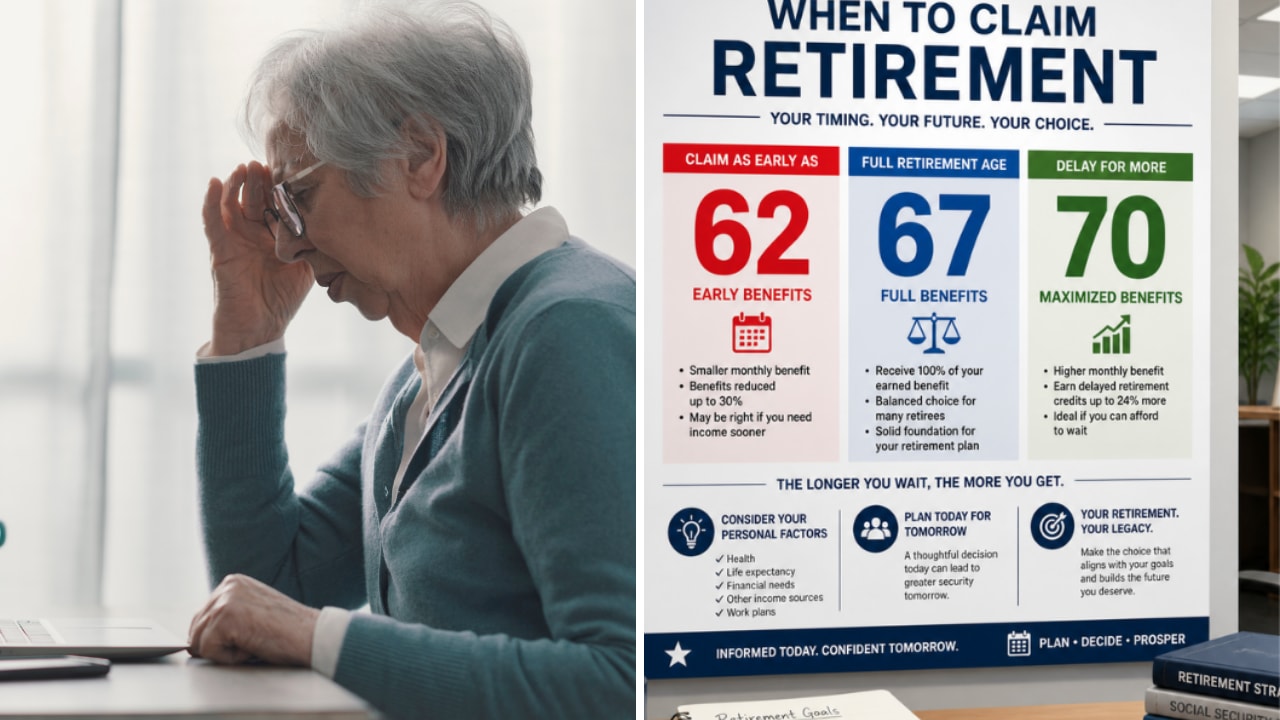
Let’s take a hypothetical: you were born in 1964, your benefit at full retirement age is $2,000 a month, and you claimed at 62 early this year. For anyone born in 1960 or later, the Social Security Administration sets full retirement age at 67 and cuts a claim at 62 by 30% for life. So your check is $1,400, and you’ve received 10 of them.
Now you’ve changed your mind. Maybe you went back to work, or you found you don’t need the money yet. You have two ways to get a bigger check, and they end up $744 a month apart.
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours for free as part of our new investment report, which you can access right here.
A do-over you only get once
Under Social Security’s rules, you can withdraw a retirement claim within 12 months of the first month you were entitled, as long as you’ve never withdrawn one before. You have to ask in writing and repay the benefits you received. SSA’s page on withdrawals says that also covers anything paid to family members on your record and anything withheld from your checks, such as taxes. After that, you can apply again whenever you like.
The other option is a suspension. Between full retirement age and 70, you can ask SSA to stop your checks and earn delayed retirement credits for every month they’re stopped. Those credits add 8% a year, and your payments start again automatically at 70.
But a suspension builds on the check you already have. The 30% cut for claiming at 62 stays, and the credits are added on top of the reduced amount.
$744 a month, for life
Here’s how the two paths compare for our 1964-born retiree:
| Metric | Withdraw within 12 months | Suspend at 67 |
|---|---|---|
| Benefit the credits build on | $2,000 | $1,400 |
| Credits, 67 to 70 | 24% | 24% |
| Monthly check at 70 | $2,480 | $1,736 |
| Cost up front | Repay $14,000 | None |
If you withdraw, you pay back the $14,000 you’ve received so far (10 checks of $1,400) and claim again at 70. Three years of credits past 67 at 8% a year add 24% to your full $2,000 benefit, which gets you to $2,480 a month.
If you suspend, you keep your $1,400 checks until 67 and then pause them for three years. The same 24% goes onto the reduced check, and you get $1,736 a month at 70.
That’s a gap of $744 a month, or $8,928 a year, for the rest of your life. Not bad at all.
Repaying $14,000 is the hard part
Coming up with $14,000 is a tall order, and it’s hardest for the people who claimed at 62 because they needed the money. If that’s you, the withdrawal may simply be out of reach.
There’s a second cost too. The suspension path keeps paying you until 67: 60 checks of $1,400 come to $84,000, counting the 10 you already have. After repaying, the withdrawal path leaves you with nothing until 70. At $744 a month, it takes about 113 months, or a bit over nine years, to make up that $84,000. So the withdrawal only comes out ahead if you live past about 79.
The way I see it, if you can cover the repayment without draining your emergency fund and your family tends to live into their 80s, this is one of the best deals Social Security offers. A bigger check for life is also the best protection against outliving your savings.
What to do before the window closes
The request goes on Form SSA-521, Request for Withdrawal of Application. You can mail it to Social Security or bring it to a local office. The 12 months run from the first month you were entitled to benefits, and you only get one withdrawal ever, so don’t spend it on a claim you might want to take back later.
Once you repay, your checks stop, and you can choose your new start date. Waiting until 70 gets you the full $2,480. Claiming sooner gets you less, but it’s still more than you’d get by suspending the reduced check.
Of course, only you know whether you can find the money and how long you’re likely to collect. But once this winter’s deadline passes, suspending at 67 is the only fix left.
Enjoy your retirement in style with these safe 6%+ dividend yields
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!