Key Takeaways
- Qualcomm rose 5.5% Friday after Alphabet disclosed a $548 million stake, days after weak handset sales hit the stock following earnings.
- Handset revenue fell 26% to $5.14 billion, while automotive revenue jumped 89% to a record $1.99 billion.
- CEO Cristiano Amon expects handset units to stay flat to down in calendar 2027, putting the burden on data centers and cars.
- The February 3 report, guided to $10.4 billion to $11.2 billion of revenue, is the next test.
Qualcomm (QCOM) got a vote of confidence from a new data center partner on Friday.
Alphabet (GOOGL) disclosed a $548 million stake in the chipmaker, and the shares rose 5.5% to $165. It came days after Qualcomm announced a multi-generational product collaboration with Amazon (AMZN) for AI data centers.
The bounce followed a rough week. Qualcomm slumped after its November 4 report as weak smartphone chip sales overshadowed data center momentum, and the broad chip selloff on November 5 piled on.
Even after Friday, the stock is down 13% over six months and 36% below its $260 52-week high.
Handsets fell, cars took off
The quarter split cleanly in two.
- Non-GAAP EPS of $2.17 edged past the $2.16 estimate but fell 28% from $3.00.
- Handset revenue dropped 26% to $5.14 billion.
- Automotive revenue rose 89% to a record $1.99 billion, its first quarter near $2 billion.
GAAP revenue fell 8% to $10.32 billion. Restructuring charges, mostly severance, pulled GAAP EPS down to $1.17.
Total revenue shows how much handsets still dominate…
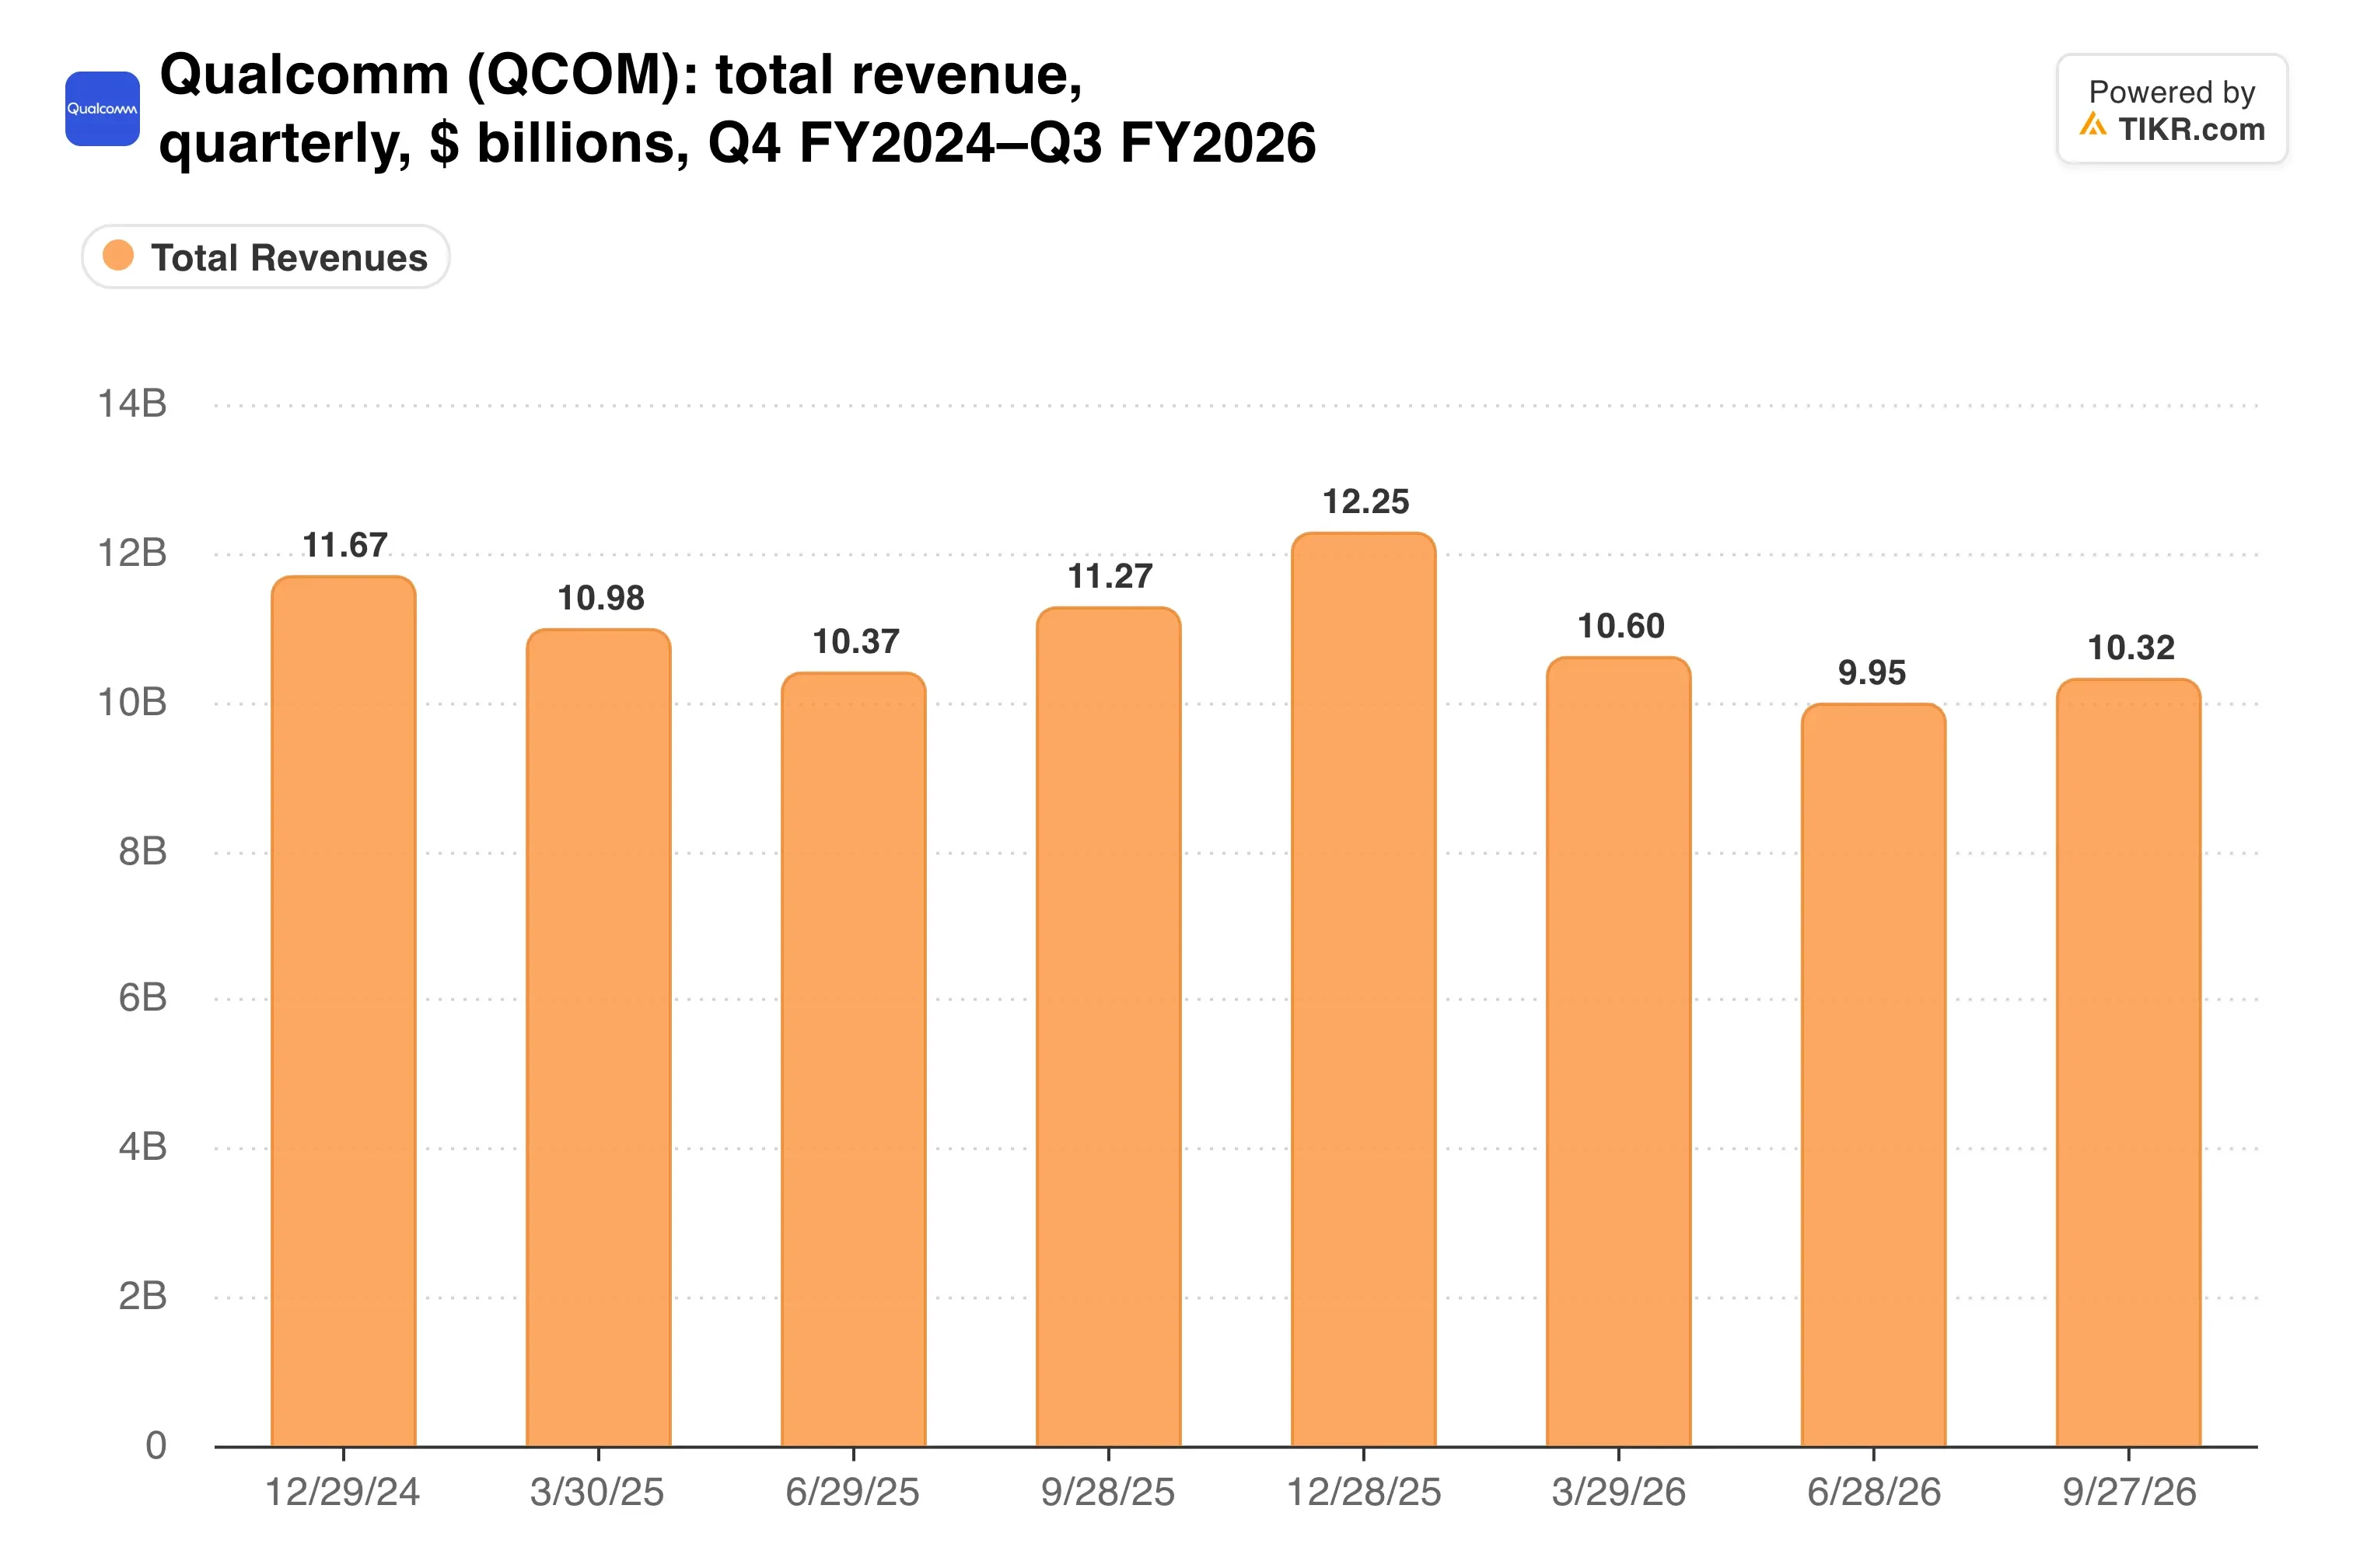
Revenue has now fallen year over year for consecutive quarters, so cars and data centers have a big hole to fill.
Betting on non-handset growth
Amon says the turn starts now. “Fiscal 2027 marks the start of our non-handset revenue inflection, including the ramp of our Data Center business,” he said in the earnings release.
Management projects non-handset revenue to grow more than 60% in fiscal 2027 and reiterated a $5 billion data center revenue target for the year. Qualcomm also renewed long-term licensing deals with Apple, Huawei and Transsion, which steadies the royalty side.
Alphabet’s stake is a signal more than a financial event. At $548 million, it equals about 0.3% of Qualcomm’s $177 billion market value.
Handsets will keep hurting. Amon said on the call that the plan assumes global handset units will remain flat to down in calendar 2027.
Can consensus growth survive that?
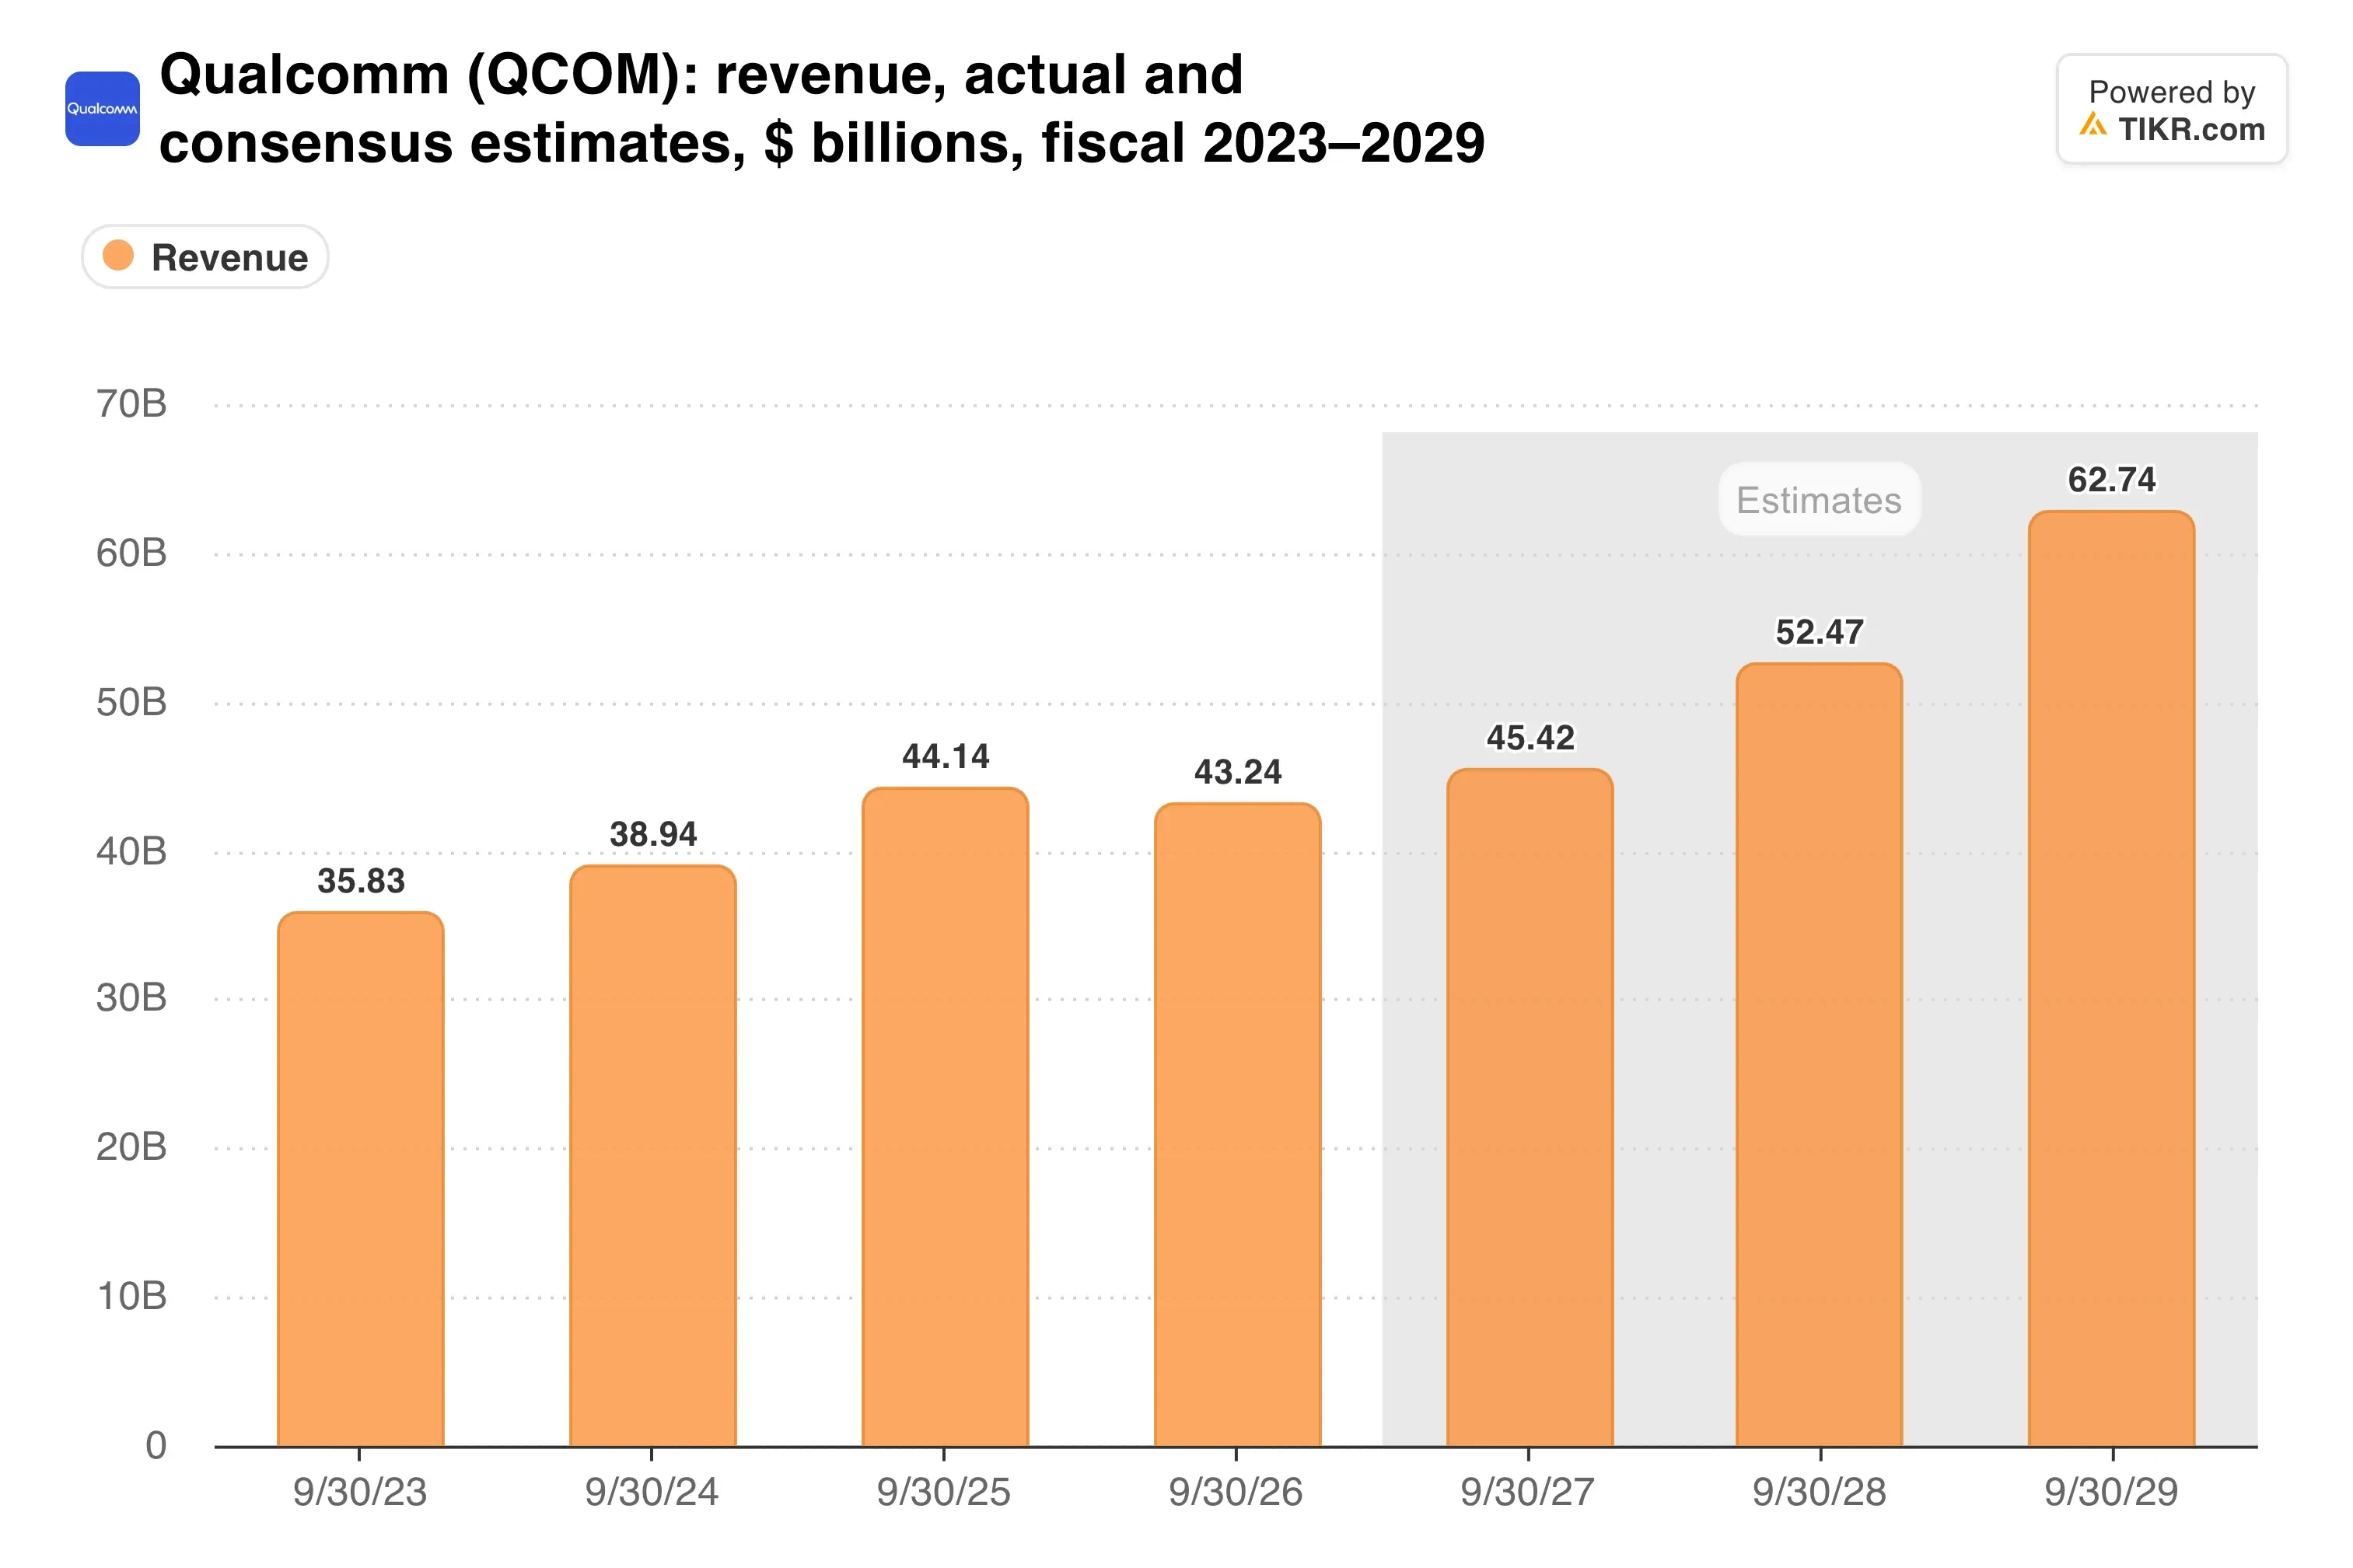
Analysts expect about 10% annual revenue growth over the next two years. That forecast leans heavily on the data center ramp showing up on time.
TIKR tracks 37 analysts on Qualcomm. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Qualcomm, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Qualcomm’s Analyst Ratings
Cheap, with a margin catch
Qualcomm trades at 16.7x forward earnings with a 2.3% dividend yield. Wall Street’s average target of $186 implies 12% upside.
Margins are the catch. Custom data center chips usually carry thinner margins than premium phone chips, and Qualcomm has flagged rising costs across wafers, packaging and memory.
First-quarter guidance shows the squeeze. Revenue of $10.4 billion to $11.2 billion topped estimates at the midpoint, yet non-GAAP EPS of $2.15 to $2.35 came in slightly below.
Here’s where profitability stands.
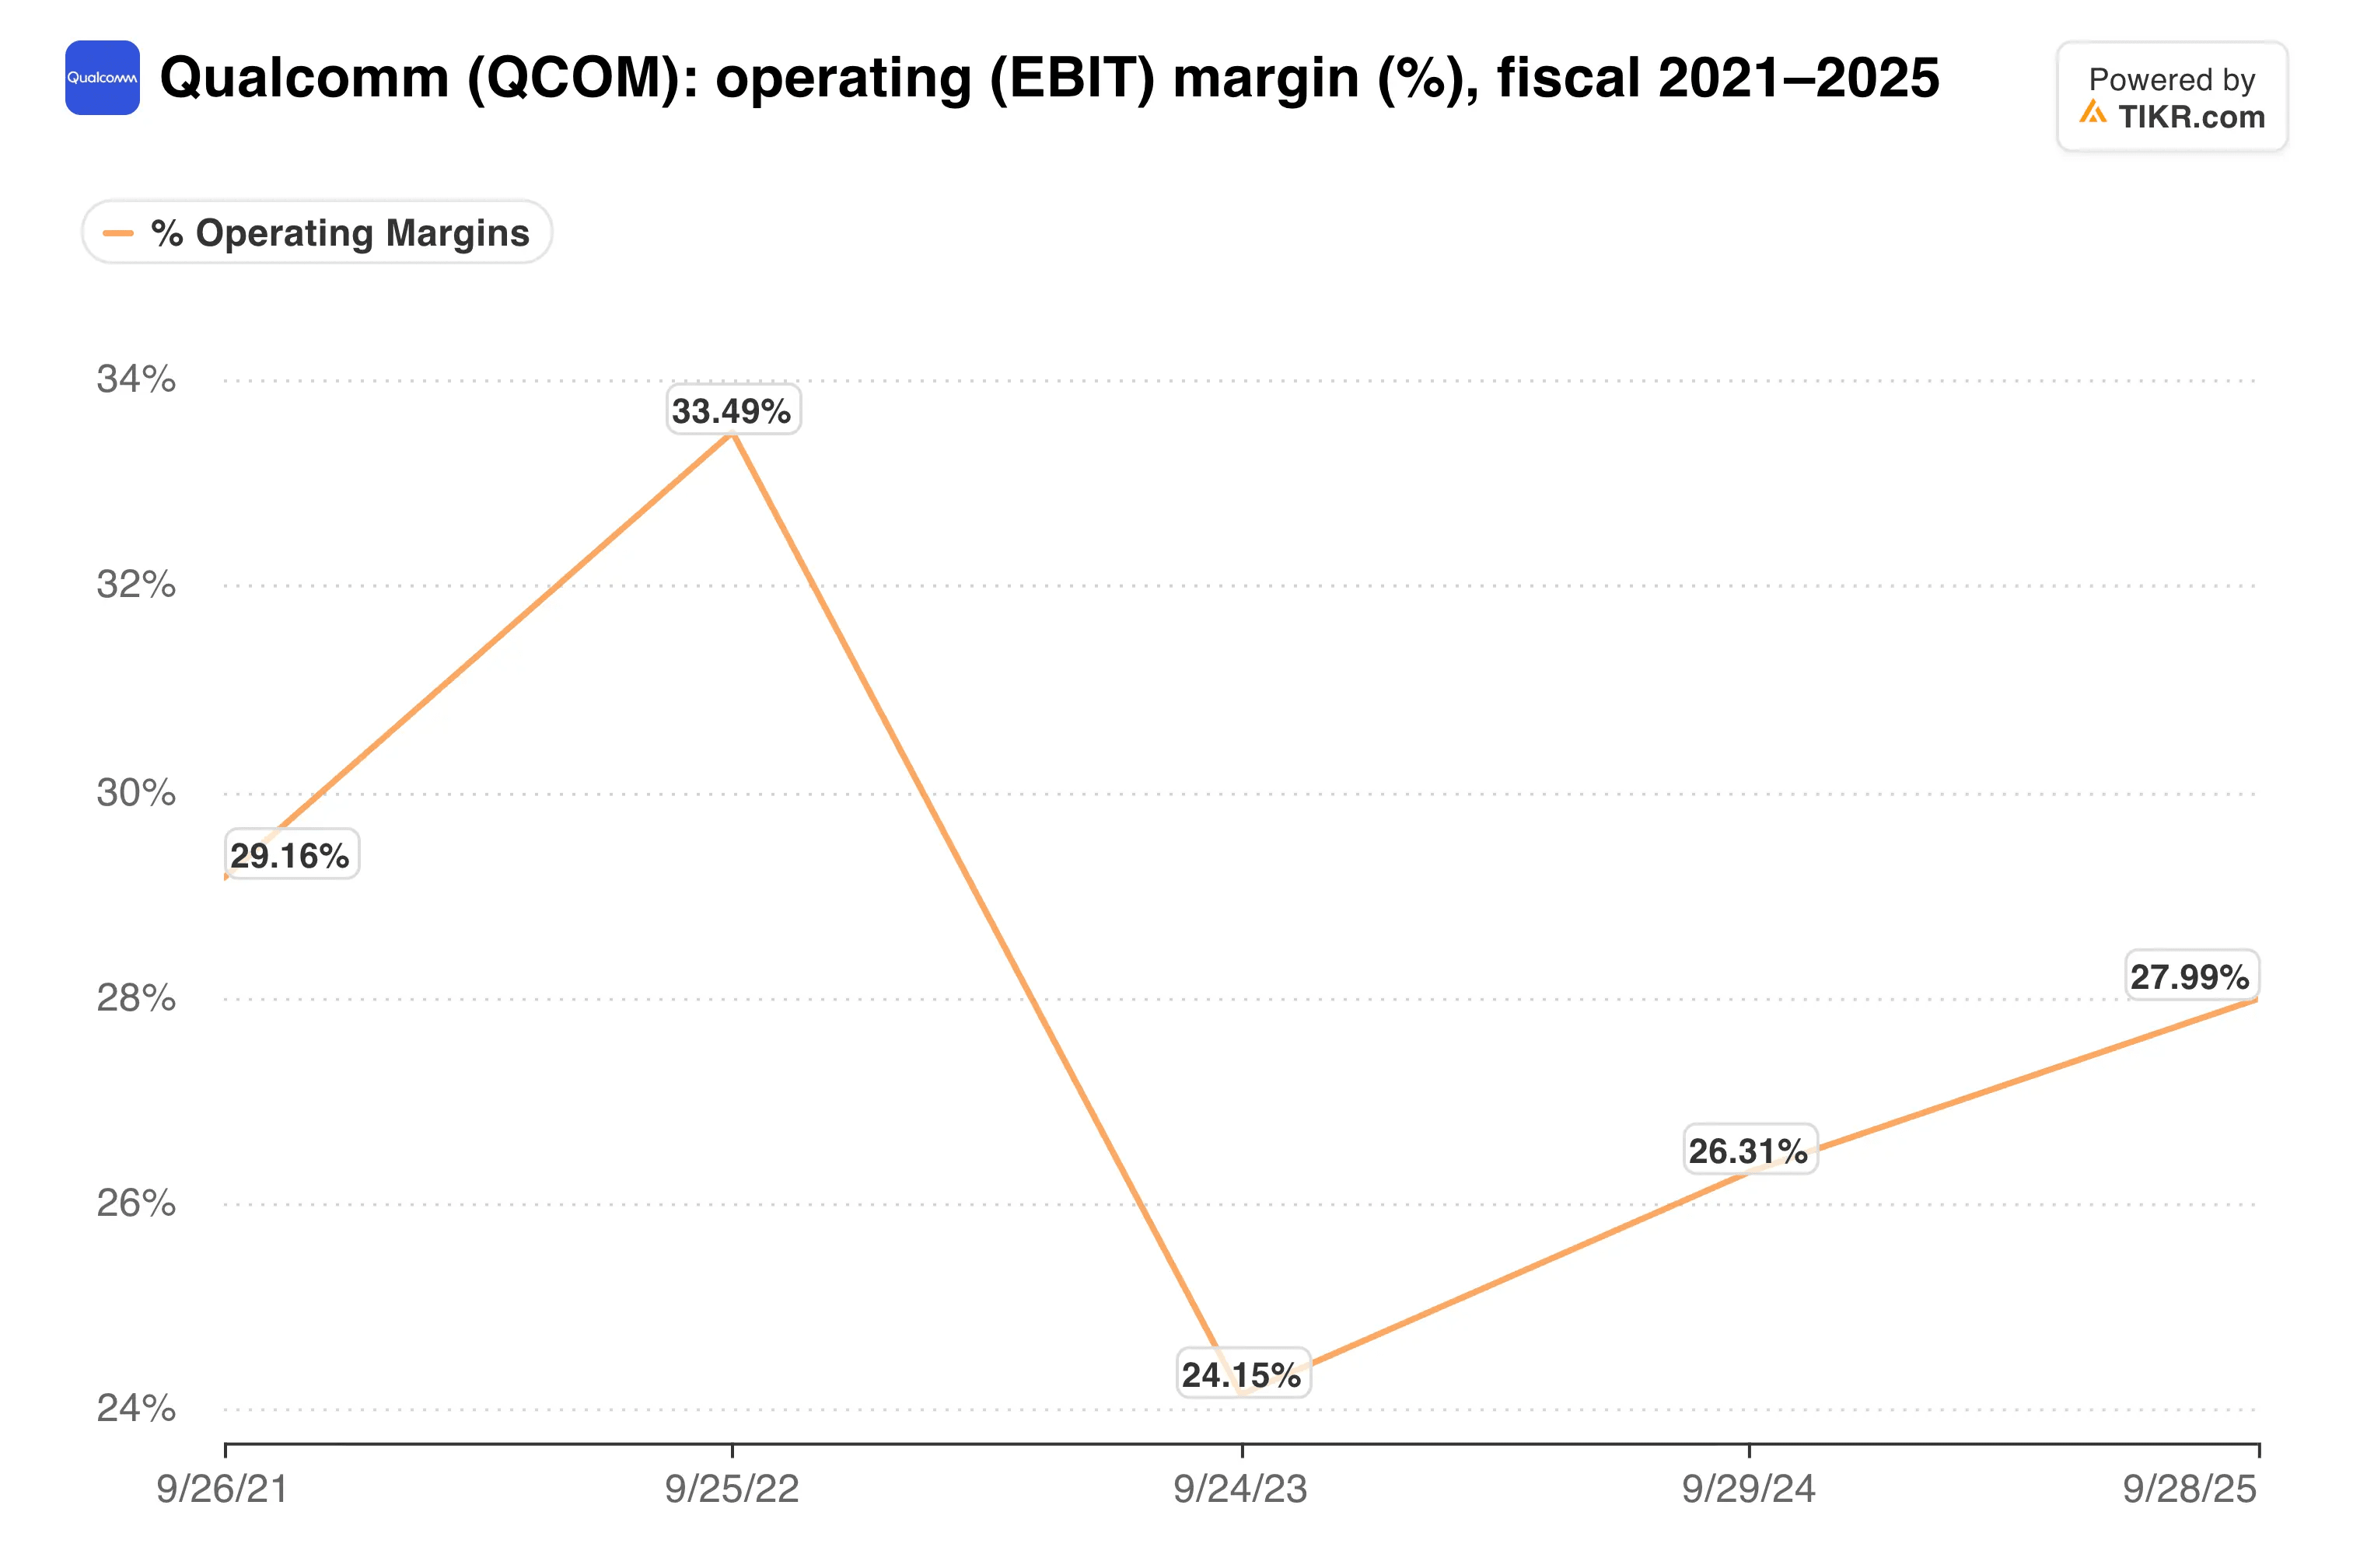
Trailing EBIT margin sits at 20.8%, and a heavier custom chip mix could press it further.
My take: Under 17x forward earnings prices Qualcomm like a shrinking phone supplier, while 89% auto growth and two hyperscaler ties point somewhere better. Still, the custom chip ramp could dilute margins before it lifts EPS. I’d buy in stages.
The February 3 report is the checkpoint. It will show whether data center revenue starts arriving at scale and whether the EPS guide holds against memory costs.
So what is Qualcomm stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Qualcomm could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!