

Key Takeaways
- A $22 billion hedge fund opened new positions in Amazon, Danaher and Meta in the third quarter, and they’re now its three largest holdings.
- The three made up 22% of its 13F stocks at Sept. 30.
- Since then, Amazon is up 7% and Danaher 3%, while Meta has fallen 15%.
- Amazon is the one the numbers back best, with rising earnings estimates and a forward P/E near the low of its own history.
A $22 billion hedge fund just filled the top of its portfolio with three stocks it didn’t own at the end of June.
Lone Pine Capital’s 13F for the quarter ended Sept. 30, filed Nov. 16, shows new positions in Amazon (AMZN), Danaher (DHR) and Meta Platforms (META) as its three biggest holdings. The firm manages $21.62 billion in all. Its 13F lists 31 positions worth $15.33 billion in US stocks at quarter-end prices, and 16 of them were new or added in the quarter.
Three new names, straight to the top
Amazon was the biggest: 5.60 million shares worth $1.39 billion at Sept. 30, or 9.1% of the fund’s 13F stocks. Danaher came next, with 4.94 million shares worth $1.10 billion (7.1%), then Meta, with 1.25 million shares worth $908 million (6%). Together, that’s 22% of everything in the 13F. The three stocks have gone different ways since the quarter ended: Amazon is up 7% and Danaher 3%, while Meta has fallen 15%.
TIKR tracks 62 analysts on Amazon. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Amazon, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Amazon’s Analyst Ratings
Amazon’s estimates keep climbing
For Amazon, it’s all about AWS, whose revenue grew 39% in the third quarter, its fastest pace in five years. That growth costs a lot. Management has guided to about $220 billion of capital spending in 2026, up from $128.3 billion in 2025. Analysts expect free cash flow to stay negative this year and next, then turn positive in 2028.
Analysts are looking past the spending. Their 2028 normalized EPS estimate rose 24% in the year to late October, and it’s $13.99 now. Even so, the stock trades at about 27x forward earnings. That’s right around its lowest quarter-end reading since TIKR’s record begins in 2014 (27x, in March) and far below its five-year average of 49x.
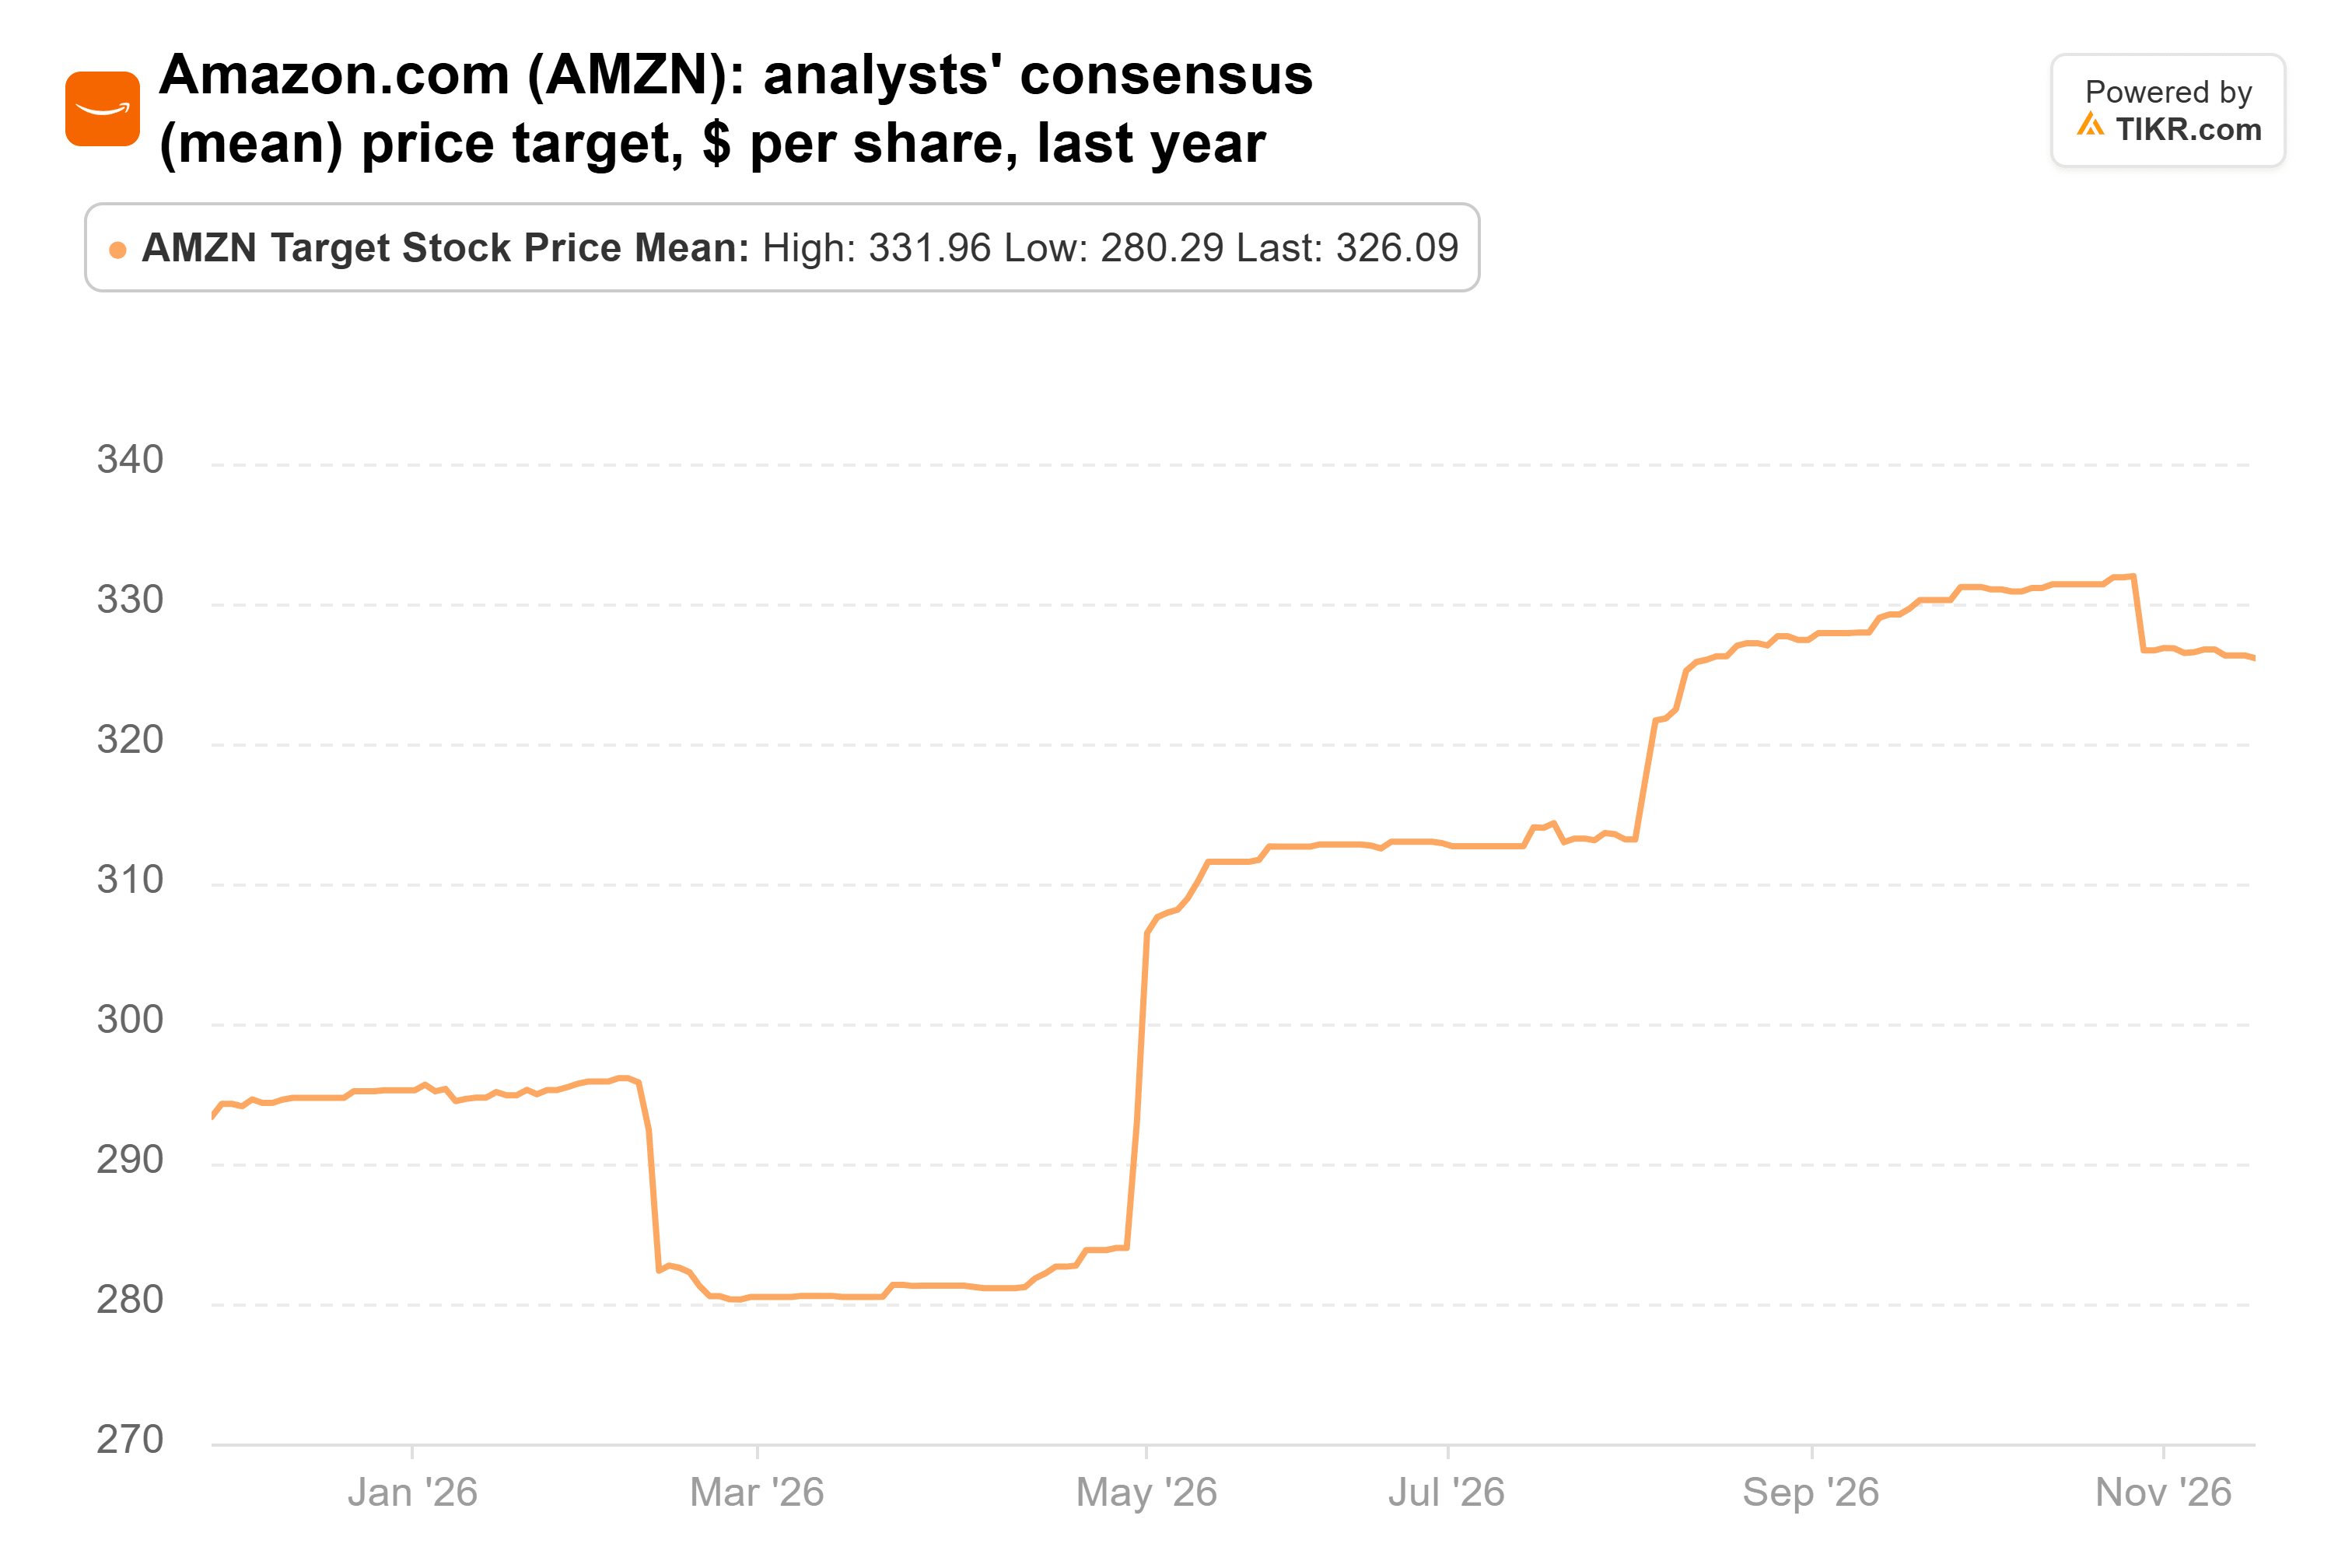
The Street’s average target has climbed with the estimates, from $293 a year ago to $326 now. That’s 22% above today’s price, from 61 analysts:
Danaher raised the bar
Danaher grows more slowly, but its numbers are moving the right way too. The company beat in the third quarter as trends improved across its end markets: revenue rose 8.5% to $6.6 billion, and adjusted EPS rose 11.5% to $2.11. Core revenue grew 3.0%, or 5.5% without respiratory testing. Management expects that second measure to grow 4% to 5% in the fourth quarter. It also lifted its full-year adjusted EPS guidance to $8.57-$8.62 from $8.45-$8.60.
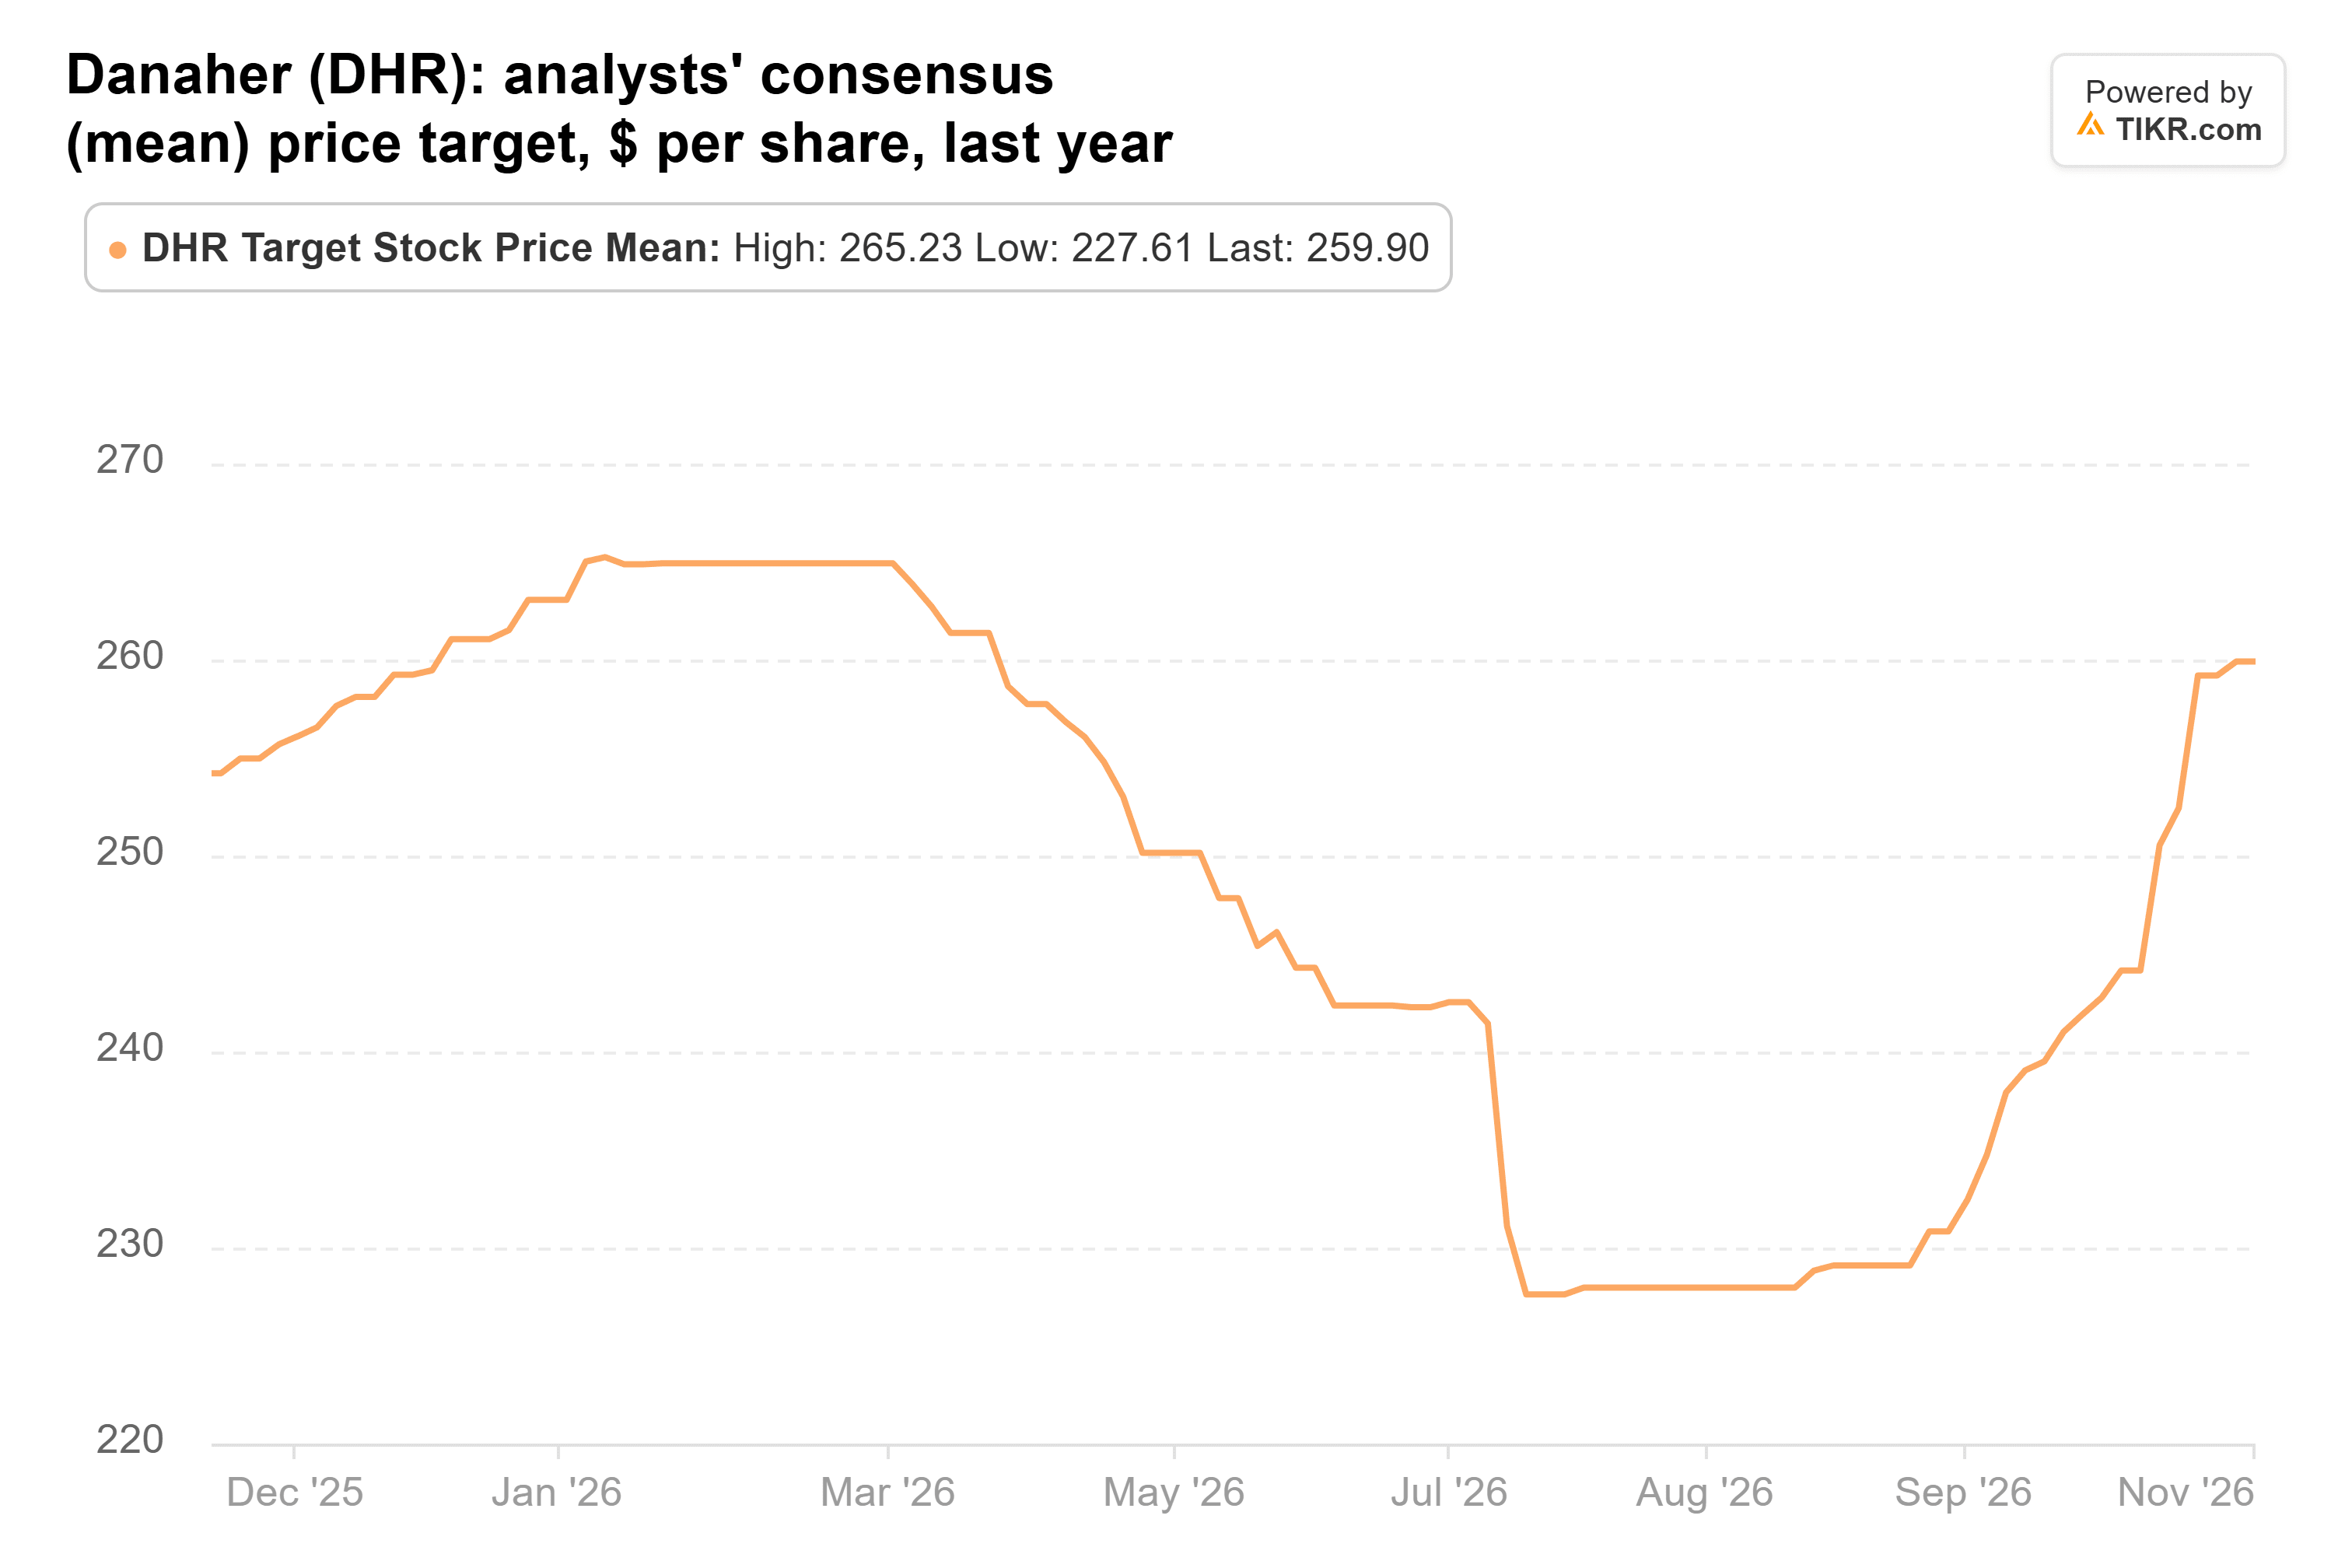
The stock trades at about 25x forward earnings. In July, the Street’s average target fell to $228, down from a January high of $265. It has since climbed back to $260, 14% above today’s price, from 24 analysts:
Meta has the upside and the bills
Meta has had the roughest stretch since Sept. 30. In the third quarter, revenue rose 26% to $64.6 billion, but capital spending of $34.9 billion was more than the $32.8 billion of cash its operations brought in. On Oct. 21, a New Mexico court ordered a $25 billion penalty, which Meta will appeal. Analysts have cut their 2027 earnings estimates 4% since the end of June, and consensus now has free cash flow bottoming at negative $48.0 billion in 2027.
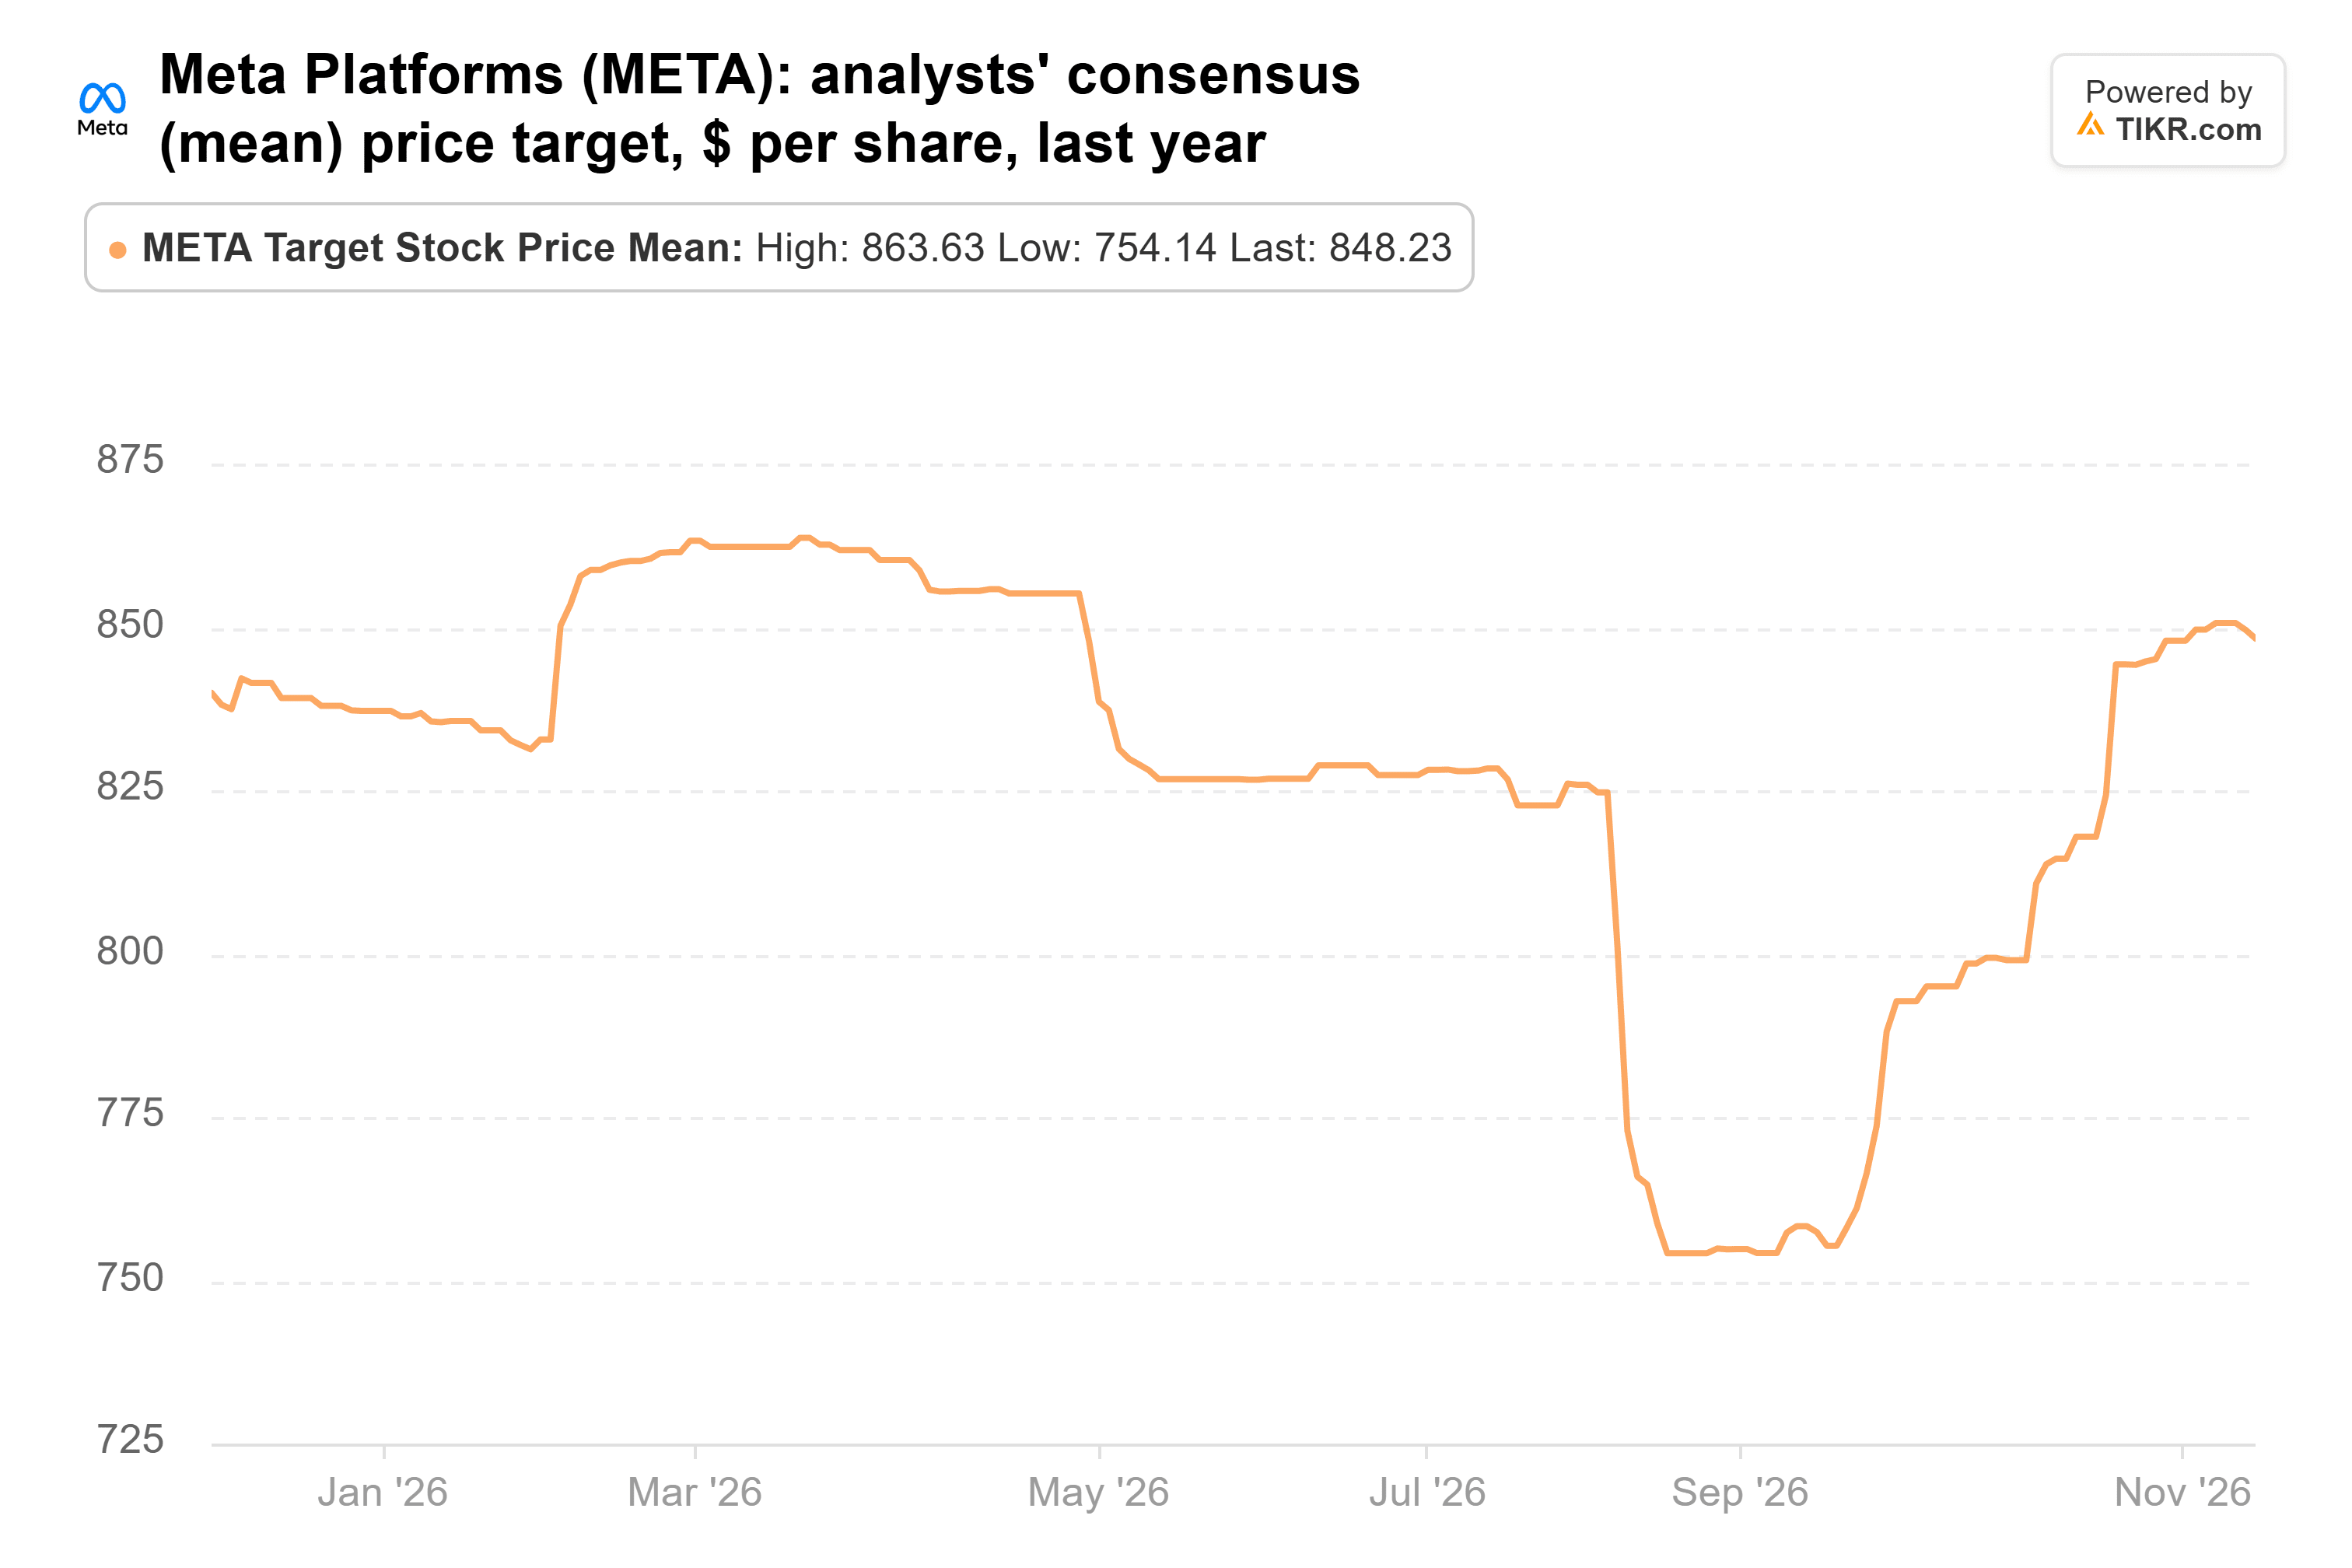
The stock is cheap against its own history: about 19x forward earnings, below its five-year average of 21x and its 10-year average of 23x. And analysts haven’t given up on it. Their average target is $848, from 62 analysts. That’s 38% above today’s price and a touch above where it stood a year ago:
The fund has company here, too: Third Point’s two largest positions at Sept. 30 were new ones in Meta and Unum, even as it sold all of its Amazon.
Amazon gets my vote
If I could only follow this fund into one of the three, it’d be Amazon. Its estimates are rising, its multiple sits near the bottom of its range, and AWS is growing faster than it has in five years. Meta has more upside on paper, but its estimates are falling while the cash goes out the door. Danaher’s raised guidance is encouraging, though its 14% upside is the smallest here.
The risk with Amazon comes from the same spending that drives the case: its long-term debt doubled to $128.9 billion in the first half of 2026. Fourth-quarter results in early February will bring the 2027 capital spending outlook. Analysts expect $278.2 billion, and a figure below that with AWS growth holding would bring the cash turn closer. The fund’s next 13F, due in mid-February, will show whether it still holds all three.
So what is Amazon stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Amazon could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


