Key Takeaways
- Antipodes Partners, a firm that manages $14.63 billion, added to its stakes in Meta Platforms (META), NiSource (NI) and Enbridge (ENB) in Q3, as its latest 13F filing shows.
- Meta was the biggest of the three, at 3.3% of the fund’s 13F holdings, and its shares have fallen 13% since Sept. 30.
- NiSource is up 17% since the quarter ended, which leaves analysts’ average target just 4% above the price.
- Meta is the one the numbers back best, though its AI spending now runs ahead of the cash its business brings in.
A fund that manages $14.63 billion just revealed that it added to three very different stocks: Meta Platforms, NiSource and Enbridge.
Antipodes Partners raised each stake by at least 31% in Q3, according to its 13F for the quarter ended Sept. 30, filed Nov. 5.
That filing covers only the firm’s US-listed stocks, $5.43 billion of them across 141 positions.
Meta got cheaper after the quarter ended
Meta was the biggest of the three. The fund raised its stake 35% to 245,897 shares, worth $178 million at Sept. 30. That was 3.3% of its 13F holdings and its fifth-largest position.
The stock has fallen 13% from its Sept. 30 close since then. Meta’s Q3 revenue rose 26% to $64.6 billion. But the $34.9 billion it spent on capital projects in the quarter was more than the $32.8 billion its operations brought in.
Analysts’ targets have barely moved. Their average has risen slightly over the past year, from $841.58 to $850.10, after a dip to $754.14 in August:
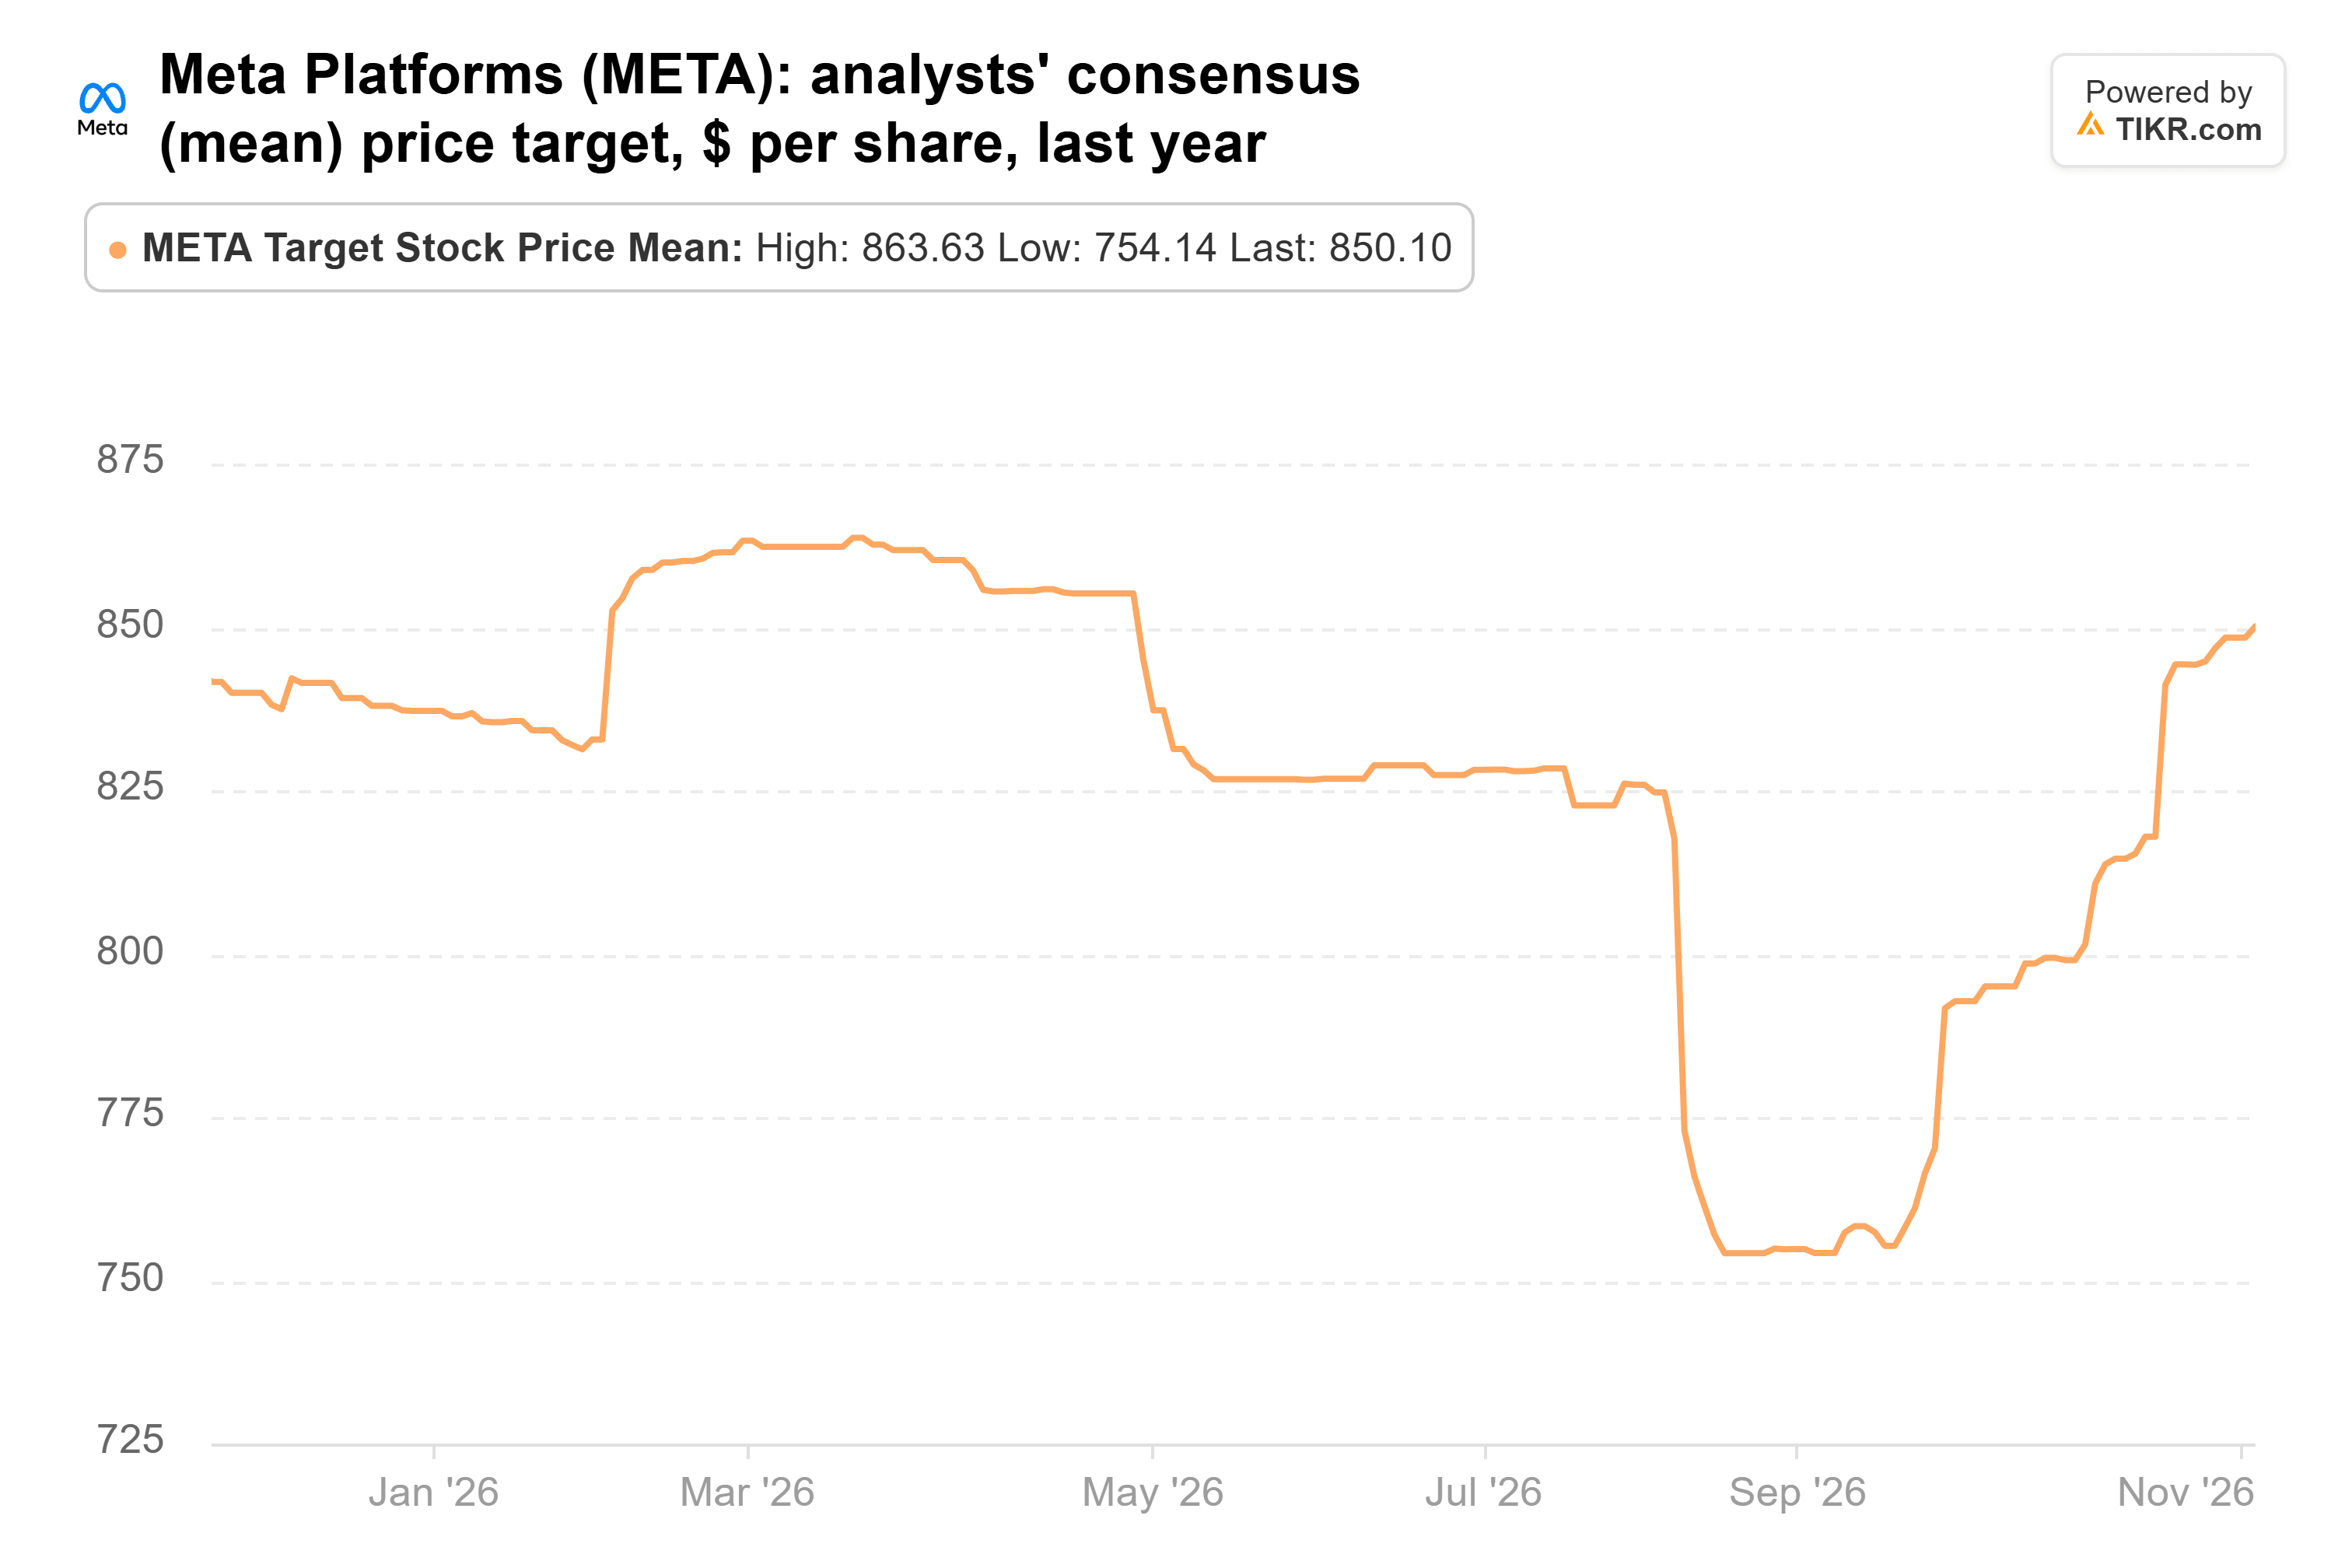
That $850.10 target sits 35% above Meta’s last close of $628.77, and 63 analysts cover the stock. At about 19x forward earnings, Meta also trades below its five-year average of 21x.
TIKR tracks 63 analysts on Meta Platforms. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Meta Platforms, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Meta Platforms’ Analyst Ratings
NiSource has already had its pop
The fund raised its NiSource stake 37% to 2.97 million shares, worth $116 million at Sept. 30, or 2.1% of its 13F holdings. Since then, the stock has jumped 17% from its Sept. 30 close.
During that stretch, on Oct. 16, NiSource announced a 20-year power deal with Microsoft. Starting in 2028, the deal adds about 1,100 MW of generation for a Microsoft data-center campus in northwest Indiana.
NiSource said Microsoft pays for all the generation and transmission needed to serve it. For a regulated utility, that’s a big new customer that pays its own way.
Analysts have raised their average target over the year, from $45.67 to $48.22, though it peaked at $51.36 in May:
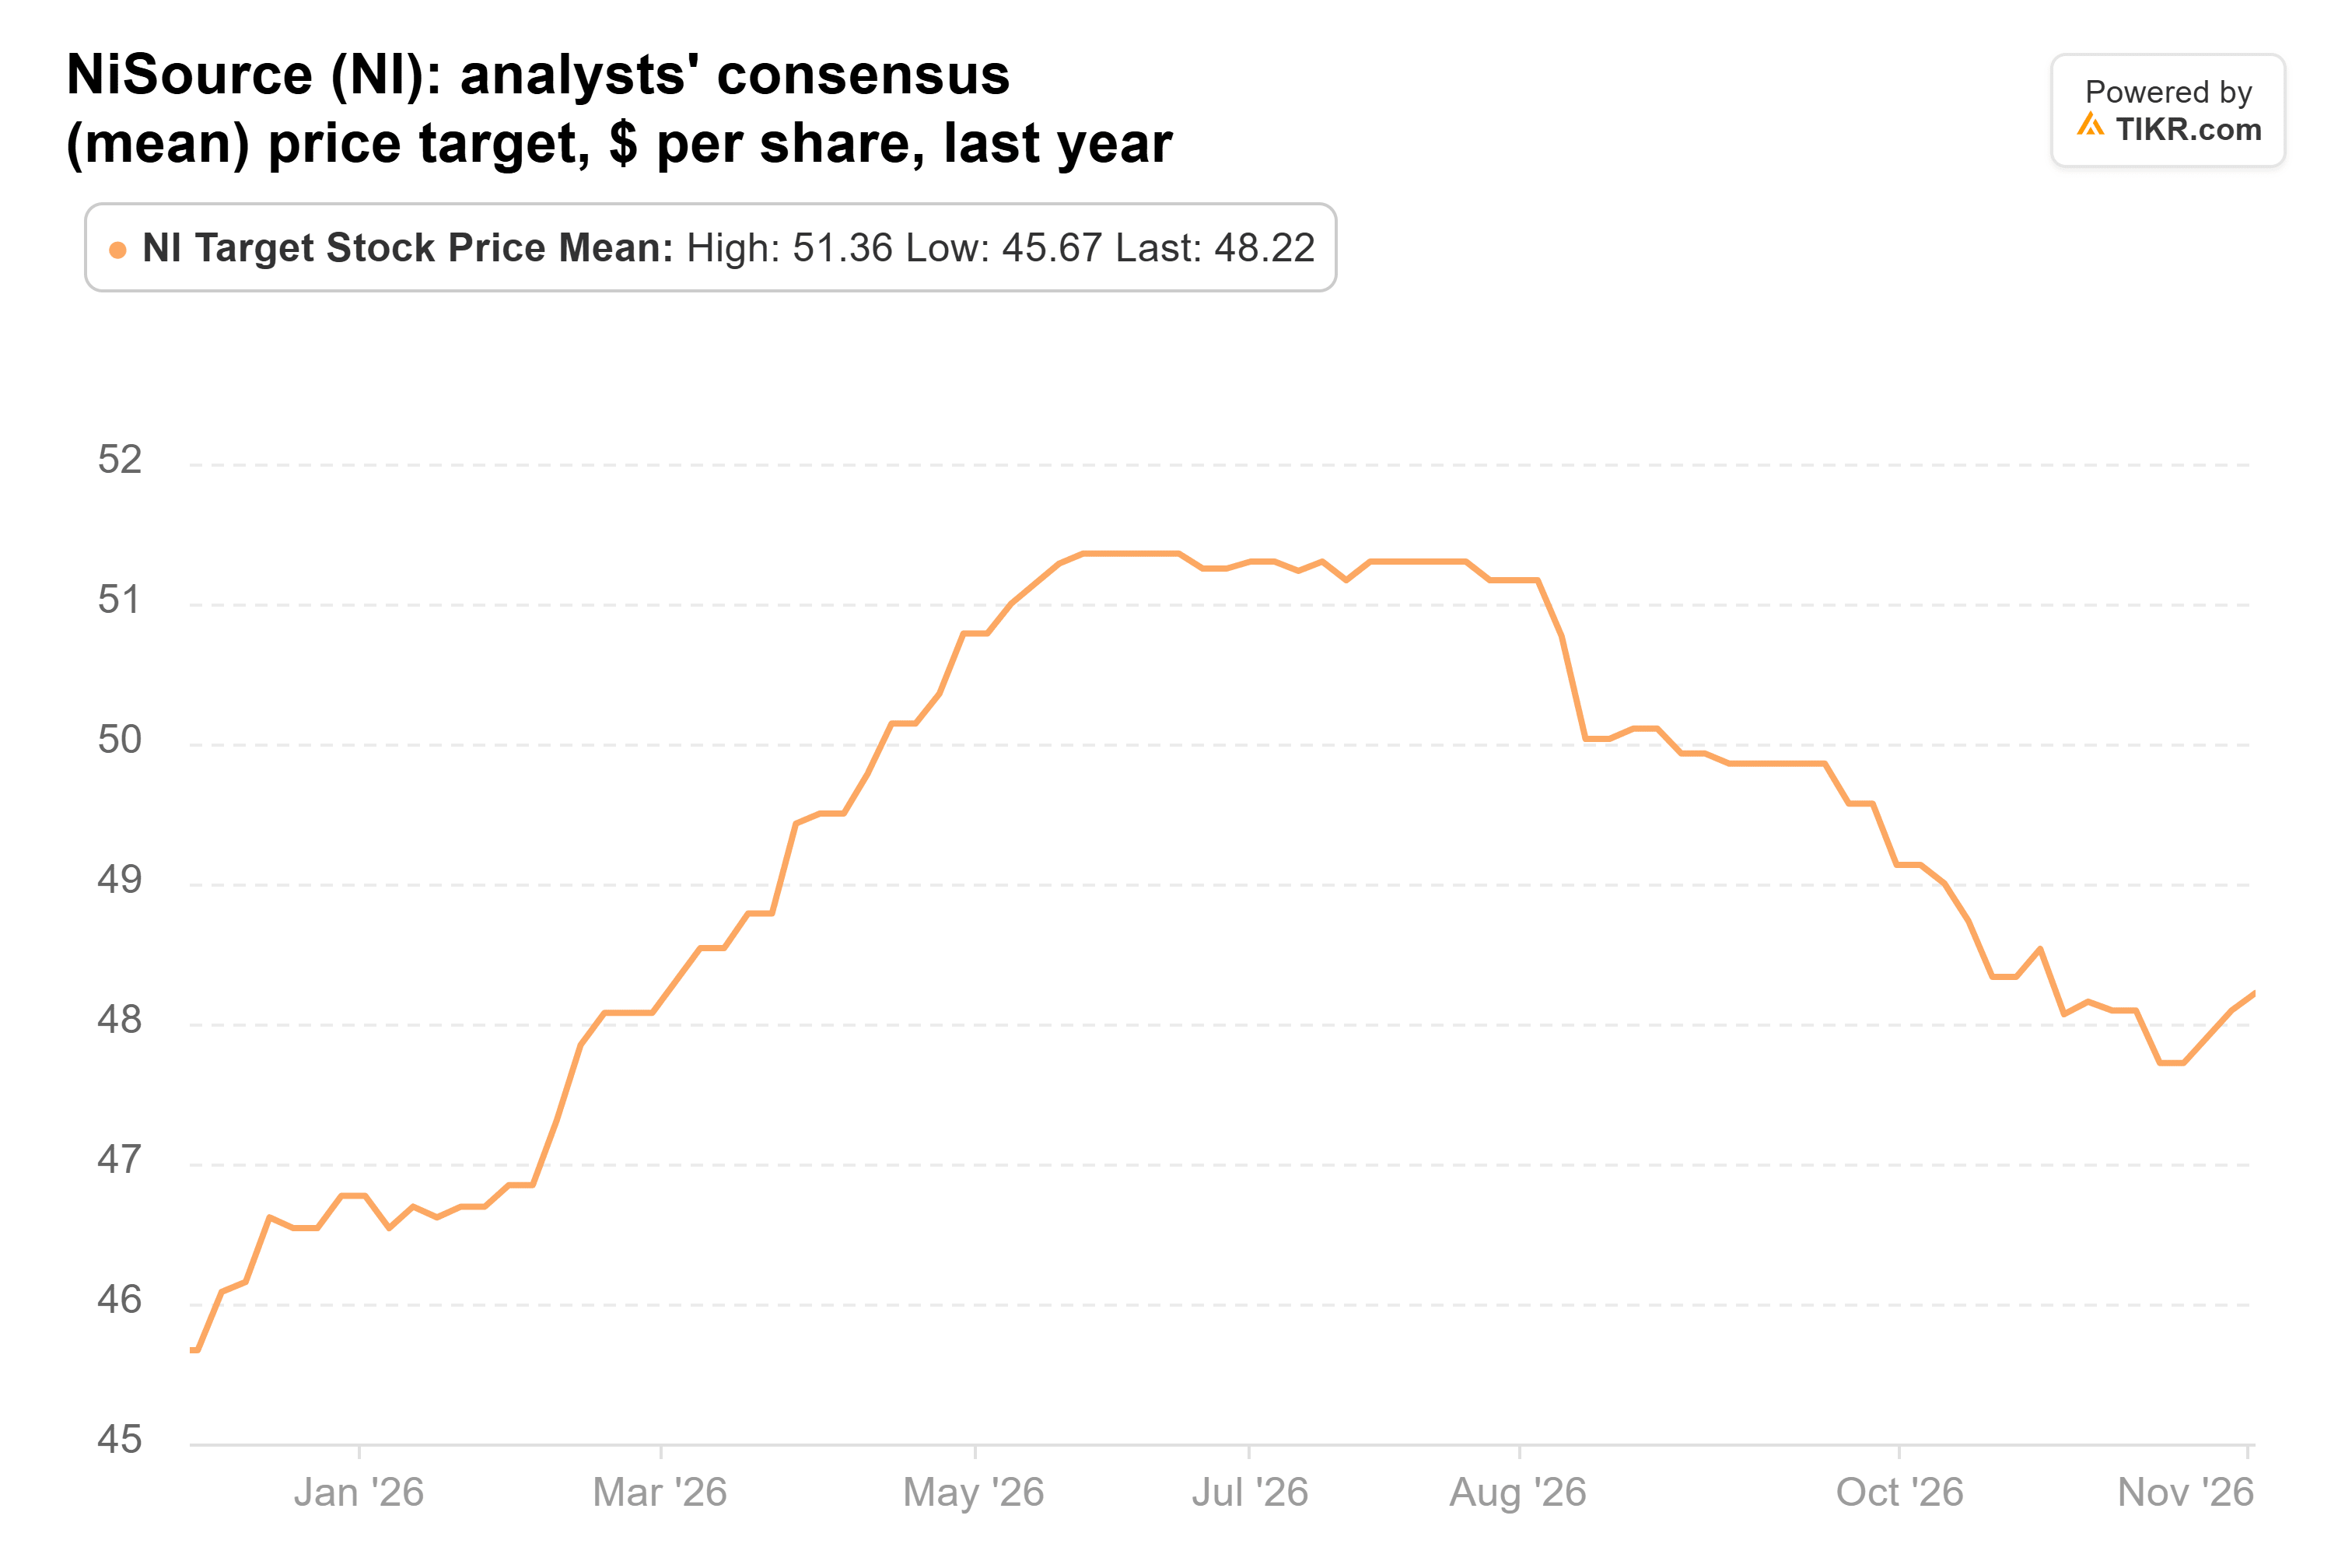
With the stock at $45.55, that average leaves 4% of upside. So analysts see little room left after the run.
Enbridge keeps hitting its numbers
The fund added 32% to its Enbridge stake, for 2.47 million shares worth $115 million at Sept. 30, also 2.1% of its 13F holdings. The stock is up 3% from its Sept. 30 close.
On Nov. 6, Enbridge reported Q3 adjusted EBITDA of C$4.4 billion, up from C$4.3 billion a year earlier. Distributable cash flow rose to C$2.7 billion from C$2.6 billion.
The company stood by its 2026 guidance and put its backlog of secured growth projects at C$38 billion. Enbridge reports in Canadian dollars, so its figures in US dollars move with the exchange rate.
The one blemish: debt ended the quarter at 5.1x EBITDA, slightly above Enbridge’s target range. The company blamed the exchange rate.
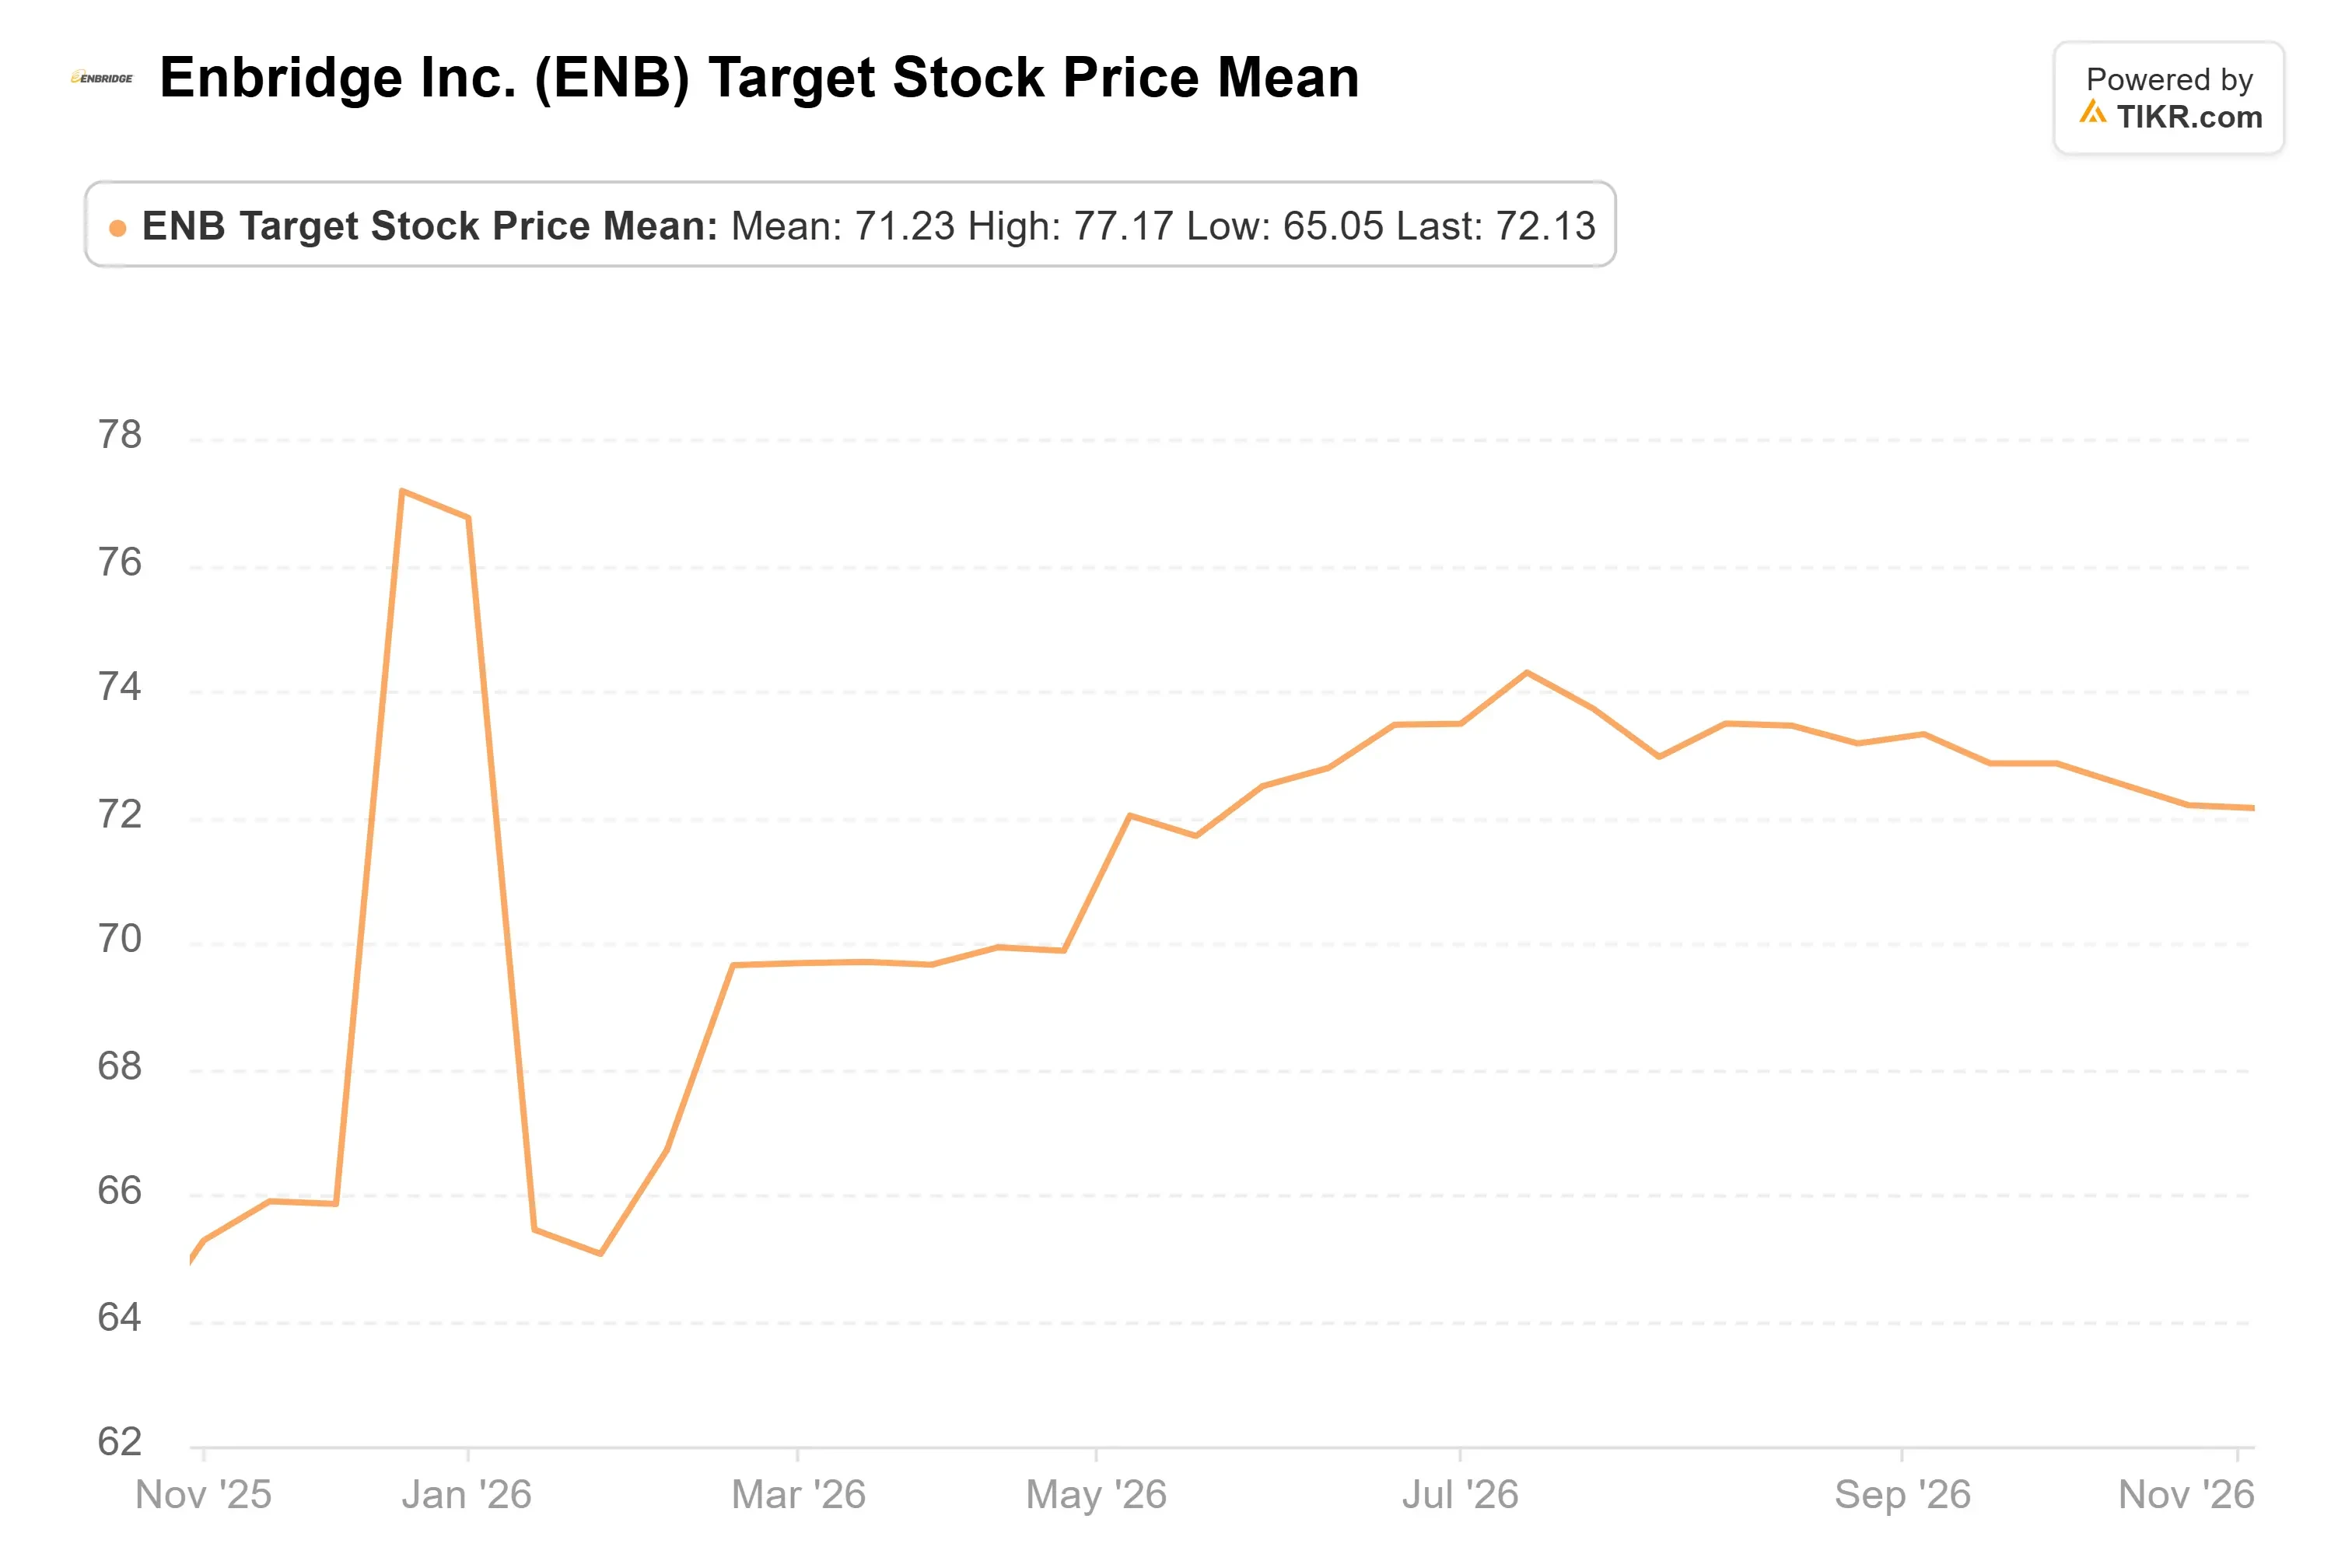
Analysts’ average target rose from C$65.27 to C$72.13 over the year. The shares closed at C$47.91, down from a July high of C$77.17:
Meta is the one I’d follow
Of the three, Meta is the stock I’d follow the fund into today.
NiSource’s big new customer is already in the price, and Enbridge offers steady growth with a balance sheet that’s a little stretched. Meta is the only one whose price has fallen since Sept. 30 while analysts’ targets held.
Meta’s spending is the risk. Analysts expect its free cash flow to stay negative in 2026, 2027 and 2028, and they’ve cut their 2027 earnings estimates 4% since the end of June.
S&P Global Ratings cut its outlook on Meta’s credit rating to negative on Oct. 30 for the same reason.
The next test is Meta’s Q4 report in late January, when it lays out its 2027 spending plan. If that spending keeps climbing without new revenue to match, the discount could last a while.
The fund’s next 13F, due by mid-February, will show whether it kept adding.
So what is Meta stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Meta could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!