Key Takeaways
- Alibaba fell 13% in the past week after reports named it the biggest client of Megaspeed, the chip buyer in Nvidia’s scandal.
- Reported U.S. curbs on Chinese companies’ AI chips abroad put Alibaba’s cloud at risk.
- Analysts still expect normalized earnings to rebound about 65% in fiscal 2027.
- The stock looks cheap enough to start small, and Nov. 19’s results should decide whether to buy more.
Alibaba (BABA) stock is down 13% in the past week while the Nasdaq 100 rose 6%.
None of it came from Alibaba’s own news. First came a scandal around Jensen Huang, who resigned as CEO of Nvidia (NVDA) on Nov. 12. Then came a report that Washington will cut off the chips Chinese companies use abroad.
Alibaba is Megaspeed’s biggest client
On Nov. 8, Huang admitted an affair, reportedly with a former executive of Megaspeed, a chip buyer under U.S. investigation. The next day, the Financial Times reported that Alibaba is Megaspeed’s largest client and, through a Singapore unit, a lender to it. The Information then reported that Huang’s relationship may have helped Chinese companies get at least $7.5 billion of Nvidia chips over several years. Megaspeed denies diverting chips, and Alibaba isn’t a target of the probe.
For Nvidia, that’s under a tenth of its $96.2 billion July quarter. Alibaba, which reportedly rents computing power through Megaspeed, has more at stake.
The offshore chip route may close
Late on Nov. 11, The Information reported that the Commerce Department is finalizing a rule barring Chinese companies from using advanced AI chips in data centers abroad. It could come this month. Cloud is Alibaba’s growth engine: AI Cloud and Compute revenue grew 45% in the June quarter. And management says its own T-Head chips still trail foreign rivals.
TIKR tracks 41 analysts on Alibaba. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Alibaba, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Alibaba’s Analyst Ratings
Cheap, but I’d size it after Nov. 19
Analysts expect normalized earnings to rebound about 65% in fiscal 2027, after a 59% drop in fiscal 2026:
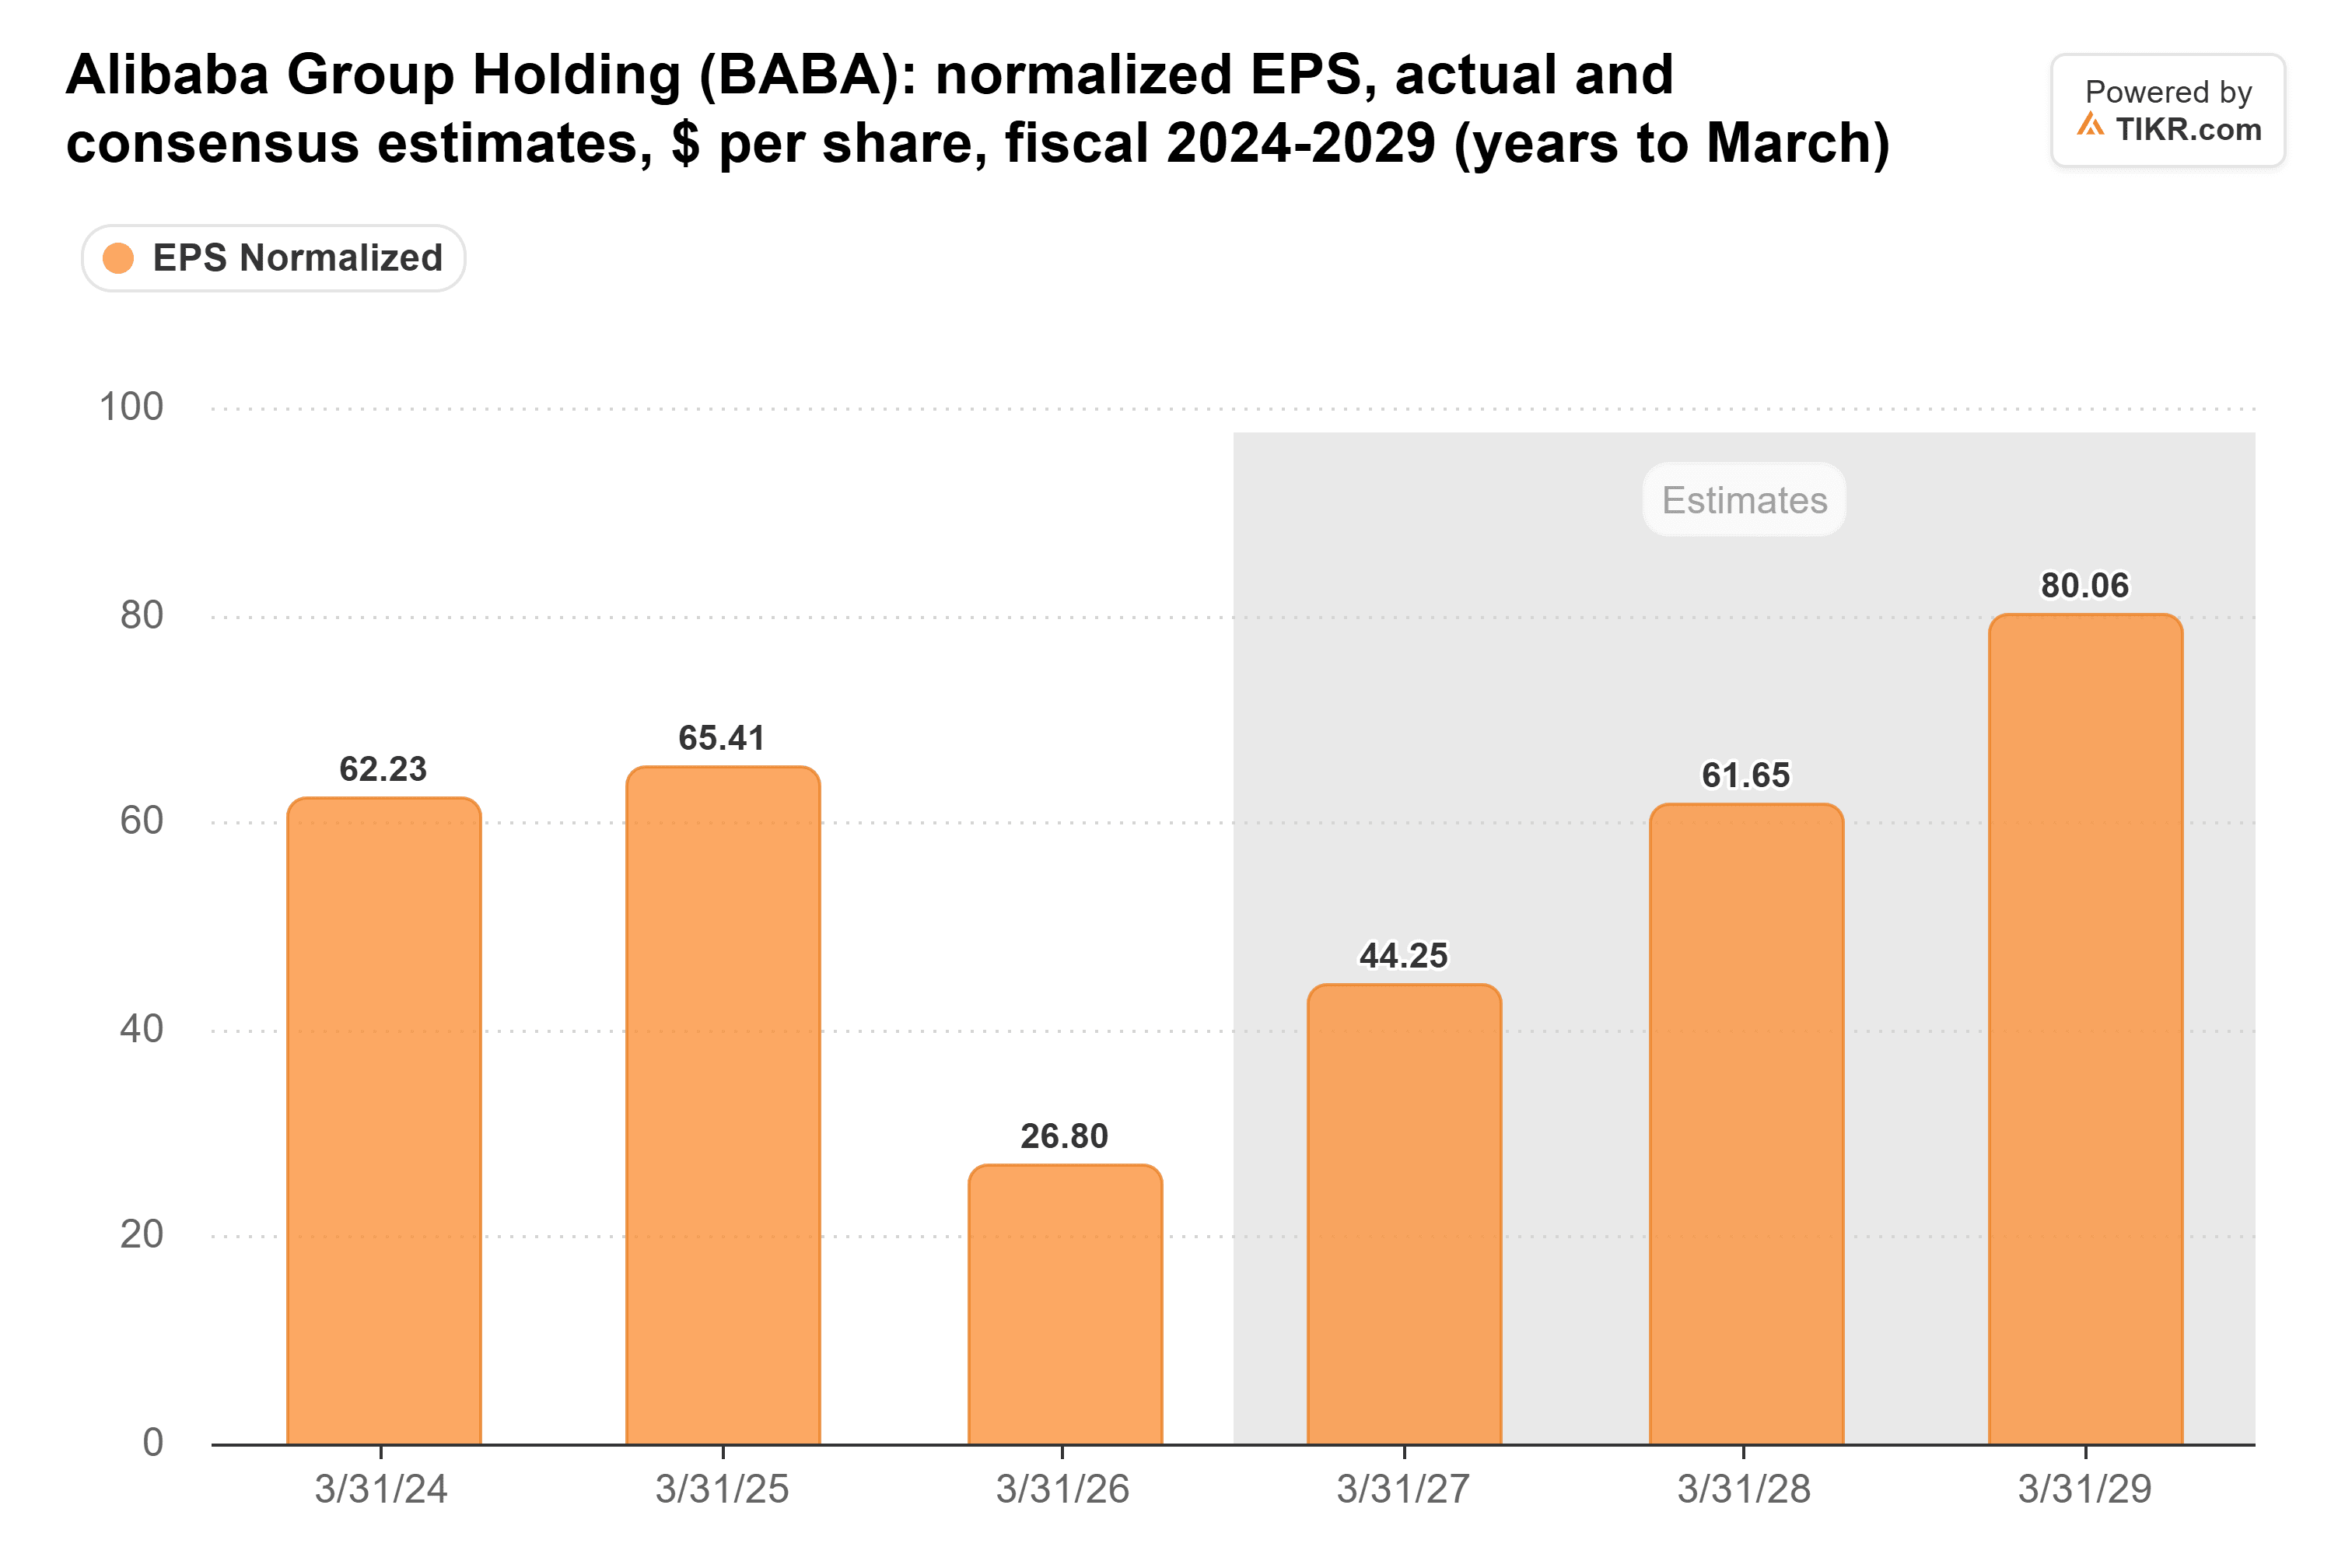
Those estimates were made before the rule report, and I’d expect some cuts if it lands as written.
Alibaba’s forward P/E was 13x on Nov. 11. That’s in line with its five-year average and about half January’s 25x:
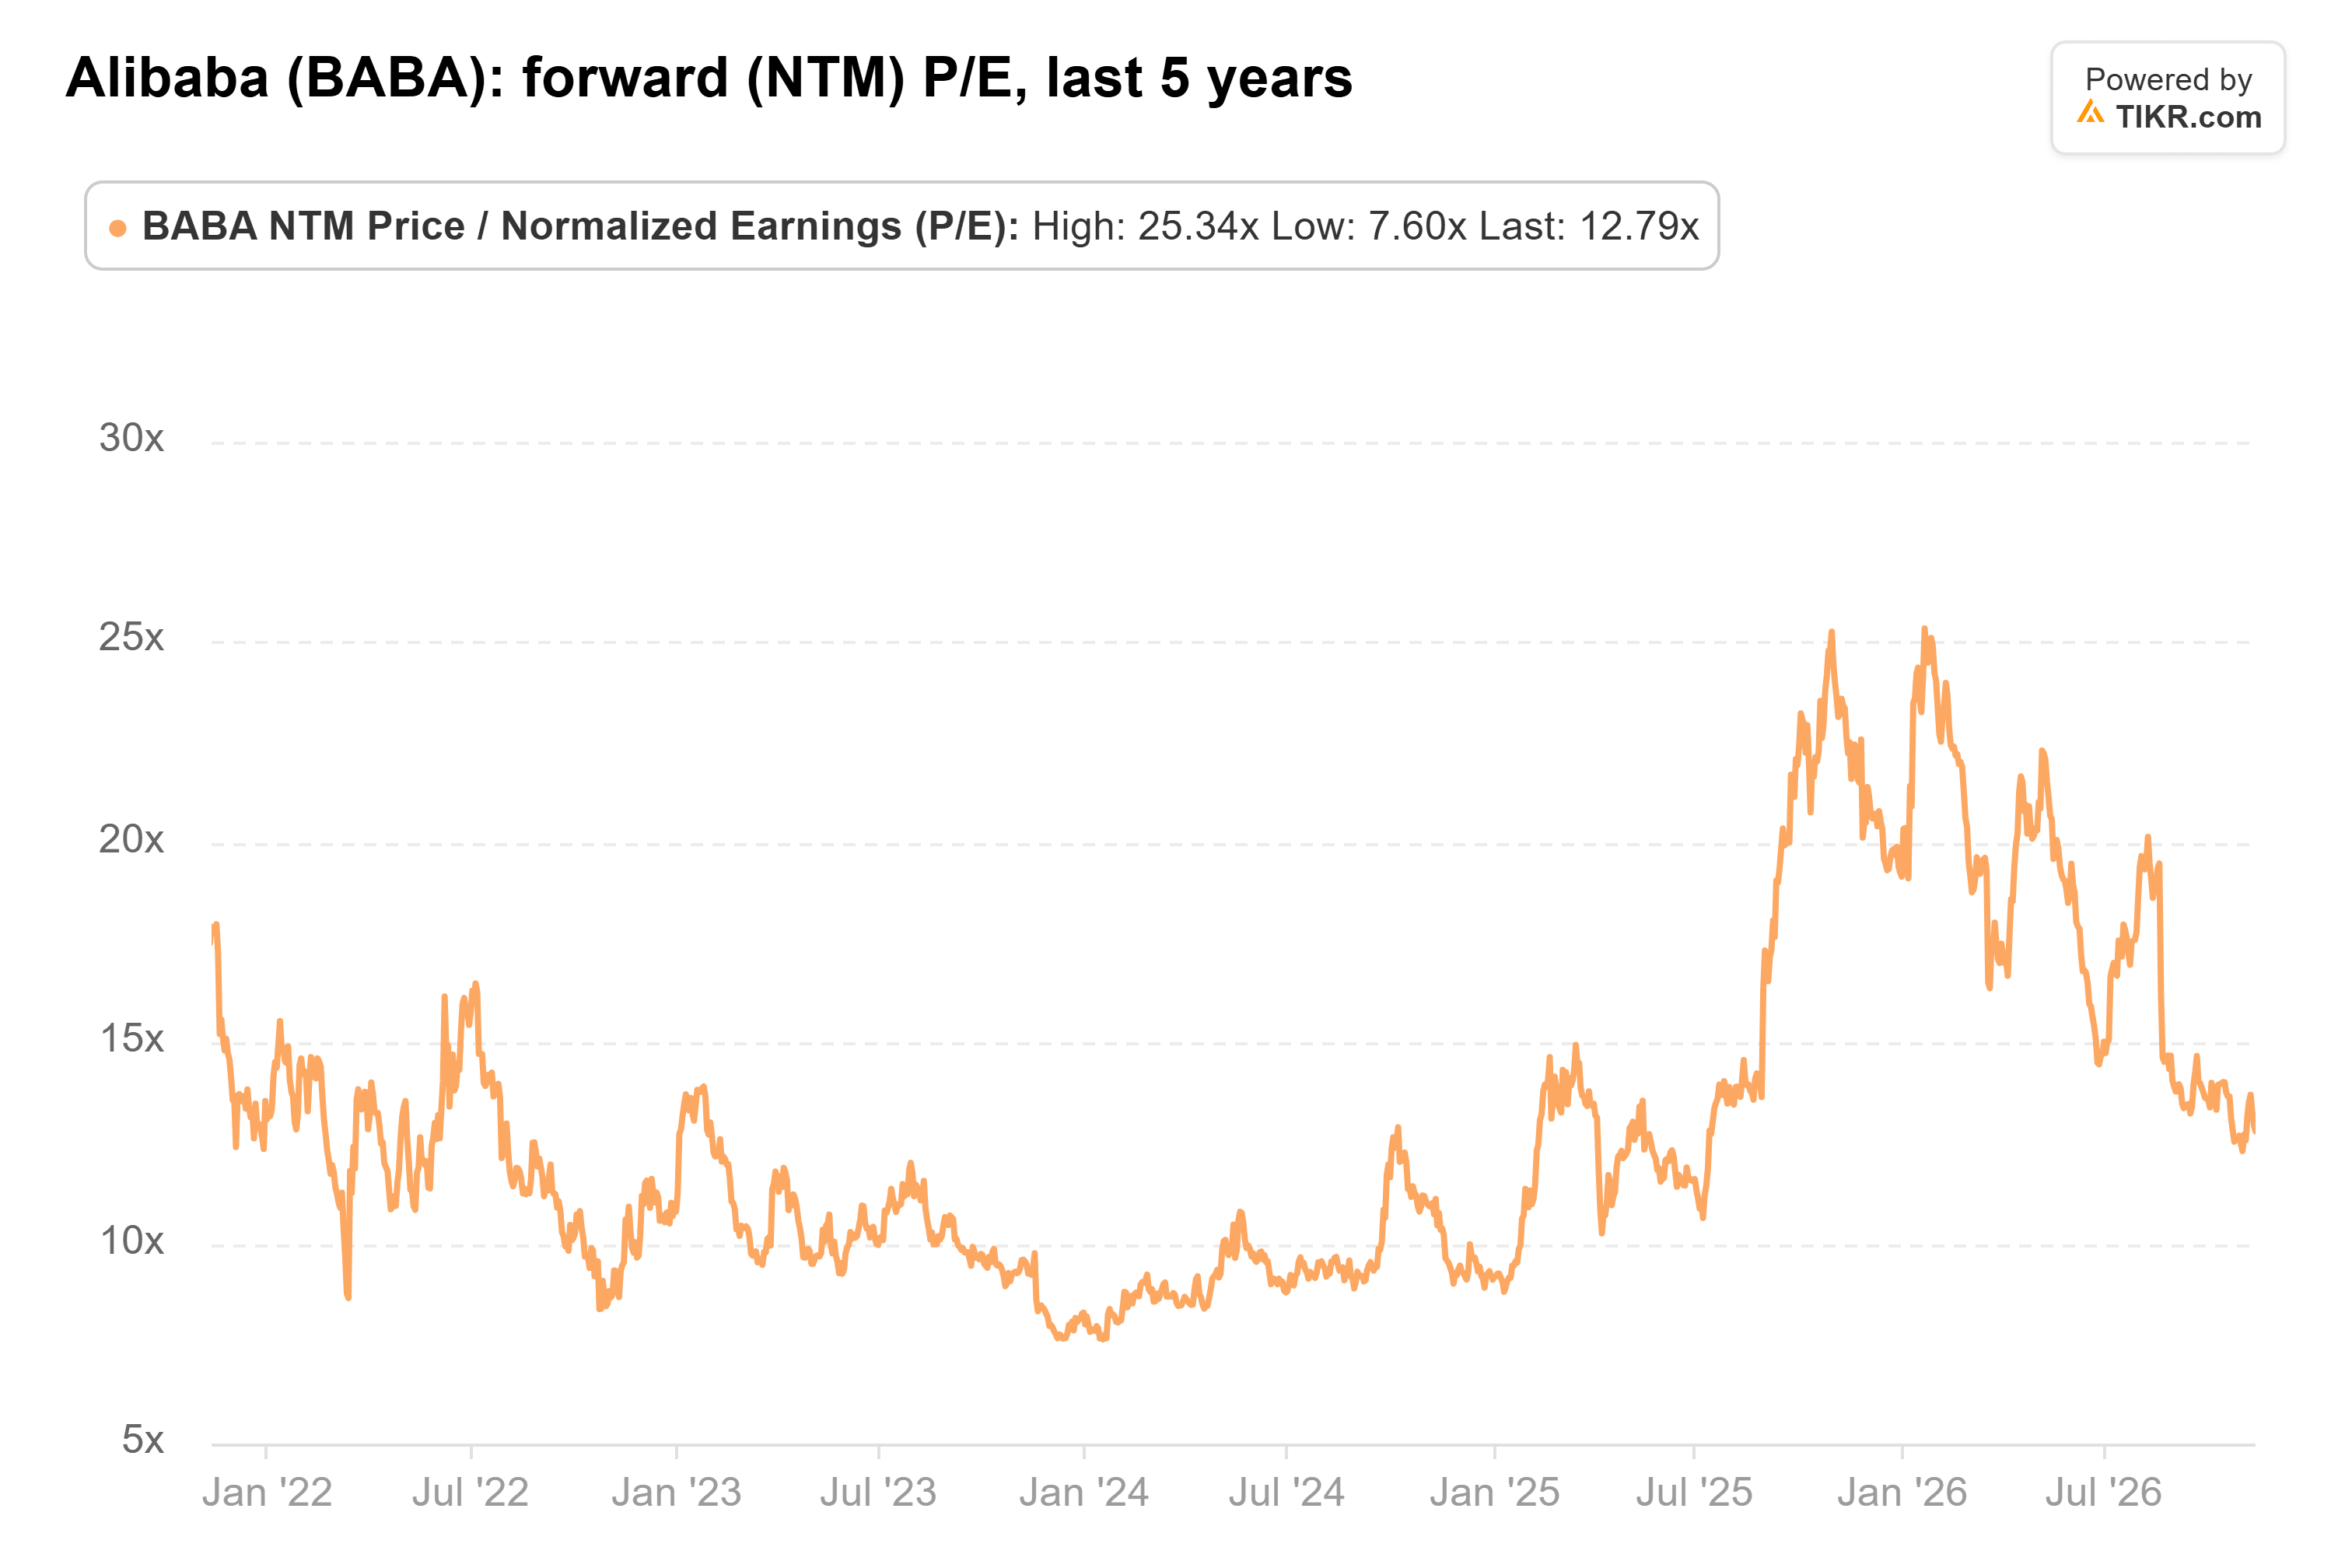
After the Nov. 12 drop, it’s about 12x, and Wall Street’s consensus target is $184.
At that multiple, I wouldn’t sell. But I wouldn’t load up before Nov. 19 either, when management can say how much of the cloud depends on chips outside China. I’d start small and add if cloud growth holds near June’s 45%. Of course, the rule isn’t final: Commerce is still checking with other agencies.
So what is Alibaba stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Alibaba could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!