


Key Takeaways
- A hedge fund firm managing $78.2 billion added to Taiwan Semiconductor, MSCI and Tesla in the third quarter, and those were its three biggest additions.
- Taiwan Semiconductor became the fund’s largest holding, and its Tesla stake more than quadrupled.
- Taiwan Semiconductor has fallen 21% since Sept. 30, while MSCI and Tesla have both risen.
- Of the three, the numbers back Taiwan Semiconductor best: it trades at 17x forward earnings, and even the lowest analyst target is above its price.
Viking Global’s new 13F shows where a $78.2 billion hedge fund firm put money to work in the third quarter. It’s a mix you don’t see often: a chipmaker, an index provider and a carmaker.
The filing covers the quarter ended Sept. 30 and was filed Nov. 16. It lists $32.7 billion of US stocks across 79 positions. Andreas Halvorsen’s fund added the most to Taiwan Semiconductor Manufacturing (TSM), MSCI (MSCI) and Tesla (TSLA), and the three stocks have gone very different ways since.
TSMC is now its biggest bet
The fund ended September with 3.90 million Taiwan Semiconductor shares worth $1.78 billion after adding 23% to the stake. That made TSMC the largest of its 13F stocks at 5.4%. The stock has fallen 21% since then. It got caught in an early-November chip sell-off on a day when TSMC had no news of its own. Meanwhile, its October sales rose 59.7% from a year earlier to NT$586.89 billion, its best month of 2026.
Analysts kept raising their targets through all of it, and the consensus went from $339.91 a year ago to $586.69.
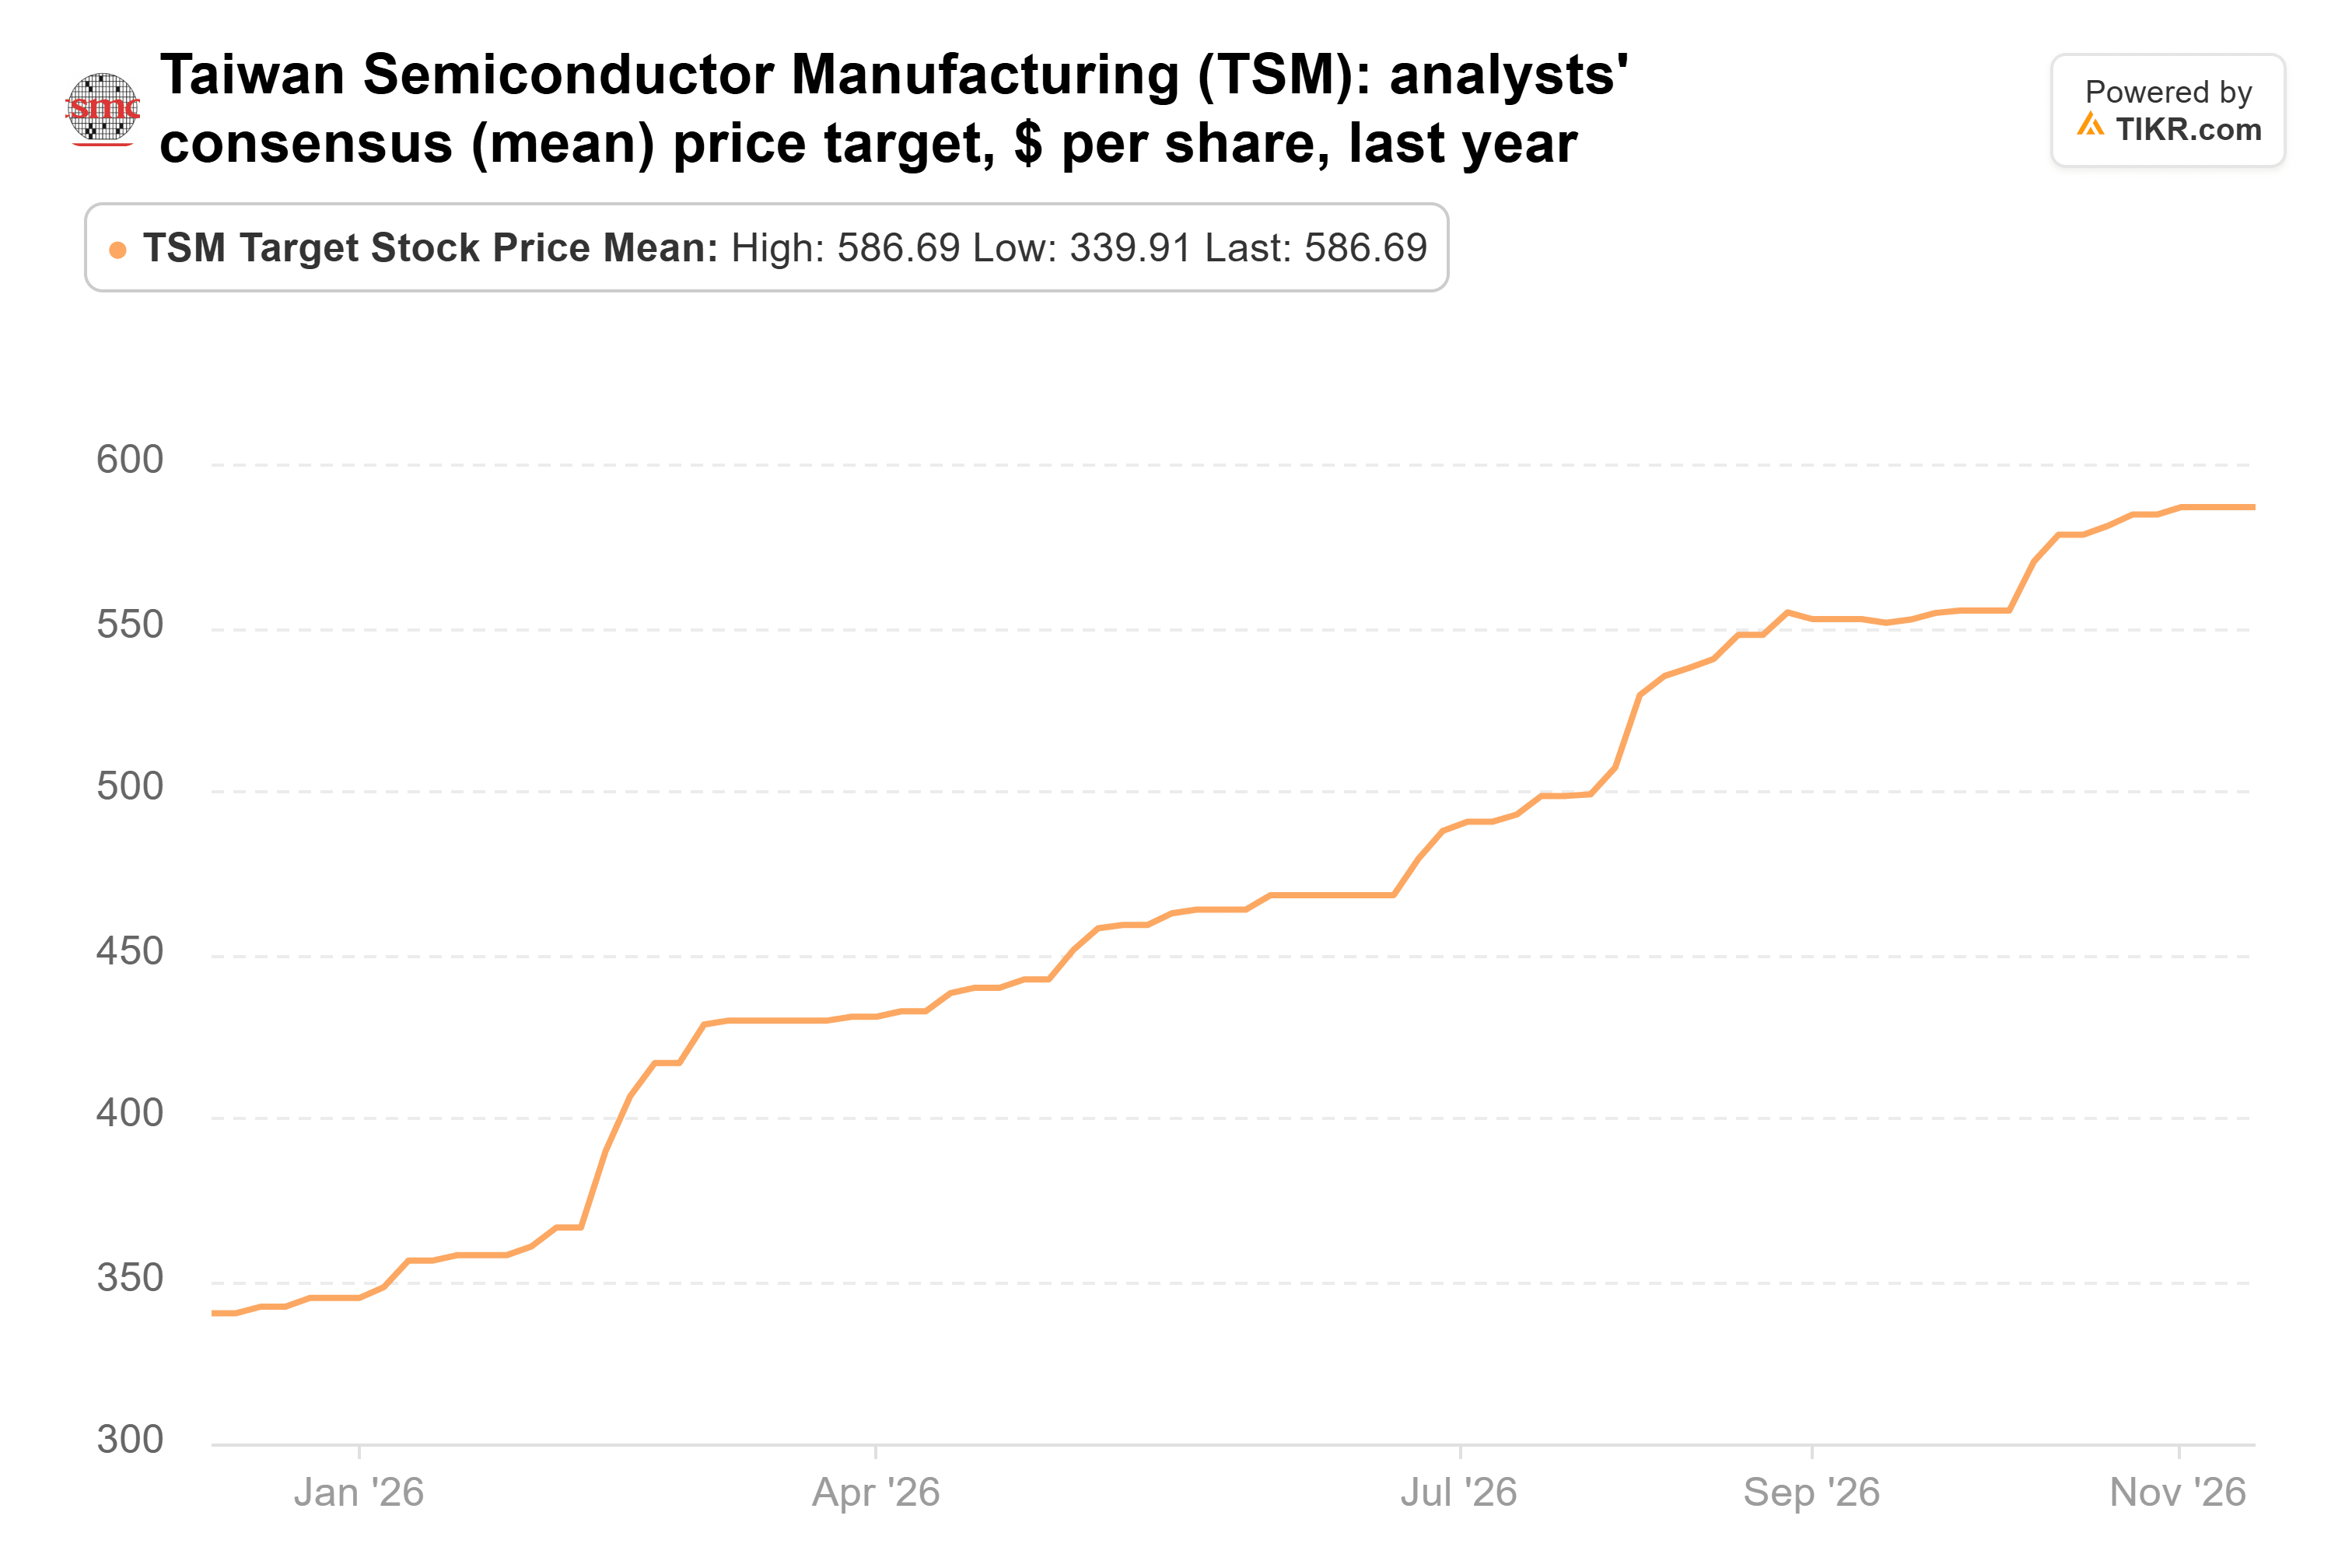
Even the lowest of the 21 analysts’ targets, $440, is above where the stock trades today.
TIKR tracks 21 analysts on TSMC. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on TSMC, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See TSMC’s Analyst Ratings
MSCI’s index business keeps growing
MSCI went the other way and has risen 18% since Sept. 30. The fund held 1.55 million shares worth $837 million at quarter-end, or 2.6% of its 13F stocks, after raising its stake 34%. MSCI said in its Oct. 20 release that third-quarter revenue rose 12.4% to $892.0 million and index revenue rose 18.1%. The company also bought back $552.3 million of its own stock in the quarter, at an average of $562.92 a share.
Analysts haven’t kept up with the stock. Over the past year the consensus target went from $655.06 to $689.94, and it’s still below July’s high of $707.06.
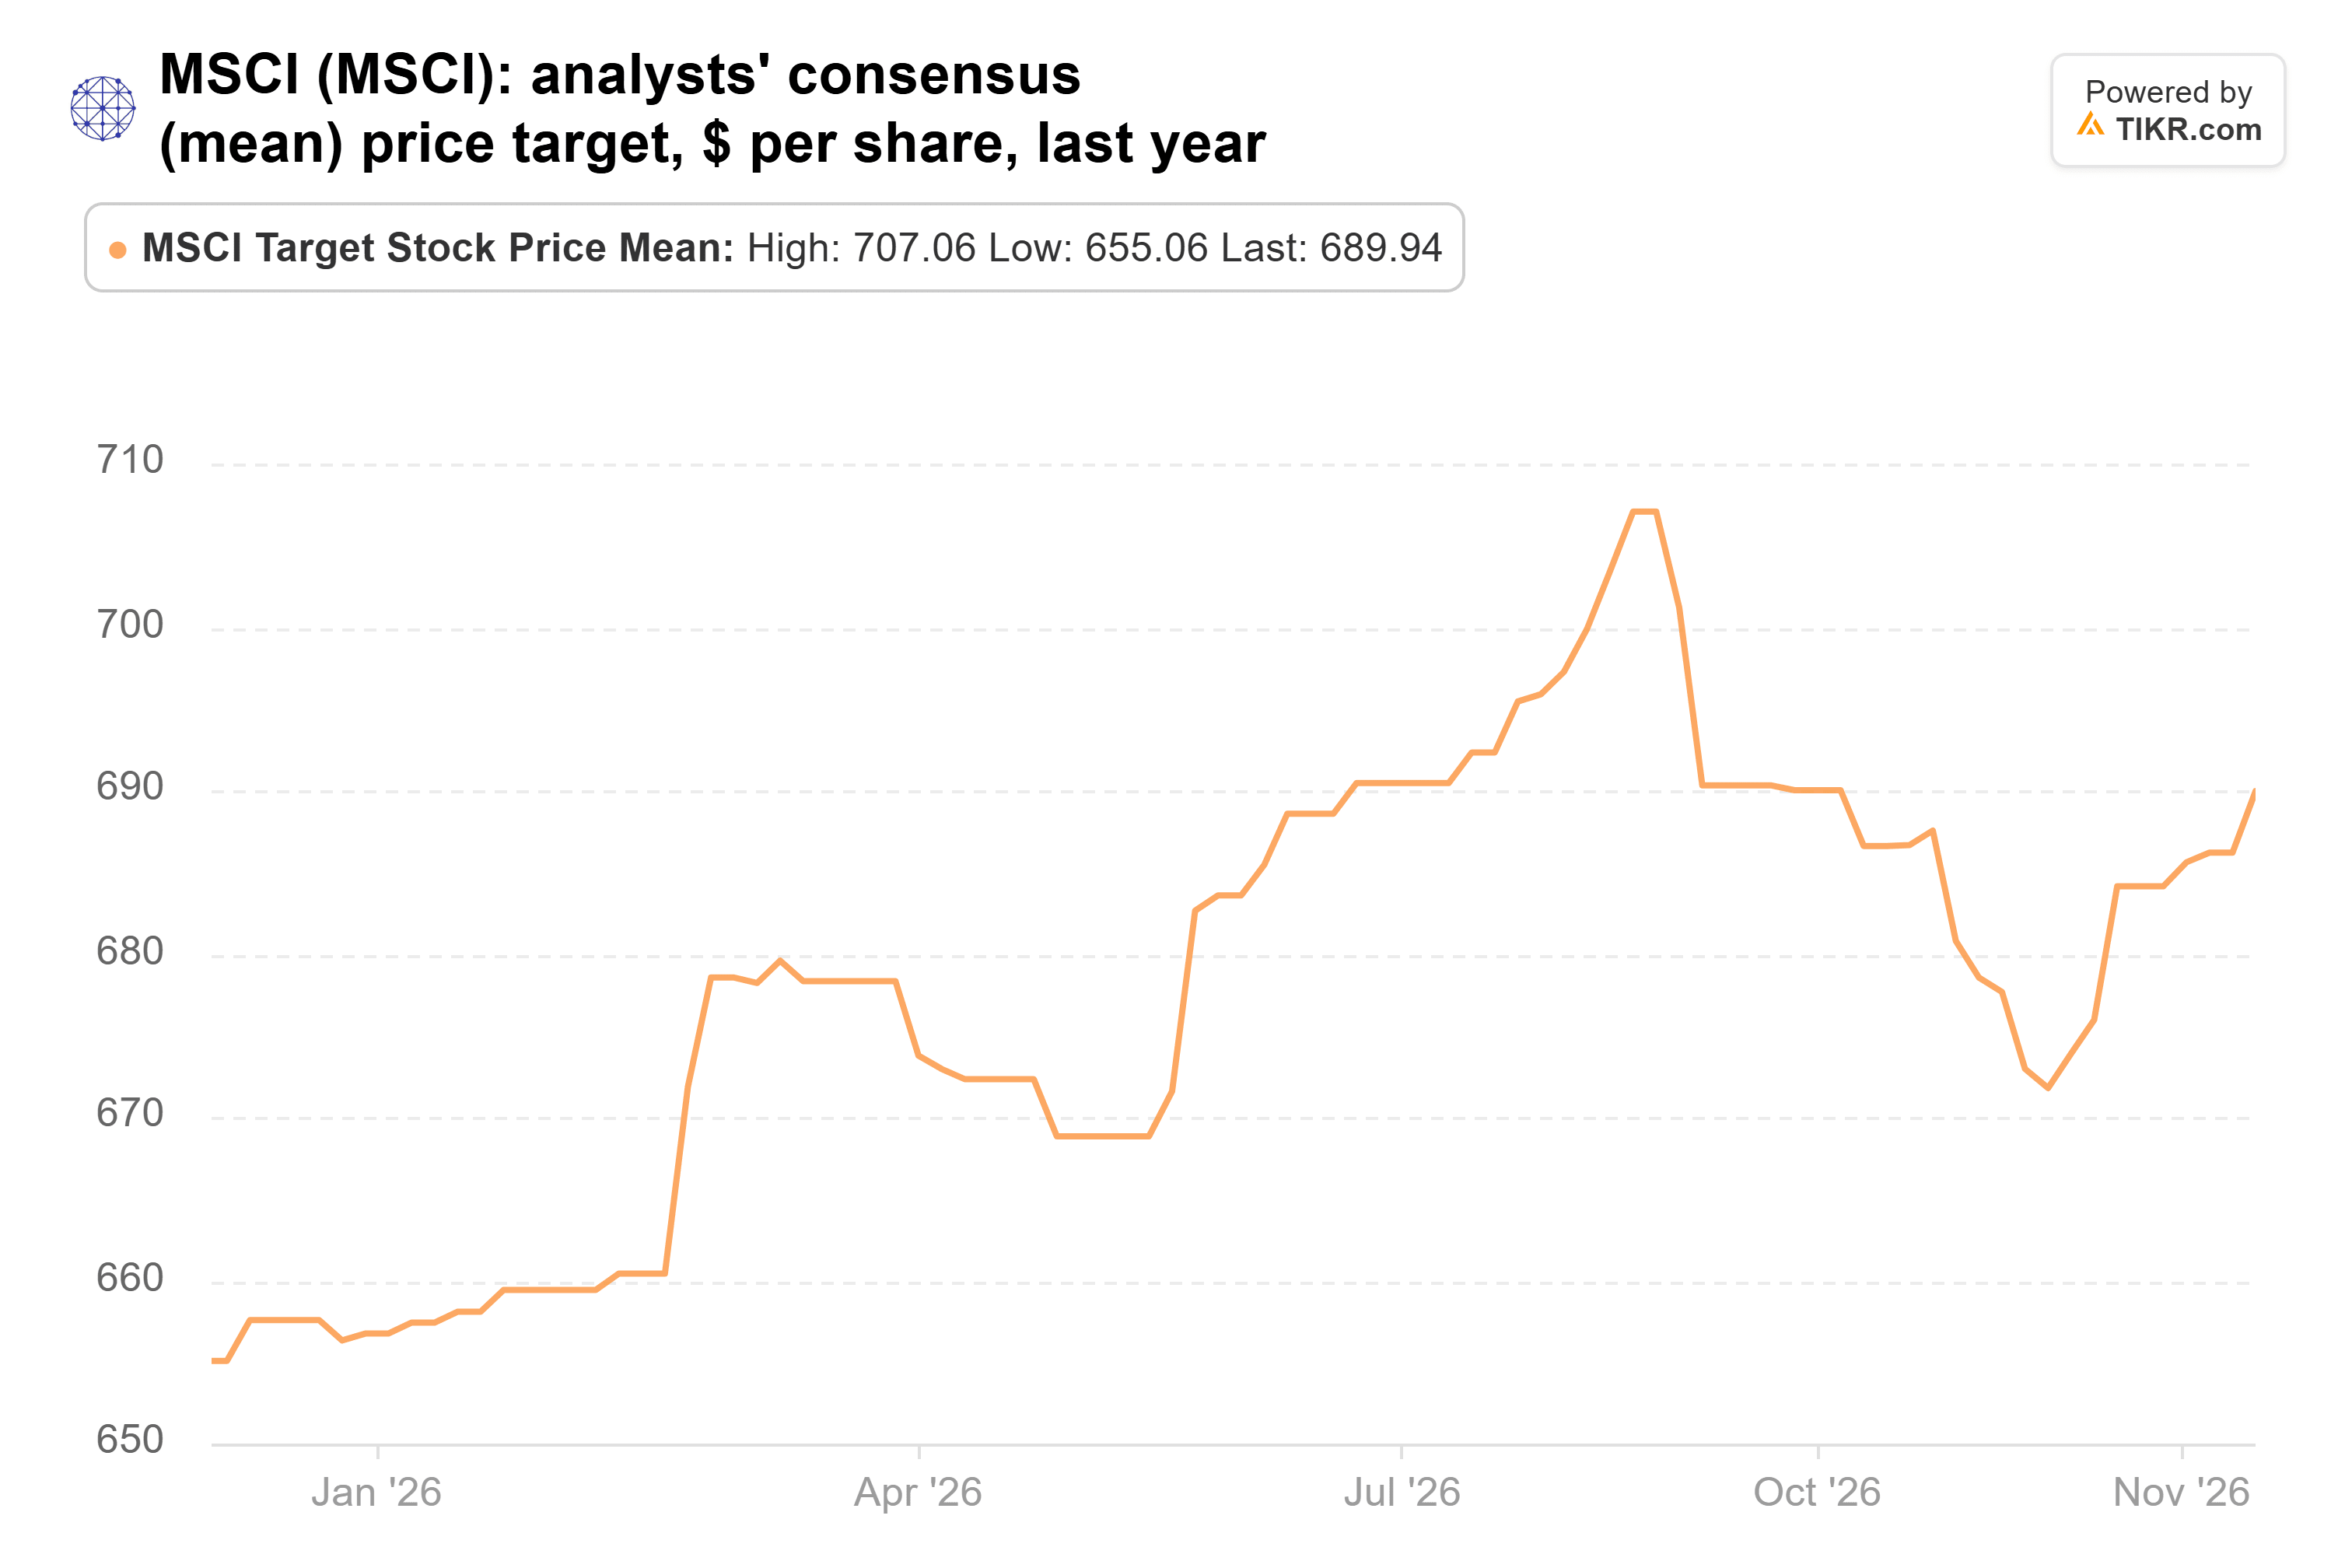
That leaves 8% upside to the average target.
Tesla got the biggest boost
The biggest change in the filing was Tesla. The fund raised its share count 327% to 2.34 million shares, worth $831 million and 2.5% of its 13F stocks. The stock is up 8% since Sept. 30.
For now, Tesla isn’t earning much. Its GAAP operating margin was 2.6% in the third quarter, down from 5.8% a year earlier, and management expects to spend about $20 billion on capital projects this year. Investors are paying for what comes next: Robotaxi, Optimus and merger talks with SpaceX. Bloomberg reported those talks could produce a deal as soon as December.
The analysts’ consensus target has barely moved in a year, going from $392.93 to $412.48.
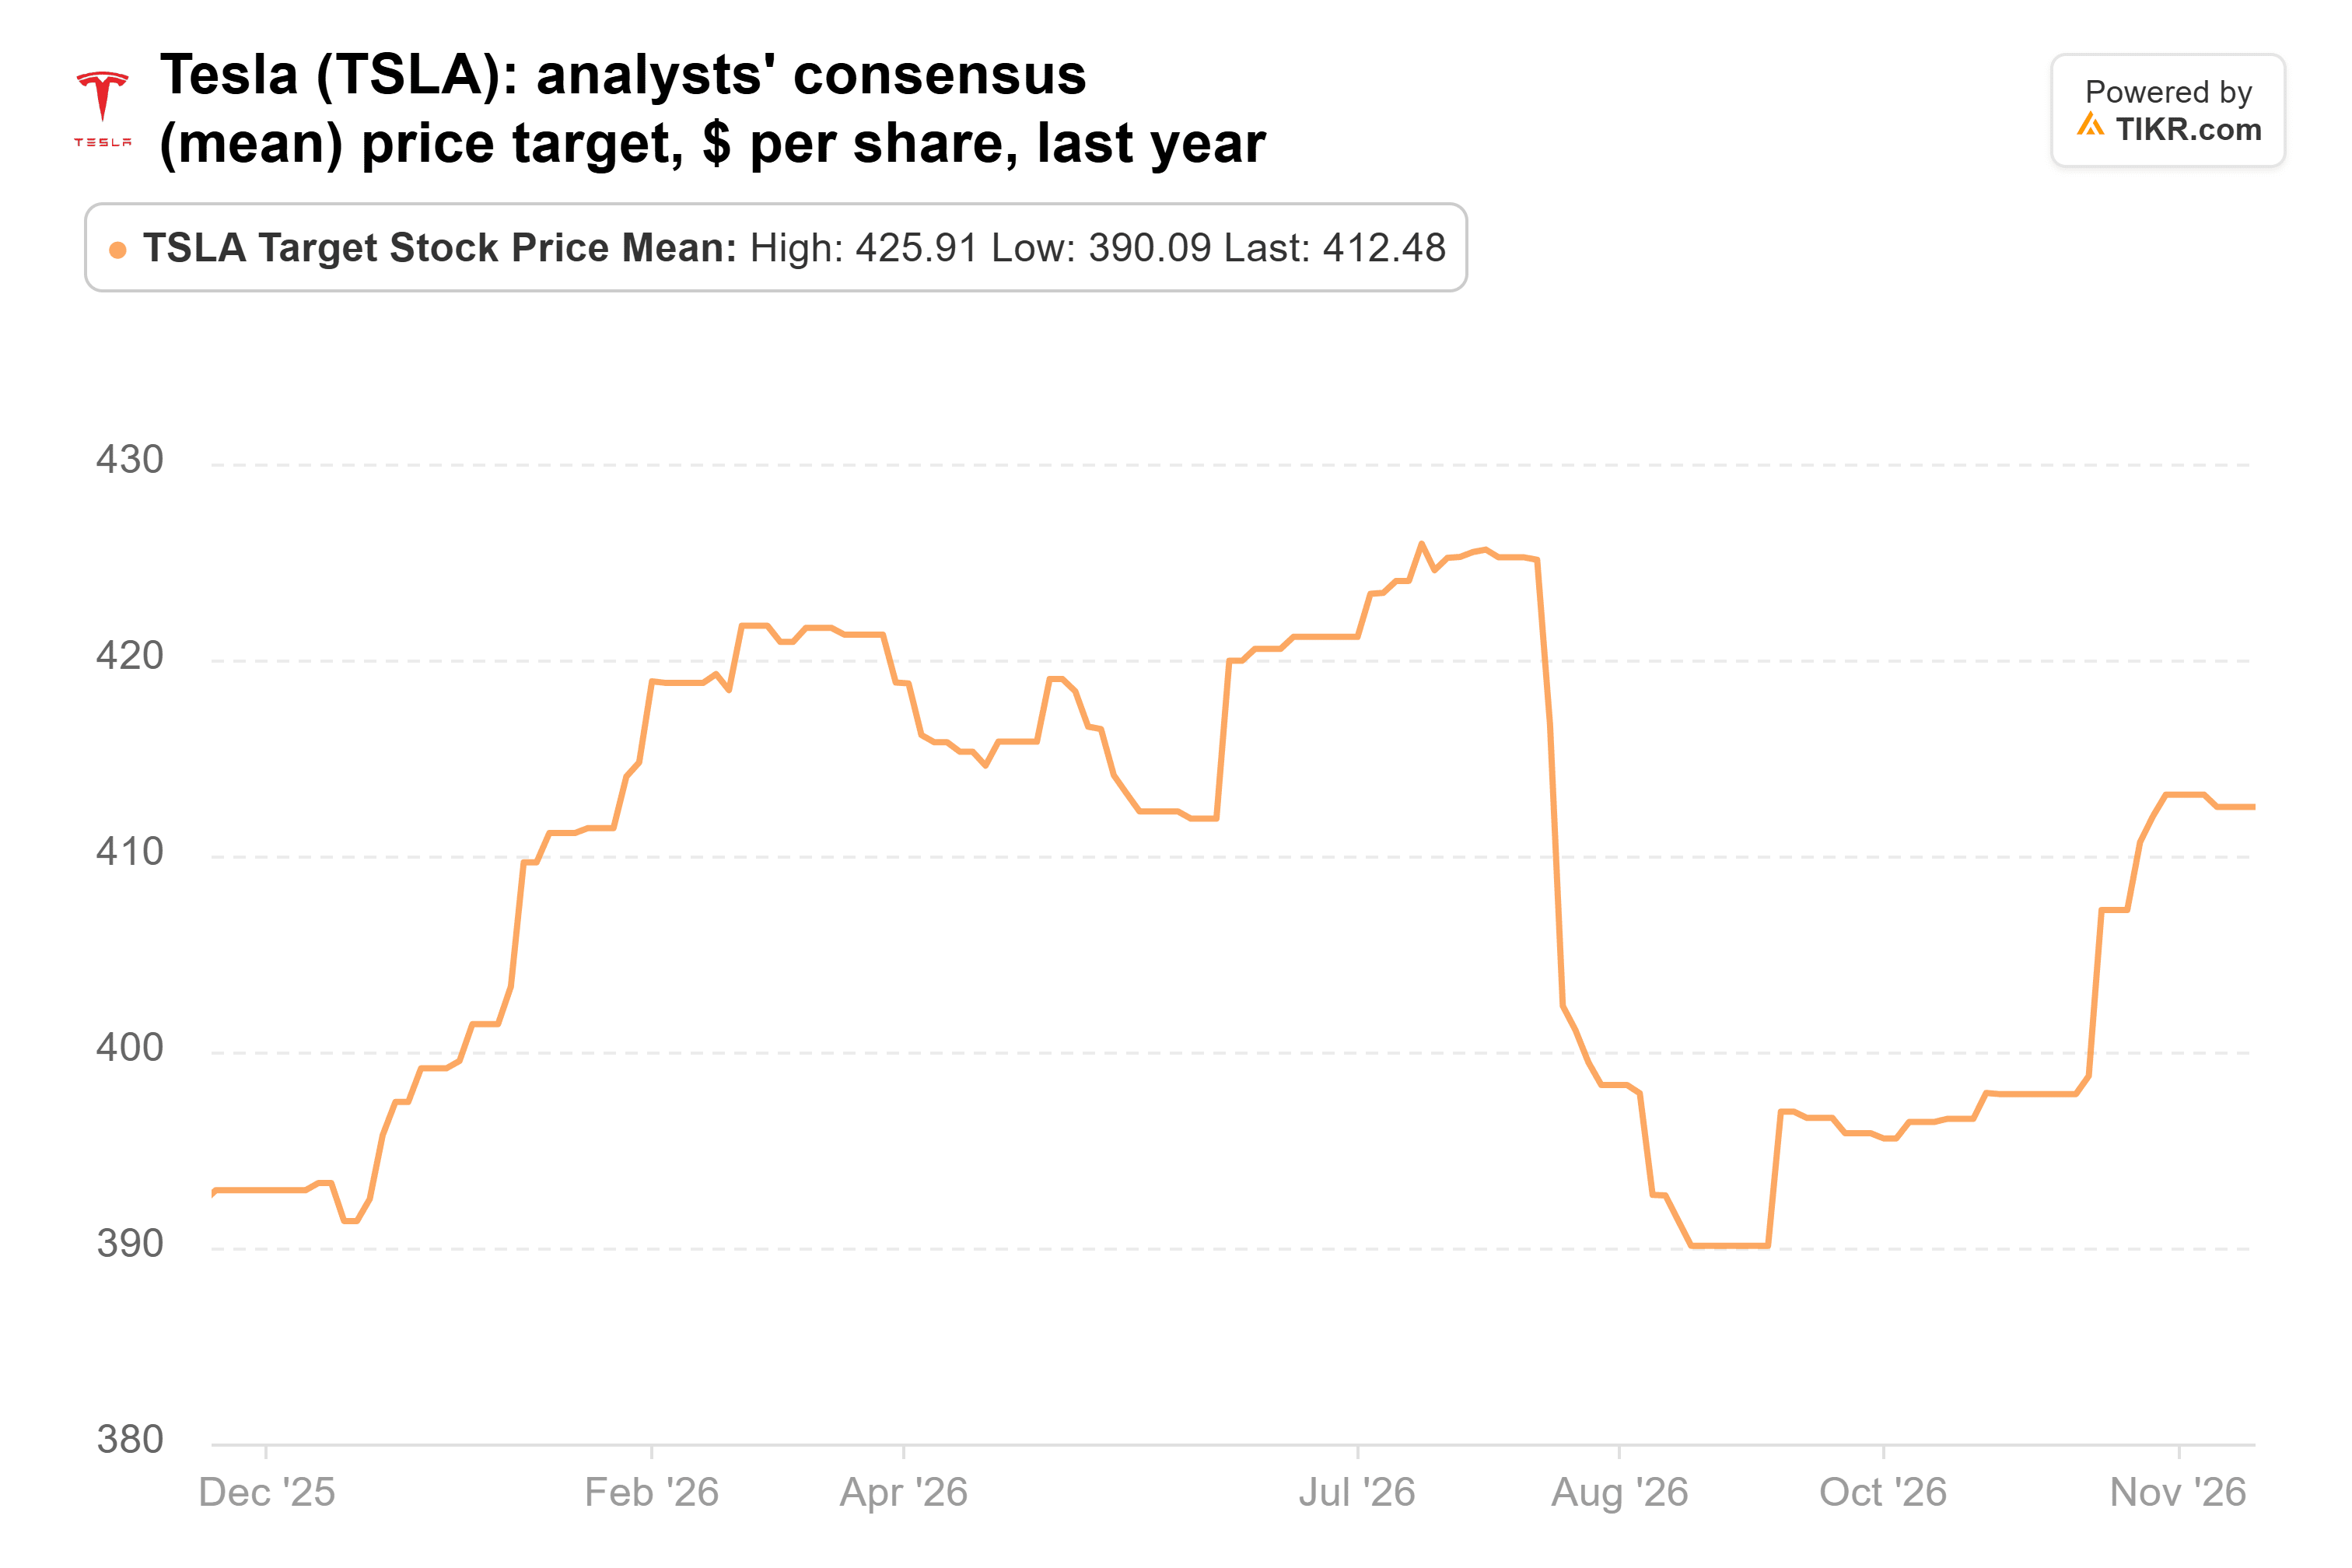
Individual targets run from $128.11 to $600, so analysts are far apart on what Tesla is worth.
The chipmaker is the one the numbers back
TSMC trades at 17x forward earnings, below its five-year average of 18x on TIKR, and the analysts’ average target is 62% above its price. MSCI trades at 29x with 8% upside. Tesla trades at 180x, well above its five-year average of 108x, with 7% upside.
Tesla needs the most from the future. Analysts expect normalized EPS of $3.30 in 2028, which is still below the $4.07 it earned in 2022. TSMC needs far less. It guided fourth-quarter revenue to $52.3 billion to $54.3 billion at a 65% to 67% gross margin, in line with the 66.4% it posted in the third quarter.
Follow the fund into TSMC
The risk with TSMC is how much it’s building. Management expects to spend $60 billion to $64 billion on capital projects in 2026, mostly for capacity that comes online in 2028 and 2029. Two customers also made up 36% of 2025 revenue. If AI spending slows before then, those new chip plants get expensive fast.
Still, if I could only follow the fund into one of these today, it’d be TSMC. MSCI’s business is in great shape, but the stock has already run. Tesla’s price depends on years of profits that analysts don’t expect yet. TSMC is 21% cheaper than it was on Sept. 30, and nothing in its own numbers explains the drop.
The next test is in mid-January, when TSMC reports fourth-quarter results and gives its 2027 outlook. A first-quarter gross margin guide of 65% or more would show the AI build is still paying off. November sales come first, around Dec. 10. The fund’s next 13F, for the quarter ending Dec. 31, is due in mid-February.
So what is TSMC stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what TSMC could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


