

Key Takeaways
- Jericho Capital Asset Management, a $12 billion fund, opened positions in Sandisk and SK hynix and added to its Lattice Semiconductor stake in the third quarter, its latest 13F shows.
- All three stocks have fallen since Sept. 30: Sandisk by 57%, SK hynix by 35% and Lattice by 12%.
- Analysts’ average targets have held up far better than the share prices, and they now sit 41% to 171% above the last close.
- Of the three, the numbers back Sandisk best. It trades at about 3x forward earnings, and management says its contracts still earn about an 80% gross margin at their floor prices.
A $12 billion fund’s latest filing shows a big bet on memory chips. Sandisk (SNDK) and SK hynix (SKHY) were the two largest new positions in Jericho Capital Asset Management’s 13F for the quarter ended Sept. 30, filed Nov. 16. The fund also added 28% to its stake in Lattice Semiconductor (LSCC). Together, the three made up 15% of its 13F stocks.
Sandisk was the biggest buy, and the hardest hit
Jericho didn’t own Sandisk three months earlier. By Sept. 30, it held 391,880 shares worth $682 million, 5.8% of its 13F stocks and its fourth-biggest holding. (That share count is from before Sandisk’s 8-for-1 split, which took effect Nov. 20.) The stock is down 57% since then, including a 24% drop in one week this month on worries across the memory industry. Kioxia, Sandisk’s joint-venture partner, saw its NAND price gains slow to the mid-20s percent in the September quarter, down from about 70%.
Sandisk itself just had a strong quarter. Its non-GAAP gross margin hit 85.1% in the three months to Oct. 2. It ended the quarter with $88.9 billion of contracted revenue still to deliver, valued at the contracts’ floor prices. Analysts’ average target is still close to its peak:
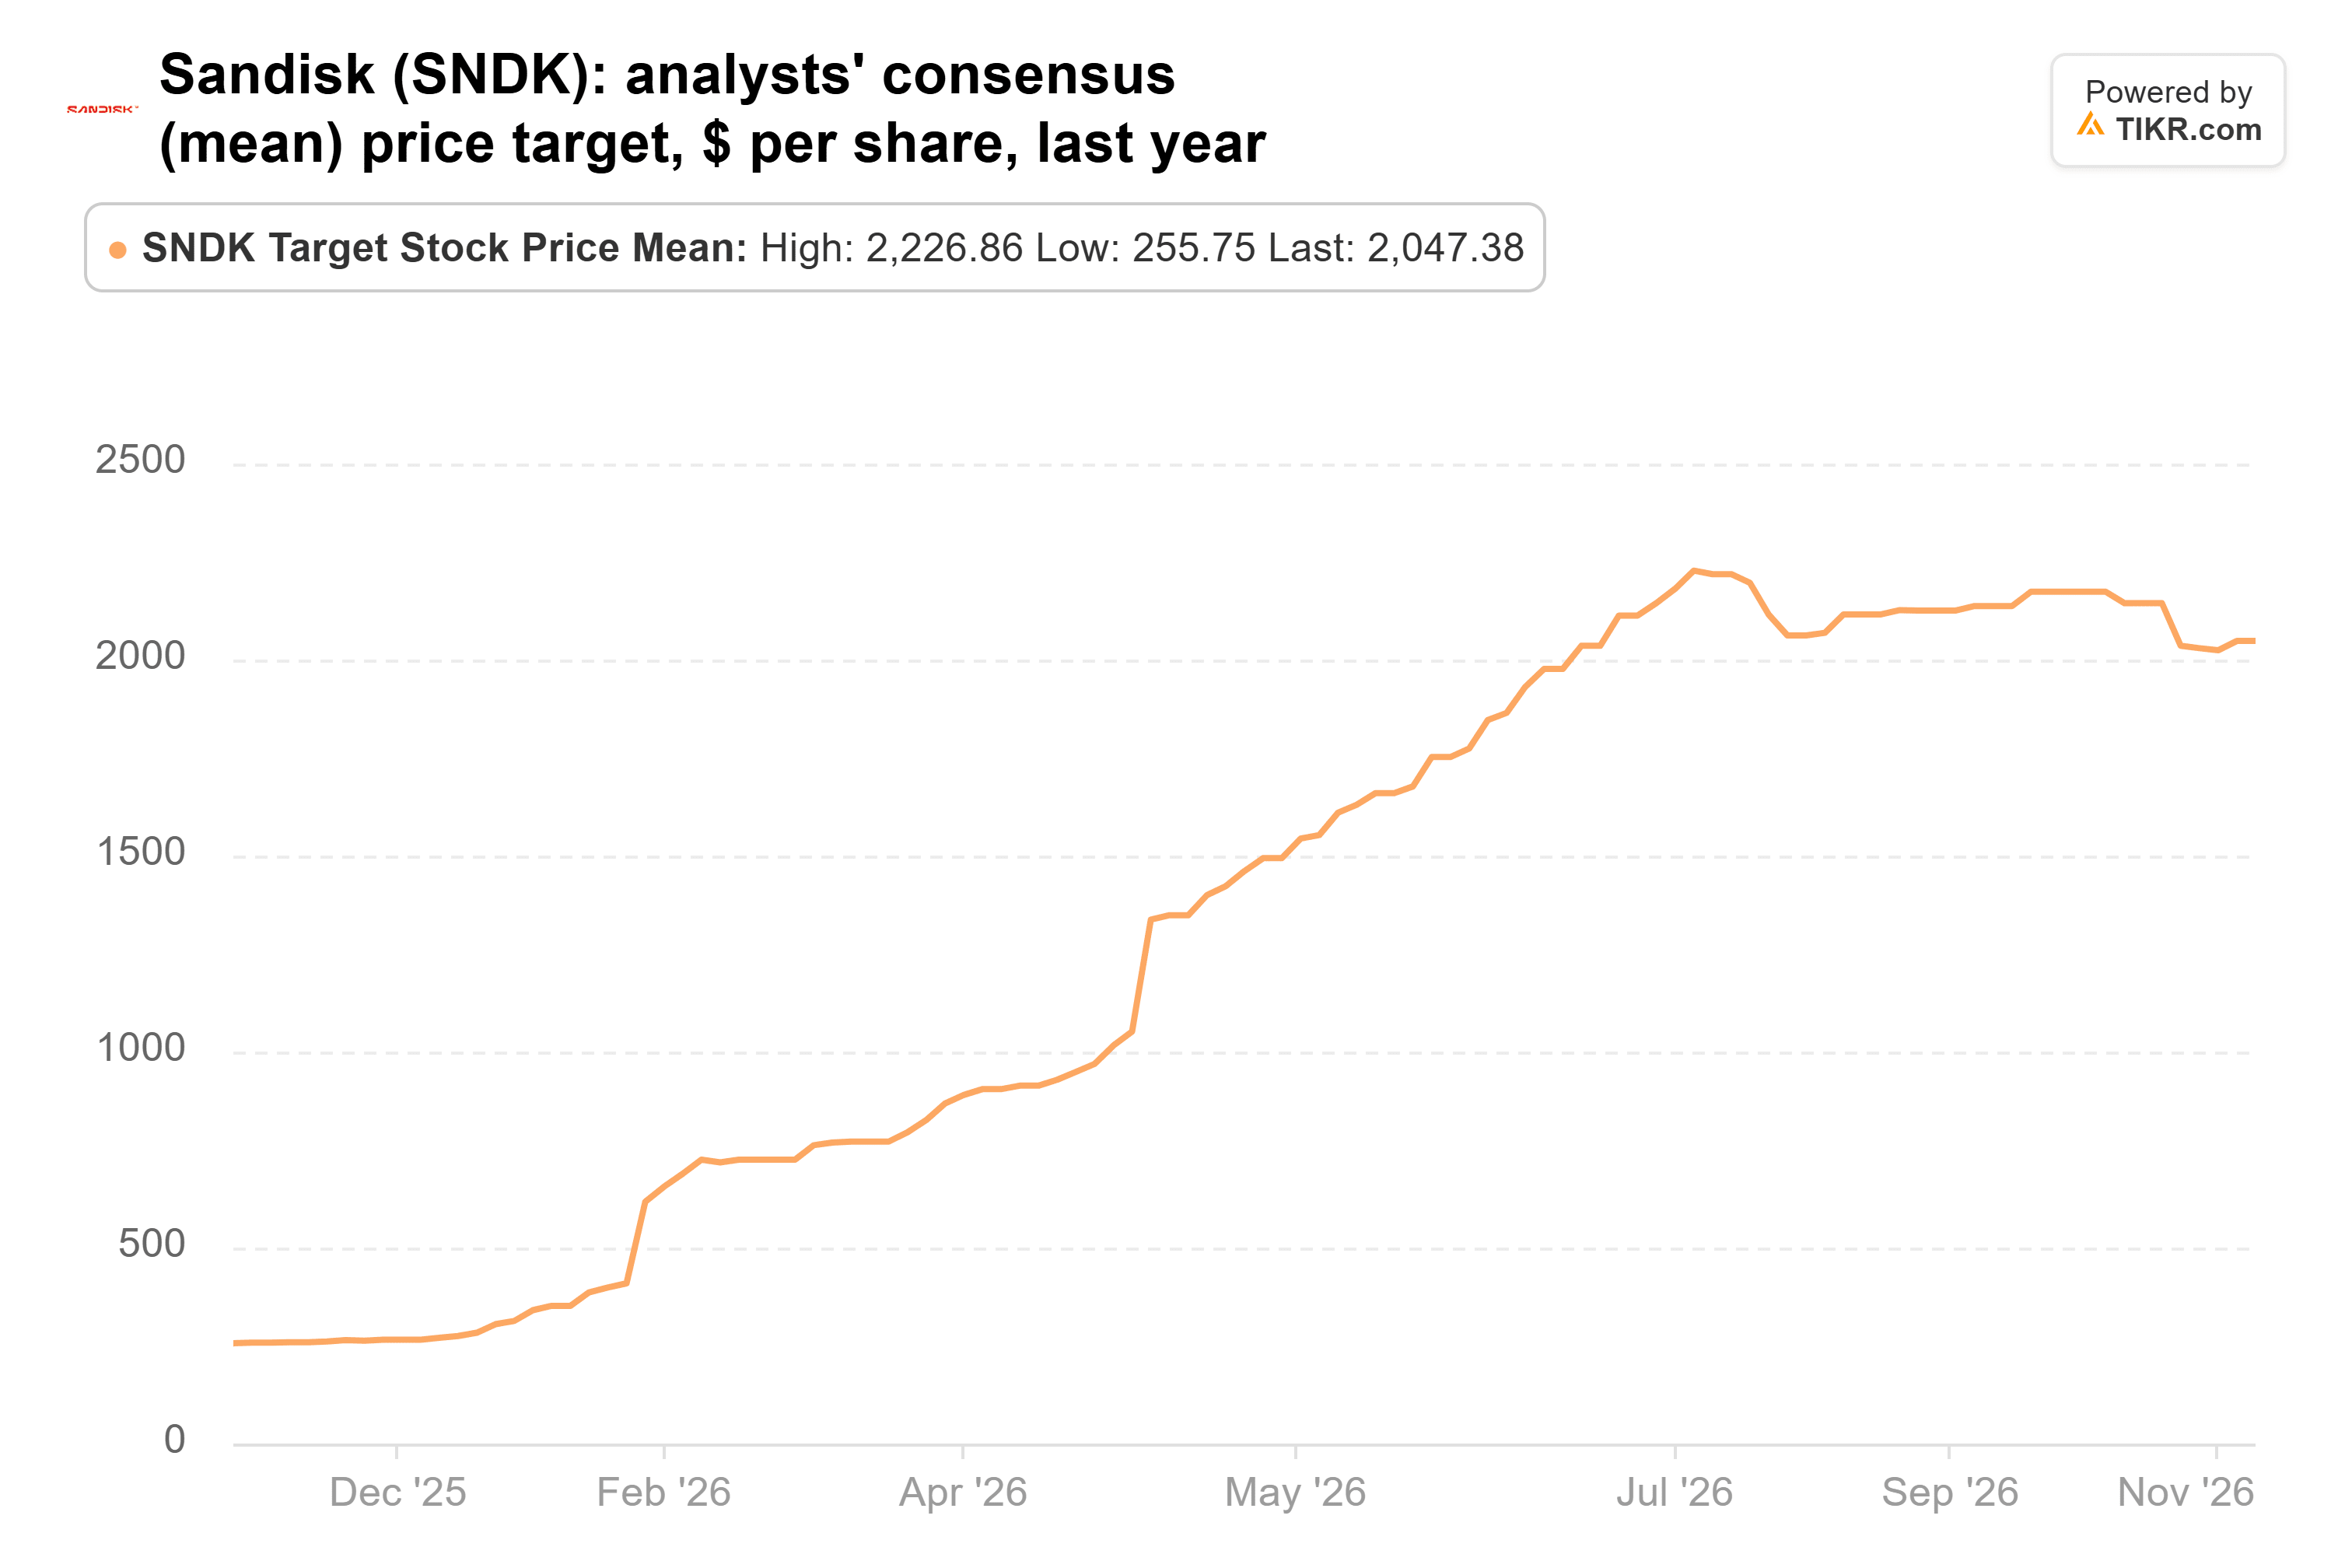
The target is about 8% below its July high, while the stock is 68% below its June high. That leaves the target 171% above the last close.
TIKR tracks 26 analysts on Sandisk. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Sandisk, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Sandisk’s Analyst Ratings
SK hynix is still running hot
SK hynix was Jericho’s other new memory stock. At Sept. 30 it held 2.96 million American depositary shares worth $546 million, 4.7% of its 13F stocks and its sixth-biggest holding. They’re down 35% since then and just closed at their lowest since the July listing.
Second-quarter revenue rose 257% from a year earlier to 79.3 trillion won, at a 76% operating margin. SK hynix also has half of its 2027 and 2028 capacity already contracted. Its biggest customer, Nvidia, just guided to $130 billion of revenue for a fourth quarter with an extra week, above estimates of about $125 billion. On the other side, Reuters reported on Nov. 18 that US officials are holding up licenses for tools SK hynix needs to expand its plant in Dalian, China.
Analysts have cut their average target since the listing, but by less than the stock has fallen:
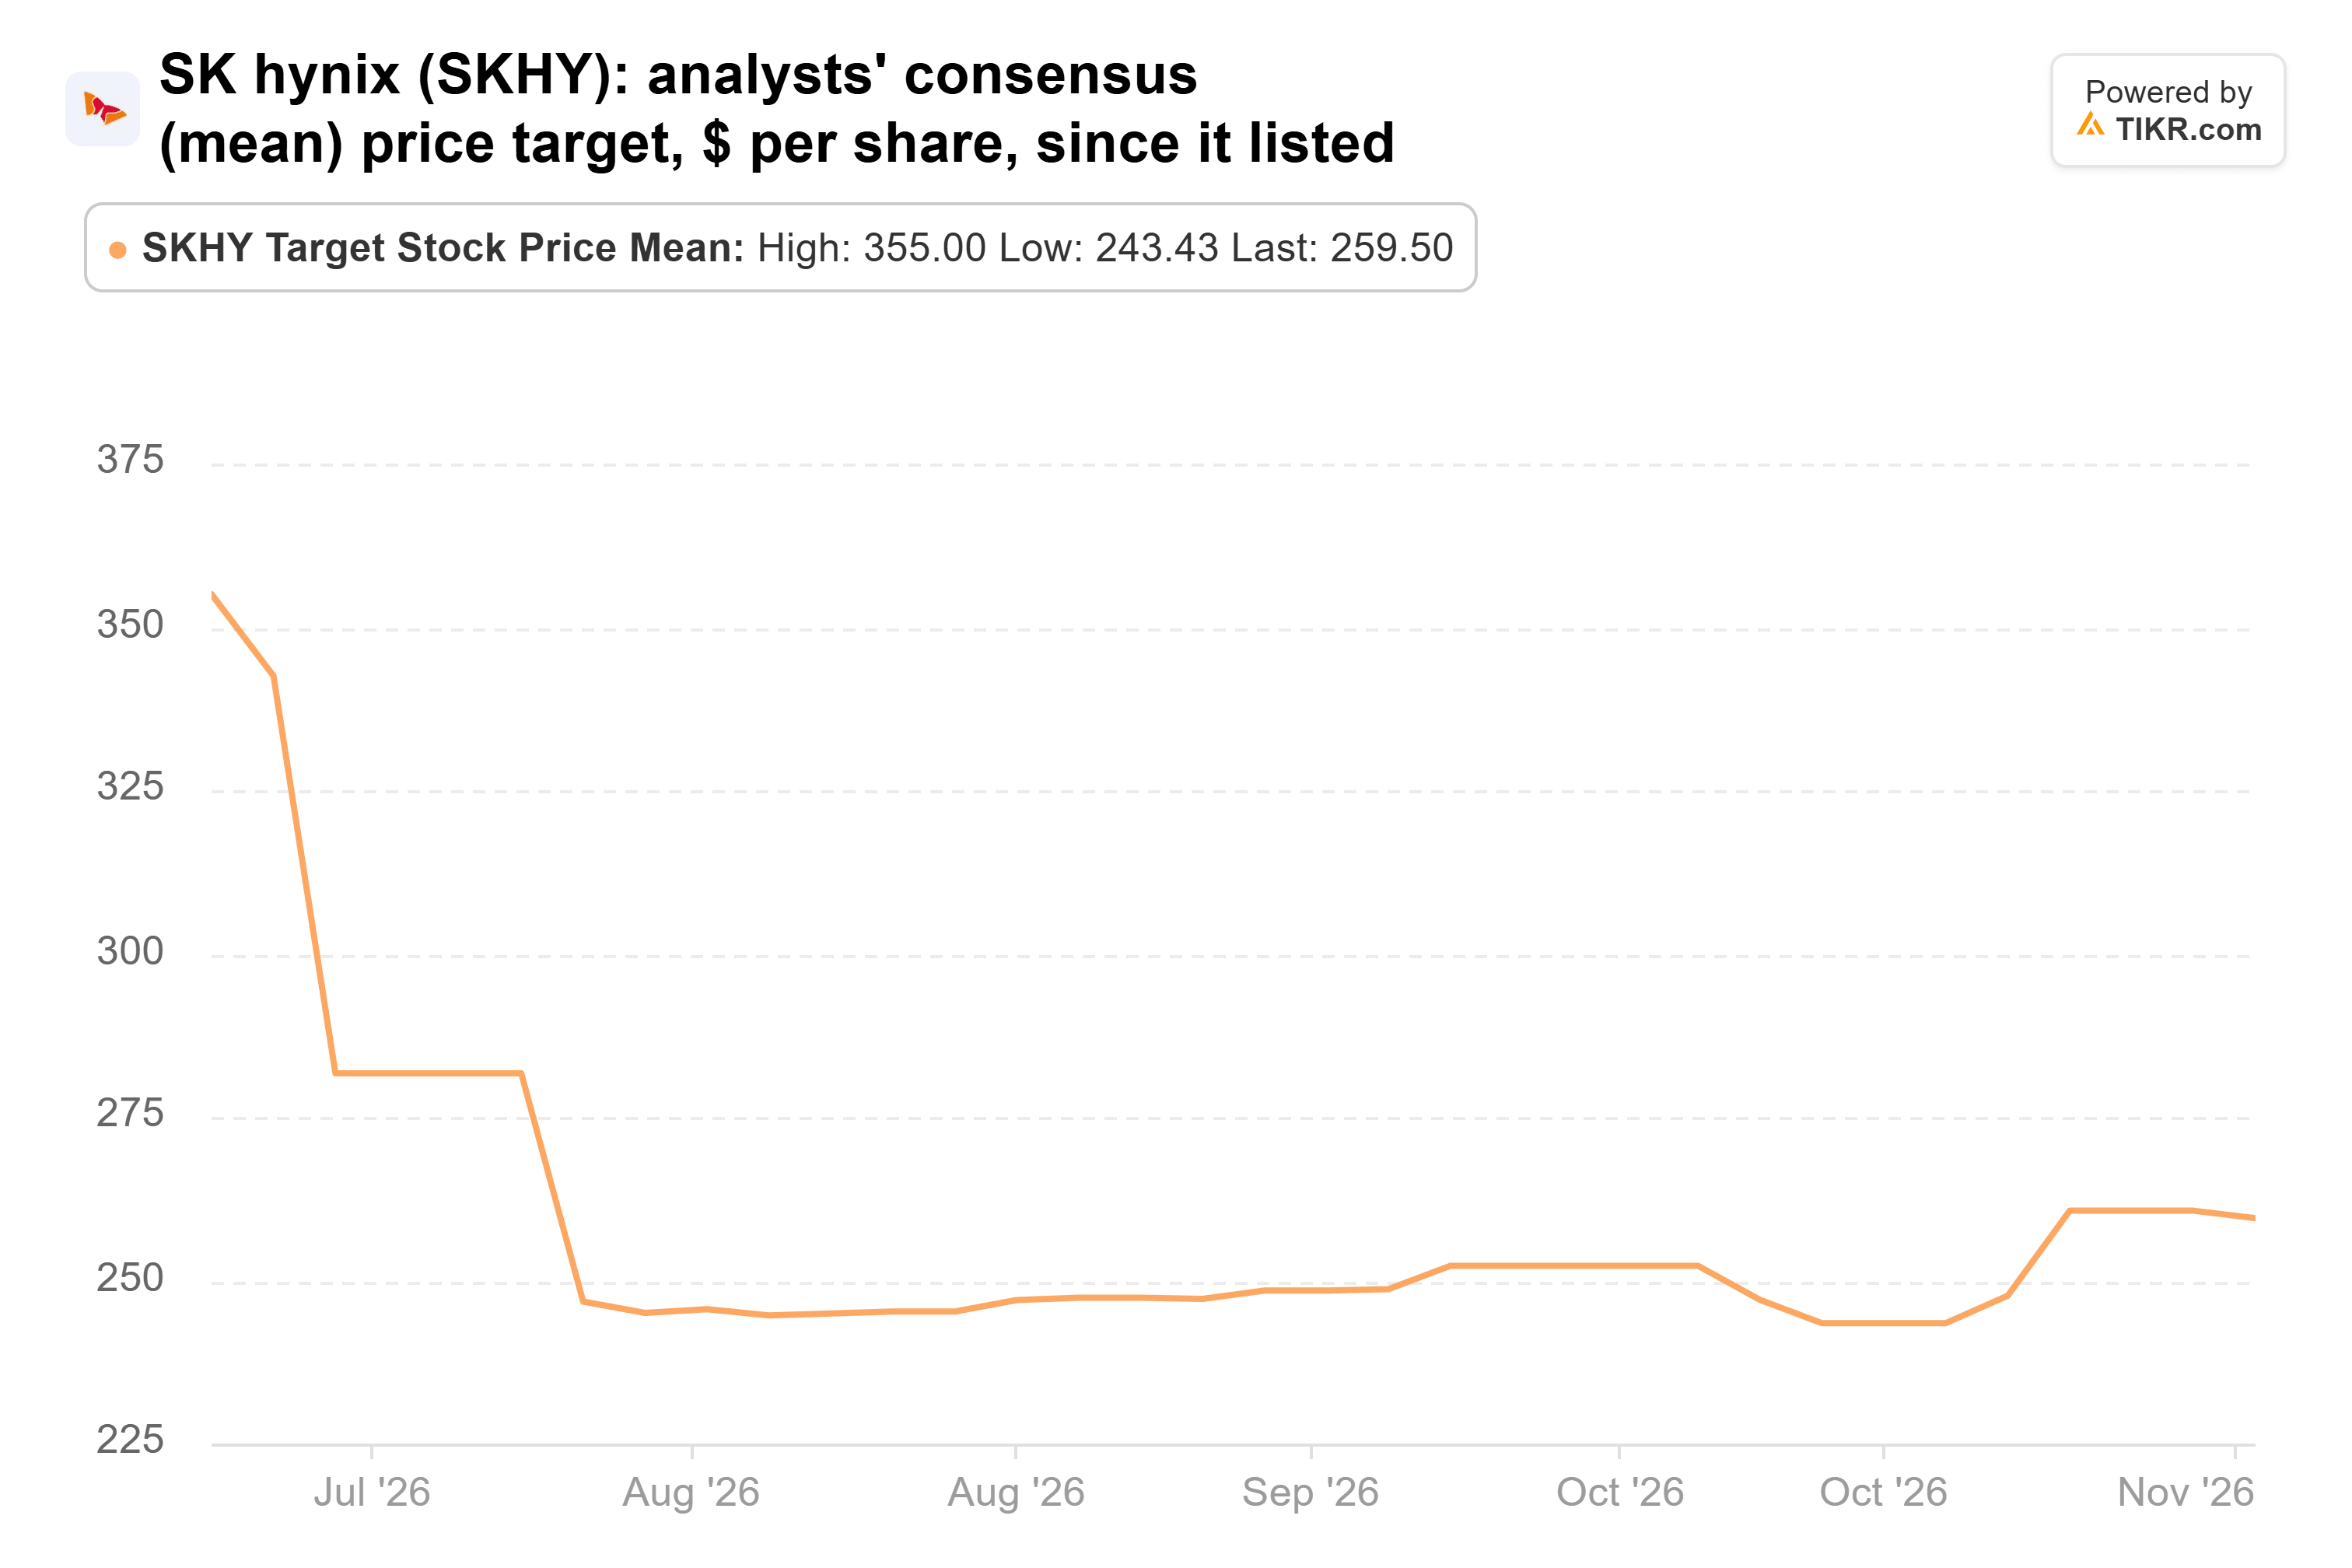
The target is 27% below where it started in July, and the stock is 40% below its September high. That leaves the target 118% above the last close. Its Korean shares traded at 4.4x forward earnings at the end of September, near the bottom of their range since 2014, and that was before the latest drop.
Lattice is growing fast
Jericho added 28% to its Lattice stake and ended September with 4.18 million shares worth $525 million, 4.5% of its 13F stocks and its seventh-biggest holding. Lattice’s revenue rose 118% to $291.0 million in the three months to Oct. 3. That figure includes AMI, the firmware company Lattice acquired during the quarter. Its own FPGA revenue still grew about 90%, to $252 million. Management guided fourth-quarter revenue to about $335 million, roughly 130% above a year earlier.
Even so, the stock is down 12% since Sept. 30. At about 28x forward earnings, it’s the only one of the three priced for growth. Analysts’ average target has nearly doubled in a year and is still close to its August peak:
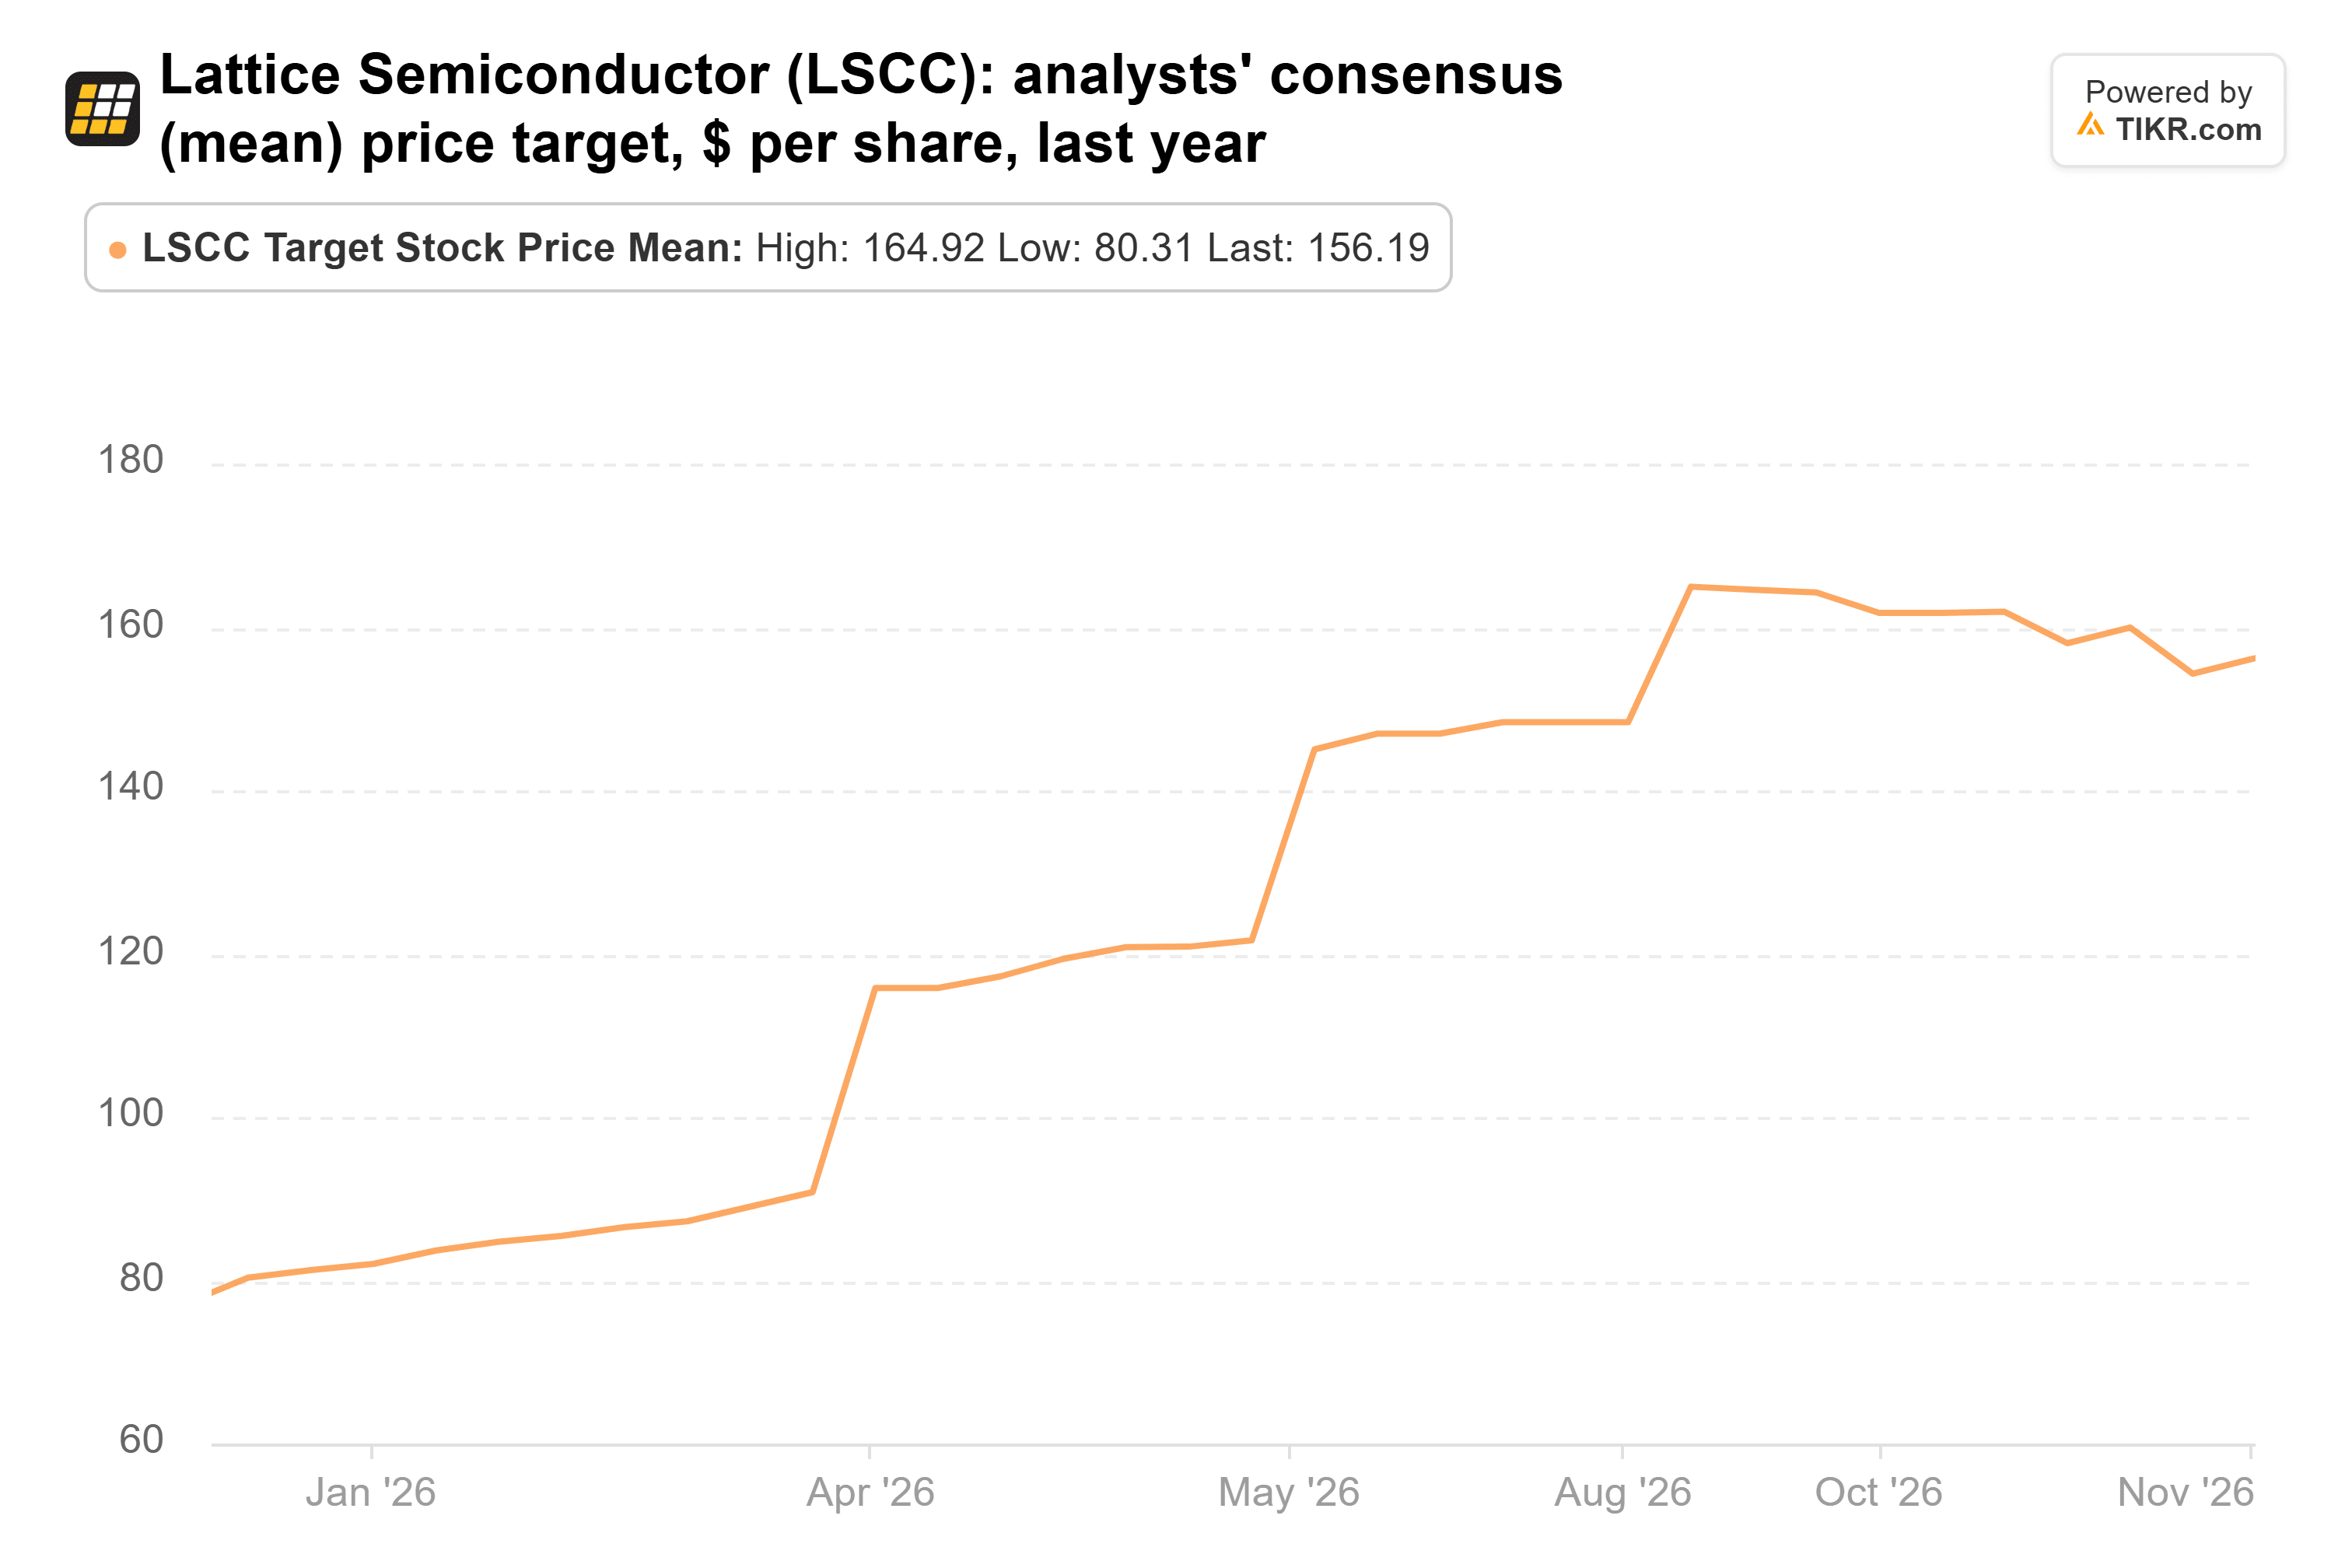
The target is 41% above the last close, the least upside of the three.
Sandisk looks too cheap
Lattice has the cleanest growth story, and its stock already prices that in. The memory makers are priced as though the boom is ending, and Sandisk most of all. It trades at about 3x forward earnings and has no debt. Management says the floor prices in its multiyear contracts still earn about an 80% gross margin. Sandisk spent $9.5 billion buying back its own stock in the two quarters to Oct. 2. It paid an average of $1,583 a share on the old share count, roughly twice its last close before the split. I agree with Evercore ISI’s argument that investors focus too much on how long NAND prices stay high and too little on those contracts.
The contracts haven’t been tested in a downturn, though, since the oldest was signed in January 2026. Three analysts have fiscal 2030 estimates, and they put EPS 49% below fiscal 2029’s, so Wall Street already expects the cycle to turn.
If I could only buy one of Jericho’s three, it’d be Sandisk. The market is pricing in a collapse that its contracts were written to soften. The test comes in late January, when Sandisk reports its fiscal second quarter against guidance of $12.2 billion to $12.6 billion of revenue. Revenue at or above the top of that range, with contracted revenue still near $88.9 billion, would back the case. Jericho’s next 13F, due in mid-February, will show whether the fund held on.
So what is Sandisk stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Sandisk could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!



