


Key Takeaways
- Alphabet hit a 52-week low, leaving it worth $3.34 trillion against Microsoft’s $3.70 trillion.
- Analysts expect Alphabet to earn about $172 billion over the next 12 months, against about $154 billion for Microsoft.
- Amazon and Microsoft trade near 25x forward earnings, while Meta and Alphabet trade near 18x to 19x, even though Google Cloud grew 103% last quarter.
- I’d rather own Alphabet, with search growth and 2027 spending plans in its early-February report as the test.
Alphabet (GOOG) hit a 52-week low this week. It’s down 20% in a month and 32% below its high, which leaves it worth $3.34 trillion. Microsoft (MSFT), just 10% off its own high, is worth $3.70 trillion.
One investor in r/ValueInvesting calls that “pretty bizarre”:
“At the end of the day, the market cap is supposed to approximate the present value of the future cash flows. I have a hard time seeing Microsoft make more money than Alphabet from now until their eventual bankruptcies.”
Which…yeah, agreed.
Microsoft gets the richer multiple
Microsoft trades at 24x the earnings analysts expect over the next 12 months. That’s below its five-year average of 29x but well above the 19x it hit in June:

Alphabet trades at 19x, against a five-year average of 23x. It was at 33x as recently as April:
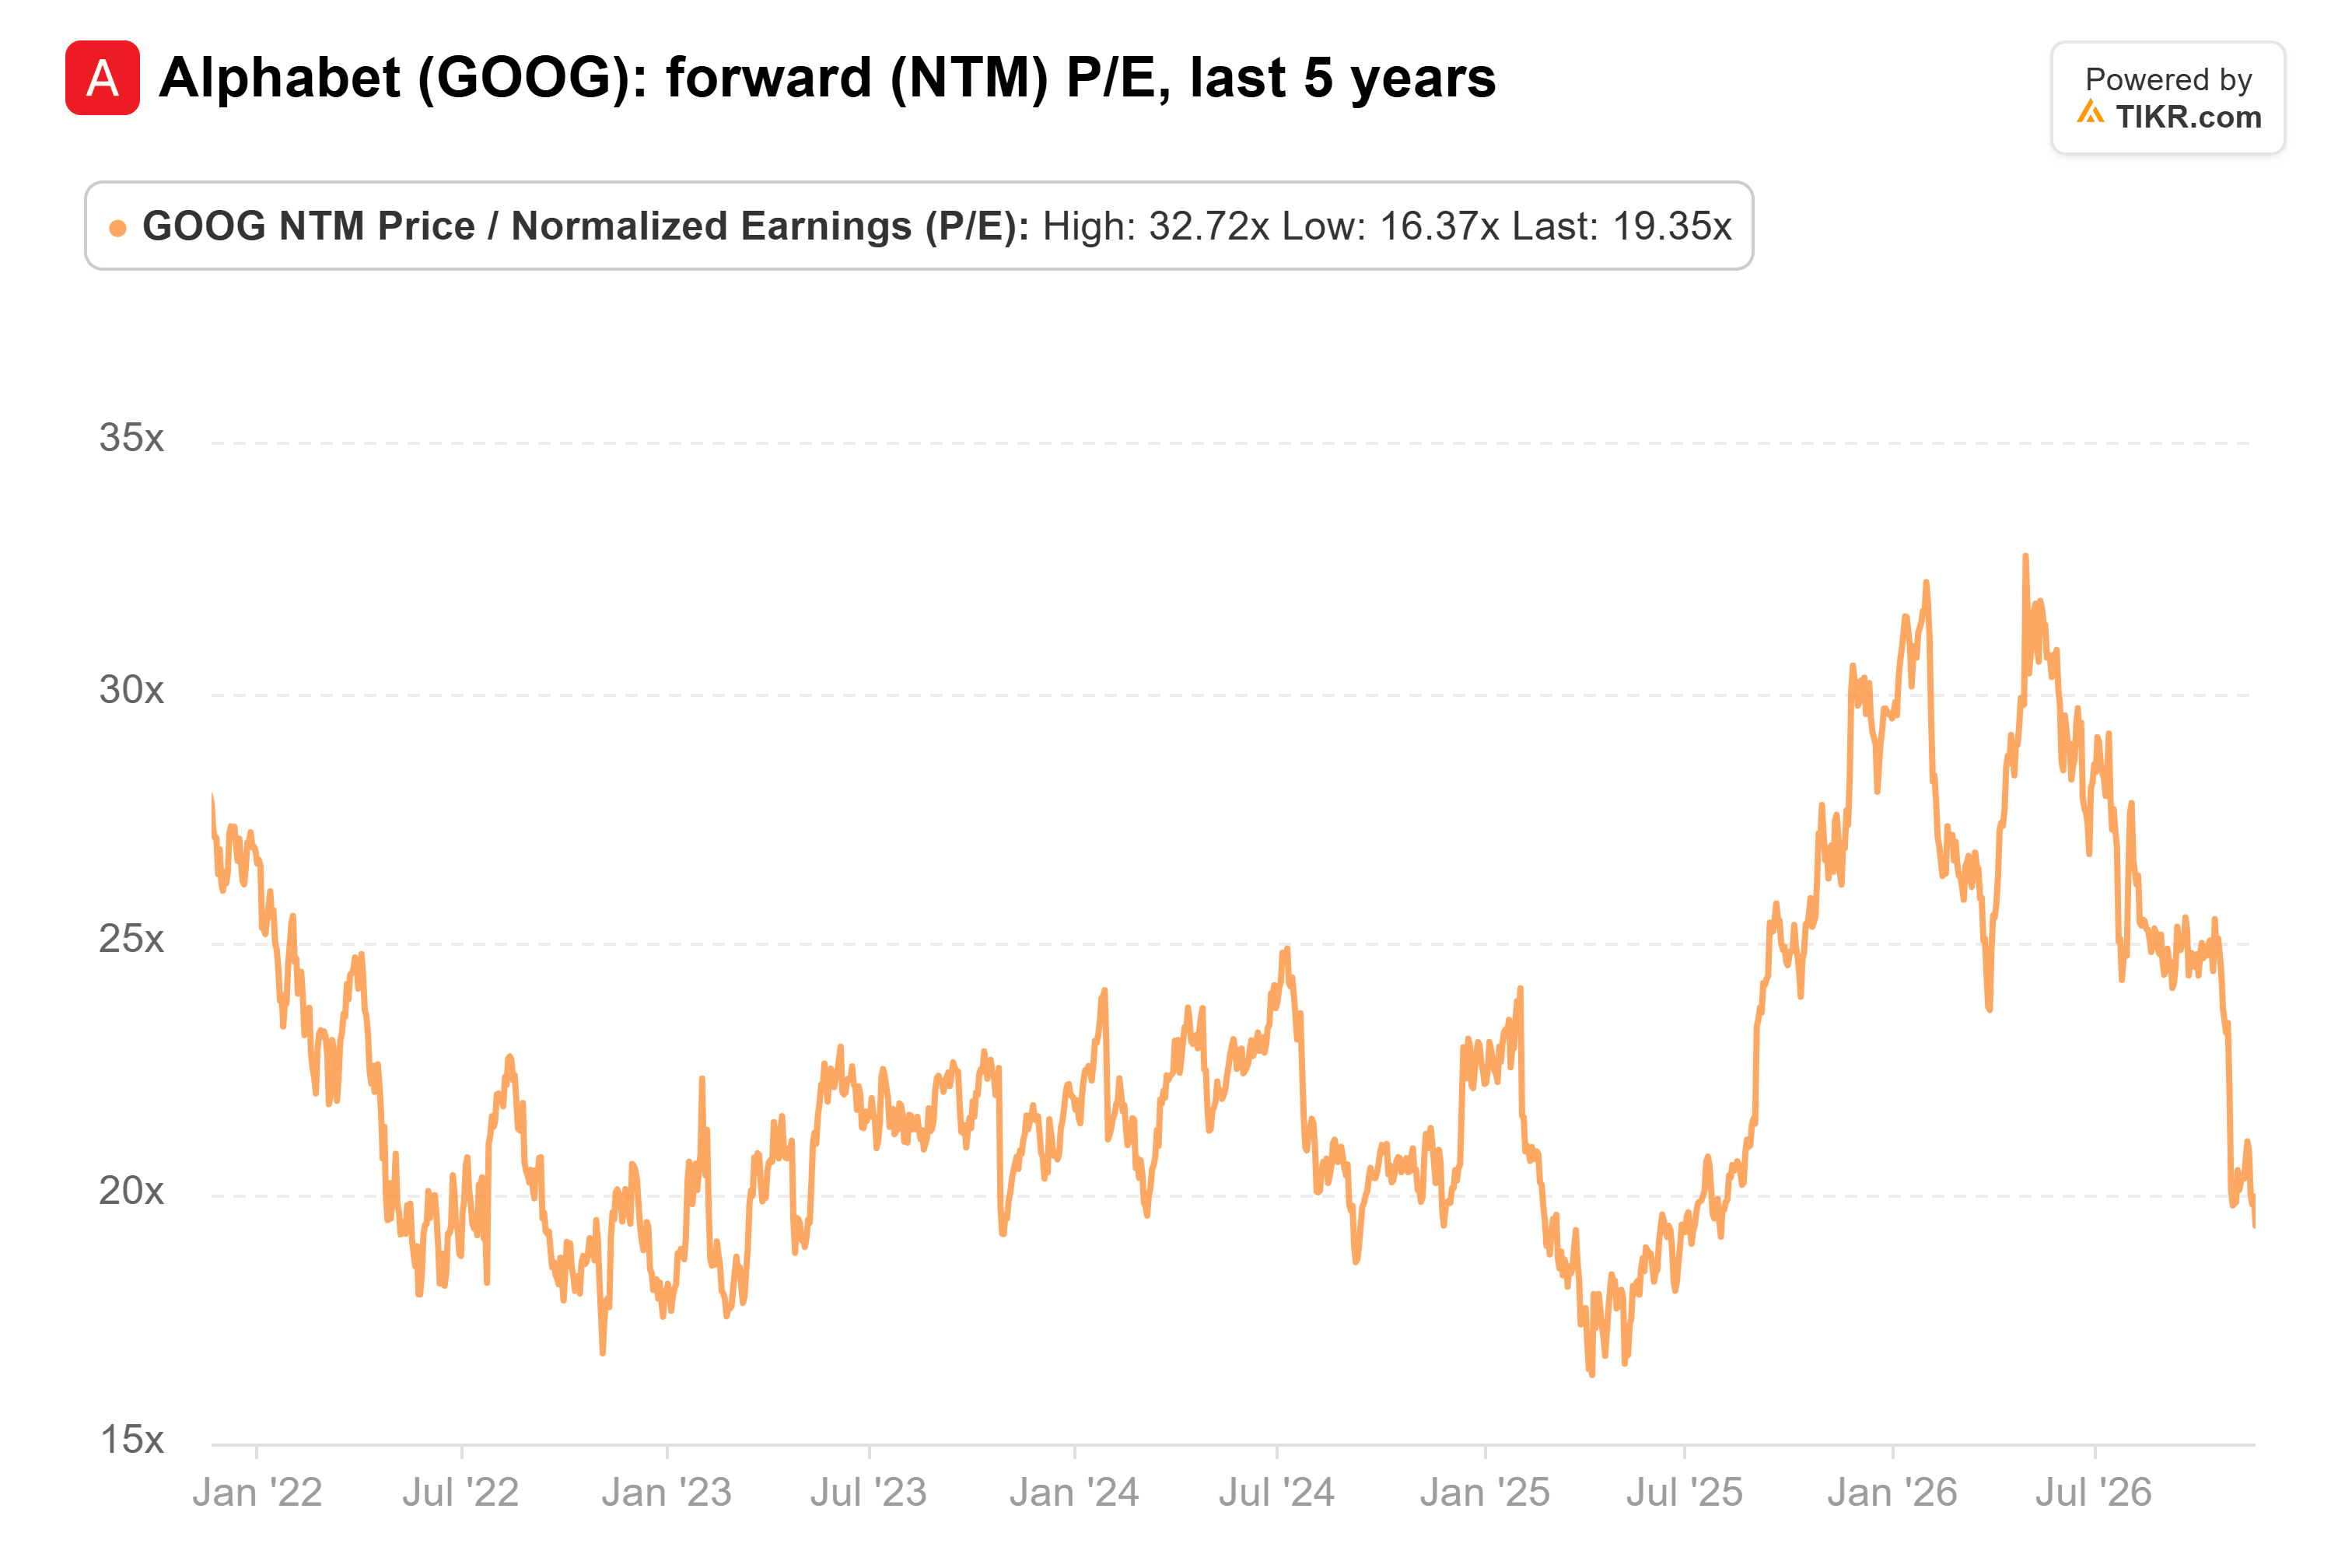
So the market has paid up for Microsoft’s earnings for years. But Alphabet’s earnings have caught up.
Alphabet is expected to earn more
Alphabet’s profit more than doubled from 2022 to 2025:
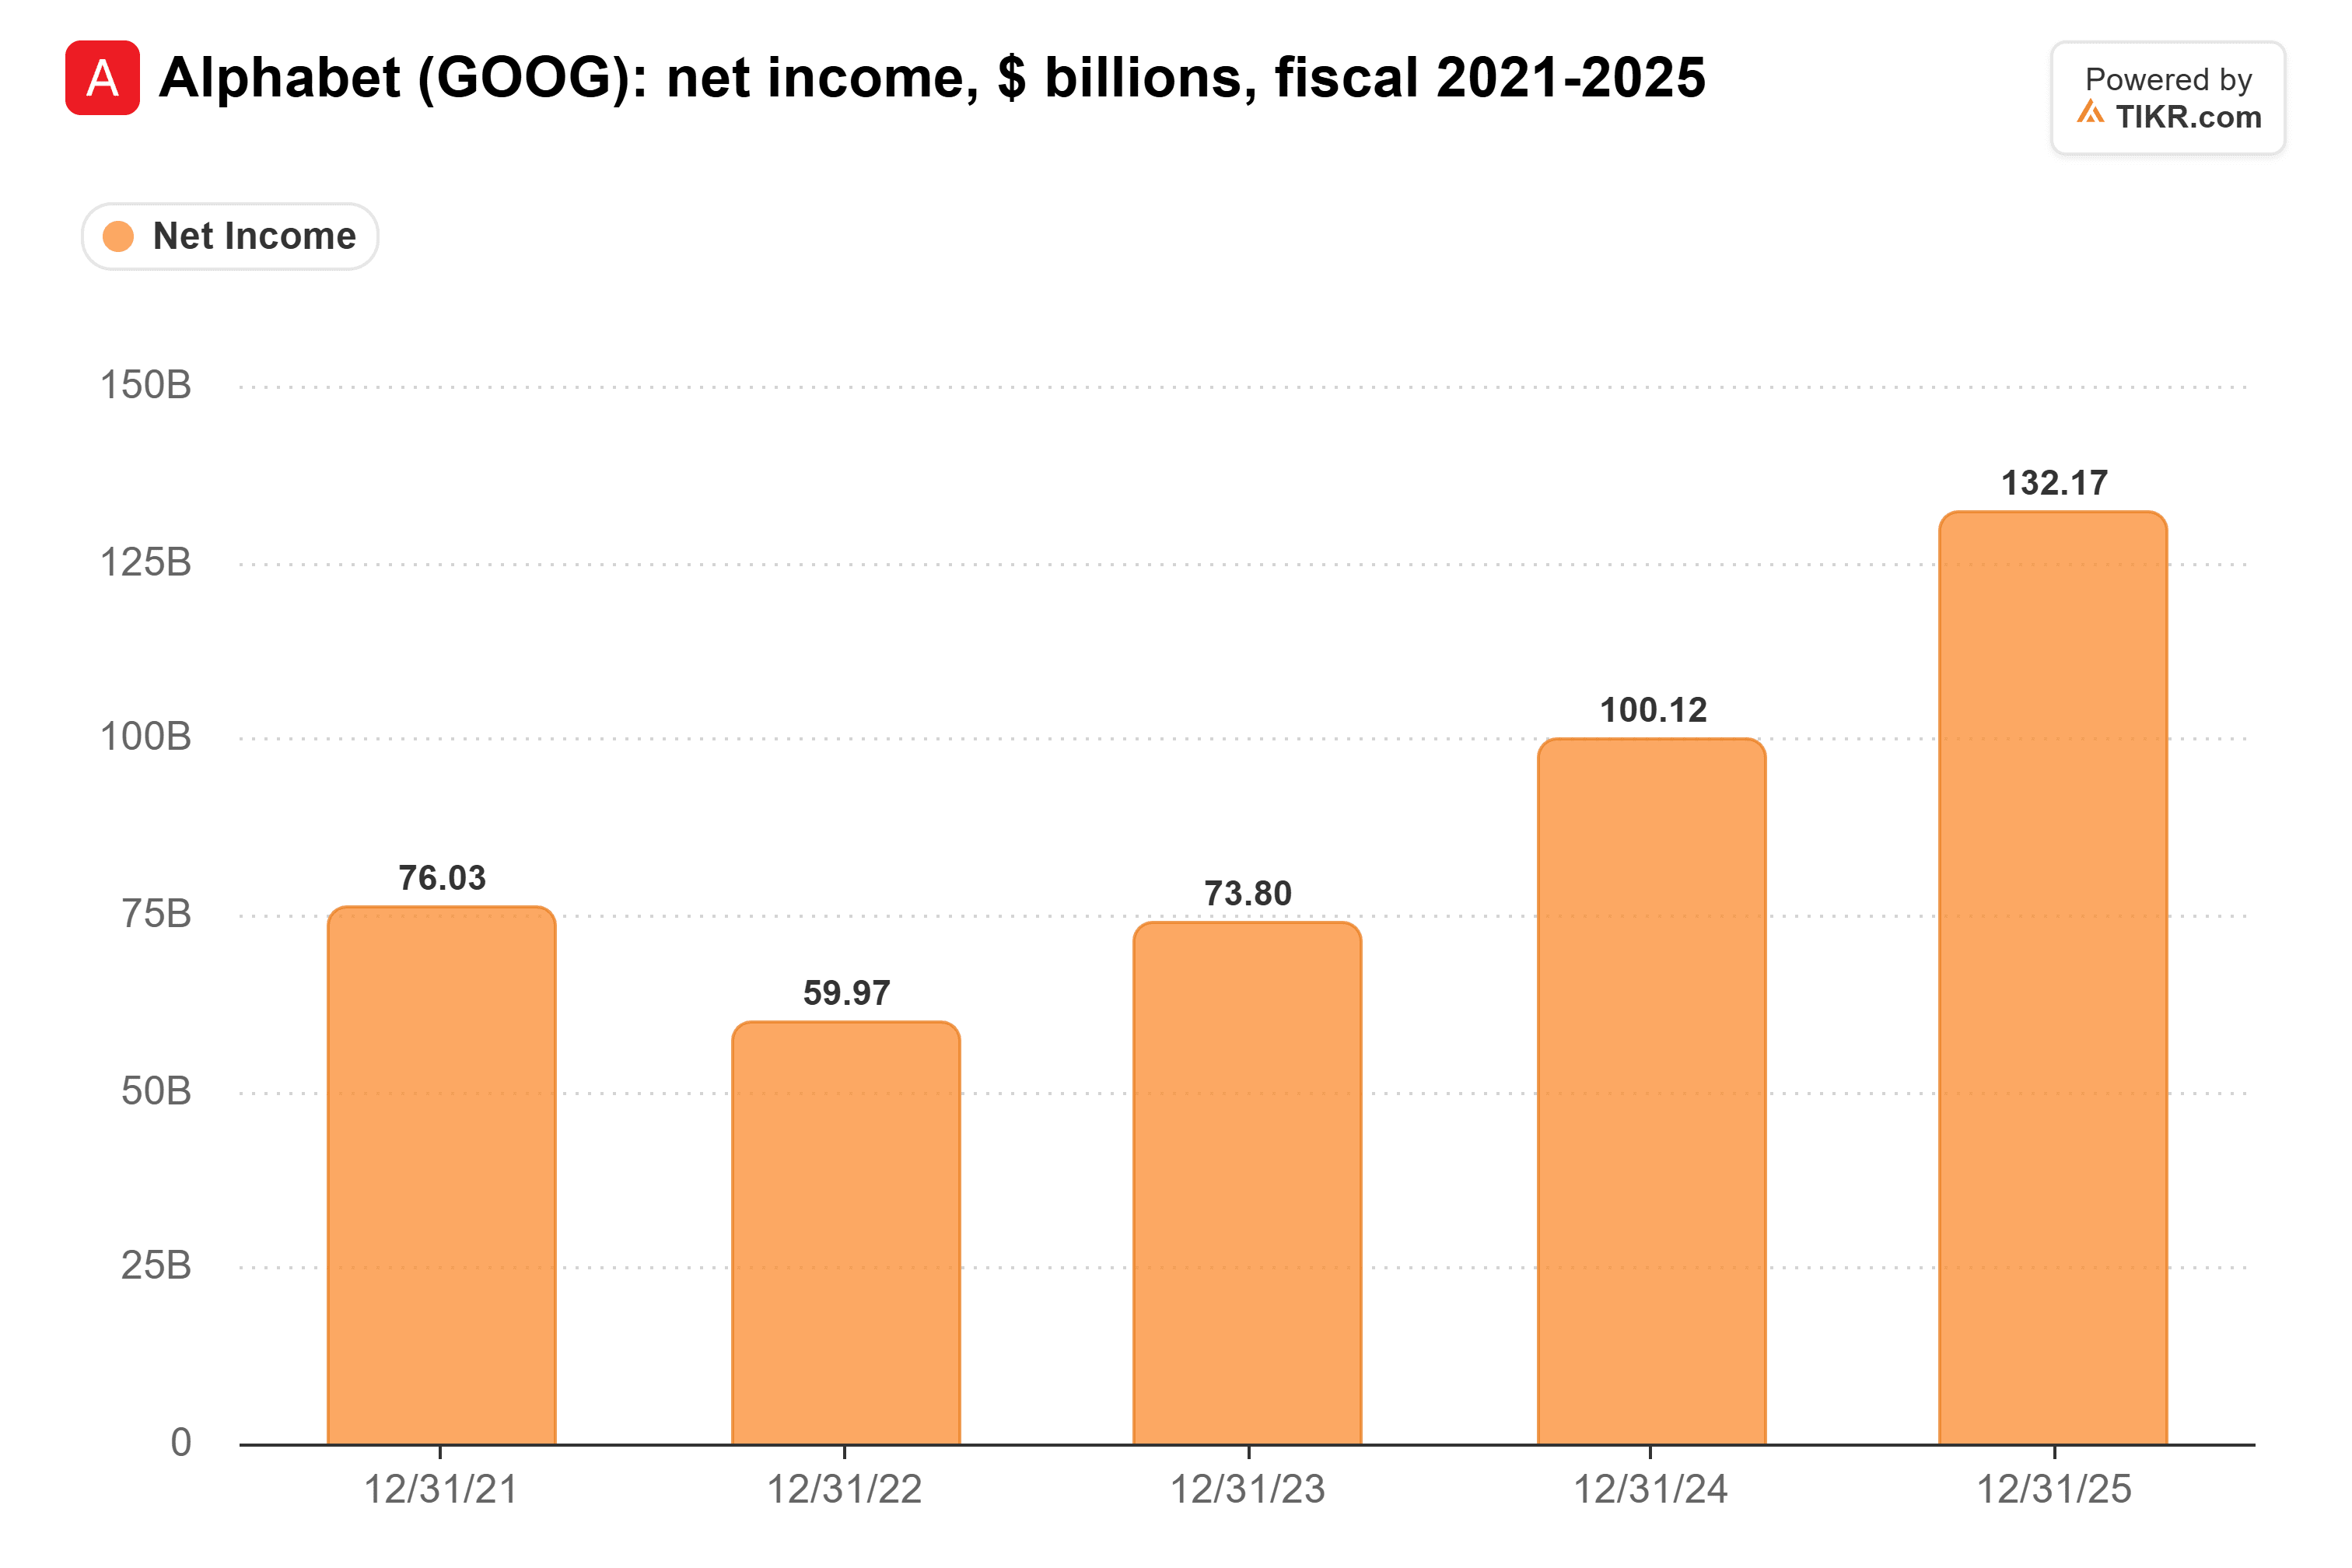
Its $132 billion of net income in 2025 was about level with the $133.7 billion Microsoft earned in its fiscal year ended June 2026.
From here, Alphabet pulls ahead. Divide each company’s market value by its forward multiple, and you get roughly what analysts expect it to earn over the next 12 months: about $172 billion for Alphabet, against about $154 billion for Microsoft.
So investors are paying $360 billion more for the company expected to earn about $18 billion less. Bizarre.
TIKR tracks 58 analysts on Microsoft. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Microsoft, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Microsoft’s Analyst Ratings
The market is pricing Alphabet like an ad company
The market isn’t treating all the big AI spenders alike. Amazon (AMZN) trades at 25x forward earnings, right next to Microsoft, while Meta Platforms (META) trades at 18x, right next to Alphabet.
That split would add up if Alphabet were only an ad business. But Google Cloud revenue grew 103% to $30.7 billion in the third quarter, faster than Amazon Web Services’ 39%, with a $561 billion backlog behind it.
Meta grew revenue 26% last quarter, almost all of it from ads, and still gets the lowest multiple of the four. I read that as the market worrying about what AI does to ad businesses in general. And Alphabet gives it some reason to: Google Search & other revenue grew 12% in the third quarter, down from 19% in the first.
Office is carrying Microsoft’s premium
Microsoft’s Productivity and Business Processes segment earned 54.0% of the company’s operating income in fiscal 2026, at a 59.9% margin. And Anthropic is now coming for that business, putting Claude Sheets and other office tools in its paid plans.
I’m not too worried yet: Microsoft 365 commercial cloud revenue grew 17% in the September quarter on 5% seat growth, as customers moved to pricier plans.
Cash is Microsoft’s real edge. It generated $67.0 billion of free cash flow in its fiscal year ended June 2026. Alphabet generated $19.7 billion over the 12 months to September, and it has announced plans to raise $80 billion from stock sales. Still, analysts expect Microsoft’s free cash flow to fall to $32.7 billion in fiscal 2027.
I’d rather own the bigger earnings
Microsoft’s premium holds up only as long as Office stays as sticky as ever, and I think it will for a while. But if I could own just one at today’s prices, it’d be Alphabet.
Of course, Alphabet’s next report, likely in early February, has to back that up. I’ll be watching for search growth at or above the third quarter’s 12%, and for the 2027 capex figures management promised with those results. Another step down in search would make the market’s discount look a lot more reasonable.
So what is Alphabet stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Alphabet could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


